
 Polyurea Greases Market | 2026-2036
Polyurea Greases Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurea Greases Market Analytics
NLGI Grade 2 premium specification is redrawing procurement benchmarks across bearing-intensive industries. ExxonMobil leverages backward integration into polyurea thickener chemistry to secure feedstock reliability. SKF anchors its position through captive lubricant production tied to bearing system sales. Klüber Lubrication specializes in application-engineered formulations for wind turbine main bearings.
Polyurea greases are synthetic lubricants formed by reacting a diisocyanate with a diamine to create a urea-based thickener structure, typically exhibiting dropping points above 240°C and superior oxidative stability compared to conventional lithium complex greases. The Automotive product type segment dominates volume as electric vehicle powertrain bearings demand thermally stable lubrication with extended service intervals. Within the Grade dimension, Food Grade formulations command premium positioning due to NSF H1 certification requirements and limited qualified supplier pools. The Heavy Load application category leads industrial offtake where mining and construction equipment subject bearings to sustained axial and radial stress.
The EPA regulates lubricant environmental persistence through VGP and sVGP discharge standards affecting marine and industrial applications. REACH restrictions on aromatic amines and isocyanate handling protocols under OSHA PEL guidelines shape formulation chemistry and plant capital requirements. NSF International H1 and H2 registrations function as gatekeeping standards for food-processing market access. Stakeholders must monitor evolving PFAS restrictions in both the European Union and individual U.S. states, as fluorinated grease alternatives face substitution pressure that could redirect specification engineers toward advanced polyurea chemistry.
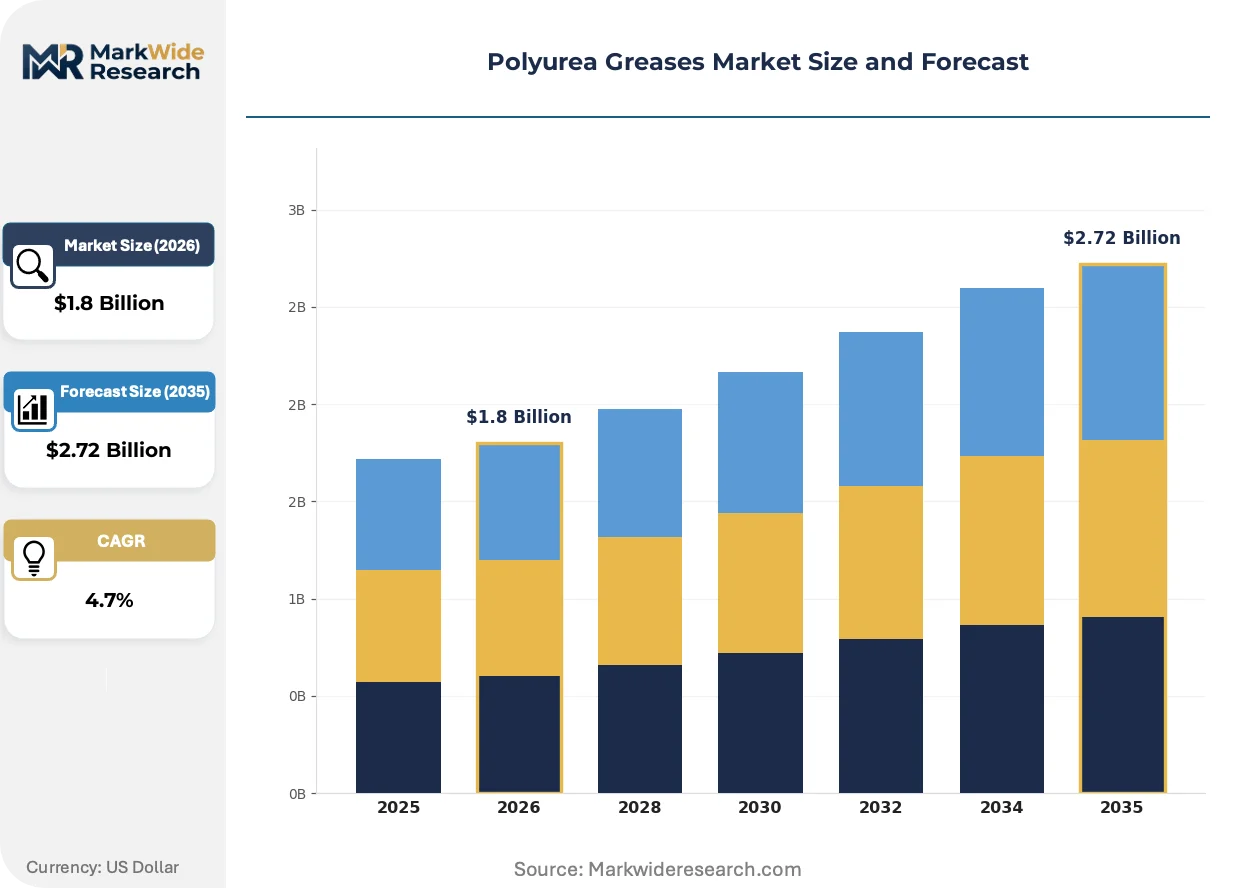
Market Dynamics
Electric vehicle thermal management requirements are compressing lubricant service intervals and elevating specification thresholds for high-temperature bearing protection across automotive supply chains.
Growth Catalysts
- EV Powertrain Thermal Loads:Electric motor bearings operate at sustained temperatures above 150°C, forcing OEMs toward polyurea chemistry with dropping points exceeding 240°C. Automotive assembly plants in Germany and China now mandate this specification for drivetrain warranties.
- REACH Phase-Out of Conventional Thickeners:ECHA restrictions on certain lithium soap precursors are redirecting formulation R&D toward urea-based alternatives. European industrial buyers face compliance deadlines that accelerate specification migration.
- Wind Turbine Scale-Up:8MW+ offshore turbines impose multi-decade bearing life requirements. Main bearing OEMs specify polyurea greases for their oxidative stability in nacelle environments with limited maintenance access.
Market Restraints
- Isocyanate Feedstock Concentration:Polyurea thickener production depends on aromatic diisocyanate supply chains concentrated in Northeast Asia. Geopolitical friction or shipping disruptions transmit directly to grease compounder margins.
- Specialized Blending Asset Requirements:Urea reaction chemistry demands temperature-controlled reactors with nitrogen blanketing systems. Capital intensity limits new entrant participation to established lubricant compounders with existing synthetic grease infrastructure.
- PFAS Substitution Uncertainty:Fluorinated grease alternatives currently occupy extreme-temperature niches above polyurea thermal limits. Evolving EU and U.S. state-level PFAS restrictions could expand addressable market boundaries, but regulatory timelines remain unresolved.
Strategic Opportunities
- Food Processing Equipment Retrofit:NSF H1-certified polyurea formulations penetrate bakeries and protein processing plants where lithium complex greases previously dominated. North American meatpacking corridors present concentrated conversion potential.
- Digital-Enabled Condition Monitoring:Integration of lubricant sensors with predictive maintenance platforms creates attach-rate expansion for premium grease specifications. Mining operators in Australia's Pilbara region pilot this convergence.
- India Industrial Acceleration:PLI scheme incentives for precision manufacturing and textile machinery create specification upgrade cycles. Domestic bearing distributors report rising inquiries for NLGI Grade 2 polyurea products.
Industry Challenges
- Formulation Chemist Scarcity:Urea thickener synthesis requires expertise in controlled diisocyanate-diamine stoichiometry. European and North American compounders compete for limited talent pools trained in high-temperature grease chemistry.
- NSF H1 Certification Timelines:Food-grade registration demands 12-18 month toxicology review cycles. Supplier qualification delays constrain speed-to-market for new entrants targeting dairy and beverage processing segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurea Greases Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive, Industrial, Marine, Aerospace Application: High-Temperature, Low-Temperature, Heavy Load, Extreme Pressure End User: Manufacturers, OEMs, Maintenance Providers, Retailers Grade: Food Grade, Industrial Grade, Military Grade, Specialty |
| Companies Covered | ExxonMobil, Chevron, Shell, TotalEnergies, SKF, Fuchs Petrolub, Klüber Lubrication, Castrol, Lubrizol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurea Greases Market Evolving Landscape
Specification engineering is migrating from component-level lubricant selection toward integrated bearing-grease system design, compressing traditional procurement autonomy and elevating technical collaboration requirements.
Advanced polyurea-thickened greases with ester-based base oil combinations are displacing lithium complex products in steel mill continuous casting operations. SKF and Schaeffler specify these formulations for tundish car bearings where water spray contamination and thermal cycling converge. The displacement accelerates as mill maintenance departments consolidate lubricant inventories to reduce misapplication risk.
EPA sVGP discharge standards for vessel lubricant environmental persistence are tightening formulation constraints on marine stern tube and deck machinery applications. U.S. Great Lakes shipping operators now face compliance verification requirements that favor biodegradable base oil carriers paired with polyurea thickeners. Lake freighter fleets in Wisconsin and Michigan drive specification pull-through toward suppliers with VGP-compliant product lines.
Japanese automotive bearing manufacturers now require grease suppliers to co-develop thermal aging test protocols specific to electric axle applications. Procurement teams at NSK and JTEKT negotiate multi-year formulation lock-ins rather than spot purchasing. This behavioral shift concentrates supplier relationships and compresses second-source qualification opportunities in the Asia-Pacific EV supply base.
Polyurea Greases Market Segmentation
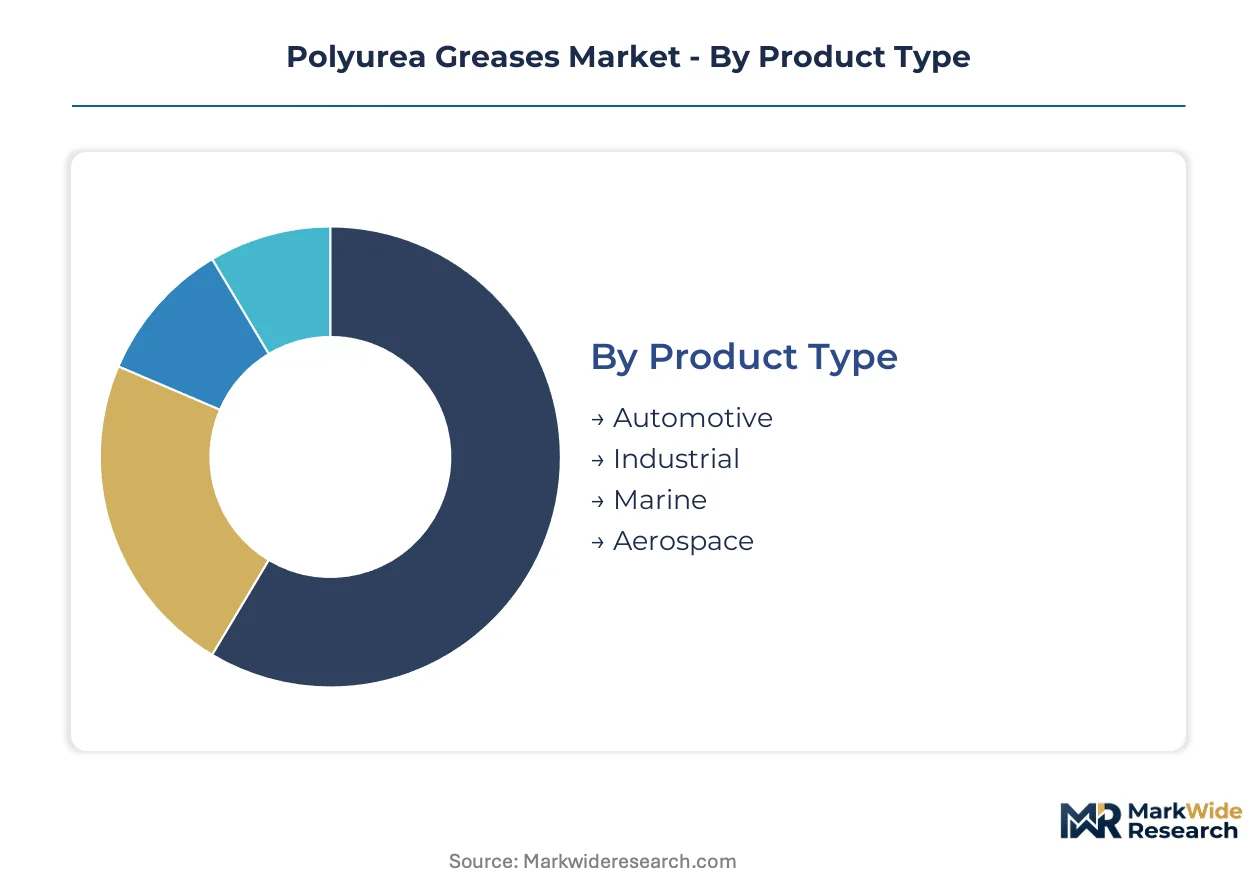
Polyurea grease procurement decisions fragment across performance specifications, regulatory certifications, and channel access requirements. Buyers in bearing-intensive industries prioritize thermal stability and compliance credentials over unit cost, concentrating margin capture in specialized formulation tiers.
Product Type:
Premium margin pools concentrate in formulations engineered for thermal extremes and extended service intervals, where specification lock-ins reduce price sensitivity.
- Automotive:Electric drivetrain bearings demand greases with dropping points above 240°C and oxidative stability for 150°C+ sustained operation. German and Chinese OEMs now mandate polyurea chemistry for powertrain warranties, compressing second-source qualification timelines.
- Industrial:Steel mill continuous casting and mining equipment subject bearings to water contamination, thermal cycling, and heavy radial loads. Ester-base oil polyurea formulations displace lithium complex products as maintenance departments consolidate lubricant inventories.
- Marine:EPA sVGP discharge standards favor biodegradable base oil carriers paired with polyurea thickeners for stern tube and deck machinery applications.
- Aerospace:Military and commercial aviation specifications demand narrow viscosity ranges and extreme-pressure additives for landing gear and actuator systems.
The dominant share belongs to Automotive, while Industrial is closing the gap fastest as steel and mining sectors accelerate specification migration.
Application:
Volume concentration tracks toward operating environments where conventional thickeners fail, elevating polyurea chemistry from specialty substitute to default specification.
- Heavy Load:Mining haul trucks and construction excavators impose sustained axial and radial stress on pivot bearings. Australian Pilbara operators and Chilean copper mines specify NLGI Grade 2 polyurea products for load-carrying capacity exceeding 500kgf.
- High-Temperature:Wind turbine main bearings in 8MW+ offshore units face nacelle temperatures with limited maintenance access. Oxidative stability requirements stretch service intervals toward multi-decade design lives.
- Extreme Pressure:Gearbox and rolling element bearings in metal forming equipment encounter boundary lubrication conditions requiring anti-wear additive packages.
- Low-Temperature:Arctic mining and cold-climate wind installations demand pumpability at -40°C without sacrificing high-temperature performance.
Heavy Load commands the largest volume position, though High-Temperature applications are expanding most quickly as renewable energy scale-up accelerates.
End User:
Procurement autonomy varies sharply by buyer type, with OEMs exerting formulation control while maintenance providers optimize for inventory reduction.
- OEMs:NSK, JTEKT, and SKF negotiate multi-year formulation lock-ins rather than spot purchasing, concentrating supplier relationships and compressing qualification opportunities.
- Maintenance Providers:Third-party industrial service contractors in Germany's precision manufacturing belt specify polyurea greases for spindle bearings to reduce changeout frequency.
- Manufacturers:In-house lubrication teams at steel mills and cement plants balance specification compliance with bulk purchasing economics.
- Retailers:Distributors serving automotive aftermarket and small industrial accounts stock NLGI Grade 2 products as default recommendations.
OEMs dominate specification authority, while Maintenance Providers are gaining procurement influence fastest as predictive maintenance platforms expand.
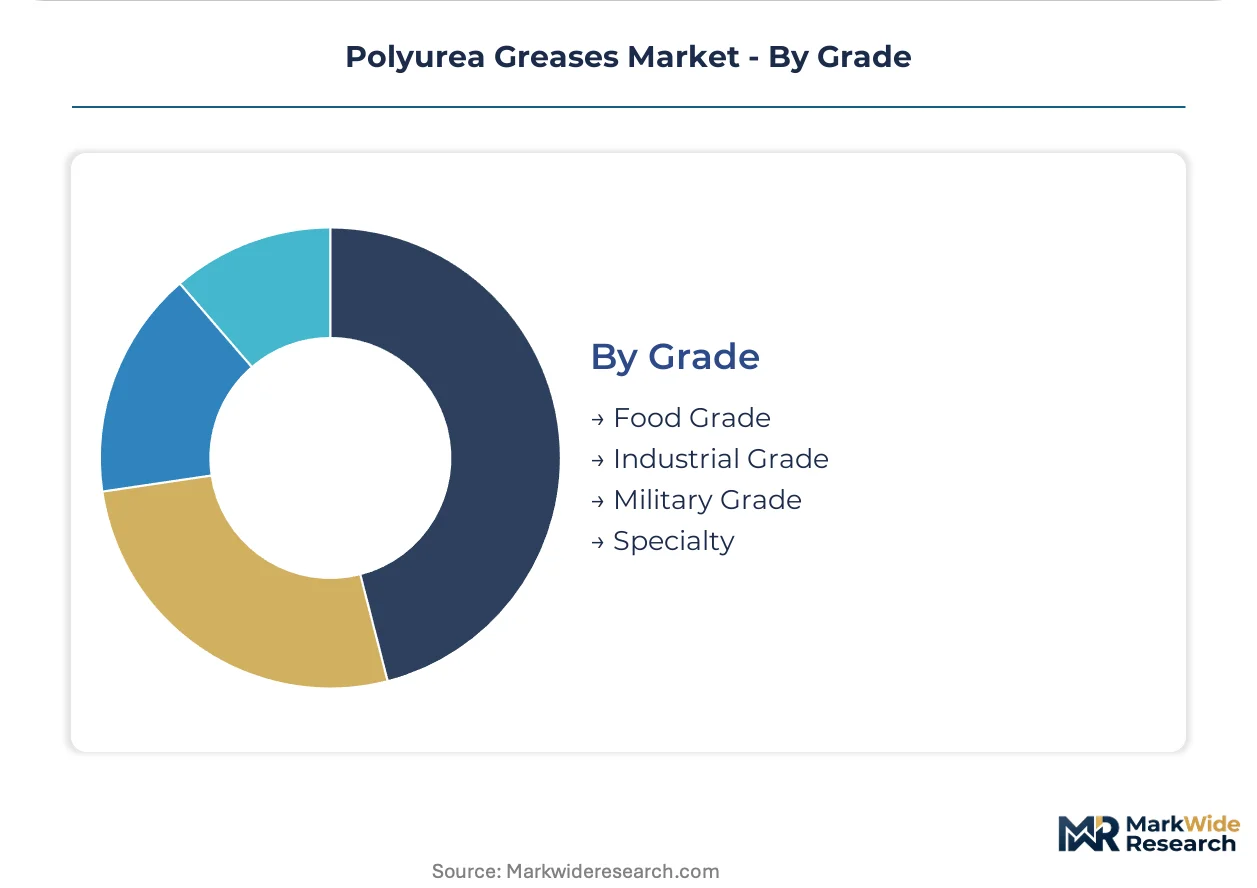
Grade:
Certification tiering creates pricing stratification that separates premium-positioned food-grade formulations from commodity industrial specifications.
- Food Grade:NSF H1 registration demands 12-18 month toxicology review cycles, constraining qualified supplier pools. North American meatpacking corridors and European dairy processors specify these formulations for incidental food contact applications.
- Industrial Grade:Unregistered formulations serve general machinery applications where regulatory compliance requirements remain minimal.
- Military Grade:MIL-PRF and DEF STAN specifications govern defense procurement with traceability and lot testing protocols.
- Specialty:Custom formulations address semiconductor cleanroom, medical device, and other niche applications with particle count or outgassing constraints.
Food Grade captures the steepest premium positioning, while Specialty grades are climbing fastest as cleanroom and precision manufacturing requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German grease compounders export polyurea formulations to Chinese EV assembly plants, establishing a trade-flow corridor that shapes procurement patterns across both markets. This bilateral exchange concentrates premium specification development in Central Europe while scaling volume manufacturing in East Asia.
United States
EPA sVGP discharge standards drive Great Lakes shipping operators toward biodegradable base oil carriers paired with polyurea thickeners. OSHA PEL guidelines on isocyanate handling shape plant capital requirements for domestic compounders. Wisconsin and Michigan lake freighter fleets generate concentrated specification pull-through for VGP-compliant product lines.
Germany
Tool-and-die shops in the precision manufacturing belt specify polyurea greases for spindle bearings to reduce changeout frequency. REACH restrictions on aromatic amines redirect formulation R&D toward urea-based alternatives at Ludwigshafen and Hamburg chemical clusters. Bavarian automotive OEMs now mandate polyurea chemistry for electric drivetrain warranties.
China
Electric vehicle powertrain assembly plants compress lubricant service intervals and elevate thermal specification thresholds. MIIT industrial upgrading guidelines accelerate precision manufacturing adoption in Jiangsu and Zhejiang provinces. Yangtze River Delta bearing distributors report rising inquiries for NLGI Grade 2 polyurea products.
India
PLI scheme incentives for precision manufacturing and textile machinery create specification upgrade cycles among domestic bearing distributors. BIS standards for industrial lubricants tighten quality benchmarks for imported formulations. Maharashtra and Gujarat industrial corridors concentrate early adoption of food-grade polyurea formulations in dairy processing equipment.
Japan
NSK and JTEKT procurement teams negotiate multi-year formulation lock-ins rather than spot purchasing for electric axle applications. METI carbon neutrality roadmaps pressure compounders toward lower-emission thickener synthesis routes. Kanto region automotive bearing manufacturers now require suppliers to co-develop thermal aging test protocols specific to EV powertrains.
Polyurea Greases Market Competitive Landscape
Listed leaders compete with private specialists across formulation tiers and geographic reach. The vendor base stratifies between integrated petrochemical majors with captive thickener supply and independent lubricant compounders with application engineering depth. Three archetypes dominate: backward-integrated energy majors, bearing-system integrators with captive lubricant production, and specialized formulation houses serving niche certification tiers. Competitive moves center on multi-year OEM formulation lock-ins and NSF H1 registration acceleration to capture food-processing retrofit demand.
Within the integrated energy tier, ExxonMobil and Shell exemplify players leveraging upstream chemical assets to secure diisocyanate feedstock reliability. SKF occupies a distinctive position as a bearing-system integrator with captive grease production tied to component sales, compressing traditional procurement autonomy for industrial buyers. Klüber Lubrication represents the specialized formulation archetype, anchoring premium positioning through application-engineered products for wind turbine and food-processing segments where certification barriers limit qualified supplier pools.
| Leading Market Players |
|---|
| ExxonMobil |
| Chevron |
| Shell |
| TotalEnergies |
| SKF |
| Fuchs Petrolub |
| Klüber Lubrication |
| Castrol |
| Lubrizol |
| Others |
Value Network & Pricing Analysis
NSF H1 certification gates both supply qualification and price differentiation simultaneously, constraining qualified supplier pools for food-grade formulations while enabling premium capture that separates certified from uncertified tiers. REACH restrictions on aromatic amines and OSHA PEL isocyanate handling protocols layer additional compliance costs that compounders pass through to specification-sensitive buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with NSF H1 registration and thermal performance specifications as the primary differentiation drivers. Price erosion runs through standard industrial grades as Asian compounders expand capacity, while food-grade and wind turbine formulations retain pricing power due to limited qualified competition. Maintenance providers at steel mills and mining operations exhibit highest price sensitivity, whereas automotive OEMs negotiating multi-year formulation lock-ins prioritize technical compliance over unit cost.
Supply Chain Analysis
Inventory cycles for aromatic diisocyanates stretch 8-12 weeks, compressing grease compounder margins when feedstock availability tightens. Polyurea thickener production draws from diisocyanate supply chains concentrated in China, South Korea, and Germany, with base oil sourcing anchored in the US Gulf Coast and Rotterdam refining hubs. Single-source vulnerability around specialty diamines for high-temperature grades poses structural risk, particularly for European compounders dependent on Asian imports. Distribution runs through authorized industrial distributors serving bearing OEMs and direct supply agreements with automotive and wind turbine manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as electric vehicle thermal management requirements force specification upgrades across automotive supply chains, displacing incumbent lithium complex chemistry before penetration rates mature.
For Market Incumbents: Fortify captive thickener supply through backward integration into diisocyanate chemistry or long-term offtake agreements with Northeast Asian feedstock producers. Accelerate NSF H1 registration pipelines to defend margin position against emerging compounders targeting food-processing retrofit demand, while locking in multi-year formulation agreements with NSK, SKF, and JTEKT before second-source qualification windows narrow. For New Entrants and Emerging Players: Differentiate on application-engineered formulations for wind turbine main bearings and food-grade dairy processing equipment, where certification barriers limit incumbent response speed. Target India's Maharashtra and Gujarat industrial corridors through partnerships with domestic bearing distributors, leveraging PLI scheme incentives to penetrate precision manufacturing upgrade cycles without direct confrontation with integrated energy majors. For Investors and Strategic Acquirers: EU PFAS restriction timelines reshape the acquisition landscape by expanding polyurea's addressable market into extreme-temperature niches currently held by fluorinated alternatives. Focus on mid-cap compounders with existing synthetic grease infrastructure and dormant NSF H1 registration pathways, as these assets command scarcity premium through the analysis window. Watch for ECHA lithium soap precursor restriction announcements as inflection signals for accelerated specification migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diisocyanate Feedstock | ExxonMobil's captive thickener chemistry secures supply reliability against Northeast Asian shipping disruptions. |
| NSF H1 Registration Acceleration | Klüber Lubrication's toxicology investment captures North American meatpacking corridor retrofit demand before competitors qualify. |
| Multi-Year OEM Formulation Lock-Ins | SKF's bearing-system bundling compresses procurement autonomy and elevates technical collaboration requirements. |
| Digital-Enabled Condition Monitoring Integration | Predictive maintenance platforms at Australian Pilbara mining operators create attach-rate expansion for premium specifications. |
| Green Manufacturing Transition | METI carbon neutrality roadmaps pressure Japanese compounders toward lower-emission thickener synthesis routes. |
Research Methodology
Cross-validation between primary interviews with grease compounder R&D directors, automotive OEM procurement leads, and wind turbine maintenance operators anchors the qualitative findings, while secondary sources including customs trade data, ECHA regulatory filings, SEC 10-K lubricant segment disclosures, and NSF International registration databases provide quantitative grounding. Bottom-up demand modeling from end-use equipment counts and top-down triangulation from lubricant industry association reports ensure coverage consistency across the analysis window.
Sensitivity analysis around electric vehicle penetration rates and PFAS substitution timelines frames the forecast uncertainty. Segmentation dimensions include product type tier, application severity grade, end-user procurement autonomy level, and regional regulatory cluster. CAGRs derive from equipment installation forecasts and specification migration curves, with thermal aging test protocol adoption and REACH compliance deadlines as industry-specific forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under base assumptions of sustained EV thermal management specification upgrades and stable diisocyanate feedstock availability; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Automotive Lubricants Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Israel Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Construction Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
Industrial Gear Oil Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
India Industrial Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Saudi Arabia Lubricants Market