
 Poland Commercial Vehicles Lubricants Market | 2026-2036
Poland Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Commercial Vehicles Lubricants Market Analytics
The gap between premium synthetic formulations and mineral-based commodity lubricants is shifting as fleet operators extend drain intervals and OEMs tighten warranty conditions. PKN ORLEN anchors its position through captive refinery capacity and nationwide fuel-station distribution. FUCHS differentiates via specialized hydraulic oils for construction and agricultural commercial vehicles. BP PLC (Castrol) competes on technical partnerships with European truck manufacturers operating in Poland.
Poland commercial vehicles lubricants encompass refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and protect powertrain components under severe-duty cycles, with viscosity grades typically spanning SAE 15W-40 to 5W-30 for modern diesel engines. Engine Oil commands the largest revenue pool given per-unit consumption volumes across heavy-duty truck fleets, while Transmission Fluid generates higher margin intensity due to specification complexity and OEM approval requirements. Hydraulic Oil demand tracks Poland's construction equipment utilization rates, with fleet operators representing the fastest-growing end-user channel as centralized procurement displaces fragmented retail purchasing.
Polish lubricant producers navigate EU REACH chemical registration requirements and F-Gas Regulation constraints on fluorinated compound content, while the national regulator enforces BIS-equivalent product quality certifications for imported formulations. The EU Green Deal's carbon-border adjustment mechanisms will reshape raw material sourcing economics for blenders serving Poland's commercial vehicle base. Stakeholders must monitor how Euro VII engine standards recalibrate OEM factory-fill specifications and aftermarket compatibility requirements.
Market Dynamics
Poland's commercial vehicle lubricant sector faces intense pressure from Euro VII emission standards, which OEMs are translating into stricter factory-fill specifications and extended drain interval requirements that favor synthetic formulations over mineral bases.
Growth Catalysts
- EU Green Deal alignment:Poland's adoption of carbon-border adjustment mechanisms is accelerating fleet operator investment in lower-emission lubricant technologies to avoid compliance penalties.
- Fleet operator consolidation:Centralized procurement by logistics companies across Silesian and Greater Poland voivodeships is displacing fragmented retail purchasing and driving volume commitments to premium synthetic grades.
- Construction equipment utilization:Hydraulic oil demand tracks Poland's infrastructure investment cycles, with specialized formulations for agricultural and construction commercial vehicles capturing specification-driven margins.
Market Restraints
- Base oil supply concentration:Group II and Group III base stock sourcing depends on limited European refinery capacity, exposing Polish blenders to input cost volatility and supply interruption risks.
- REACH registration burden:EU ECHA chemical compliance requirements impose fixed costs that disproportionately burden small and mid-sized domestic lubricant formulators against integrated majors.
- Extended drain interval compression:OEM warranty conditions now mandating 100,000+ kilometer service intervals are reducing per-vehicle lubricant consumption volumes despite unit value increases.
Strategic Opportunities
- Sub-regional voivodeship penetration:Lesser Poland and Podkarpackie voivodeships show underdeveloped fleet service infrastructure relative to freight density growth on east-west corridors.
- Biodegradable hydraulic fluids:EU F-Gas Regulation constraints on fluorinated compounds create white space for ester-based formulations in environmentally sensitive construction applications.
- Digital fleet management integration:Telematics-enabled oil condition monitoring is automating predictive maintenance scheduling and creating subscription-based lubricant replenishment channels.
Industry Challenges
- OEM approval timeline compression:Accelerated Euro VII certification cycles demand faster laboratory validation and field testing protocols than domestic testing infrastructure currently supports.
- Specialized formulation talent scarcity:Poland's technical education pipeline produces insufficient tribologists and lubricant chemists relative to synthetic formulation complexity requirements.
- Legacy fleet compatibility:Pre-Euro VI commercial vehicles in Polish operating fleets require backward-compatible formulations that complicate inventory management for multi-generation service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Commercial Vehicles Lubricants Market |
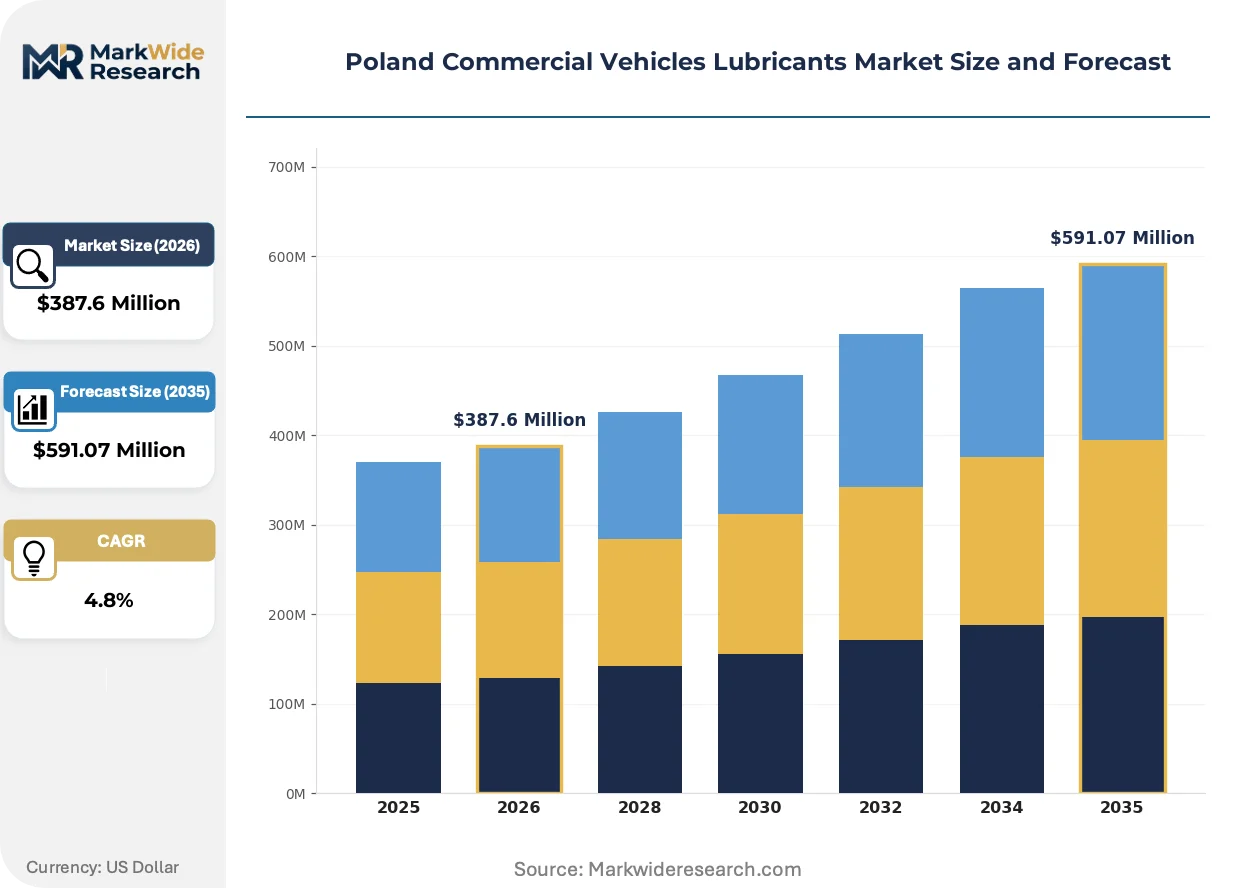
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Hydraulic Oil, Grease Application: Heavy-Duty Trucks, Light-Duty Trucks, Buses, Vans End User: Fleet Operators, Retail Customers, Repair Shops, Distributors Distribution Channel: Online Retail, Direct Sales, Convenience Stores, Automotive Shops |
| Companies Covered | BP PLC (Castrol), FUCHS, LOTOS OIL, PKN ORLEN (ORLEN oil), TotalEnergies, ExxonMobil Corporation, Royal Dutch Shell Plc, Motul, Valvoline Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Commercial Vehicles Lubricants Market Evolving Landscape
Poland's lubricant landscape is being actively reconfigured by three intersecting forces: synthetic formulation chemistry advances, EU regulatory tightening on chemical content and emissions, and fundamental shifts in how fleet operators procure and manage fluid consumption across their vehicle bases.
Artificial intelligence-driven oil analysis platforms are automating real-time viscosity degradation monitoring and predictive drain scheduling for heavy-duty truck fleets. PKN ORLEN and major logistics operators are piloting sensor-based condition monitoring that transmits fluid health data directly to maintenance management systems. This capability is automating the transition from calendar-based to condition-based maintenance, compressing traditional lubricant sales cycles while opening recurring revenue streams for integrated service providers.
EU F-Gas Regulation constraints on fluorinated greenhouse gases are forcing reformulation of specialty lubricants previously dependent on perfluoropolyether chemistry. ECHA enforcement of restricted substance lists is compelling Polish blenders to source alternative thickeners and base stocks for high-temperature applications. Construction equipment segments operating in sensitive watershed areas face the most acute substitution pressure, driving adoption of polyol ester and polyalkylene glycol alternatives.
Centralized fleet procurement is consolidating purchasing authority away from individual depot managers toward Warsaw and Kraków-based procurement headquarters. Long-term supply agreements with performance guarantees are displacing spot market transactions for engine oils and transmission fluids. This concentration is most visible among cross-border logistics operators serving German and Czech manufacturing supply chains, where total cost of ownership metrics now dominate specification decisions over per-liter pricing.
Poland Commercial Vehicles Lubricants Market Segmentation
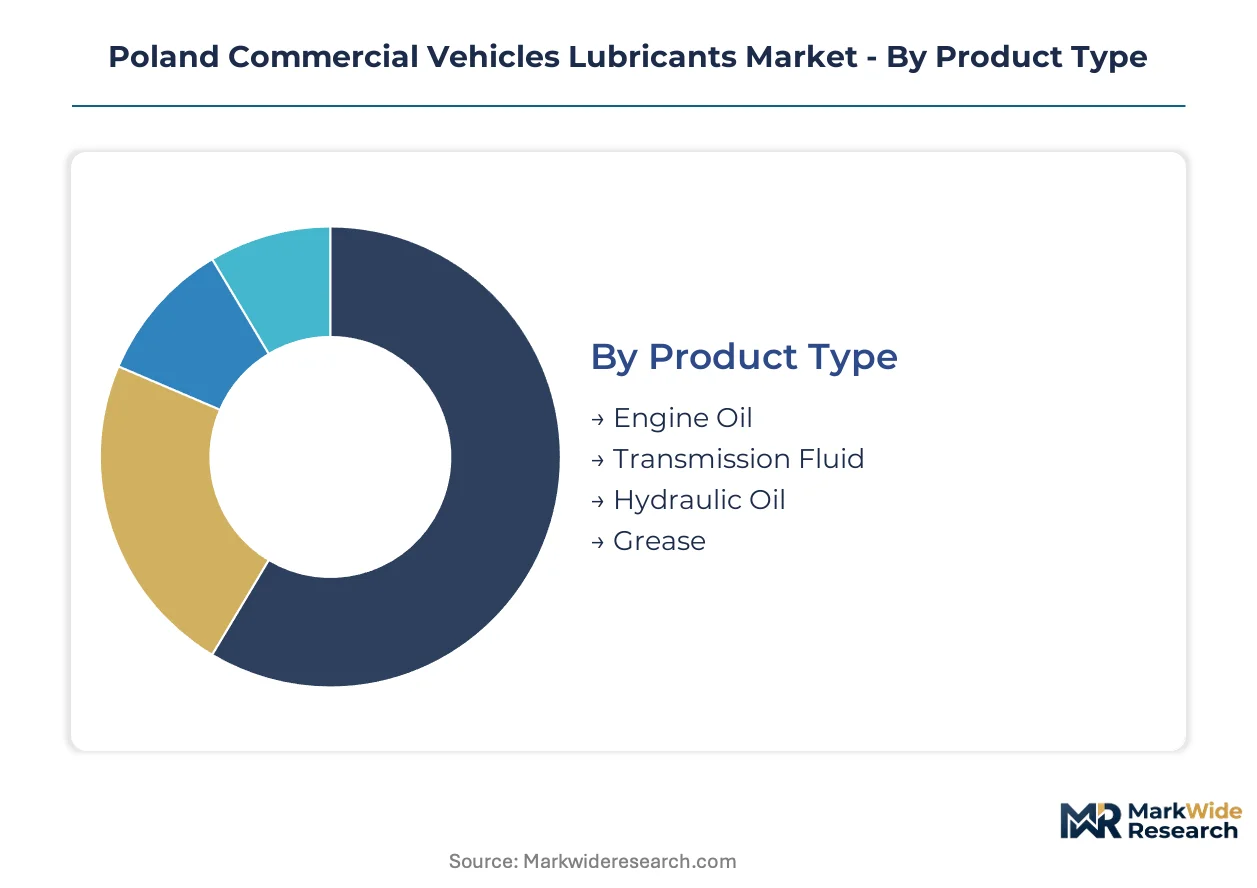
Poland's commercial vehicle lubricant market segments along four distinct dimensions that each carry different margin structures and procurement dynamics. Fleet operators, construction contractors, and independent repair networks each trigger distinct specification requirements and volume patterns across these categories.
Product Type:
Upgrade cycles from mineral to synthetic formulations are compressing replacement intervals while elevating per-liter values across all product categories.
- Engine Oil:Refined petroleum-based and synthetic formulations spanning SAE 15W-40 to 5W-30 viscosity grades for modern diesel engines. Demand concentrates in heavy-duty truck fleets across Silesian and Greater Poland voivodeships where freight density drives per-unit consumption volumes. Extended drain intervals mandated by Euro VII standards are accelerating synthetic penetration despite higher upfront costs.
- Transmission Fluid:Specialized formulations requiring OEM approval for warranty compliance, with higher specification complexity than engine lubricants. Fleet procurement headquarters in Warsaw and Kraków are consolidating purchasing authority for transmission fluids through long-term supply agreements with performance guarantees.
- Hydraulic Oil:Tracks Poland's construction equipment utilization rates with specialized formulations for agricultural and earth-moving machinery.
- Grease:Lithium-complex and calcium-sulfonate thickeners for chassis, wheel bearing, and fifth-wheel applications in commercial vehicle maintenance.
Engine Oil sits at the top of the volume ranking, with Transmission Fluid climbing the fastest as OEM approval requirements tighten.
Application:
Vehicle duty cycles determine lubricant stress profiles, with severe-service applications demanding higher-grade formulations and more frequent monitoring.
- Heavy-Duty Trucks:Long-haul freight vehicles operating 150,000+ kilometers annually with extended drain interval requirements. EU Green Deal alignment is accelerating fleet investment in lower-emission lubricant technologies to avoid carbon-border adjustment penalties.
- Light-Duty Trucks:Urban delivery and regional distribution vehicles with stop-start duty cycles generating higher thermal stress on lubricant films.
- Buses:Public transit and intercity coach applications with high passenger-load factors and regulated emission compliance requirements.
- Vans:Last-mile delivery and service vehicle segments with fragmented ownership structures and retail-dominant purchasing patterns.
Heavy-Duty Trucks generate the dominant volume share, while Light-Duty Trucks are expanding most quickly through e-commerce logistics growth.
End User:
Procurement centralization is bifurcating the customer base between volume-contracted fleet operators and price-sensitive fragmented buyers.
- Fleet Operators:Centralized procurement by logistics companies displacing fragmented retail purchasing across Silesian and Greater Poland voivodeships. Telematics-enabled oil condition monitoring is automating predictive maintenance scheduling and creating subscription-based replenishment channels.
- Retail Customers:Owner-operators and small fleet owners purchasing through convenience stores and automotive shops with spot-market pricing sensitivity.
- Repair Shops:Independent service networks managing multi-generation fleet compatibility requirements for pre-Euro VI through Euro VII vehicles.
- Distributors:Regional stockists serving secondary voivodeships with inventory management complexity from specification proliferation.
Fleet Operators command the volume leadership position, with Repair Shops gaining share fastest through outsourced maintenance contracts.
Distribution Channel:
Channel economics reflect the tension between immediate availability requirements and total cost optimization in procurement workflows.
- Online Retail:E-commerce platforms capturing specification-driven buyers with technical documentation and bulk pricing transparency.
- Direct Sales:Manufacturer-to-fleet agreements with performance guarantees and integrated fluid analysis services.
- Convenience Stores:PKN ORLEN's nationwide fuel-station network providing captive refinery capacity with immediate roadside availability.
- Automotive Shops:Independent service points with technical consultation capabilities for complex specification matching.
Direct Sales leads volume contribution, with Online Retail showing the steepest expansion trajectory through procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's commercial vehicle lubricant sector operates at higher synthetic penetration rates than Poland, yet both markets face identical Euro VII compliance timelines and carbon-border adjustment pressures from Brussels.
Silesian Voivodeship
Heavy-duty truck fleets along the A4 and A1 motorway corridors generate concentrated demand for extended-drain synthetic engine oils. ECHA REACH registration requirements filter imported formulations through rigorous chemical safety documentation. Katowice-based logistics parks house centralized procurement operations for cross-border freight operators serving German manufacturing supply chains.
Greater Poland Voivodeship
Distribution centers around Poznań drive hydraulic oil consumption for regional construction equipment fleets. EU Green Deal carbon-border adjustment mechanisms incentivize lower-emission lubricant procurement decisions. The Konin-Turek industrial zone hosts blending facilities supplying factory-fill agreements with domestic truck assemblers.
Lesser Poland Voivodeship
Underdeveloped fleet service infrastructure relative to freight density growth on east-west corridors creates white space for distributor expansion. F-Gas Regulation constraints on fluorinated compounds pressure hydraulic fluid reformulation in environmentally sensitive construction zones. Kraków procurement headquarters consolidate purchasing authority for transmission fluids through performance-guaranteed supply agreements.
Masovian Voivodeship
Warsaw-based fleet operators pilot telematics-enabled oil condition monitoring for predictive maintenance scheduling. BIS-equivalent product quality certifications enforced by national regulators govern imported formulation standards. The Warsaw-Łódź logistics belt attracts direct sales channels from major blenders seeking volume commitments from centralized procurement functions.
Poland Commercial Vehicles Lubricants Market Competitive Landscape
Top-tier vendors anchor synthetic formulation supply, while mineral-based commodity producers compete on price-sensitive retail channels. The vendor base organizes around captive refinery integration, specialized hydraulic expertise, and technical partnership networks with OEMs. Three archetypes dominate: integrated energy majors with downstream lubricant divisions, independent specialists in construction and agricultural applications, and premium synthetic formulators targeting extended-drain specifications. Competitive moves concentrate on long-term fleet supply agreements and digital condition monitoring service integration.
Within the integrated major tier, PKN ORLEN anchors its position through captive refinery capacity and nationwide fuel-station distribution reach. BP PLC (Castrol) and FUCHS occupy differentiated positions—Castrol through technical partnerships with European truck manufacturers, FUCHS via specialized hydraulic oils for construction and agricultural commercial vehicles. These three exemplify how market access, specification complexity, and OEM relationship depth create distinct competitive vectors.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| FUCHS |
| LOTOS OIL |
| PKN ORLEN (ORLEN oil) |
| TotalEnergies |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| Motul |
| Valvoline Inc |
| Others |
Value Network & Pricing Analysis
Tribologist and lubricant chemist scarcity in Poland's technical education pipeline widens labor-cost differentials between synthetic formulation specialists and commodity blenders, compressing margins at the economy tier while premium pricing holds firm.
Pricing Analysis
Bundled fluid analysis services separate from unbundled per-liter transactions across fleet procurement channels. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels stratifies by Euro VII certification grade and volume commitment scale. Pricing pressure stems from centralized fleet procurement headquarters extracting performance guarantees. Owner-operators in fragmented retail channels exhibit highest price sensitivity, while cross-border logistics operators prioritize total cost of ownership metrics.
Supply Chain Analysis
Dual-sourcing requirements mandated by major fleet operators force Polish blenders to qualify multiple Group II and Group III base stock suppliers across Germany, the Netherlands, and Belgium. Raw material dependencies center on API Group base oils, polyalphaolefin synthetic stocks, and specialized additive packages from European chemical producers. Supply chain risk concentrates in single-source vulnerability for high-performance ester base stocks under EU F-Gas Regulation constraints. Distribution runs through PKN ORLEN's captive refinery network, direct manufacturer-to-fleet agreements, and regional distributor stockists serving secondary voivodeships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's commercial vehicle lubricant sector represents a late-cycle quality story as Euro VII emission standards shift fleet procurement toward premium synthetic formulations with extended drain intervals and OEM warranty compliance.
For Market Incumbents: Deploy captive refinery integration to anchor cost position against imported base oil volatility. Secure long-term supply agreements with telematics-enabled condition monitoring services to lock in fleet operator loyalty. Counter the threat of specialized hydraulic formulators by accelerating biodegradable ester-based product registration under EU F-Gas Regulation timelines. For New Entrants and Emerging Players: Begin with underdeveloped fleet service infrastructure in Lesser Poland and Podkarpackie voivodeships where freight density growth outpaces distributor coverage. Target construction equipment contractors facing F-Gas-driven hydraulic fluid reformulation pressure in environmentally sensitive zones. Pursue a technical partnership route with agricultural machinery OEMs seeking specialized lubricant specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among independent blenders lacking captive base oil supply but holding strong regional distributor relationships in east-west corridor logistics markets. Long-term viability hinges on synthetic formulation capability buildout and OEM approval portfolio depth. Watch for inflection when Euro VII factory-fill specification announcements trigger accelerated laboratory validation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group II/III refinery capacity insulates Polish blenders from European supply interruption risks. |
| Telematics-Enabled Condition Monitoring | Sensor-based oil analysis automates predictive maintenance scheduling for heavy-duty truck fleets. |
| Biodegradable Hydraulic Fluid Registration | Ester-based formulations capture specification-driven margins under EU F-Gas Regulation constraints. |
| OEM Technical Partnership Expansion | Factory-fill agreements with domestic truck assemblers lock in aftermarket compatibility requirements. |
| Regional Distributor Acquisition | Podkarpackie and Lesser Poland voivodeship coverage addresses freight density growth gaps. |
Research Methodology
Direct dialogue with lubricant formulation chemists, fleet procurement directors, OEM technical partnership managers, and independent service network operators combined with secondary validation from ECHA REACH registration databases, Polish Central Statistical Office trade data, SEC filings of integrated energy majors, and EU Green Deal implementation trackers. Bottom-up and top-down triangulation cross-validated volume estimates against base oil import flows and commercial vehicle registration patterns.
Bottom-up modeling segmented the market by product type, application duty cycle, end-user procurement structure, and distribution channel across the analysis window. CAGRs derived from elasticity-adjusted consumption models incorporating Euro VII specification transition timelines and synthetic penetration curves. Key forecast inputs included fleet operator consolidation rates and construction equipment utilization indices from infrastructure investment cycles.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to EU carbon-border adjustment mechanisms and geopolitical disruptions to Group III base oil supply routes. Forecasts reflect documented assumptions regarding OEM approval timeline compression and technical education pipeline output. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Sri Lanka Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Mining Lubricants Market
Lubricants
Anti-Static Oil Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market