
 Lube Skid Market | 2026-2036
Lube Skid Market Size, Share, and Industry Trends Forecast 2026-2036
Lube Skid Market Analytics
API-certified heavy-duty configurations are redrawing competitive benchmarks across the lube skid landscape. Taylor Pump & Lift leverages in-house tank fabrication to control lead times on custom builds. Fluidall anchors its position through a national distributor network serving fleet maintenance depots. Maintainer Corporation of Iowa specializes in severe-service skids engineered for agricultural and construction OEM channel partners.
A lube skid is a self-contained, frame-mounted lubrication distribution system comprising storage tanks, pumping units, filtration modules, and metered dispensing hardware, typically fabricated from carbon or stainless steel with capacities from 50 to 500 gallons. The assembly delivers bulk oil, grease, and coolant to off-road equipment, eliminating drum handling and reducing contamination exposure. Standard skids dominate unit volume through OEM bundling agreements with truck body manufacturers, while customized configurations capture disproportionate margin pools from oil and gas field service operators requiring hazardous-location certifications. Mobile lube skids represent the fastest-expanding installation category, driven by construction companies adopting centralized fleet servicing models across dispersed job sites.
OSHA lockout/tagout standards and EPA Spill Prevention, Control, and Countermeasure rules shape tank design, secondary containment integration, and pump seal specifications for domestic manufacturers. DOT highway transport regulations govern axle loading and tie-down configurations for mobile units crossing state lines. Stakeholders must weigh permanent infrastructure investments against flexible mobile deployments as customer consolidation and site centralization redefine service economics.
Market Dynamics
EPA Tier 4 Final emissions mandates are compressing diesel-powered service equipment deployment, redirecting capital toward electric pump configurations and forcing fabricators to redesign thermal management and power electronics integration.
Growth Catalysts
- Multi-well pad drilling density:Permian Basin operators demand rapid equipment turnaround cycles that bulk lubrication systems deliver. Pad consolidation is eliminating drum-based servicing at scale.
- OSHA lockout/tagout enforcement:Secondary containment integration and pump seal specifications are becoming non-negotiable in fleet maintenance contracts. Compliance-driven replacement cycles are accelerating.
- Western Australia mining procurement:Self-contained lubrication systems are displacing centralized depot models across Pilbara iron ore and Goldfields operations. Remote site logistics favor mobile deployment.
Market Restraints
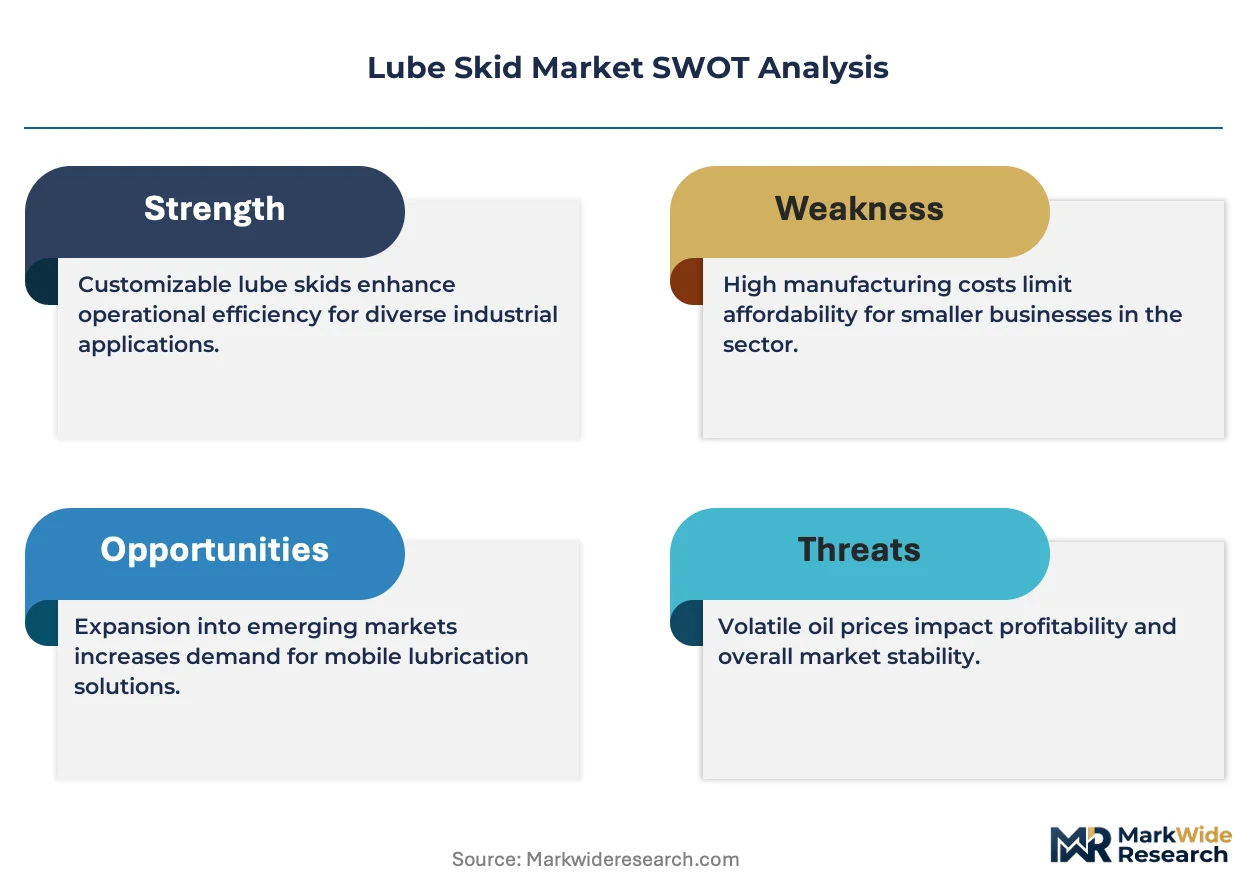
- Stainless steel input volatility:Tank fabrication costs swing with nickel and chromium alloy pricing. Carbon steel alternatives face corrosion warranty limitations in severe-service applications.
- DOT highway transport compliance:Axle loading and tie-down configurations for mobile units crossing state lines add engineering overhead and limit rapid redeployment flexibility.
- Electric pump thermal derating:High-ambient operating environments in Australian and Middle Eastern deployments constrain flow rates versus diesel equivalents. Battery energy density limits runtime.
Strategic Opportunities
- Hazardous-location certification gaps:Oil and gas field service operators in the Permian Basin and Bakken Formation require Class I Division 1 configurations that few fabricators currently supply.
- Construction fleet centralization:Dispersed job site servicing models are creating demand for trailer-mounted skids with integrated power generation. Rental channel penetration remains underdeveloped.
- EU Green Deal alignment:REACH-compliant synthetic lubricant handling systems are becoming mandatory for European mining and quarrying operations. Early certifiers capture specification lock-in.
Industry Challenges
- EPA Spill Prevention, Control and Countermeasure documentation:Facility-specific spill response plans require tank-by-tank engineering validation that extends lead times and inflates project engineering costs.
- Filtration module integration complexity:OEM bundling agreements with truck body manufacturers demand proprietary hose routing and control interfaces that fragment supplier ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lube Skid Market |
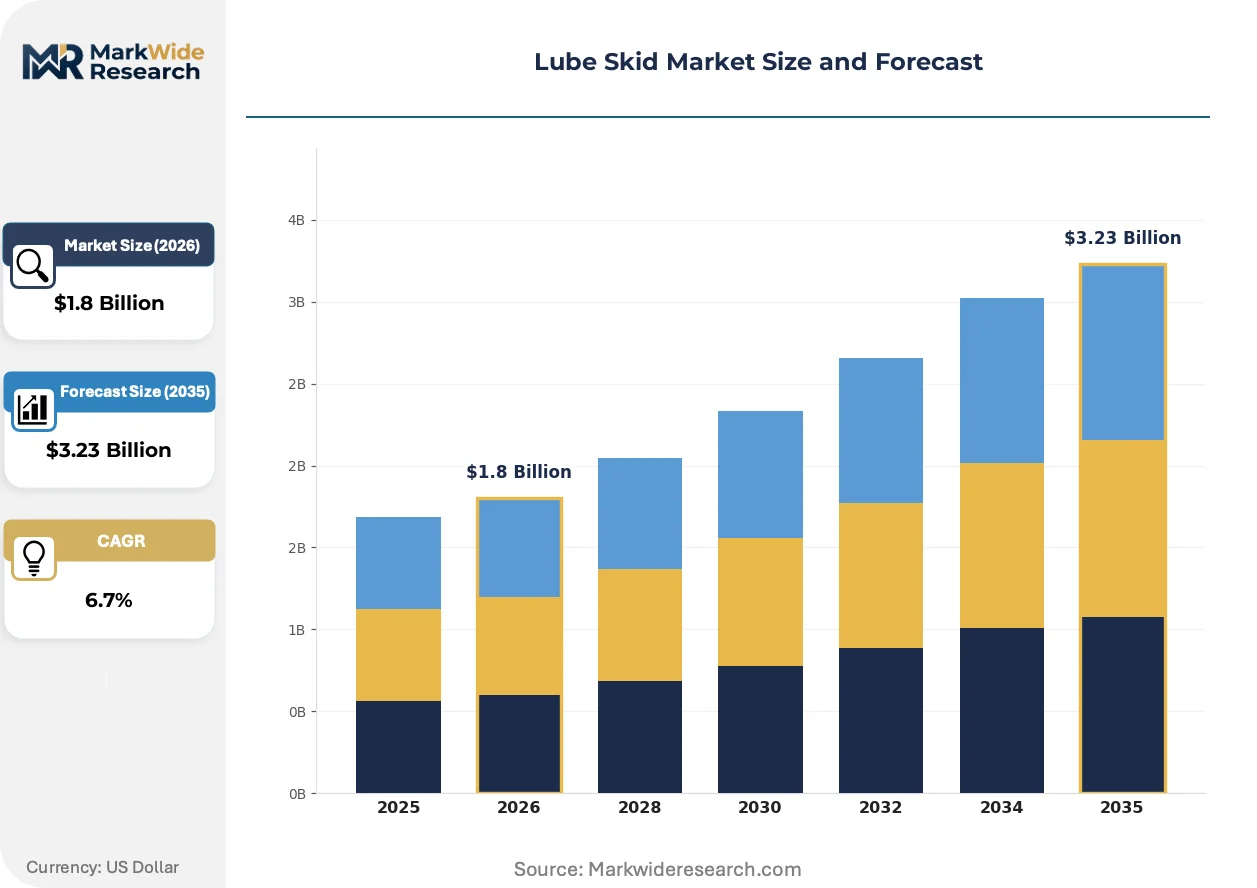
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lube Skids, Customized Lube Skids, Mobile Lube Skids, Fixed Lube Skids End User: Automotive Repair Shops, Industrial Maintenance Facilities, Oil & Gas Operations, Construction Companies Size: Small Skids, Medium Skids, Large Skids, Extra Large Skids Installation: Permanent Installation, Temporary Installation, On-Site Fabrication, Pre-Manufactured |
| Companies Covered | Taylor Pump & Lift, Fluidall, Maintainer Corporation of Iowa, Sage Oil Vac, Service Trucks International, Elliott Machine Works, Curry Supply, Summit Truck Bodies, Iowa Mold Tooling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lube Skid Market Evolving Landscape
Digital fluid monitoring and predictive maintenance architectures are rewriting service economics for lubrication infrastructure. Fabricators are racing to embed telemetry before specification standards crystallize.
Variable-frequency drive electric pumps are displacing fixed-speed diesel alternatives in underground mining and enclosed maintenance facilities. Australian coal and hard-rock operators are specifying VFD configurations for ventilation-limited environments. The technology is compressing total cost of ownership calculations by eliminating fuel logistics and reducing noise exposure compliance costs.
REACH substance restrictions on certain lubricant additives are forcing reformulation of hydraulic and gear oils used in European heavy equipment. ECHA evaluations are driving compatibility testing requirements for seal materials and tank coatings. Skid fabricators serving EU-bound OEM channels are accelerating stainless steel specification to handle aggressive synthetic chemistries.
Centralized procurement by consolidated mining contractors is compressing vendor lists and demanding outcome-based fluid management contracts. Equipment-as-a-service models are displacing capital purchase arrangements for large fleet operators. Western Australian iron ore majors and Permian Basin drilling contractors are piloting full-fluid-responsibility agreements with penalty clauses for contamination events.
Lube Skid Market Segmentation
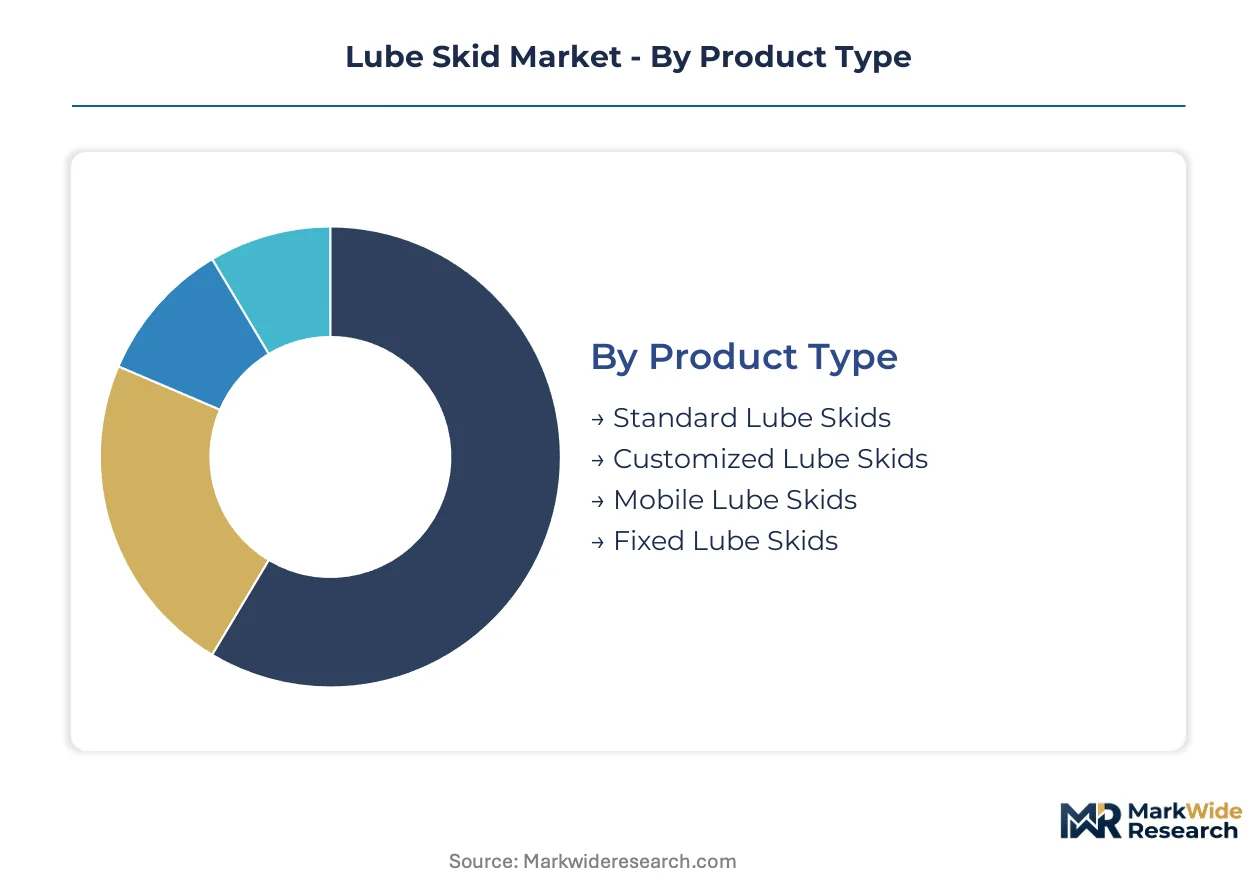
Lube skid segmentation reveals how fabrication economics and deployment flexibility create divergent margin structures across product configurations. Customer consolidation in mining and oil field services is compressing vendor lists within specific size and installation categories.
Product Type:
Standard configurations face mounting substitution pressure from rental fleet operators and integrated service providers bundling lubrication into broader maintenance contracts.
- Standard Lube Skids:Pre-engineered assemblies with fixed tank configurations and universal pump specifications serve high-volume OEM channel partners. Fleet maintenance depots in the Permian Basin specify these for rapid deployment across multi-well pad operations where customization adds unnecessary lead time.
- Customized Lube Skids:Engineered-to-order systems incorporate hazardous-location certifications, specialized filtration modules, and proprietary control interfaces demanded by oil and gas field service operators. Western Australia mining contractors specify these for Pilbara iron ore sites requiring Class I Division 1 compliance and extreme-ambient thermal management.
- Mobile Lube Skids:Trailer-mounted or truck-body-integrated units with DOT-compliant tie-downs and axle-loading configurations serve construction fleet centralization trends.
- Fixed Lube Skids:Permanent infrastructure installations anchor centralized depot models in agricultural and industrial maintenance facilities.
Standard lube skids anchor the volume base while mobile lube skids gain share at the steepest rate.
End User:
Cost tier stratification separates specification-intensive energy and mining applications from price-sensitive automotive service channels.
- Automotive Repair Shops:Small-capacity skids with basic metered dispensing serve quick-lube operators and independent garages. EPA Spill Prevention, Control and Countermeasure compliance requirements are accelerating replacement of aging drum-based systems in US metropolitan markets.
- Industrial Maintenance Facilities:Medium-capacity fixed installations with integrated filtration and coolant handling support manufacturing plant centralized lubrication programs. OSHA lockout/tagout enforcement is mandating secondary containment upgrades that favor skid replacement over retrofit.
- Oil & Gas Operations:Severe-service mobile configurations with explosion-proof electrical enclosures and synthetic lubricant compatibility dominate Permian Basin and Bakken Formation procurement.
- Construction Companies:Trailer-mounted rental fleet deployments with integrated power generation serve dispersed job site servicing models.
Automotive repair shops anchor the volume base while oil and gas operations capture the highest margin pools.
Size:
Application scale determines tank fabrication material selection and transport modality constraints across the size spectrum.
- Small Skids:50-100 gallon carbon steel assemblies serve light-duty fleet maintenance and agricultural equipment servicing. Australian Goldfields operations specify these for remote exploration camps where helicopter transport limits payload.
- Medium Skids:150-250 gallon configurations balance capacity against DOT highway transport axle-loading limits for mobile deployment.
- Large Skids:300-400 gallon stainless steel specifications handle aggressive synthetic chemistries required by EU Green Deal-aligned mining operations.
- Extra Large Skids:500+ gallon fixed infrastructure serves consolidated mining contractor depot models with full-fluid-responsibility contract structures.
Medium skids anchor the volume base while large skids expand most quickly on synthetic lubricant compatibility requirements.
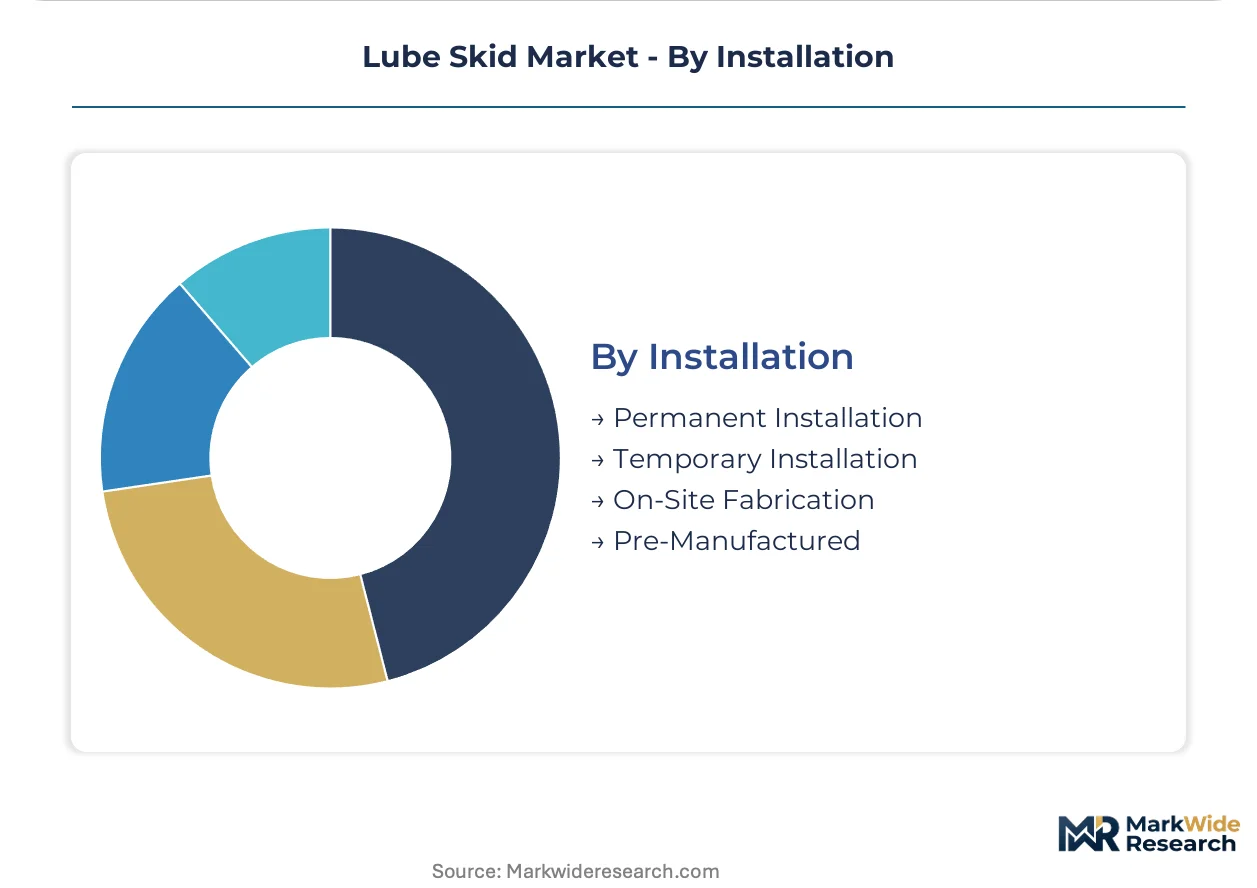
Installation:
Customer type separation distinguishes capital-purchase infrastructure from operational-expense rental models redefining service economics.
- Permanent Installation:Concrete-anchored fixed systems with hard-piped distribution networks serve industrial maintenance facilities and mining depot centralization. Western Australian iron ore majors favor these under outcome-based fluid management contracts with contamination penalty clauses.
- Temporary Installation:Rapid-deploy skids with modular connection points serve construction project phases and emergency maintenance response.
- On-Site Fabrication:Field-welded tank assemblies with location-specific spill containment address remote site access constraints in Pilbara and Permian Basin operations.
- Pre-Manufactured:Factory-tested skids with documented weld certifications and hydrostatic test records accelerate commissioning for EPA and OSHA compliance audits.
Pre-manufactured installations anchor the volume base while temporary installations climb the fastest on construction fleet rental channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for lube skid systems reflect concentrated mining equipment procurement from Australia and specialized hazardous-location fabrications from the United States. Western Australian iron ore majors import mobile lubrication infrastructure to service dispersed Pilbara operations. Permian Basin operators source explosion-proof configurations from domestic fabricators while exporting surplus standard skids to Latin American construction markets.
United States
Multi-well pad drilling density in the Permian Basin accelerates procurement of rapid-deployment lubrication systems. EPA Tier 4 Final emissions mandates compress diesel-powered equipment deployment while redirecting capital toward electric pump configurations. Houston-area fabricators supply explosion-proof skids to Bakken Formation operators requiring Class I Division 1 certifications.
Australia
Pilbara iron ore and Goldfields mining operations displace centralized depot models with self-contained mobile lubrication systems. TGA-equivalent state mining safety regulations mandate secondary containment integration for remote site deployments. Perth-based procurement offices specify severe-service skids for helicopter-transport to exploration camps in Western Australia's remote northwest.
Germany
REACH-compliant synthetic lubricant handling systems become mandatory for European mining and quarrying operations under EU Green Deal alignment. ECHA substance restrictions force compatibility testing for seal materials and tank coatings. Bavarian industrial equipment manufacturers specify stainless steel skid configurations for aggressive synthetic chemistries in Ruhr Valley mining operations.
Canada
Oil sands operators in Alberta specify heated tank configurations for cold-weather synthetic lubricant handling. Health Canada and provincial environmental regulators enforce spill prevention documentation for mobile units crossing provincial boundaries. Calgary-based energy service companies procure trailer-mounted skids for dispersed northern drilling campaigns.
Brazil
Iron ore majors in Minas Gerais pilot centralized fleet servicing models with imported mobile lubrication infrastructure. ANVISA-aligned industrial safety standards shape secondary containment specifications for severe-service applications. São Paulo-state construction contractors rent trailer-mounted skids for dispersed infrastructure project phases.
Lube Skid Market Competitive Landscape
Listed leaders compete with private specialists across fabrication capacity and hazardous-location certification depth. The vendor base clusters around three tiers: national distributor networks controlling fleet maintenance depot channels, in-house tank fabricators managing custom build lead times, and severe-service specialists engineering for agricultural and construction OEM partnerships. Strategic moves concentrate on M&A to secure distributor relationships and capacity expansion to capture rental fleet operator procurement.
Among Iowa-based fabricators, Taylor Pump & Lift and Maintainer Corporation of Iowa exemplify the in-house production archetype, while Fluidall represents the national distributor network model. These three companies anchor competitive positioning across standard and customized configuration tiers without overlapping significantly in end-user specialization.
| Leading Market Players |
|---|
| Taylor Pump & Lift |
| Fluidall |
| Maintainer Corporation of Iowa |
| Sage Oil Vac |
| Service Trucks International |
| Elliott Machine Works |
| Curry Supply |
| Summit Truck Bodies |
| Iowa Mold Tooling |
| Others |
Value Network & Pricing Analysis
Twelve-to-sixteen-week lead times for custom stainless steel tank fabrication concentrate pricing power with in-house fabricators in Iowa and Texas while compressing margins for distributors sourcing from third-party metalworkers. This lead-time band reflects supply-chain concentration in domestic tank fabrication and shapes how buyers trade off customization premiums against standard-configuration availability.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the lube skid landscape. Three-tier pricing stratifies across hazardous-location certified, severe-service, and standard configurations, with EPA Tier 4 Final compliance requirements and stainless steel grade differentiation as primary price levers. Cost compression in standard skids is intensifying because rental fleet operators are consolidating procurement volumes. Construction companies exhibit highest price sensitivity due to project-based capital cycles, while Permian Basin oilfield service operators show lowest sensitivity given contamination-penalty exposure.
Supply Chain Analysis
The United States and Australia anchor tank fabrication capacity for severe-service and hazardous-location configurations, with Germany supplying REACH-compliant synthetic lubricant handling systems for EU-bound channels. Raw material flows draw from domestic carbon steel mills, South Korean stainless steel suppliers, and Chinese pump component manufacturers. Single-source vulnerability concentrates in explosion-proof electrical enclosures sourced through limited certified vendors. Distribution runs through national distributor networks serving fleet maintenance depots, direct OEM channel partnerships, and emerging rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and regional regulatory clusters creates niche opportunities as consolidated mining contractors and oilfield operators demand outcome-based fluid management contracts rather than capital purchases.
For Market Incumbents: Compound certification depth in Class I Division 1 configurations to defend against emerging specialists from the electrical enclosure supply base. Secure captive supply of stainless steel tank fabrication capacity in the Permian Basin to compress lead times for hazardous-location orders. Anchor distributor exclusivity clauses in Western Australian mining procurement offices before rental fleet operators develop direct relationships. For New Entrants and Emerging Players: Remote site telemetry integration represents a service-layer gap where incumbents under-serve predictive maintenance demand from Pilbara iron ore and Permian Basin operators. Target trailer-mounted rental fleet deployments in Brazil's construction sector, where ANVISA-aligned safety standards are newly enforced and local fabrication capacity remains thin. Pursue equipment-as-a-service go-to-market models with full-fluid-responsibility contract structures to bypass incumbent capital-sales relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents where lube skid fabrication operates as a non-core division with underexploited hazardous-location capabilities. Long-term viability hinges on positioning for synthetic lubricant compatibility requirements spreading from EU Green Deal alignment to Australian and North American mining operations. Watch for inflection when Western Australian iron ore majors convert pilot outcome-based contracts to fleet-wide mandates, signaling specification lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Hazardous-Location Certification Investment | Class I Division 1 capabilities unlock Permian Basin and Bakken procurement specifications with limited qualified suppliers. |
| Backward Integration into Tank Fabrication | In-house stainless steel welding capacity compresses custom build lead times and protects margin from alloy price volatility. |
| Rental Fleet Channel Development | Construction fleet centralization in Brazil and North America favors trailer-mounted skid deployment over capital purchase. |
| Digital Telemetry Platform Integration | Predictive maintenance architectures differentiate service economics before standards crystallize across mining and oilfield segments. |
| EU Green Deal Alignment Certification | REACH-compliant synthetic lubricant handling systems capture specification lock-in for European mining and quarrying OEM channels. |
Research Methodology
Desk research of customs trade data, EPA enforcement records, and TGA mining safety directives preceded structured interviews with maintenance directors at Pilbara iron ore operations, Permian Basin drilling contractors, OEM procurement teams at truck body manufacturers, and aftermarket service heads at national distributor networks. Bottom-up unit shipment estimates triangulated against top-down capital expenditure analysis across mining, oil and gas, and construction end-use segments.
Variance decomposition across product type, end user, size tier, and installation modality shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price movements within standard, customized, mobile, and fixed configuration categories. Electric pump thermal derating constraints in Australian deployments and stainless steel input cost volatility served as industry-specific forecast sensitivity inputs.
Forecasts assume regulatory continuity in EPA Tier 4 Final enforcement, OSHA lockout/tagout standards, and EU REACH substance restrictions; material policy shifts would require re-modeling across the analysis window. Specific risks include nickel and chromium alloy price spikes, DOT highway transport rule changes affecting mobile unit configurations, and battery energy density limitations constraining electric pump runtime in high-ambient environments. Recalibration cycles align with material shifts in mining contractor consolidation patterns and synthetic lubricant formulation mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Nigeria Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Yarn Lubricant Market
Lubricants
Morocco Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Qatar Automotive Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Israel Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Forestry Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
India Industrial Lubricants Market
Lubricants
Poland Lubricants Market