
 Netherlands Metalworking Fluids Market | 2026-2036
Netherlands Metalworking Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Metalworking Fluids Market Insights
Synthetic-grade fluid specifications is redrawing competitive boundaries in the Netherlands. FUCHS leverages its Mannheim-based R&D pipeline to anchor premium positioning among Dutch machine shops. Exxon Mobil Corporation competes through backward integration into Group II/III base oil supply. CIMCOOL Europe specializes in aqueous coolant systems for the regional automotive tier-one base.
Metalworking fluids are formulated lubricants and coolants engineered with mineral, synthetic, or bio-based base stocks combined with extreme-pressure additives, emulsifiers, and corrosion inhibitors, designed to reduce friction, dissipate heat, and extend tool life during machining operations. Cutting Fluids leads product type demand as milling and turning operations in Dutch fabrication shops require flood application for chip evacuation and surface finish control. Neat oil formulations within the Form dimension command margin premiums due to extended sump life and reduced microbial contamination in high-precision aerospace work.
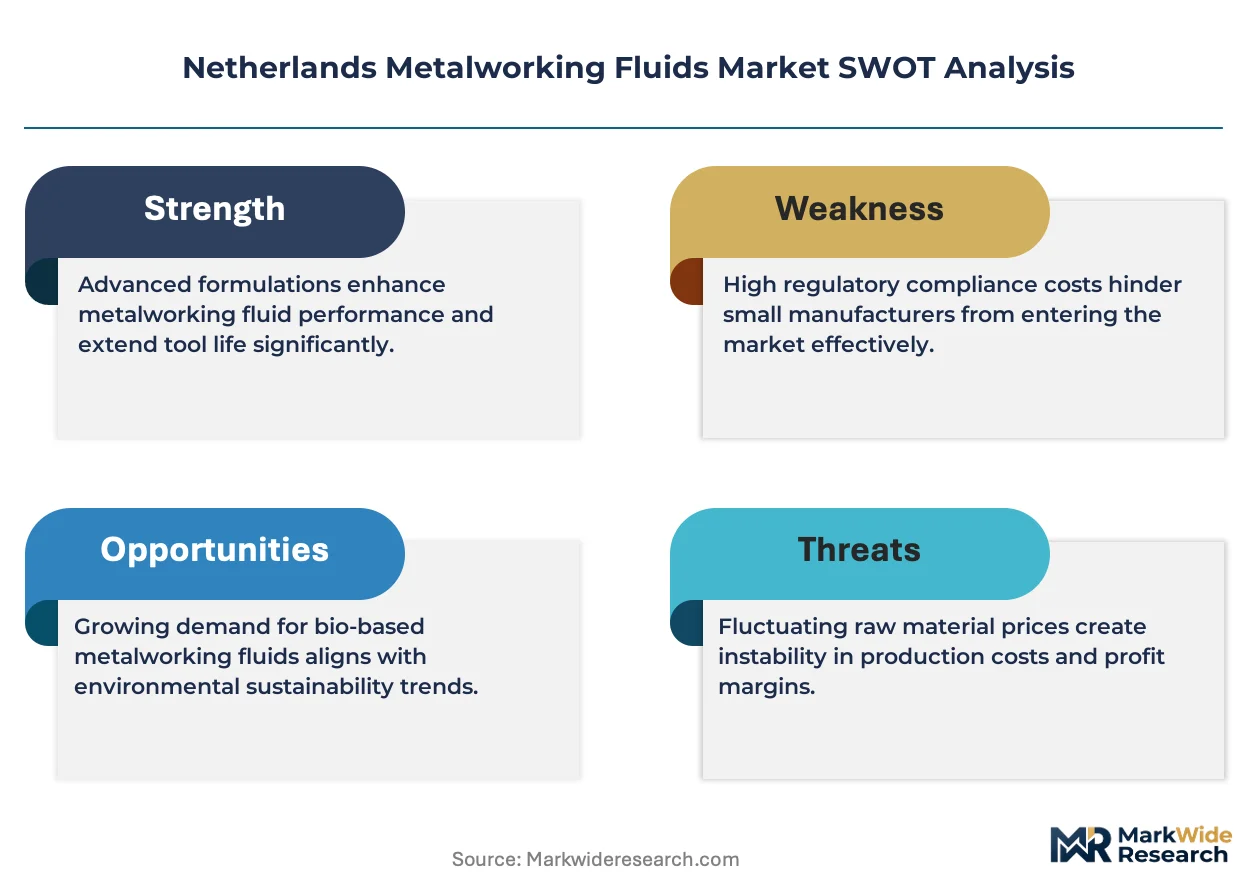
REACH registration requirements and the EU F-Gas Regulation constrain formulation chemistry choices for suppliers operating in the Netherlands. The Dutch central environmental agency enforces strict wastewater discharge limits on metalworking effluent, elevating demand for semi-synthetic and bio-stable emulsion products. Stakeholders must monitor evolving EU MDR traceability standards as medical device machining emerges as a specification-sensitive outlet.
Market Dynamics
REACH registration deadlines and the EU Green Deal are compressing formulation freedom for Dutch metalworking fluid suppliers, forcing rapid chemistry pivots toward bio-based esters and semi-synthetic alternatives before 2030 compliance windows close.
Growth Catalysts
- Automotive OEM expansion:Eindhoven-Tilburg corridor manufacturers are scaling precision machining capacity for electric drivetrain components, pulling demand for advanced neat oils with extended sump life.
- EU Green Deal chemistry mandates:Bio-based ester formulations gain preference credits under circular economy procurement rules, rewarding Dutch formulators with verified carbon footprint reductions.
- North Brabant manufacturing concentration:Fabrication clusters around Eindhoven generate localized demand density, reducing logistics costs for coolant system service providers.
Market Restraints
- Base oil supply concentration:Group II/III base stock production concentrates in Rotterdam-adjacent refineries, creating single-point vulnerability for Dutch blenders during turnaround seasons.
- REACH registration cost barriers:Small and mid-sized formulators face disproportionate compliance burdens for novel additive packages, consolidating innovation capacity among larger players.
- Wastewater discharge limits:Dutch central environmental agency enforcement of strict metalworking effluent standards elevates treatment costs, squeezing margins on conventional emulsion products.
Strategic Opportunities
- Medical device machining vertical:EU MDR traceability requirements create specification-sensitive demand for certified fluid systems in orthopedic and surgical instrument manufacturing.
- Zeeland and Limburg underpenetration:Southern provinces beyond North Brabant host smaller metal fabrication shops with legacy soluble oil systems ripe for semi-synthetic upgrades.
- Aqueous coolant service models:Centralized fluid management contracts displace drum-based purchasing in mid-sized Dutch machine shops, locking in multi-year revenue streams.
Industry Challenges
- Formulation chemist scarcity:Netherlands-based lubricant laboratories compete for talent with German and Belgian R&D centers, elongating product development cycles.
- Legacy system integration friction:Machine shops running 15-plus-year-old CNC equipment face compatibility testing burdens when adopting bio-stable emulsion technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Metalworking Fluids Market |
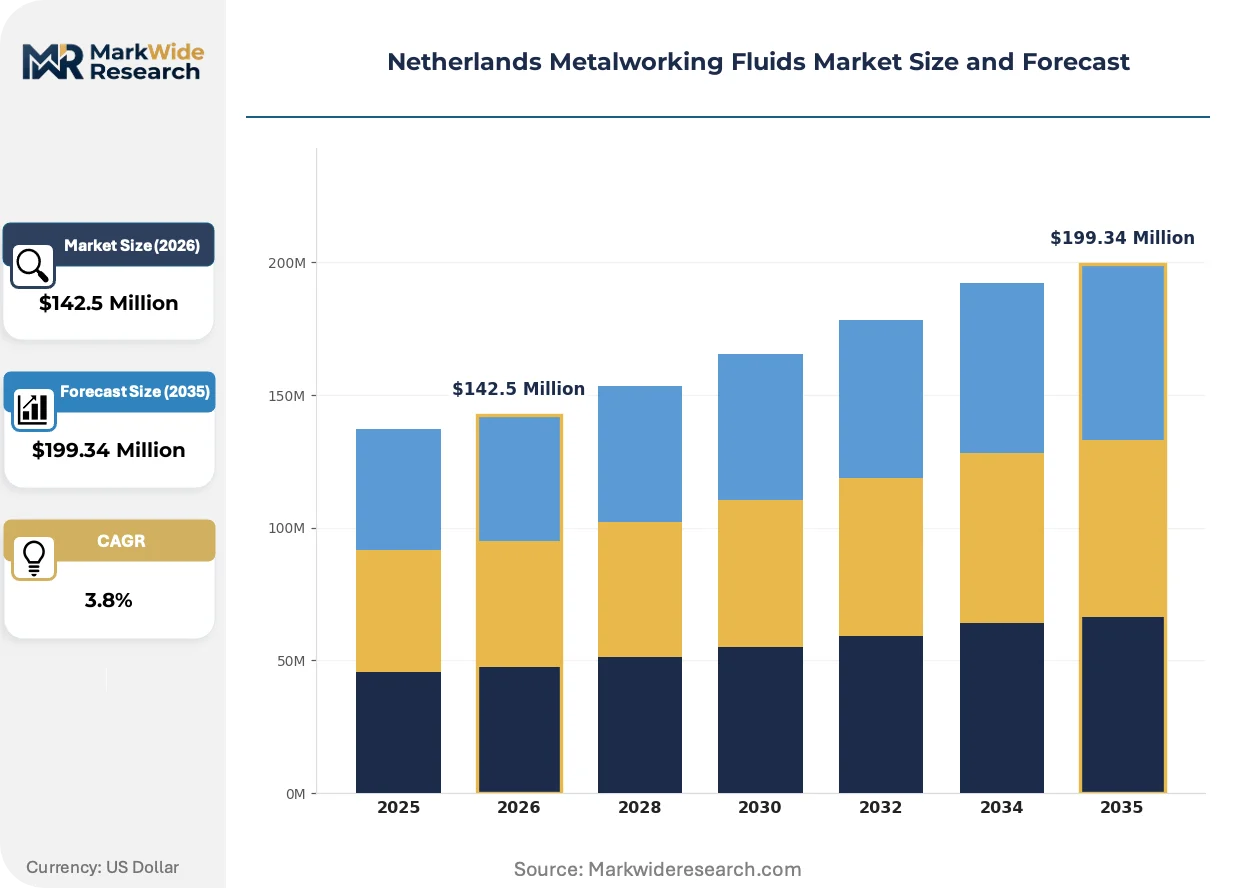
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $199.34 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Fluids, Grinding Fluids, Corrosion Inhibitors, Hydraulic Fluids Application: Milling, Turning, Drilling, Grinding End User: Aerospace, Automotive, Electrical, Fabrication Form: Aqueous, Non-Aqueous, Emulsion, Neat |
| Companies Covered | Exxon Mobil Corporation, FUCHS, Valvoline, Quaker Chemical Corporation, Motul, Perstorp, CIMCOOL Europe, Aimol, Kuwait Petroleum Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Metalworking Fluids Market Trends and Innovations
Formulation chemistry and service delivery models are undergoing parallel transformation as Dutch metalworking operations confront tightening environmental boundaries and labor constraints.
Semi-synthetic micro-emulsion technologies are displacing conventional soluble oils in Dutch fabrication shops. These formulations deliver superior bio-stability and extended sump life without the premium cost structure of full synthetics. Automotive tier-one suppliers in the Eindhoven-Tilburg corridor are adopting them at pace to reduce microbial testing frequency and wastewater treatment loads.
REACH authorization requirements are constraining the use of boron-based extreme-pressure additives in metalworking fluids sold into the Netherlands. Formulators are accelerating substitution with sulfur-phosphorus and bio-based polymer alternatives. Neat oil products for aerospace precision machining face the steepest reformulation timelines due to performance certification requirements.
Fluid management outsourcing is consolidating procurement authority among Dutch machine shop networks. Regional service providers are displacing traditional distributor relationships with telemetry-equipped central systems that monitor concentration and pH remotely. This pattern concentrates most visibly in North Brabant's automotive supplier parks where multi-site operations seek unified compliance reporting.
Netherlands Metalworking Fluids Market Segmentation
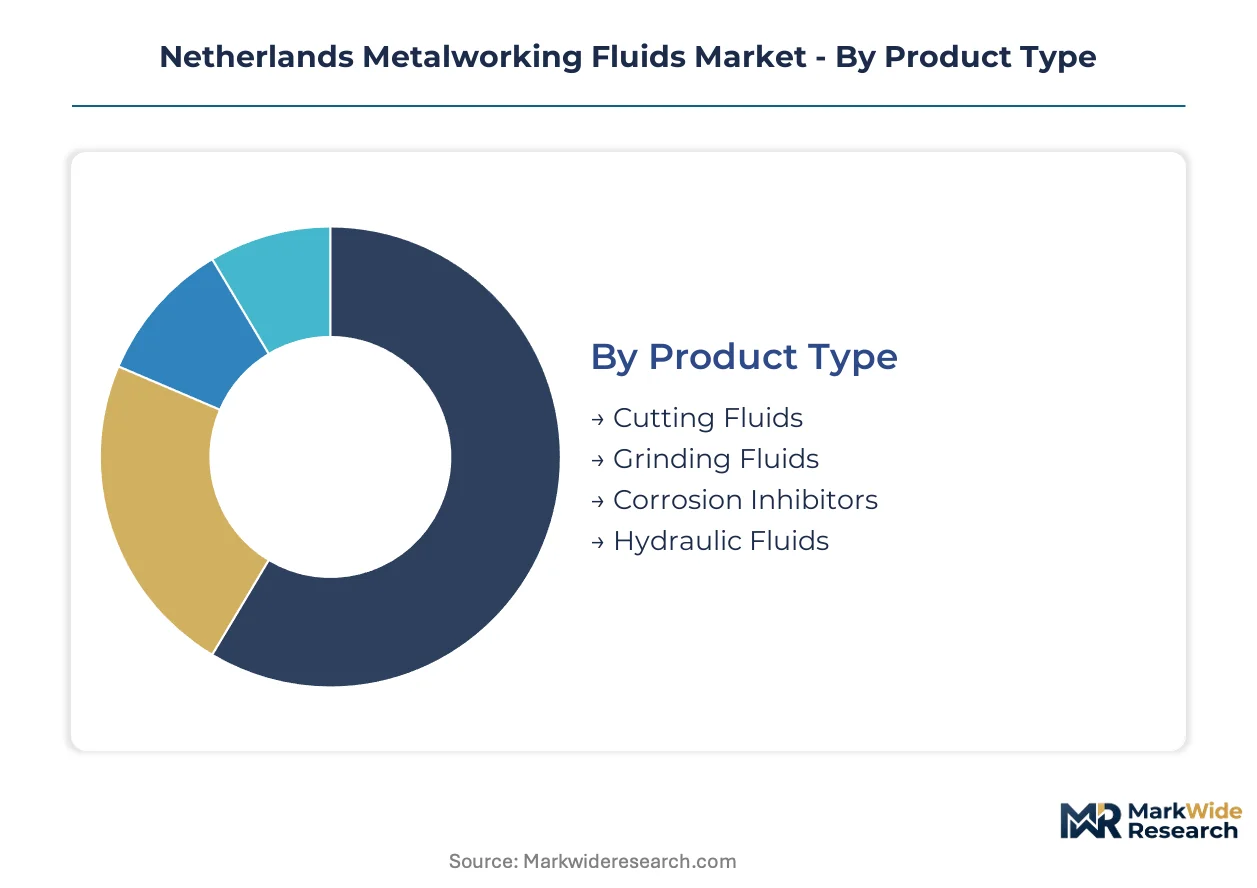
Segmentation in the Netherlands metalworking fluids market reveals how regulatory pressure and application specificity split demand across chemistry types and customer profiles. Understanding these divisions exposes where substitution risk concentrates and where premium positioning remains defensible.
Product Type:
Substitution pressure from dry machining and minimum quantity lubrication technologies weighs heaviest on conventional fluid categories, forcing suppliers to defend relevance through performance differentiation.
- Cutting Fluids:Formulated lubricants combining mineral, synthetic, or bio-based base stocks with extreme-pressure additives for milling and turning operations. Demand concentrates in Eindhoven-Tilburg automotive supplier parks where flood application systems remain standard for chip evacuation and surface finish control.
- Grinding Fluids:Low-viscosity formulations engineered for heat dissipation and wheel cleaning in precision grinding operations. North Brabant fabrication clusters pull specialized synthetic variants for medical device machining where thermal damage tolerance is tightest.
- Corrosion Inhibitors:Additive packages protecting finished metal surfaces during storage and transit, typically co-formulated with cutting fluids.
- Hydraulic Fluids:Metalworking-adjacent lubricants for machine tool hydraulic systems, facing cross-category competition from universal industrial hydraulic products.
Cutting Fluids anchors the volume base while Grinding Fluids gains share at the steepest rate.
Application:
Cost tier stratification separates high-volume standardized operations from specification-sensitive precision work, with chemistry investment scaling directly to tolerance requirements.
- Milling:Flood coolant application dominating roughing and finishing operations across Dutch fabrication shops, with semi-synthetic micro-emulsions displacing conventional soluble oils for bio-stability advantages.
- Turning:Continuous chip formation demanding consistent lubrication film strength; neat oil formulations command margin premiums in high-precision aerospace component work where extended sump life justifies chemistry investment.
- Drilling:Point contact operations with concentrated heat generation, typically served by standard emulsion products with lower additive loading.
- Grinding:Precision finishing with tight thermal constraints, pulling synthetic and semi-synthetic formulations in orthopedic instrument manufacturing around Eindhoven.
Milling captures the broadest customer base while Grinding commands the highest per-liter pricing.
End User:
Customer type determines specification intensity, with certified supply chains demanding full formulation traceability against commodity-oriented procurement.
- Automotive:Tier-one suppliers in the Eindhoven-Tilburg corridor scaling electric drivetrain machining capacity, pulling advanced neat oils with REACH-compliant additive packages for extended sump life and reduced microbial testing burden.
- Aerospace:Precision machining operations with tightest performance certification requirements, facing steepest reformulation timelines as boron-based extreme-pressure additives lose REACH authorization.
- Electrical:Component fabrication with moderate precision demands, representing stable emulsion consumption.
- Fabrication:General metalworking shops across North Brabant and beyond, with legacy soluble oil systems ripe for semi-synthetic upgrade.
Automotive anchors procurement volume while Aerospace drives specification evolution fastest.
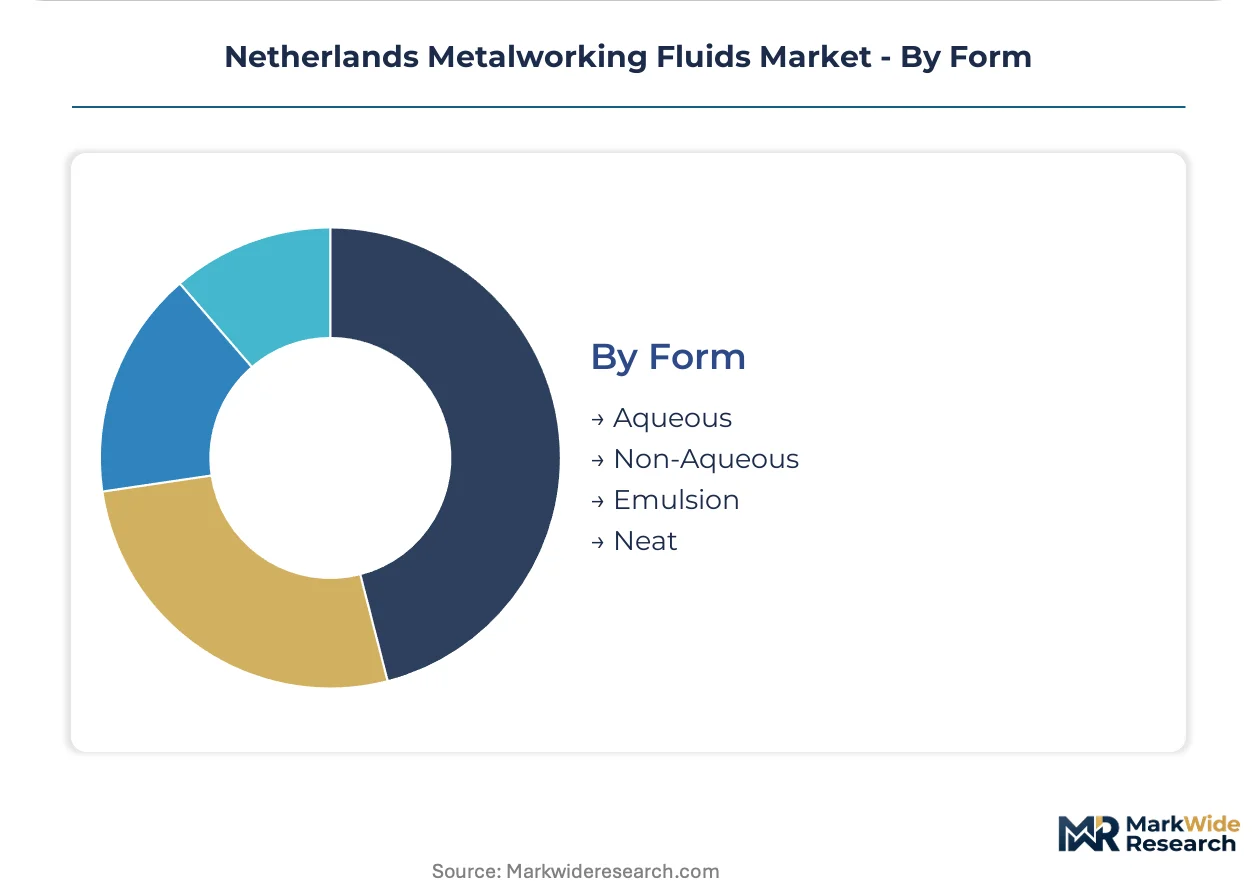
Form:
Supply concentration around Rotterdam-adjacent base oil refining shapes form availability, with aqueous and emulsion products enjoying logistics advantages over neat oil alternatives.
- Neat:Undiluted oil formulations delivering maximum lubricity and extended sump life without microbial degradation risk; premium positioning in aerospace and medical device machining where contamination tolerance is minimal.
- Emulsion:Oil-in-water dispersions balancing cooling and lubrication, dominating general fabrication with lower per-liter cost and easier wastewater treatment compared to neat oils.
- Aqueous:Water-based synthetic formulations with no mineral oil content, gaining preference under circular economy procurement rules for verified carbon footprint reduction.
- Non-Aqueous:Solvent-based and synthetic ester formulations serving specialized applications with extreme temperature or chemical resistance demands.
Emulsion holds the volume foundation while Aqueous climbs fastest on regulatory preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian metalworking fluid exports supply Dutch fabrication networks through the Antwerp-Rotterdam pipeline, while German formulators push southward into North Brabant's automotive supplier parks. Cross-border chemistry registration under REACH enables this integrated Benelux-Rhine supply architecture.
Germany
Mannheim-based R&D centers develop synthetic-grade specifications for Dutch precision machining. ECHA registration requirements for boron-based additives force coordinated reformulation timelines across the border. Baden-Württemberg automotive suppliers extend their coolant specifications into Eindhoven-Tilburg tier-one operations.
Belgium
Antwerp refining clusters produce Group II/III base stocks for Dutch blending operations. REACH compliance documentation flows through Brussels-based regulatory coordination. Flanders fabrication shops share wastewater treatment protocols with their Zeeland counterparts across the Scheldt estuary.
France
Aerospace machining specifications from Toulouse and Bordeaux influence Dutch neat oil formulation standards. ANSM traceability requirements for medical device manufacturing create cross-border certification demand. Hauts-de-France metalworking clusters source semi-synthetic emulsions through Rotterdam distribution hubs.
United Kingdom
Post-Brexit UKCA marking diverges from CE conformity, complicating fluid exports to Dutch medical device machinists. Midlands automotive suppliers maintain legacy soluble oil systems that pressure Dutch formulators to support dual-specification production. HSE workplace exposure limits differ from Dutch central environmental agency standards.
Netherlands Metalworking Fluids Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and service delivery dimensions. The Netherlands market structures around three tiers: multinational oil majors with backward integration into base oil supply, European specialists with regional R&D footprints, and local service providers with fluid management contracts. Strategic moves concentrate on M&A for additive technology access and geographic expansion into underpenetrated southern provinces.
Within the multinational tier, Exxon Mobil Corporation and FUCHS exemplify divergent approaches to Dutch market presence. CIMCOOL Europe occupies a specialist position focused on aqueous coolant systems. These three anchors demonstrate how scale, regional R&D proximity, and service-model specialization carve distinct competitive territories in a market compressed by REACH deadlines and wastewater discharge enforcement.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| FUCHS |
| Valvoline |
| Quaker Chemical Corporation |
| Motul |
| Perstorp |
| CIMCOOL Europe |
| Aimol |
| Kuwait Petroleum Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH registration requirements gate both supplier qualification and price differentiation in the Netherlands metalworking fluids market, compressing margins for uncertified blenders while rewarding verified bio-based formulations with procurement preference credits under EU Green Deal frameworks.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with neat oil formulations commanding margin premiums due to extended sump life and reduced microbial testing burdens. Price differentiation hinges on REACH compliance certification and volume scale, with automotive tier-one suppliers in North Brabant showing lowest price sensitivity. Cost compression in conventional emulsion tiers is intensifying because wastewater treatment expenses erode margins on legacy soluble oil products.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on the Antwerp-Rotterdam pipeline elevate inbound logistics costs for additive packages sourced from German and Belgian chemical clusters. Supply concentrates in Germany, Belgium, and domestic Rotterdam-adjacent refineries, with Group II/III base stock production drawing from Mannheim and Antwerp facilities. Single-source vulnerability concentrates around boron-based additive substitution timelines. Distribution runs through regional fluid management service contracts displacing traditional drum-based purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands metalworking fluids market rewards formulators who control scarce REACH-compliant chemistry capabilities, as ECHA authorization deadlines eliminate competitors lacking bio-based ester formulation expertise or centralized wastewater treatment infrastructure.
For Market Incumbents: Secure backward integration into Group II/III base oil supply through Rotterdam-adjacent refining partnerships, insulating margin structures from turnaround-season volatility. Expand aqueous coolant service contracts in North Brabant automotive supplier parks to lock in multi-year revenue streams and displace distributor relationships. Prioritize certification investment for EU MDR traceability standards ahead of medical device machining demand acceleration. For New Entrants and Emerging Players: Fluid management outsourcing gaps in Zeeland and Limburg fabrication clusters offer white-space entry points where legacy soluble oil systems remain unconverted. Target semi-synthetic upgrade opportunities in smaller metalworking shops beyond the Eindhoven-Tilburg corridor, where incumbent service density is lowest. Pursue telemetry-equipped central system deployment as the primary go-to-market angle, differentiating through unified compliance reporting capabilities. For Investors and Strategic Acquirers: REACH 2030 compliance windows reshape the acquisition landscape toward formulators with verified bio-based ester pipelines and established ECHA registration portfolios. Long-term viability centers on chemistry innovation capacity rather than commodity blending scale. Monitor ECHA authorization timelines for sulfur-phosphorus additive packages as the critical inflection signal for portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group II/III feedstock from Rotterdam refineries insulates margin volatility during turnaround seasons. |
| Bio-Based Ester Formulation Investment | REACH-compliant chemistry secures procurement preference credits under EU Green Deal circular economy rules. |
| Fluid Management Service Expansion | Telemetry-equipped central systems displace drum purchasing and lock multi-year contracts in North Brabant. |
| EU MDR Certification Pathway | Traceability-compliant fluid systems capture specification-sensitive medical device machining demand around Eindhoven. |
| Geographic Expansion into Limburg | Underpenetrated fabrication clusters offer semi-synthetic upgrade runway beyond saturated Brabant corridors. |
Research Methodology
The analysis maps synthetic-grade, semi-synthetic, and bio-based fluid sub-sectors, each validated through formulation chemists, automotive tier-one procurement leads, and wastewater treatment specialists. Primary interviews with plant engineers, coolant system service providers, and Dutch central environmental agency compliance officers combined with secondary validation from ECHA registration databases, Cefic chemical industry reports, and SEC filings of listed lubricant majors. Bottom-up demand modeling across machining application types triangulated against top-down supply-side capacity assessments.
Consistency checks against ECHA authorization timelines and Rotterdam refinery turnaround schedules validated projection outputs across the analysis window. Segmentation dimensions modeled include product chemistry tier, machining application intensity, end-user certification requirements, and provincial demand concentration. CAGRs derived from sump life extension trends and bio-stable emulsion adoption curves, with automotive electric drivetrain machining capacity expansion serving as the primary volume driver input.
Forecasts assume regulatory continuity in REACH and EU F-Gas regimes; material policy shifts would require re-modeling. Boron-based additive authorization withdrawals or Dutch wastewater discharge limit tightening represent specific revision triggers. Recalibration cycles align with ECHA substance evaluation updates and automotive OEM capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Indonesia Lubricants Market
Lubricants
Construction Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
ASEAN Lubricants Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Contact Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Synthetic Lubricants Market