
 Spain Lubricants Market | 2026-2036
Spain Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Lubricants Market Insights
Market Context
Multi-source procurement among fleet operators and industrial buyers is consolidating around established national distributors with integrated blending capabilities. Repsol leverages its captive refinery network in Tarragona to secure feedstock cost advantages across Iberian supply routes. CEPSA anchors its position through deep channel control of service station networks and direct OEM relationships with domestic vehicle assemblers. BP PLC (Castrol) competes on brand equity in high-performance synthetic segments where technical specification compliance commands premium positioning.
Technical Definition and Segment Structure
Spain lubricants comprise formulated fluid and semi-fluid preparations engineered from base oils combined with additive packages to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosities typically graded under SAE J300 for engine oils and ISO 3448 for industrial applications. Engine oil formulations dominate volume throughput given Spain's substantial passenger vehicle parc and commercial transport density, though margin pools concentrate in synthetic and biobased technologies where additive chemistry complexity sustains higher unit economics. The aftermarket channel leads distribution value capture due to fragmented vehicle age profiles and mandatory periodic maintenance intervals, while OEM fill positions require longer qualification cycles but lock in specification-driven replacement demand.
Regulatory Framework and Outlook
EU REACH chemical registration requirements and the F-Gas Regulation constrain formulation chemistries available to blenders operating in Spain, compelling reformulation investments and supplier qualification audits. The Spanish Ministry for Ecological Transition enforces national climate targets that tighten industrial emissions benchmarks, directly linking lubricant thermal efficiency performance to end-user compliance costs. Stakeholders must monitor evolving EU Ecolabel criteria for lubricants and anticipate how Spain's transposition of CSRD reporting obligations will reshape procurement transparency requirements across fleet and industrial buyer segments.
Market Dynamics
Fleet operators across Spain's commercial transport sector are consolidating procurement around synthetic lubricant specifications, compressing replacement cycles and rewiring distributor relationships toward technical-service bundling.
Growth Catalysts
- EU Green Deal decarbonization targets:Spain's alignment with bloc-wide carbon neutrality mandates accelerates biobased formulation requirements across industrial machinery segments.
- Catalonia's automotive component manufacturing corridor:Concentrated industrial machinery deployment generates sustained demand for high-performance hydraulic and metalworking fluids.
- Synthetic additive chemistry:Extended drain intervals and thermal stability improvements pull fleet operators away from mineral-based alternatives.
Market Restraints
- Base oil feedstock volatility:Repsol's captive Tarragona refinery capacity limits price transmission flexibility for non-integrated blenders.
- REACH chemical registration constraints:ECHA compliance timelines extend new product introduction cycles by 18-24 months.
- Group III+ base oil supply concentration:Iberian Peninsula reliance on Mediterranean import routes creates inventory risk during logistics disruptions.
Strategic Opportunities
- Andalusia's underpenetrated agricultural machinery segment:Mechanization growth in olive harvesting equipment creates whitespace for biodegradable hydraulic fluids.
- EU Ecolabel lubricant certification:Early positioning against tightening public procurement sustainability criteria locks in municipal fleet contracts.
- Direct-to-fleet digital platforms:Bypassing traditional service station networks captures margin from price-transparent large operators.
Industry Challenges
- Additive chemist talent scarcity:Specialized formulation expertise for biobased-synthetic hybrids concentrates in Tarragona and Madrid metropolitan clusters.
- OEM qualification cycle compression:Spanish vehicle assemblers demand simultaneous validation across multiple specification tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Lubricants Market |
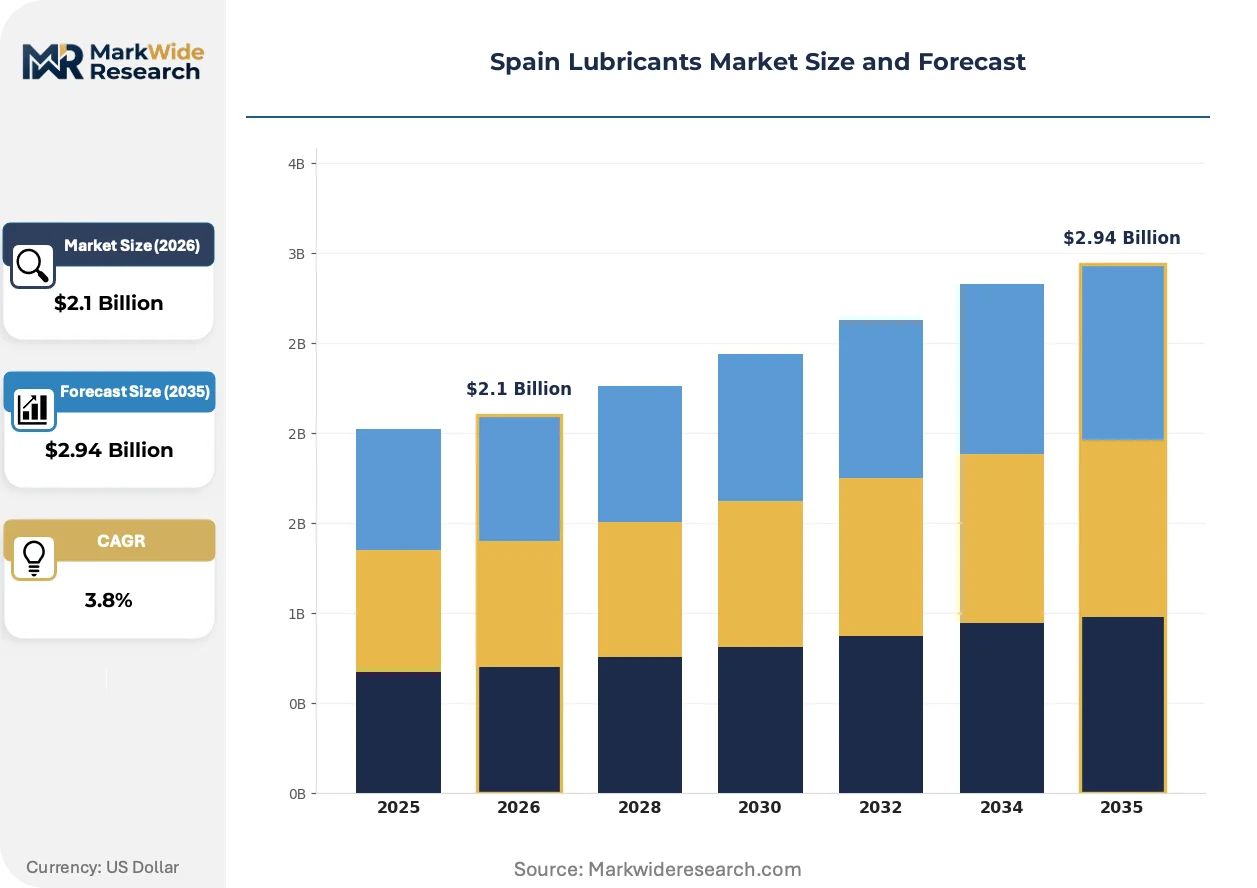
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Greases Application: Automotive, Industrial Machinery, Marine, Aerospace Technology: Synthetic, Mineral, Biobased, Semi-Synthetic End User: OEMs, Aftermarket, Service Stations, Fleet Operators |
| Companies Covered | Repsol, CEPSA, BP PLC (Castrol), TotalEnergies, Royal Dutch Shell Plc, ExxonMobil Corporation, Chevron Corporation, FUCHS, Eni SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Lubricants Market Trends and Innovations
Formulation chemistry and distribution architecture are undergoing parallel transformation, with regulatory pressure and fleet procurement centralization acting as twin accelerants.
Polyalphaolefin-based synthetic engine oils are consolidating position across Spain's heavy-duty fleet segment. Transport operators with vehicles exceeding 500,000 annual kilometers specify these formulations for extended drain intervals. The technology is consolidating aftermarket volume toward distributors with in-house oil analysis and condition monitoring capabilities.
Spain's transposition of CSRD reporting obligations forces lubricant procurement transparency across corporate fleet buyers. Mandatory supply chain emissions disclosure links thermal efficiency performance to Scope 3 accounting compliance. Industrial buyers in Basque Country manufacturing clusters are restructuring supplier qualification audits around verified carbon intensity data.
Service bundling is displacing standalone product sales in the commercial vehicle channel. Fleet maintenance contracts now integrate fluid management with predictive analytics. Madrid-based logistics operators lead this shift, consolidating vendor relationships around single-source technical service agreements rather than multi-brand product sourcing.
Spain Lubricants Market Segmentation
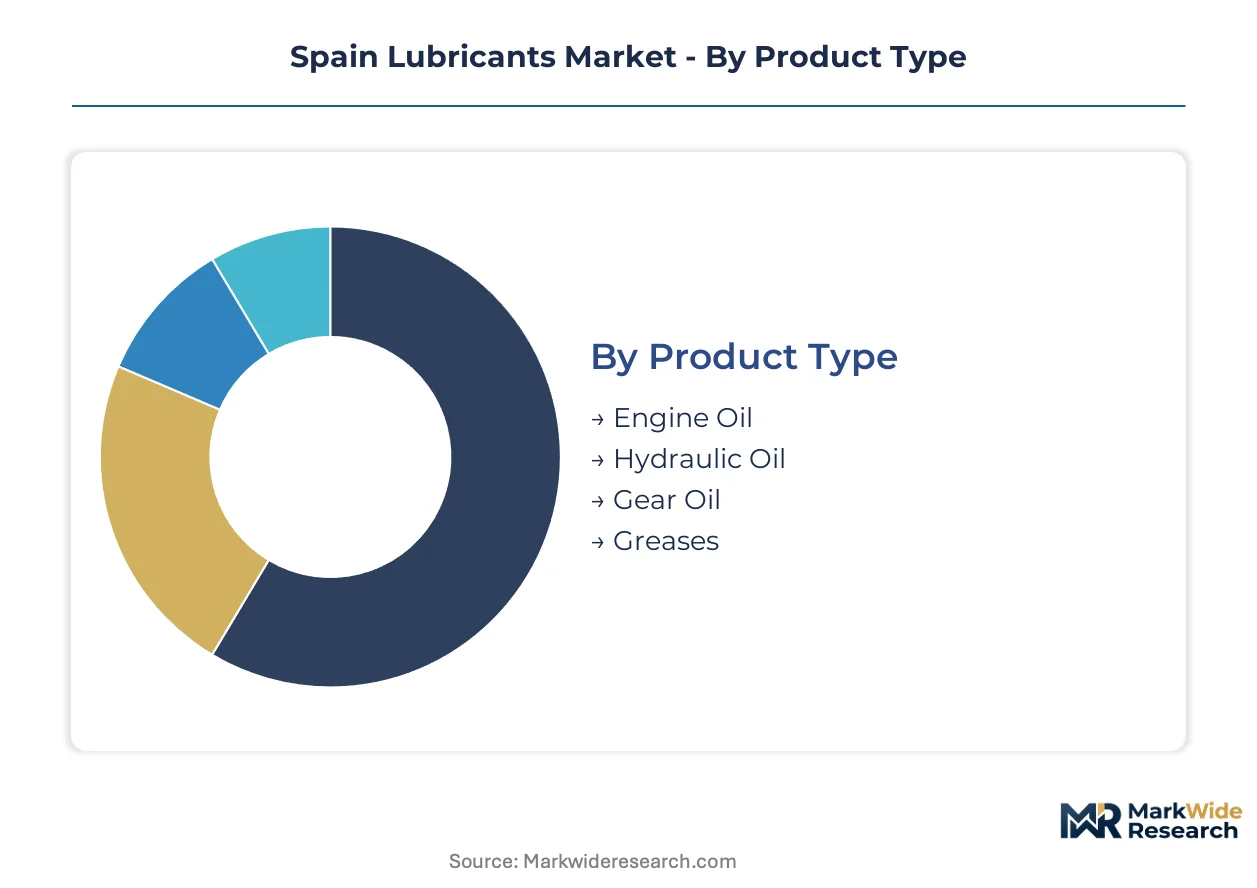
Segmentation in Spain's lubricants market reveals how formulation chemistry, application intensity, and procurement channel economics create distinct competitive battlegrounds. Understanding these divisions exposes where margin pools concentrate and which technology transitions will reshape supplier positioning.
Product Type:
Replacement cycle dynamics vary sharply across lubricant categories, with drain interval extension and equipment criticality driving divergent purchasing behavior.
- Engine Oil:Formulations span SAE viscosity grades from 0W-20 to 15W-40, with additive packages tuned for gasoline direct injection, diesel particulate filter compatibility, and hybrid powertrain thermal management. Fleet operators in Madrid's logistics corridors specify synthetic grades for vehicles exceeding 400,000 kilometers annually, compressing maintenance downtime.
- Hydraulic Oil:Anti-wear additives and viscosity index improvers enable precision control in high-pressure industrial systems. Catalonia's automotive component manufacturing plants generate concentrated demand for zinc-free formulations that protect servo-valve coatings in stamping presses and robotic assembly lines.
- Gear Oil:Extreme pressure additives protect hypoid gear sets in commercial vehicle differentials and industrial gearboxes. Mining equipment operators in Asturias specify SAE 80W-140 synthetic blends for load-bearing axle applications.
- Greases:Thickener systems (lithium complex, polyurea, calcium sulfonate) suspend base oil for slow-speed, high-load bearing applications. Wind turbine maintenance in Galicia's onshore wind farms drives demand for long-life greases with corrosion inhibitors.
Volume placements concentrate in Engine Oil; the faster expansion belongs to synthetic Hydraulic Oil grades serving automated manufacturing.
Application:
Cost tier differentiation separates specification-intensive industrial applications from price-sensitive consumer automotive segments.
- Automotive:Passenger vehicle parc maintenance and commercial fleet operations generate baseline throughput. Spain's aging vehicle fleet, with average ages exceeding twelve years in rural provinces, sustains steady aftermarket demand across mineral and semi-synthetic price tiers.
- Industrial Machinery:Metalworking fluids, compressor oils, and turbine lubricants command premium positioning through technical service bundling. Basque Country machine tool builders qualify suppliers through extended field trials before specifying hydraulic fluids for export equipment.
- Marine:Stern tube oils, cylinder lubricants, and deck machinery fluids must satisfy IMO environmental compliance for Mediterranean port calls. Barcelona and Valencia container terminals drive demand for biodegradable stern tube formulations.
- Aerospace:Synthetic ester-based turbine oils and instrument lubricants require AS9100 quality certification and batch traceability. Madrid-Barajas maintenance facilities source through approved aviation distributors with cold chain documentation.
Revenue concentration sits with Industrial Machinery; Marine applications are climbing the fastest as port emissions regulations tighten.
Technology:
Supply concentration around Group III+ base oils and specialty additive packages determines which blenders can execute each technology tier.
- Synthetic:Polyalphaolefin and ester base stocks enable extended drain intervals and thermal stability for high-performance engines. Repsol's Tarragona refinery supplies captive PAO feedstock for Iberian synthetic formulation.
- Mineral:Solvent-refined Group I and hydrocracked Group II base oils serve price-sensitive applications with shorter service intervals. Independent blenders without refinery integration rely on Mediterranean import arbitrage for mineral base stock supply.
- Biobased:Vegetable oil esters and synthetic esters from renewable feedstocks meet EU Ecolabel criteria for public procurement. Andalusian olive harvesting equipment operators trial biodegradable hydraulic fluids for soil contamination protection.
- Semi-Synthetic:Blends combining mineral and synthetic base stocks balance cost and performance for mid-tier fleet specifications. Regional distributors in Castile-La Mancha package semi-synthetic engine oils for agricultural machinery service intervals.
Volume placements concentrate in Mineral formulations; Biobased technology is gaining share fastest under EU Green Deal procurement mandates.
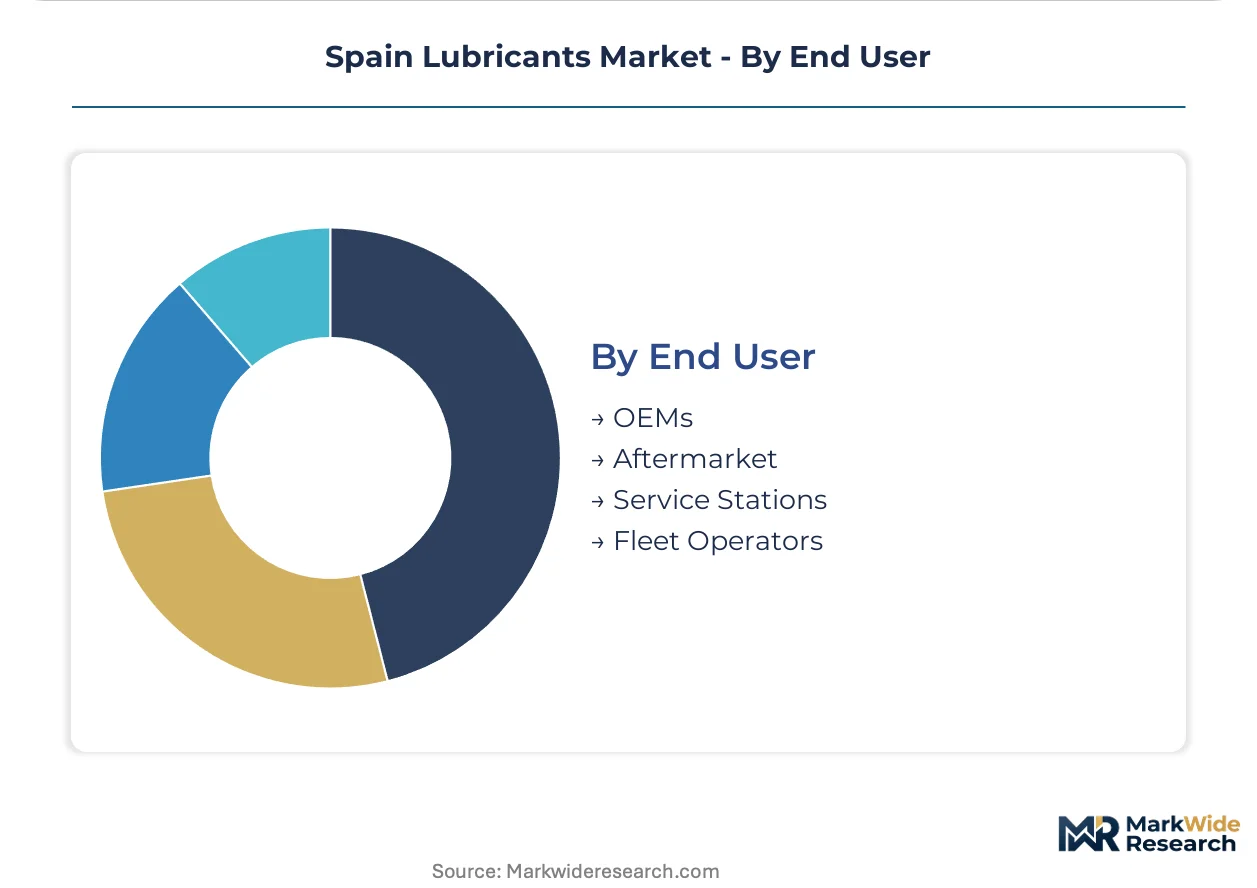
End User:
Customer type determines whether procurement emphasizes technical specification compliance, price transparency, or integrated service bundling.
- OEMs:Vehicle and equipment manufacturers specify factory-fill lubricants through multi-year supply agreements with qualification cycles spanning 18-24 months. Spanish car assemblers in Martorell and Pamplona lock in synthetic engine oil supply through captive blending arrangements.
- Aftermarket:Fragmented independent workshops and retail auto parts channels drive volume through brand recognition and technical hotline support. Madrid metropolitan area distributors compete on same-day delivery coverage for garage customers.
- Service Stations:Integrated oil company networks combine fuel retail with lubricant package sales and quick-lube bay services. CEPSA's Iberian service station footprint anchors consumer-facing lubricant distribution.
- Fleet Operators:Large transport and logistics companies centralize procurement through direct supplier relationships with oil analysis and predictive maintenance bundling. Barcelona-based container hauliers specify single-source technical service agreements replacing multi-brand sourcing.
Volume placements concentrate in Aftermarket channels; Fleet Operators are expanding procurement fastest through digital platform centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's lubricant demand concentrates in industrial corridors where automotive manufacturing and logistics infrastructure create sustained consumption baselines. The country's regional economies exhibit divergent technology adoption patterns shaped by local industry composition and EU funding access.
Madrid
Central Spain's logistics operators specify synthetic engine oils for high-mileage commercial fleets serving Iberian distribution networks. The Ministry for Ecological Transition enforces national emissions benchmarks that link thermal efficiency performance to compliance costs. Madrid-based container hauliers consolidate procurement through direct-to-fleet digital platforms that bypass traditional distributor networks.
Catalonia
Automotive component manufacturing in Barcelona's industrial belt generates concentrated demand for zinc-free hydraulic fluids protecting precision servo-valve systems. EU REACH chemical registration requirements constrain formulation chemistries available to blenders operating in the region. The Martorell automotive cluster locks in synthetic lubricant supply through captive blending arrangements with integrated refiners.
Basque Country
Machine tool builders in Bilbao and surrounding manufacturing hubs qualify suppliers through extended field trials before specifying hydraulic fluids for export equipment. Spain's transposition of CSRD reporting obligations forces procurement transparency across corporate industrial buyers. Basque manufacturers restructure supplier qualification audits around verified carbon intensity data for Scope 3 compliance.
Andalusia
Mechanization growth in olive harvesting equipment creates whitespace demand for biodegradable hydraulic fluids protecting soil from contamination. EU Ecolabel criteria for lubricants tighten public procurement sustainability requirements across municipal fleets. Seville-based agricultural equipment distributors trial biobased formulations for environmentally sensitive harvesting operations.
Valencia
Mediterranean port operations at Spain's third-largest container terminal drive demand for biodegradable stern tube oils satisfying IMO environmental compliance. The F-Gas Regulation constrains formulation options for marine applications requiring thermal stability. Valencia's shipping services cluster consolidates around distributors with integrated fluid analysis and condition monitoring capabilities.
Spain Lubricants Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated refiners leverage captive feedstock positions to secure Iberian supply routes. The market structure consolidates around three tiers: national champions with refinery integration, multinational brand licensors, and independent blenders serving regional niches. Strategic archetypes include upstream-integrated majors, specification-focused synthetics specialists, and service-bundled distributors. M&A activity and backward integration into base oil production represent the dominant competitive vectors reshaping supplier positioning.
Among Spain-based integrated operators, Repsol and CEPSA exemplify the national champion archetype through refinery-linked supply control. BP PLC (Castrol) occupies a position within the multinational brand tier where technical specification compliance commands premium positioning in high-performance synthetic segments.
| Leading Market Players |
|---|
| Repsol |
| CEPSA |
| BP PLC (Castrol) |
| TotalEnergies |
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| Chevron Corporation |
| FUCHS |
| Eni SpA |
| Others |
Pricing and Supply Chain Analysis
Specialized additive chemist concentrations in Tarragona and Madrid metropolitan clusters feed labor-cost differentials that widen pricing-tier spreads between premium synthetic formulations and economy mineral grades across Spain's lubricant market.
Pricing Analysis
Warranty-backed technical service bundling commands premium positioning against unbundled product-only sales in Spain's commercial fleet channel. Three-tier pricing structure across premium, standard, and economy levels separates synthetic PAO-based engine oils with predictive maintenance contracts from semi-synthetic mid-tier fleet specifications and mineral-based economy grades for aging passenger vehicles. Price differentiation hinges on additive chemistry complexity and EU Ecolabel certification status. Cost compression in mineral base oil tiers is intensifying because Repsol's captive Tarragona refinery capacity limits price transmission flexibility for non-integrated blenders. Fleet operators with centralized procurement platforms exhibit lowest price sensitivity; rural independent workshops show highest.
Supply Chain Analysis
Direct-to-fleet digital platforms handle hyperscale buyer demand while traditional service station networks retain consumer automotive volume. Base oil feedstock draws from Spain's domestic refinery capacity at Tarragona, Mediterranean import routes through Valencia and Barcelona, and Northwest European Group III+ supply via Rotterdam. Key inputs span polyalphaolefin base stocks, zinc-free anti-wear additive packages, and vegetable oil esters for biobased formulations. Single-source vulnerability concentrates around Iberian Peninsula reliance on Mediterranean import routes for specialty Group III+ base oils, creating inventory risk during logistics disruptions. Distribution runs through national distributors with integrated blending capabilities, direct OEM supply agreements, and oil company service station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's lubricants market represents a consolidation play where REACH compliance timelines and captive refinery advantages are forcing independent blenders without upstream integration toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from biobased formulation mandates by securing backward integration into renewable feedstock supply chains and accelerating Tarragona-area additive chemistry talent recruitment. Defensive positioning requires locking in Martorell and Pamplona automotive cluster supply through extended qualification cycles that replicate specification-driven replacement demand. Channel control through direct-to-fleet digital platforms anchors volume against distributor disintermediation threats. For New Entrants and Emerging Players: Launch via biodegradable hydraulic fluid specialization targeting Andalusia's mechanizing olive harvesting equipment segment, where soil contamination protection requirements outpace incumbent biobased portfolio development. Whitespace concentrates in EU Ecolabel-certified municipal fleet contracts across Seville, Granada, and Córdoba procurement offices. Technical service bundling with predictive analytics integration offers the most penetrable go-to-market angle against legacy distributor relationships. For Investors and Strategic Acquirers: The window for entry favors mid-cap independent blenders with established Andalusian agricultural distribution and pending biobased formulation certifications. Long-term viability centers on acquisition targets possessing regional channel control without the capital burden of refinery integration. Watch for inflection when CSRD reporting obligations force Basque Country and Catalonia industrial buyers to restructure supplier audits around verified carbon intensity data, accelerating preference for transparent supply chain operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive PAO feedstock supply from Tarragona refinery capacity secures Iberian synthetic formulation cost advantages against Mediterranean import-dependent competitors. |
| EU Ecolabel Certification Program | Early positioning against tightening Spanish public procurement sustainability criteria locks in municipal fleet contracts across Andalusian and Valencian regional governments. |
| Direct-to-Fleet Digital Platform Launch | Bypassing CEPSA's service station network captures margin from price-transparent Madrid and Barcelona logistics operators consolidating vendor relationships. |
| Biobased Formulation R&D Investment | Vegetable oil ester expertise addresses EU Green Deal procurement mandates while differentiating from mineral-dependent independent blenders. |
| Technical Service Bundling Expansion | Integrated fluid analysis and condition monitoring capabilities consolidate aftermarket volume toward distributors with in-house predictive maintenance infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with lubricant plant managers, fleet procurement directors at Madrid and Barcelona logistics operators, automotive OEM technical specification leads, and aftermarket distributor channel partners. Secondary validation drew from ECHA REACH registration databases, Spanish Ministry for Ecological Transition emissions filings, EU Ecolabel certification registries, and Iberian customs trade statistics. Bottom-up volume modeling across product type, application, technology, and end-user segments triangulated against top-down macroeconomic drivers.
Data-stream reconciliation aligned base oil production capacities, additive package import volumes, and finished lubricant distribution channel throughput across the projection horizon. Segmentation dimensions spanned formulation chemistry tiers, industrial versus automotive application intensity, synthetic-mineral-biobased technology gradients, and procurement channel archetypes. CAGRs derived from regression analysis against vehicle parc aging curves, industrial machinery deployment rates in Catalonia's automotive corridor, and EU decarbonization policy implementation trajectories. Forecast inputs incorporated fleet operator synthetic adoption rates and REACH compliance-driven product reformulation cycles.
Base oil price volatility, regulatory timeline delays, and logistics disruption frequency are the dominant revision risks warranting scenario sensitivity analysis. Forecasts reflect documented assumptions regarding EU Ecolabel criteria evolution and CSRD reporting obligation enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Global Engineered Fluids Market
Lubricants
China Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Mining Lubricants Market
Lubricants
Chile Lubricants Market