
 Lubrication Equipment Market | 2026-2036
Lubrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Lubrication Equipment Market Analysis
Synthetic lubricant formulations is rebalancing capital allocation across the equipment supply chain as mineral-oil-compatible hardware faces obsolescence risk. Graco Inc. leverages its North American manufacturing scale to dominate high-pressure pump assemblies. SKF Group anchors European demand through integrated bearing-lubrication bundles. Bijur Delimon International specializes in corrosion-resistant marine applications across Asian port infrastructure.
Lubrication equipment encompasses pumps, fittings, and distribution networks engineered to deliver controlled volumes of oil or grease to friction points, typically operating at pressures from 500 to 10,000 psi depending on application severity. Its primary commercial purpose is to extend machinery life and reduce energy loss in rotating and sliding assemblies. Automatic lubricators command the largest product-type revenue pool due to labor-cost savings in continuous-process industries. Electro-mechanical systems represent the fastest-expanding technology segment as Industry 4.0 architectures demand sensor-integrated, condition-monitored delivery. The transportation application category concentrates margin in rail and heavy-truck fleet contracts where downtime penalties exceed equipment costs.
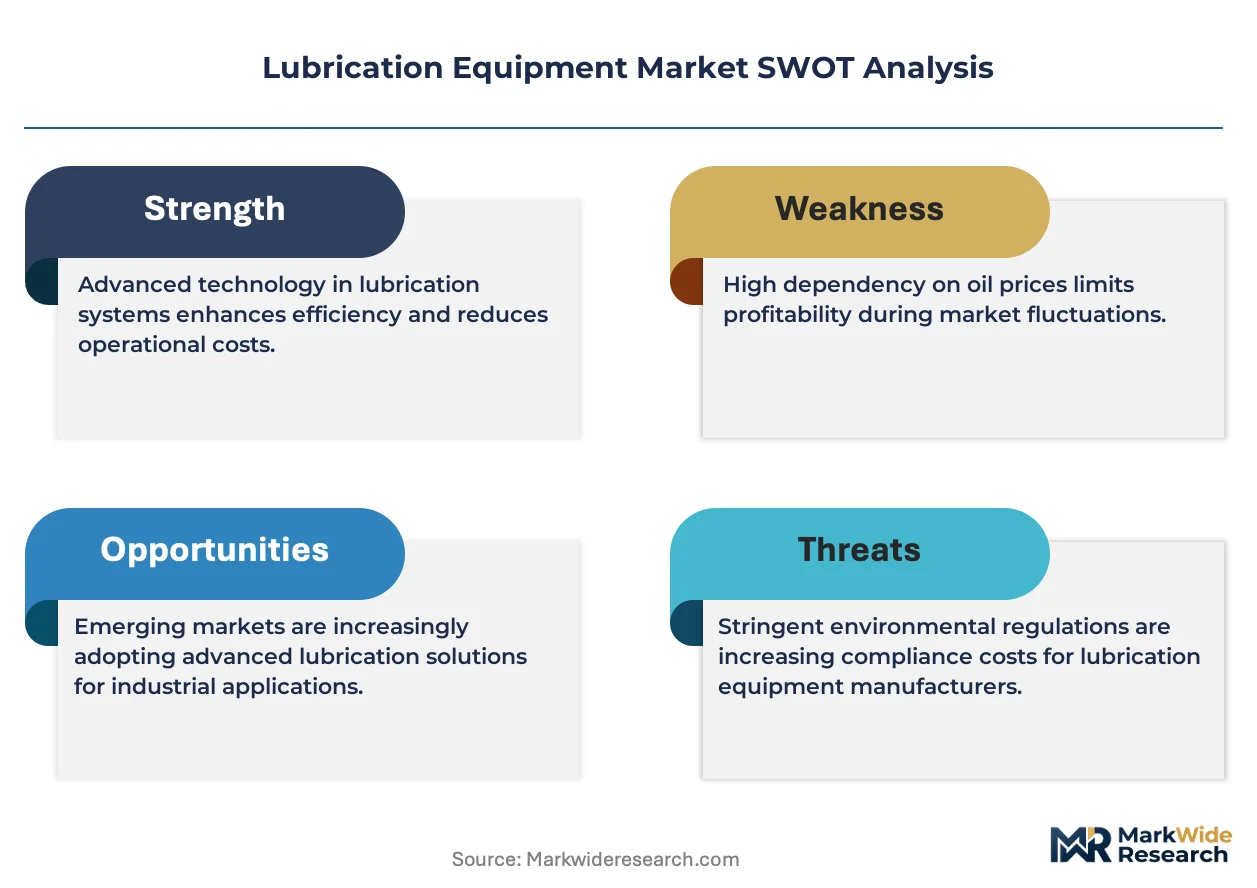
The EPA enforces Clean Air Act standards that compel sealed lubrication systems to prevent volatile organic compound emissions in metalworking facilities. OSHA mandates lockout-tagout compatibility and pressure-relief specifications that shape portable grease pump design. ISO 4406 cleanliness codes and EU REACH chemical restrictions further constrain material selection and filter performance requirements. Stakeholders must weigh regulatory compliance costs against predictive maintenance value capture when configuring product portfolios for multi-jurisdiction deployment.
Market Dynamics
The transition from mineral-oil to synthetic lubricant formulations is forcing equipment manufacturers to redesign pump seals, hose materials, and filtration media, creating a hardware refresh cycle that favors integrated system suppliers over component vendors.
Growth Catalysts
- EPA Clean Air Act enforcement:Metalworking facilities across the United States must deploy sealed lubrication systems to capture volatile organic compound emissions, accelerating replacement of open-grease dispensing equipment.
- Rail fleet electrification:European railway operators are expanding centralized lubrication contracts for pantograph and axle systems as electric locomotive deployment intensifies friction-point maintenance requirements.
- Precision manufacturing clusters:Stuttgart and Munich industrial zones sustain premium procurement of computer-controlled lubrication systems for CNC machine tool uptime guarantees.
Market Restraints
- Base oil price volatility:Synthetic ester and polyalphaolefin feedstock costs fluctuate with petrochemical cracking margins, compressing equipment margins when lubricant producers delay capital purchases.
- Filter media supply concentration:High-efficiency fiberglass and cellulose filtration substrates depend on a limited set of German and Japanese specialty paper manufacturers, creating single-source vulnerability.
- Mineral-oil hardware stranded assets:Existing installed bases of nitrile-seal pumps face accelerated functional obsolescence as ISO 4406 cleanliness codes tighten particle-count tolerances.
Strategic Opportunities
- Indian port infrastructure modernization:Jawaharlal Nehru Port Trust and Mundra Port expansion projects require corrosion-resistant marine lubrication systems for container crane slewing bearings.
- EU Green Deal industrial retrofit mandates:Carbon-intensive steel and cement plants must upgrade to closed-loop lubrication recovery systems to qualify for transition financing.
- Sensor-integrated electro-mechanical convergance:Condition-monitoring algorithms fused with precision metering pumps enable predictive lubrication intervals in unmanned continuous-process facilities.
Industry Challenges
- Mechatronics skill scarcity:Field service technicians must simultaneously diagnose hydraulic, pneumatic, and IoT communication faults, stretching vocational training pipelines.
- Multi-jurisdiction certification timelines:Equipment vendors face staggered OSHA lockout-tagout, EU CE machinery directive, and China GB standard approval processes that delay product launches.
- Legacy PLC integration friction:Modern Ethernet/IP-enabled lubrication controllers encounter protocol mismatches with decades-old plant automation architectures in brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubrication Equipment Market |
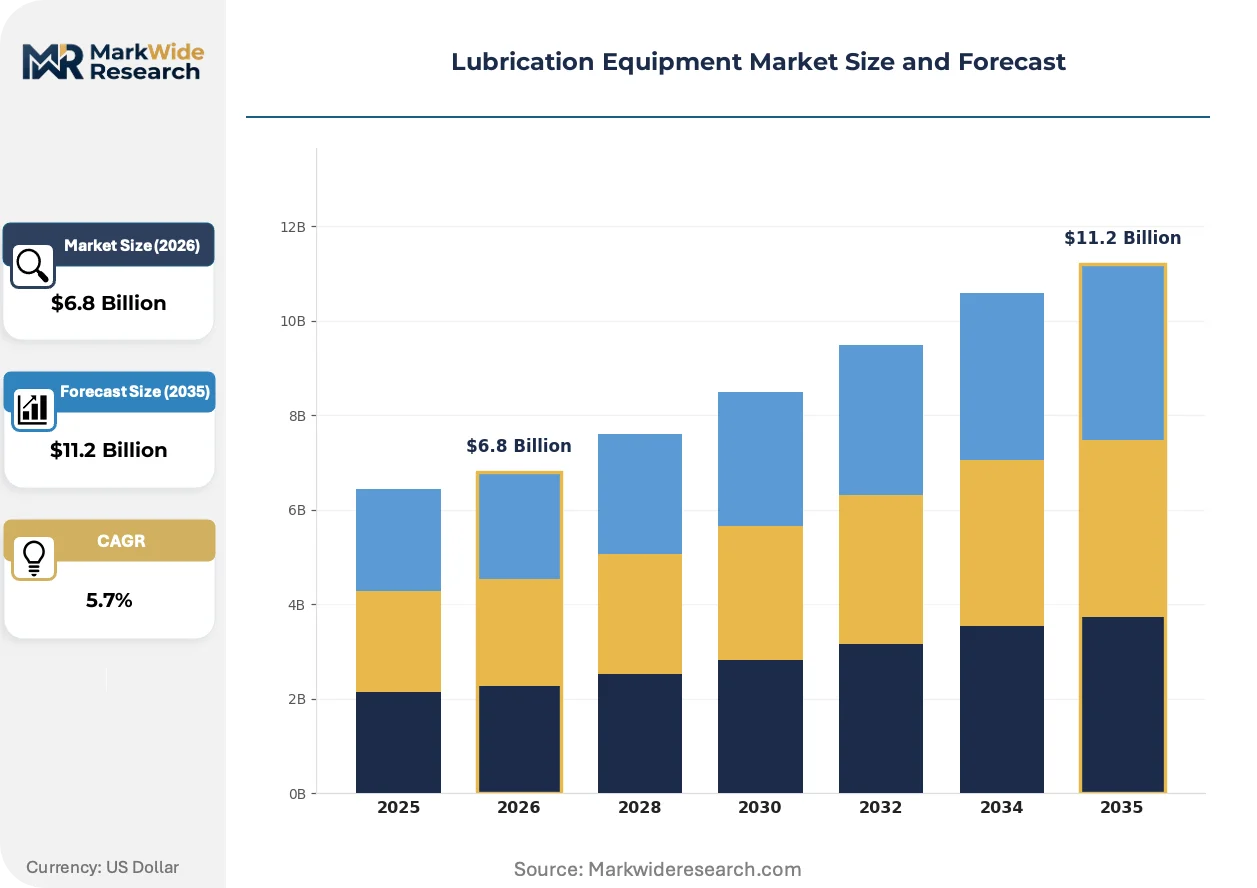
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Lubricators, Grease Pumps, Oil Pumps, Lubrication Fittings End User: Automotive Sector, Manufacturing Industry, Aerospace, Marine Technology: Centralized Lubrication Systems, Manual Systems, Electro-Mechanical Systems, Pneumatic Lubrication Application: Industrial Equipment, Transportation, Construction Machinery, Agricultural Machinery |
| Companies Covered | Bijur Delimon International, Industrial Innovations, Inc., Graco Inc., Groeneveld-BEKA, Lubrication Technologies, Inc., SKF Group, Trico Corporation, Alemite Corporation, Lincoln Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubrication Equipment Market Emerging Trajectories
Electro-mechanical lubrication systems are displacing pneumatic and hydraulic alternatives as Industry 4.0 architectures demand precise, data-rich delivery mechanisms. Three developments are compressing technology adoption cycles.
Electro-mechanical metering pumps with integrated load cells and flow sensors are expanding into food and beverage processing lines where USDA sanitary design standards prohibit compressed-air contamination. Dairy processors in Wisconsin and cheese manufacturers in the Netherlands are retrofitting filling and packaging equipment with sealed, washdown-rated automatic lubricators. This shift is compressing maintenance intervals from calendar-based to condition-based scheduling, reducing grease consumption volumes by eliminating over-lubrication.
REACH chemical restrictions on certain extreme-pressure additives are forcing reformulation of lubricant chemistries used in metalworking centralized systems. The European Chemicals Agency substance evaluation process has flagged several sulfur-phosphorus compounds common in gear lubrication, compelling equipment vendors to validate compatibility with replacement ionic liquid and borate ester formulations. German automotive stamping plants are conducting accelerated wear testing to recertify pump materials against these new chemistries before production-scale deployment.
Fleet maintenance departments are unbundling lubrication service contracts from comprehensive MRO agreements, creating direct procurement relationships with specialized equipment vendors. Heavy-truck operators in the United States are issuing separate RFPs for automated chassis lubrication systems rather than accepting bundled dealer service packages. This disintermediation is visible most acutely in long-haul trucking corridors through Texas and California, where downtime penalties exceed $1,500 per hour and fleet managers demand dedicated lubrication uptime guarantees distinct from powertrain warranties.
Lubrication Equipment Market Segmentation
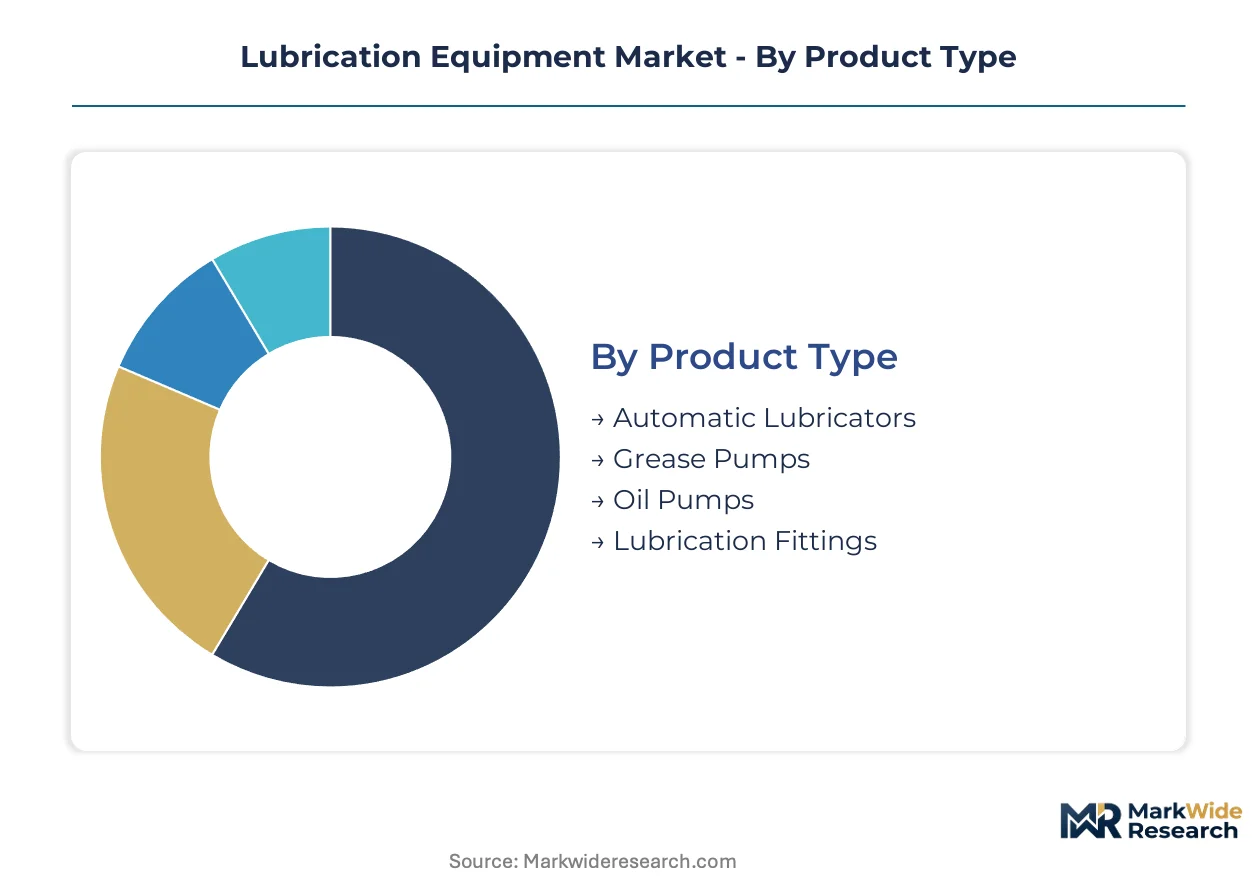
Lubrication equipment procurement patterns diverge sharply across product architectures and operational environments. Equipment specification, maintenance protocols, and regulatory compliance requirements reshape vendor priorities differently within each segment boundary.
Product Type:
Supply concentration in precision metering technology tilts competitive advantage toward integrated system manufacturers over component specialists.
- Automatic Lubricators:Programmable dispensing units with embedded controllers deliver measured grease or oil doses at timed intervals without operator intervention. Demand clusters in continuous-process manufacturing facilities across Germany and the United States where labor-cost reduction drives replacement of manual greasing routines.
- Grease Pumps:High-pressure positive displacement units, often pneumatic or battery-powered, force semi-solid lubricants through narrow distribution lines to remote friction points. Fleet maintenance depots in Texas and California heavy-trucking corridors specify these for chassis lubrication service contracts that unbundle from comprehensive MRO agreements.
- Oil Pumps:Gear, vane, or piston configurations engineered for lower-viscosity fluid transfer at pressures typically below 3,000 psi.
- Lubrication Fittings:Threaded connectors, check valves, and quick-couplers that seal against contamination while enabling attachment of dispensing equipment.
Today's leader: Automatic Lubricators. Tomorrow's challenger: Electro-mechanical converged variants.
End User:
Cost-tier stratification separates premium precision-system buyers from price-sensitive maintenance departments running legacy mineral-oil hardware.
- Automotive Sector:Tier-1 suppliers and OEM assembly plants deploy centralized lubrication networks for stamping presses, welding robots, and conveyor systems. Stuttgart and Munich manufacturing zones sustain premium procurement volumes tied to CNC machine tool uptime guarantee contracts.
- Manufacturing Industry:Metalworking, plastics processing, and packaging operations across diverse facility scales. Metalworking facilities in the United States face EPA Clean Air Act enforcement mandating sealed systems to capture volatile organic compound emissions from open dispensing equipment.
- Aerospace:Airframe assembly and MRO operations with extreme cleanliness specifications per AS9100 quality standards.
- Marine:Port cargo handling, offshore platforms, and vessel propulsion systems exposed to salt corrosion.
Manufacturing Industry commands current volume. Automotive Sector offers the steepest expansion trajectory through fleet electrification maintenance contracts.
Technology:
Application severity determines whether distributed manual points or fully automated architectures justify capital deployment.
- Centralized Lubrication Systems:Pump-reservoir-distribution networks feeding multiple machine points from a single control point, common in paper mills and steel rolling operations.
- Manual Systems:Hand-operated grease guns and oil cans requiring operator presence at each lubrication point, still prevalent in intermittent-duty construction equipment.
- Electro-Mechanical Systems:Sensor-integrated metering pumps with Ethernet/IP connectivity enabling condition-monitored delivery intervals. These are expanding most quickly into food and beverage processing lines where USDA sanitary design standards prohibit compressed-air contamination.
- Pneumatic Lubrication:Compressed-air-driven pumps and atomizers for high-volume coating applications in mining and bulk material handling.
Centralized Lubrication Systems anchor replacement demand. Electro-Mechanical Systems are gaining share fastest through Industry 4.0 predictive maintenance architectures.
Application:
Customer type fragmentation separates owner-operated fleet managers from capital-intensive process plant engineering departments.
- Industrial Equipment:Machine tools, compressors, and rotating process machinery in factory environments. EU Green Deal industrial retrofit mandates push carbon-intensive steel and cement plants toward closed-loop lubrication recovery systems to qualify for transition financing.
- Transportation:Rail pantograph and axle systems, heavy-truck chassis, and bus fleets. European railway operators are expanding centralized lubrication contracts as electric locomotive deployment intensifies friction-point maintenance requirements.
- Construction Machinery:Excavators, cranes, and earthmoving equipment with severe contamination exposure and intermittent duty cycles.
- Agricultural Machinery:Tractors, harvesters, and irrigation pumps operating in dust and moisture conditions with seasonal utilization patterns.
Industrial Equipment holds mature volume concentration. Transportation offers the fastest path to margin expansion through uptime-guarantee contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters sustain premium centralized lubrication system procurement volumes. Fleet operators across heavy-trucking corridors demand uptime-guaranteed service contracts. Port infrastructure modernization in Asian maritime hubs drives corrosion-resistant equipment specifications.
United States
Metalworking facilities in Michigan and Ohio deploy sealed lubrication systems to comply with EPA Clean Air Act volatile organic compound capture mandates. OSHA lockout-tagout specifications shape portable grease pump designs for maintenance departments. Wisconsin dairy processors retrofit USDA-compliant automatic lubricators into food packaging lines.
Germany
Stuttgart and Munich industrial zones sustain premium procurement of computer-controlled lubrication systems for CNC machine tool uptime guarantees. EU REACH chemical restrictions on extreme-pressure additives compel equipment vendors to validate new lubricant chemistries. Automotive stamping plants conduct accelerated wear testing before production-scale deployment.
China
Steel and cement plants face GB standard industrial retrofit mandates pushing closed-loop lubrication recovery system upgrades. Yangtze River Delta manufacturing bases concentrate demand for electro-mechanical metering pumps with sensor integration. MIIT Industry 4.0 directives accelerate predictive maintenance architecture adoption.
India
Jawaharlal Nehru Port Trust and Mundra Port expansion projects require corrosion-resistant marine lubrication systems for container crane slewing bearings. BIS certification timelines create staggered product launch schedules for equipment vendors. Gujarat and Maharashtra industrial corridors concentrate food processing retrofit demand for sanitary-design automatic lubricators.
Japan
Tokyo-Osaka manufacturing belts sustain precision lubrication equipment demand for semiconductor fabrication and robotics assembly. METI carbon neutrality roadmaps push steel plants toward closed-loop recovery systems. JIS cleanliness standards constrain filter media specifications for high-purity applications.
Lubrication Equipment Market Vendor Landscape
Global majors compete with regional champions across technology integration and service contract structures. The vendor base stratifies into integrated system suppliers, component specialists, and aftermarket service providers. Three archetypes dominate: North American scale manufacturers leveraging manufacturing footprint, European precision engineering houses bundling bearing-lubrication solutions, and Asian corrosion-resistant specialists targeting maritime infrastructure. Competitive moves center on sensor-integrated electro-mechanical convergence and fleet maintenance contract disintermediation.
Within the integrated system supplier tier, Graco Inc. and SKF Group exemplify contrasting geographic anchoring strategies. Graco represents North American manufacturing scale advantages in high-pressure pump assembly production. SKF occupies a position as a European precision engineering house with integrated bearing-lubrication bundling capabilities. Bijur Delimon International sits within the corrosion-resistant specialist archetype, with its company name signaling maritime application focus across Asian port infrastructure markets.
| Leading Market Players |
|---|
| Bijur Delimon International |
| Industrial Innovations, Inc. |
| Graco Inc. |
| Groeneveld-BEKA |
| Lubrication Technologies, Inc. |
| SKF Group |
| Trico Corporation |
| Alemite Corporation |
| Lincoln Industrial |
| Others |
Supply Flow & Price Mechanics
Automotive Tier-1 suppliers and heavy-truck fleet operators concentrate procurement volume, anchoring contract-based long-term pricing with embedded service guarantees rather than transactional spot purchasing.
Pricing Analysis
Input-cost pass-through from synthetic lubricant feedstock volatility shapes equipment margin structures. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated electro-mechanical systems from pneumatic alternatives and legacy manual hardware. Cost compression in standard-tier pneumatic equipment is intensifying because mineral-oil hardware faces accelerated obsolescence. Fleet maintenance departments running legacy systems exhibit highest price sensitivity, while precision manufacturing clusters in Germany demonstrate lowest sensitivity due to uptime guarantee contract structures.
Supply Chain Analysis
High-efficiency fiberglass and cellulose filtration substrates rest on German and Japanese specialty paper manufacturers, creating concentrated upstream dependency. Pump seal elastomers and corrosion-resistant marine coatings draw from South Korean and Chinese petrochemical processors. Single-source vulnerability in filter media supply exposes equipment vendors to allocation risk during capacity constraints. Distribution runs through authorized distributor networks serving industrial maintenance departments, with direct procurement relationships expanding among unbundled fleet service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in electro-mechanical system tiers where sensor integration commands premium positioning, while synthetic lubricant compatibility requirements accelerate hardware refresh cycles.
For Market Incumbents: To counter stranded-asset risk in mineral-oil-compatible installed bases, prioritize backward integration into seal and filtration component production. Accelerate certification investment for REACH-compliant chemistries and USDA sanitary designs to defend premium positioning against integrated bearing-lubrication bundlers. For New Entrants and Emerging Players: Indian port infrastructure maintenance departments represent an underserved buyer archetype with unmet demand for corrosion-resistant marine specifications. Target Jawaharlal Nehru Port Trust and Mundra Port expansion projects through local BIS certification partnerships, leveraging direct procurement relationships bypassing established MRO bundlers. For Investors and Strategic Acquirers: Integrated bearing-manufacturing conglomerates are the most active acquirer in this space, seeking lubrication system capabilities to complete motion-technology stacks. Acquisition target archetypes include electro-mechanical metering pump specialists with Ethernet/IP-enabled controller portfolios. Watch for MIIT Industry 4.0 directive acceleration in China as inflection indicator for predictive maintenance architecture adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Manufacturing | Captures margin from synthetic-lubricant compatibility redesign cycles and reduces supplier concentration risk. |
| Sensor-Integrated Electro-Mechanical Product Launch | Addresses Industry 4.0 predictive maintenance architectures demanded by German automotive stamping plants. |
| REACH Compliance Certification Investment | Validates pump material compatibility with ionic liquid and borate ester lubricant chemistries for EU market access. |
| Long-term Service Contract with Fleet Operators | Locks in uptime-guaranteed revenue streams across Texas and California heavy-trucking corridors. |
| Joint Venture for Indian Port Infrastructure | Combines corrosion-resistant technology with local BIS certification capabilities for Jawaharlal Nehru Port Trust projects. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured maintenance directors at German automotive stamping plants, plant engineers at Wisconsin dairy processors, OEM procurement teams at Tier-1 suppliers, aftermarket service heads at heavy-truck fleet operators, and technical R&D directors at filtration media manufacturers. Secondary validation drew from customs trade data, SEC 10-K equipment vendor filings, EPA enforcement action databases, and EU REACH substance evaluation records. Bottom-up equipment shipment tracking and top-down industrial capital expenditure analysis were triangulated against regional regulatory implementation timelines.
Segment-weighting across product type, end-use vertical, technology architecture, and application severity determined value allocation throughout the projection horizon. Electro-mechanical system penetration rates, synthetic lubricant formulation adoption curves, and fleet electrification maintenance contract expansion were modeled as industry-specific forecast inputs. CAGRs were derived from fitted growth curves against historical equipment replacement cycles and regulatory compliance deadlines.
Underlying measurement precision varies by segment; automatic lubricator shipment data carries tighter precision than emerging electro-mechanical system forecasts. Projections reflect assumptions regarding REACH chemical restriction implementation pace and OSHA enforcement intensity. Material deviation in EPA Clean Air Act enforcement scope or synthetic base oil feedstock cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Anti-Static Oil Market
Lubricants
Aviation Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Marine Grease Market
Lubricants
ASEAN Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Global Lubricants Market