
 Mexico Lubricants Market | 2026-2036
Mexico Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Lubricants Market Foresight
Bulk-to-blended packaging flexibility is hardening as fleet operators and industrial buyers shift from standardized drums toward modular totes and customized volume contracts. ExxonMobil Corporation leverages its Gulf Coast supply infrastructure to anchor premium synthetic distribution across northern Mexico. Shell Plc competes through channel control in the aftermarket, sustaining retail visibility through dedicated service bay partnerships in Mexico City and Monterrey.
Lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades and oxidation stability determining operational suitability. The automotive application segment dominates volume consumption due to Mexico's vehicle assembly density, while industrial lubricants generate concentrated margin pools from steel and cement operations in Coahuila. Engine oil leads product type demand through OEM fill requirements and high-frequency drain intervals, though hydraulic fluid extends fastest from construction and mining equipment renewal cycles.
SEMARNAT oversees environmental compliance for lubricant formulation and waste oil handling, while PROFECO enforces labeling and consumer protection standards that constrain import arbitrage. NOM-120-SEMARNAT-2011 establishes used oil collection obligations that reshape aftermarket service economics and collection infrastructure investments. Stakeholders must monitor regulatory alignment between state environmental agencies and federal enforcement priorities as compliance costs redistribute across the value chain.
Market Dynamics
Fleet operators in Mexico's Bajío corridor are consolidating lubricant procurement under long-term volume contracts, compressing distributor margins while elevating formulation specificity as the dominant competitive battleground.
Growth Catalysts
- NOM-120-SEMARNAT-2011:Mandatory used oil collection obligations are forcing aftermarket service networks to invest in reverse logistics infrastructure, creating captive demand for compliant collection and re-refining services.
- Synthetic base oil substitution:OEM fill specifications for Group II and Group III base stocks are tightening across automotive assembly plants in Guanajuato and Querétaro, pulling blenders toward higher-margin product tiers.
- Construction equipment renewal:Hydraulic fluid demand from mining and infrastructure projects in Coahuila is accelerating drain interval compression, expanding consumption volume per machine hour.
Market Restraints
- Base oil import dependency:Mexico lacks domestic API Group II/III production capacity, exposing blenders to Gulf Coast refinery margin volatility and USMCA tariff friction on specialty additive packages.
- PROFECO labeling enforcement:Strict consumer protection standards on viscosity grade claims and performance certifications constrain parallel import arbitrage, limiting price competition from non-compliant suppliers.
- Re-refining technology gaps:Local used oil reprocessing facilities operate below international yield benchmarks, elevating waste disposal costs and compressing circular economy margins.
Strategic Opportunities
- Yucatán Peninsula industrialization:Lagging lubricant penetration in southeastern Mexico offers first-mover positioning as manufacturing investment rotates away from saturated northern corridors.
- SEMARNAT circular economy incentives:Emerging tax credits for re-refined base oil utilization create margin expansion potential for vertically integrated collectors with processing capabilities.
- Digital fleet management convergence:Telematics-enabled oil condition monitoring is integrating with procurement platforms, enabling predictive drain scheduling and locking lubricant suppliers into embedded service contracts.
Industry Challenges
- Additive chemist scarcity:Formulation expertise for Mexico-specific climate conditions—high altitude, humidity variance, dust exposure—resides concentrated with multinational technical centers, constraining local R&D autonomy.
- State-federal regulatory misalignment:Environmental enforcement priorities diverge between SEMARNAT central directives and state agency implementation, complicating nationwide compliance program design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Lubricants Market |
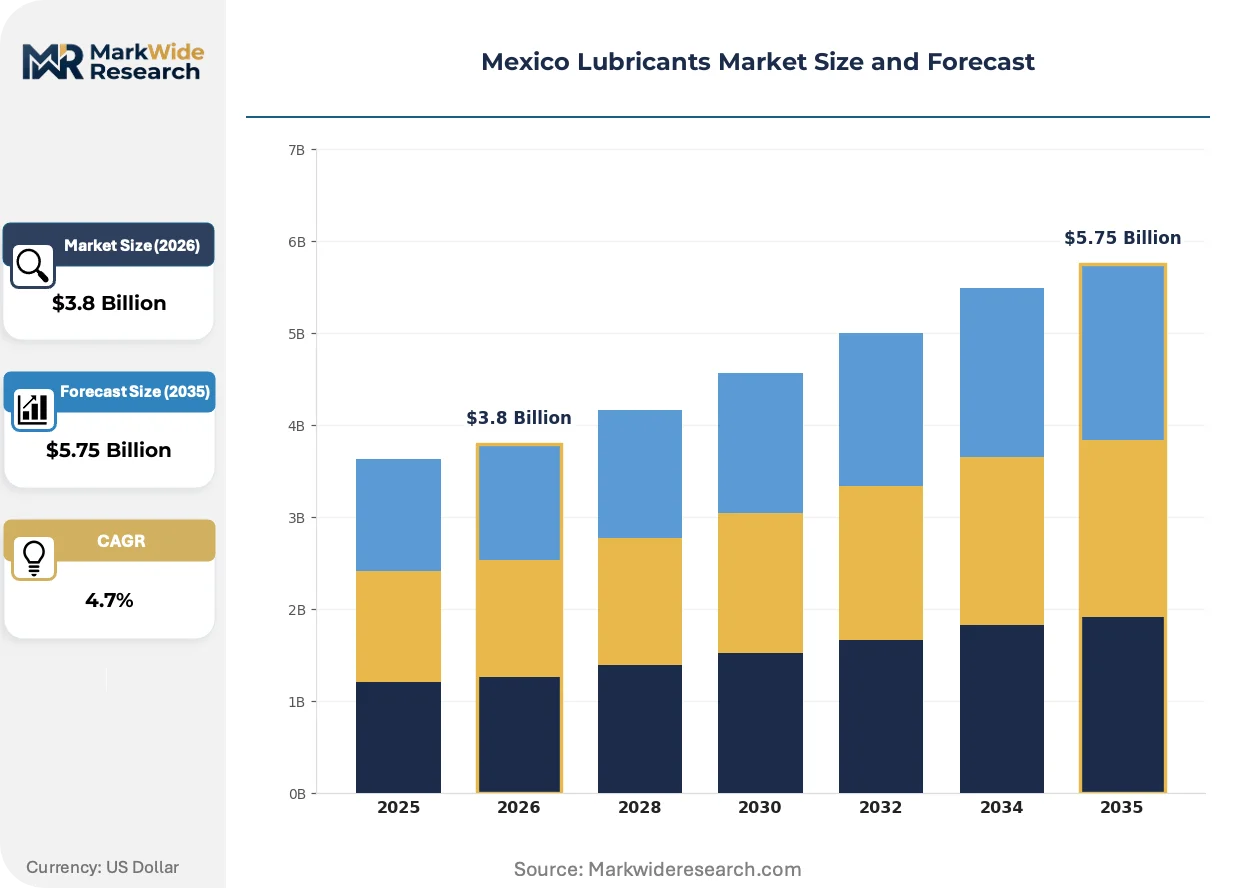
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Fluid, Transmission Fluid, Gear Oil Application: Automotive, Industrial, Marine, Agriculture End User: OEMs, Aftermarket Providers, Fleet Operators, Airlines Distribution Channel: Retail, E-Commerce, B2B Sales, Direct Sales |
| Companies Covered | ExxonMobil Corporation, Shell Plc, BP p.l.c., Chevron Corporation, TotalEnergies, Roshfrans, Raloy, Mexicana de Lubricantes, Fuchs Petrolub SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Lubricants Market Shifts & Advancements
Synthetic formulation advancement and regulatory pressure on waste streams are converging to restructure Mexico's lubricant value chain, with technology adoption pacing set by automotive OEM specification cycles rather than end-user preference.
Polyalphaolefin (PAO) and ester-based synthetic lubricants are integrating into heavy-duty diesel and industrial hydraulic applications, delivering extended drain intervals and thermal stability under high-load conditions. Mining operators in Coahuila and fleet managers in Monterrey are adopting these chemistries fastest, accepting 40-60% price premiums for operational uptime gains. This integration is compressing conventional mineral oil share in premium segments while elevating blender technical service requirements.
NOM-120-SEMARNAT-2011 implementation is tightening used oil collection and transport documentation obligations across Mexico's 32 federal entities. The regulation mandates generator-to-processor chain-of-custody tracking, elevating compliance costs for independent workshops and favoring integrated service networks with captive collection infrastructure. Aftermarket service bays in Mexico City and Guadalajara are consolidating waste handling partnerships to meet documentation burdens.
Fleet procurement departments are unbundling lubricant supply from equipment maintenance contracts, shifting toward direct volume negotiations with blenders and bypassing traditional distributor markups. This disintermediation is most pronounced among commercial vehicle operators in the Bajío automotive corridor, where procurement centralization is compressing distributor margins and forcing channel restructuring toward logistics and technical service provision rather than product resale.
Mexico Lubricants Market Segmentation
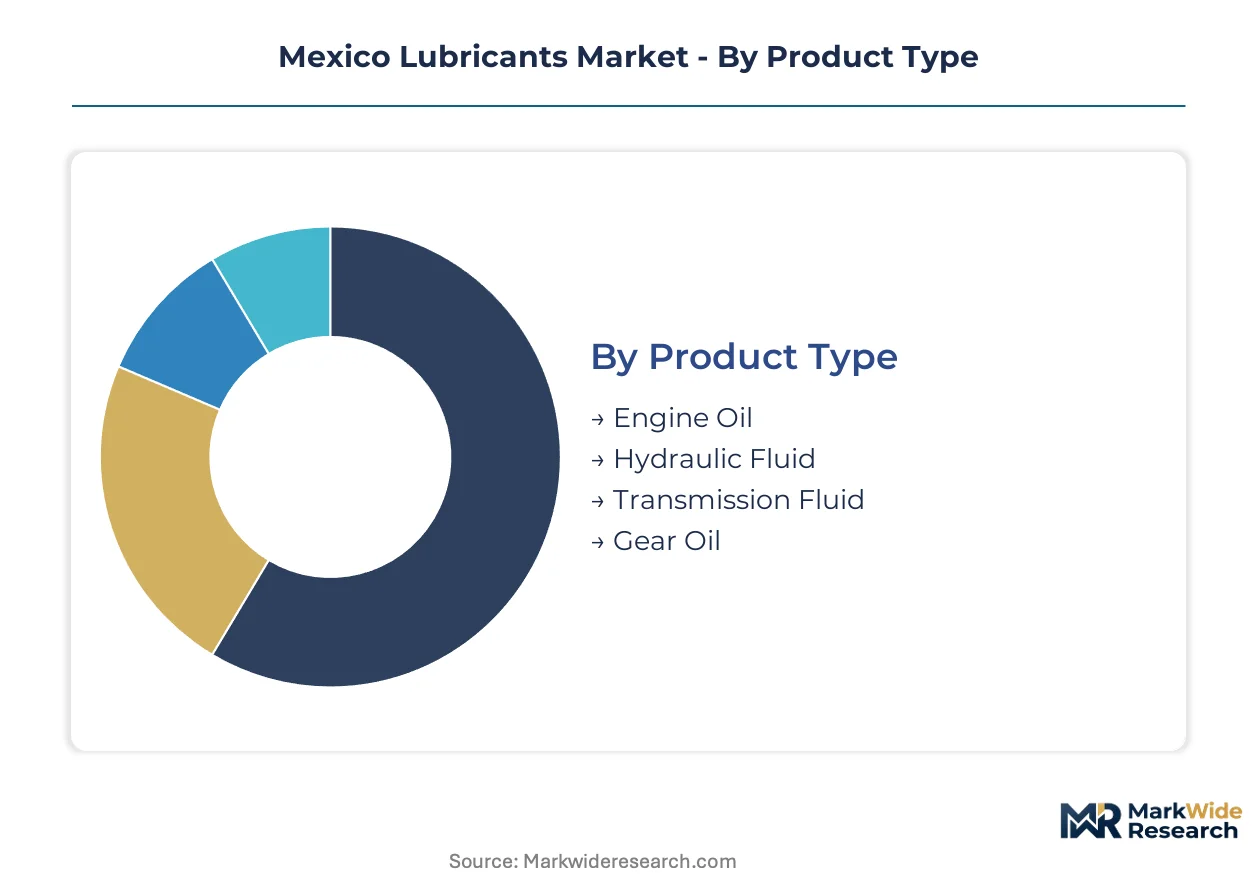
Mexico's lubricant demand fragments across equipment replacement cycles, procurement consolidation patterns, and regulatory compliance tiers. Understanding these segment boundaries reveals where formulation premiums extract value versus where volume contracts dominate pricing.
Product Type:
Equipment upgrade intensity varies sharply by fluid category, with drain interval extension and thermal specification tightening driving substitution decisions.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages meeting API SP and ILSAC GF-6 specifications. OEM fill requirements at Guanajuato and Querétaro assembly plants lock in synthetic penetration, while high-frequency drain intervals in commercial fleets sustain volume density. Volume placements concentrate in Engine Oil; the faster expansion belongs to Hydraulic Fluid.
- Hydraulic Fluid:Anti-wear formulations with zinc dialkyldithiophosphate (ZDDP) chemistry and viscosity index improvers for construction and mining equipment. Coahuila mining operators and Bajío infrastructure contractors are compressing replacement cycles amid equipment renewal waves, accepting synthetic ester premiums for uptime protection.
- Transmission Fluid:Friction-modified ATF and manual transmission oils with shear-stable viscosity grades. OEM warranty requirements in automotive assembly constrain aftermarket substitution.
- Gear Oil:Extreme-pressure hypoid formulations for axle and differential applications. Heavy-duty trucking corridors sustain steady demand without rapid specification shifts.
Formulation complexity escalates from gear oils toward engine and hydraulic fluids, with premium capture concentrated where OEM specifications intersect with severe-service operating conditions.
Application:
End-use profitability diverges between high-volume automotive consumption and concentrated-margin industrial operations serving steel and cement producers.
- Automotive:Passenger vehicle and commercial fleet lubrication spanning OEM fill, service fill, and aftermarket retail. Vehicle assembly density in the Bajío corridor generates captive demand for synthetic formulations meeting domestic and export market specifications. Automotive generates the deepest volume base; industrial commands the steepest margin expansion.
- Industrial:Steel rolling mills in Coahuila, cement kilns, and manufacturing equipment lubrication. Severe operating temperatures and contamination exposure drive premium synthetic adoption with technical service bundling.
- Marine:Outboard motor oils and stern tube lubricants for coastal and inland waterway operations. Environmental discharge regulations constrain formulation choices.
- Agriculture:Tractor hydraulic fluids and engine oils for seasonal equipment intensity. Price sensitivity limits synthetic penetration despite extended drain interval economics.
Automotive applications dominate procurement volume; industrial segments deliver the most concentrated margin pools through technical specification premiums.
End User:
Procurement centralization intensity separates price-takers from specification-setters across Mexico's lubricant value chain.
- OEMs:Automotive assembly plants in Guanajuato and Querétaro specifying factory-fill lubricants for domestic production and export markets. Fill specifications cascade backward to blender formulation investments and base oil sourcing requirements.
- Aftermarket Providers:Independent workshops, quick-lube chains, and service bays managing retail consumer and small fleet demand. NOM-120-SEMARNAT-2011 compliance obligations are consolidating waste handling partnerships toward integrated networks.
- Fleet Operators:Commercial vehicle and mining equipment managers unbundling lubricant supply from maintenance contracts. Bajío corridor fleet procurement departments are negotiating direct volume agreements with blenders, compressing traditional distributor margins.
- Airlines:Aviation turbine lubricants for commercial and cargo operations. Specification stringency and regulatory certification create insular procurement channels with limited crossover to other segments.
Fleet operators are accelerating procurement disintermediation; OEMs retain the strongest specification-setting leverage over upstream formulation.
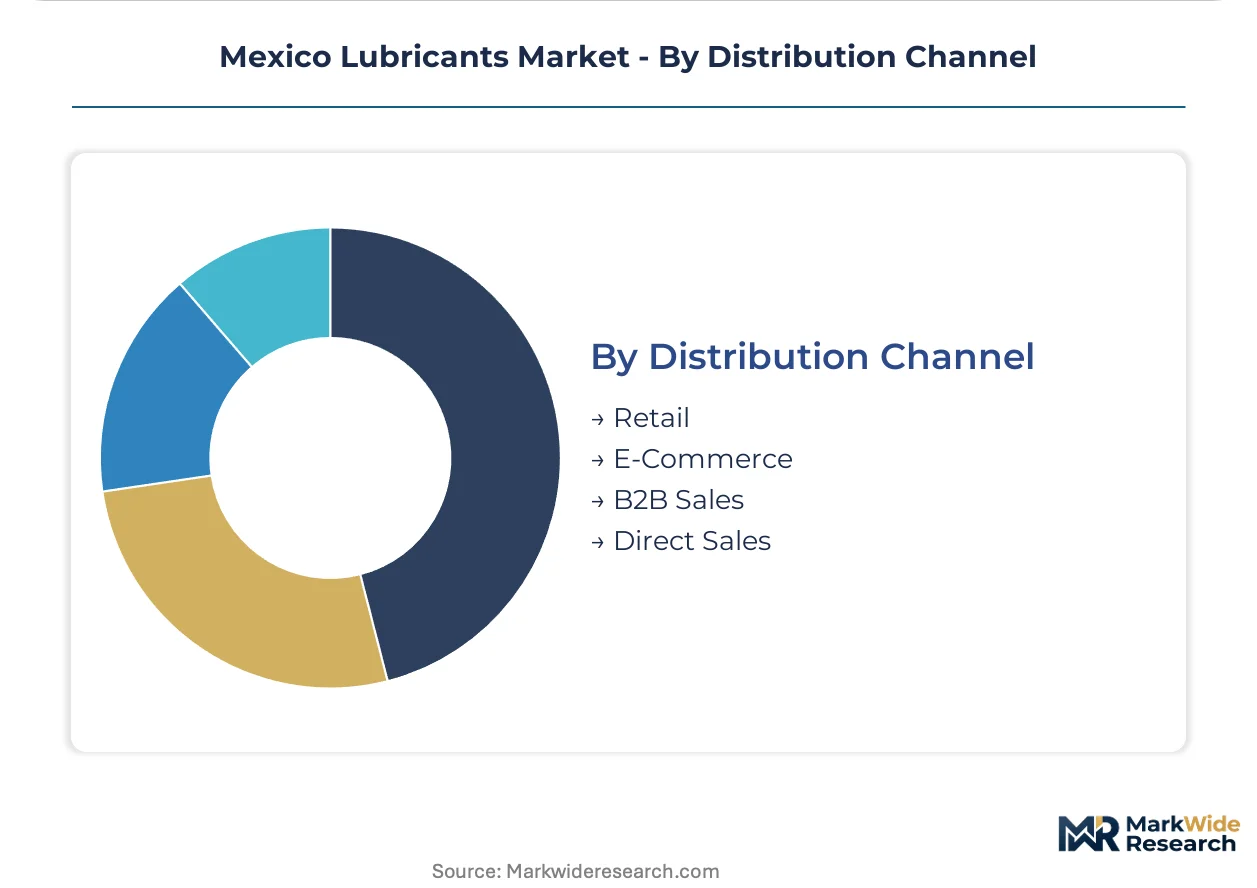
Distribution Channel:
Channel economics reshape around bulk logistics efficiency versus technical service intensity as procurement patterns shift.
- Retail:Automotive parts stores, hypermarkets, and service stations serving DIY consumers and small workshops. PROFECO labeling enforcement constrains parallel import arbitrage, protecting compliant domestic suppliers.
- E-Commerce:Digital platforms capturing consumer and small fleet procurement with delivery logistics and price transparency. Penetration remains limited by immediate-need fulfillment requirements and technical consultation gaps.
- B2B Sales:Distributor networks serving fleet, industrial, and agricultural accounts with volume contracts and technical field support. Margin compression is forcing channel restructuring toward logistics and service provision rather than product resale.
- Direct Sales:Blender-to-end-user relationships eliminating distributor markups through long-term volume agreements. Bajío fleet consolidation and Coahuila mining procurement are accelerating this channel's expansion.
B2B networks still handle the greatest volume throughput; direct sales channels are climbing fastest as procurement centralization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's lubricant production concentrates in northern blending facilities while consumption clusters in the Bajío automotive corridor, creating a north-south supply flow shaped by USMCA trade integration and domestic manufacturing density.
Bajío Region
Automotive assembly plants in Guanajuato and Querétaro generate captive demand for synthetic engine oils meeting export-market specifications. SEMARNAT's NOM environmental standards govern waste oil handling across the corridor's service networks. OEM fill requirements at Volkswagen, Honda, and Mazda facilities pull blenders toward Group III base stock formulations.
Nuevo León
Monterrey's heavy-duty trucking corridors and steel rolling mills sustain concentrated industrial lubricant consumption with severe-service thermal specifications. PROFECO labeling enforcement protects compliant domestic suppliers from parallel import arbitrage. Fleet operators in the metropolitan area are consolidating procurement under direct blender contracts, bypassing traditional distributor channels.
Mexico City Metro
The capital's dense aftermarket service bay network faces escalating NOM-120-SEMARNAT-2011 compliance costs for used oil collection documentation. State environmental agencies enforce federal mandates with varying intensity across the metropolitan zone. Quick-lube chains and independent workshops are consolidating waste handling partnerships toward integrated networks with captive reverse logistics.
Coahuila
Mining operations in the coal and metal extraction belts drive hydraulic fluid demand with compressed replacement cycles amid equipment renewal waves. The state's industrial base lacks domestic re-refining capacity at international yield benchmarks. Steel producers in Monclova and Piedras Negras anchor premium synthetic adoption for high-temperature rolling mill applications.
Yucatán Peninsula
Southeastern Mexico presents underpenetrated lubricant markets as manufacturing investment rotates from saturated northern corridors. Lagging infrastructure for bulk distribution and technical service coverage constrains blender expansion. Mérida and Campeche industrial zones offer first-mover positioning for direct sales models targeting emerging fleet operators.
Mexico Lubricants Market Competitive Landscape
The competitive structure tilts toward multinational blenders with integrated supply chains and captive distribution networks. Gulf Coast supply infrastructure anchors premium synthetic distribution, while regional specialists defend position through aftermarket channel control. Three archetypes dominate: integrated majors with backward base oil sourcing, national blenders with service bay partnerships, and niche formulators targeting severe-service industrial applications. Capacity rationalization and direct procurement contracting represent the dominant competitive moves reshaping channel economics.
Among integrated majors, ExxonMobil Corporation and Shell Plc exemplify contrasting strategic positions. ExxonMobil leverages its Gulf Coast refinery integration to anchor synthetic distribution across northern Mexico, while Shell competes through dedicated service bay partnerships sustaining retail visibility in Mexico City and Monterrey. BP p.l.c. and Chevron Corporation occupy positions within the premium-tier blender category, their scale enabling formulation investments for OEM fill specifications. Roshfrans and Raloy represent the national blender archetype, their regional manufacturing footprint aligning with state-level procurement consolidation patterns.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell Plc |
| BP p.l.c. |
| Chevron Corporation |
| TotalEnergies |
| Roshfrans |
| Raloy |
| Mexicana de Lubricantes |
| Fuchs Petrolub SE |
| Others |
Supply & Pricing Matrix
Gulf Coast Group II/III base oil posted prices cascade through Mexico's blender network into three distinct pricing tiers, with USMCA tariff friction on specialty additive packages amplifying cost volatility for mid-tier formulators serving Bajío fleet operators.
Pricing Analysis
Margin tightening in the mid-tier synthetic segment reflects direct blender-to-fleet contracting that strips distributor markups from the value chain. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified Group III formulations from commercial-grade Group II blends and mineral-based aftermarket products. Cost-down pressure on standard-tier products accelerates because fleet procurement centralization in Guanajuato and Querétaro compresses volume premiums. Aftermarket providers exhibit the highest price sensitivity due to NOM-120-SEMARNAT-2011 compliance cost absorption, while OEM fill specifications lock in the lowest sensitivity at premium tiers.
Supply Chain Analysis
API Group II/III base oil supply rests on Gulf Coast refinery output from the United States, with specialty additive packages drawing from German and Japanese chemical producers. Zinc dialkyldithiophosphate anti-wear chemistries, viscosity index improvers, and detergent-dispersant packages constitute critical formulation inputs. Single-source vulnerability concentrates in USMCA-dependent additive import channels subject to customs documentation scrutiny. Distribution runs through Monterrey bulk terminals into modular tote logistics for Bajío automotive corridors, with residual drum shipments serving fragmented aftermarket workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM-120-SEMARNAT-2011's mandatory used oil collection infrastructure transforms compliance cost into a barrier-to-entry moat, rewarding blenders with captive reverse logistics networks and marginalizing independent distributors lacking documentation capabilities.
For Market Incumbents: Anticipate fleet procurement disintermediation by anchoring direct volume contracts with technical service bundling in Coahuila mining and Bajío commercial vehicle operations. Defensive consolidation of waste handling partnerships in Mexico City and Guadalajara service bay networks neutralizes emerging re-refiner entrants. Backward integration into Gulf Coast base oil offtake agreements secures margin protection against USMCA tariff friction on specialty additive packages. For New Entrants and Emerging Players: Launch via direct sales models targeting Yucatán Peninsula manufacturing zones where bulk distribution infrastructure gaps create first-mover positioning outside incumbent channel control. White-space concentration in Mérida and Campeche industrial corridors offers procurement relationship formation before northern blender saturation extends southeast. Telematics-enabled oil condition monitoring integration provides the most penetrable service differentiation angle for fleet embedded contracting. For Investors and Strategic Acquirers: Distressed-cycle entries favor national blenders with SEMARNAT-compliant collection infrastructure in central Mexican states over asset-light distributors facing NOM documentation cost spirals. Long-term viability hinges on circular economy positioning as re-refined base oil utilization incentives mature. Monitor SEMARNAT tax credit implementation velocity as the inflection signal for vertically integrated collector-processor margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Gulf Coast offtake agreements insulate blenders from USMCA tariff volatility on Group II/III feedstocks. |
| Reverse Logistics Infrastructure Buildout | NOM-120-SEMARNAT-2011 compliant collection networks capture captive waste oil flows for re-refining economics. |
| Direct Fleet Contracting Expansion | Bypassing distributor markups in Bajío corridors locks volume commitments through technical service bundling. |
| Telematics Platform Integration | Oil condition monitoring convergence enables predictive drain scheduling and embedded procurement relationships. |
| Yucatán Distribution Footprint Establishment | Southeastern manufacturing rotation creates first-mover positioning ahead of incumbent channel extension. |
Research Methodology
Document review covered SEC filings from multinational energy companies, Mexican customs trade records, and SEMARNAT regulatory guidance, complemented by interviews with blender procurement directors, fleet maintenance managers in Guanajuato and Querétaro, aftermarket service bay operators, and Coahuila mining equipment supervisors. Secondary validation drew from PROFECO consumer protection bulletins, base oil price reporting services, and automotive OEM technical specification databases. Bottom-up volume triangulation across product type and application segments was cross-checked against top-down macroeconomic drivers.
Segmentation outputs across the analysis window reflect modeled interactions between synthetic formulation penetration rates, fleet procurement centralization velocity, and NOM-120-SEMARNAT-2011 compliance cost absorption. The analytical framework incorporated product type splits, application end-uses, end-user procurement archetypes, and regional manufacturing density as core dimensions. CAGRs were derived from equipment replacement cycle timing, OEM specification tightening trajectories, and construction equipment renewal waves in Coahuila. Forecast inputs included base oil price elasticity assumptions and used oil collection infrastructure buildout rates.
The model assumes a particular technology adoption path; alternative pathways for synthetic ester penetration in severe-service hydraulic applications would alter the outlook for premium-tier volume capture. Forecasts reflect assumptions about USMCA trade continuity, SEMARNAT enforcement intensity uniformity across federal entities, and Gulf Coast refinery capacity allocation. A small set of named triggers—re-refining tax credit implementation, additive import tariff adjustments, and telematics platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Thailand Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Food Grade Lubricant Market
Lubricants
Marine Grease Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Europe Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
South Korea Automotive Lubricants Market
Lubricants
Europe Grease Market
Lubricants
China Commercial Vehicles Lubricants Market