
 Europe Gas Barrier Membrane Market | 2026-2036
Europe Gas Barrier Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gas Barrier Membrane Market Foresight
Aftermarket service revenue for membrane inspection and remediation is tilting toward specialized contractors who bundle installation with long-term performance guarantees. Delta Membranes leverages its UK distribution network to dominate specification channels for below-grade applications. A. Proctor Group Ltd anchors its position through backward integration into polymer compounding, controlling raw material consistency for critical aerospace sealing grades.
Europe gas barrier membranes are multi-layer polymer laminates engineered to achieve oxygen transmission rates below 0.1 cc/m²/day, typically coextruded or metallized to block gas ingress in sensitive enclosures. Their primary commercial purpose is preserving product integrity across pharmaceuticals packaging, electronics protection, and construction insulation by eliminating oxidative degradation and moisture-driven corrosion. Polyethylene and polyamide formulations occupy the mature volume tier, while metallized films capture expanding margin pools in electronics protection where hermetic performance commands specification premiums. Ethylene vinyl alcohol competes aggressively in food packaging, though its moisture sensitivity limits deployment in unconditioned construction environments.
EMA stability testing guidelines for pharmaceutical primary packaging, REACH restrictions on fluorinated polymer precursors, and the EU Green Deal embodied-carbon thresholds for construction materials collectively reshape formulation roadmaps and supplier qualification protocols. CE marking under the Construction Products Regulation mandates declared permeability values for membranes used in building envelopes, creating compliance barriers for non-European producers. Stakeholders must monitor evolving F-Gas Regulation phase-out schedules and polymer recycling mandates under the CSRD to anticipate raw material cost trajectories and qualification timelines.
Market Dynamics
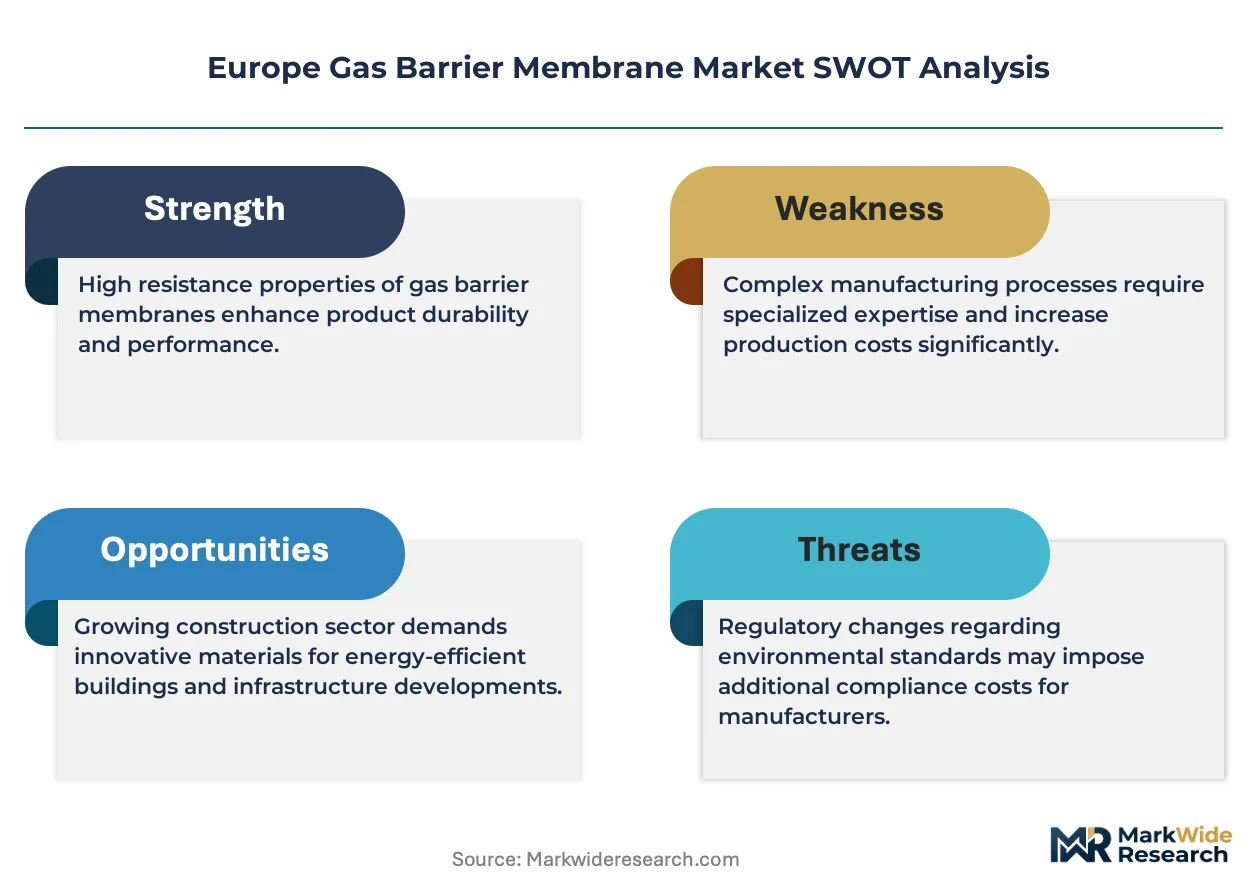
Regulatory pressure from the EU Green Deal and F-Gas Regulation is compressing formulation cycles, forcing suppliers to abandon fluorinated gas-based barrier layers and accelerate metallized film and polyamide alternatives through qualification pipelines.
Growth Catalysts
- Residential Retrofit Mandates:German federal building renovation programs specify high-performance membranes for energy-efficient envelopes, pulling volume through certified contractor networks.
- REACH Fluorinated Precursor Restrictions:ECHA restrictions on perfluorinated polymer feedstocks are redirecting R&D investment toward metallized polyethylene terephthalate and aluminum oxide coatings.
- Public Housing Schemes:French Anah and ELAN law renovation frameworks mandate permeability declarations for social housing insulation systems, concentrating demand among pre-qualified membrane suppliers.
Market Restraints
- Ethylene Vinyl Alcohol Moisture Sensitivity:EVOH's hydrophilic degradation in unconditioned construction sites limits deployment to climate-controlled pharmaceutical and food packaging, excluding outdoor building applications.
- Aluminum Metallization Supply Concentration:Vacuum metallization capacity clusters in southern Germany and northern Italy, creating geographic chokepoints for high-barrier electronics-grade films.
- CE Marking Compliance Burden:Construction Products Regulation declared permeability testing adds 12-18 month qualification timelines for non-European membrane producers seeking building envelope access.
Strategic Opportunities
- Polish and Romanian Construction Markets:EU cohesion fund infrastructure programs in eastern member states are specifying membrane systems for first-time building envelope upgrades, opening specification channels outside established western European contractor relationships.
- Aerospace Sealing Grades:Backward integration into polymer compounding enables custom ethylene-vinyl acetate and ionomer formulations for satellite and aircraft pressure vessel applications.
- CSRD Embodied Carbon Reporting:Corporate Sustainability Reporting Directive polymer recycling mandates create first-mover advantage for membrane suppliers with verified post-industrial polyamide feedstock chains.
Industry Challenges
- Multi-layer Coextrusion Technician Scarcity:Operating precision seven-layer blown film lines requires specialized extrusion die calibration expertise that outpaces vocational training program output in France and Germany.
- EMA Stability Protocol Alignment:Pharmaceutical primary packaging qualification demands oxygen transmission rate consistency across temperature-humidity cycling that conflicts with construction-grade membrane batch-to-batch variation tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gas Barrier Membrane Market |
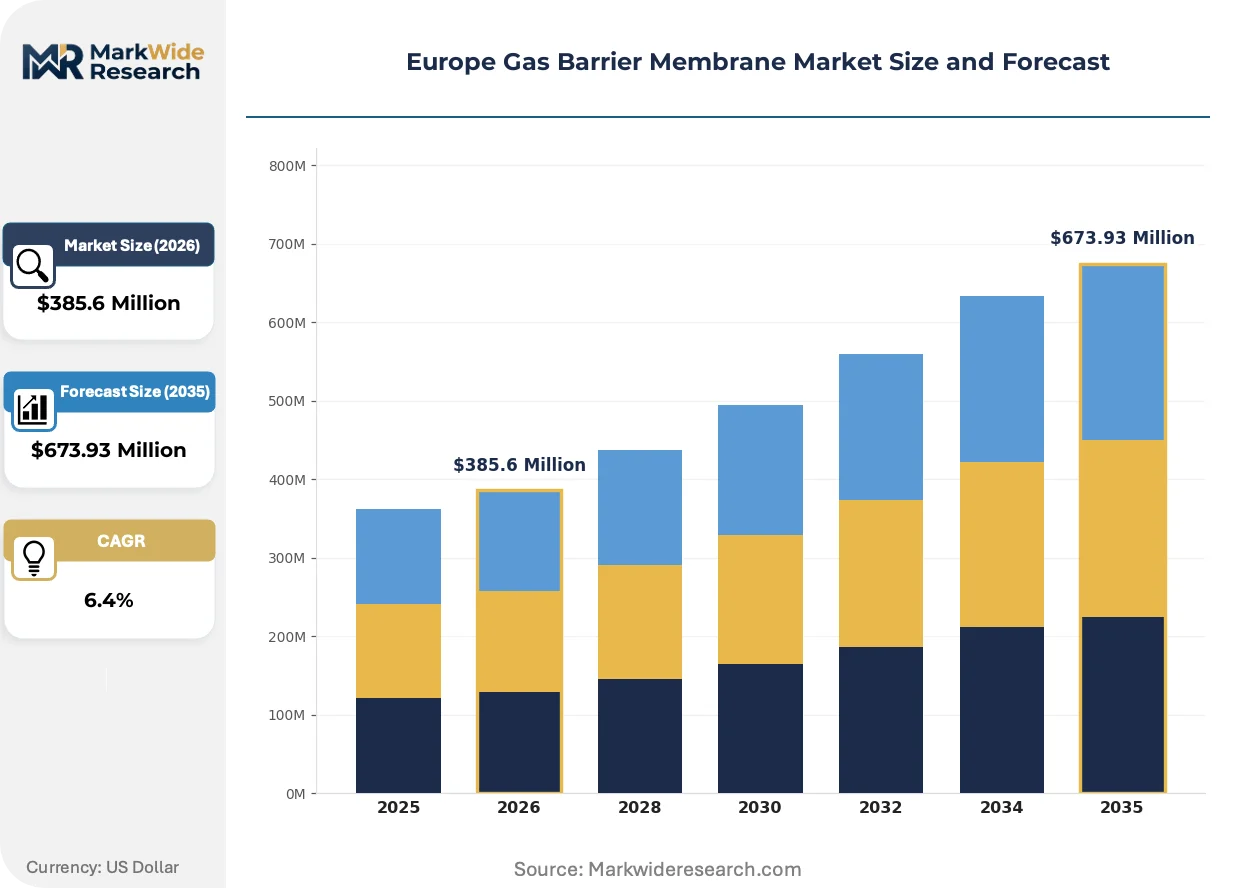
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinylidene Chloride, Ethylene Vinyl Alcohol, Metallized Films, Polyamide, Polyester Application: Food Packaging, Pharmaceuticals Packaging, Electronics Protection, Construction Insulation, Automotive Components, Aerospace Sealing Installation Type: Roofing Systems, Wall Cladding, Flooring, Foundation Barriers, Underground Structures, Temporary Enclosures End User: Packaging Manufacturers, Construction Contractors, Electronics Assemblers, Pharmaceutical Companies, Vehicle Manufactures, Aerospace Industries |
| Companies Covered | Delta Membranes, Industrial Textiles & Plastics Ltd, Permagard Products Limited, Monarflex sro, A. Proctor Group Ltd, Newton Waterproofing, RIW Ltd, CETCO, Berry Global Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gas Barrier Membrane Market Shifts & Advancements
Material science convergence with digital manufacturing controls is redefining barrier performance verification, compressing the gap between laboratory specification and field-achieved permeability.
Metallized aluminum oxide coating via plasma-enhanced chemical vapor deposition is digitizing quality assurance protocols. Electronics manufacturers in the Netherlands and Finland are adopting inline spectroscopic monitoring of barrier uniformity, replacing destructive batch testing. This is digitizing supplier-customer data exchange, enabling real-time permeability certificates that accompany each membrane roll.
The F-Gas Regulation phase-down schedule is tightening refrigerant gas containment standards for cold chain packaging. ECHA enforcement of hydrofluorocarbon quotas is forcing pharmaceutical logistics providers toward hermetic metallized pouches for temperature-sensitive biologics. French and German vaccine distribution networks are now specifying sub-0.05 cc/m²/day transmission rates that exceed conventional polyethylene capabilities.
Specification authority is migrating from general contractors to specialized membrane installation firms with long-term performance guarantees. Below-grade waterproofing and radon barrier projects in Belgium and Austria now bundle membrane supply with 10-year ingress warranties, displacing commodity product bidding. This service integration concentrates procurement decisions among certified applicator networks rather than distributor stockists.
Europe Gas Barrier Membrane Market Segmentation
Gas barrier membrane segmentation in Europe reflects divergent performance requirements across packaging integrity, building envelope durability, and hermetic sealing applications. Formulation chemistry, installation method, and end-user certification standards create distinct commercial tiers with incompatible procurement channels.
Product Type:
Use-case spectrum spans commodity food packaging through satellite-grade hermetic seals, with oxygen transmission rates varying by three orders of magnitude across material classes.
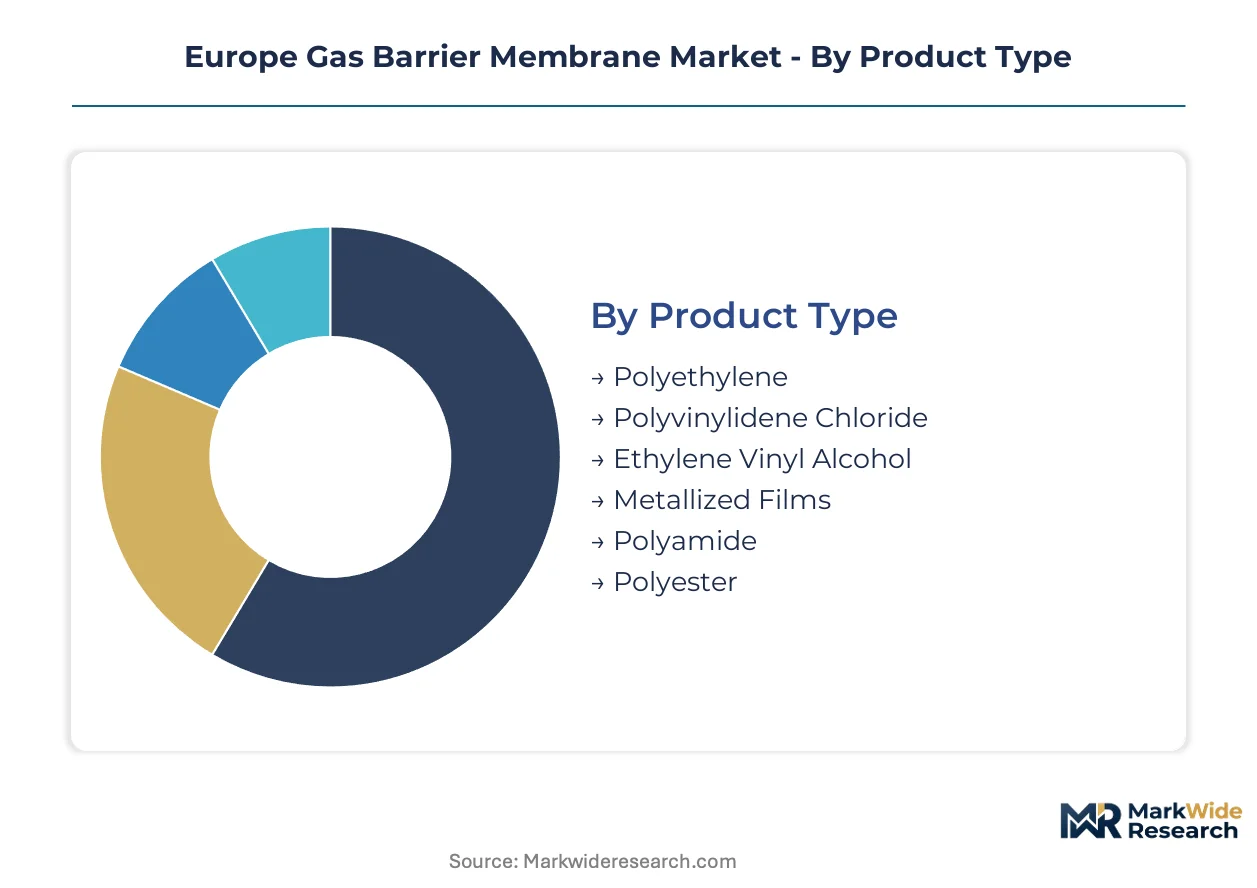
- Polyethylene:Linear low-density formulations dominate volume through coextruded multi-layer structures achieving 0.5-2.0 cc/m²/day transmission rates. German food packaging converters specify this for chilled meat and dairy where cost sensitivity outweighs ultra-high barrier demands.
- Metallized Films:Aluminum oxide vapor-deposited polyester achieves sub-0.05 cc/m²/day performance for pharmaceutical cold chain and electronics hermetic packaging. Dutch vaccine distribution networks and Finnish semiconductor fabs are driving specification premiums for inline spectroscopic quality verification.
- Polyvinylidene Chloride:High-clarity shrink films for fresh produce packaging with moderate barrier properties.
- Ethylene Vinyl Alcohol:Hydroxyl-group density delivers exceptional oxygen blocking in dry conditions; moisture sensitivity restricts deployment to climate-controlled pharmaceutical primary packaging.
- Polyamide:Nylon 6 and 6/6 copolymers provide puncture resistance and thermal stability for retort pouches and construction underlayments.
- Polyester:Biaxially oriented PET substrates serve as metallization carriers and standalone mechanical protection layers.
The dominant share belongs to polyethylene, while metallized films are closing the gap fastest.
Application:
Margin structure stratifies sharply: packaging applications compete on throughput efficiency while aerospace and electronics segments command qualification premiums.
- Food Packaging:Modified atmosphere packaging for red meat and cheese drives high-volume consumption of coextruded polyethylene-EVOH laminates. French retail consolidation toward centralized distribution centers is standardizing barrier specifications across private-label supply chains.
- Construction Insulation:Vapor-open versus vapor-closed membrane positioning determines specification in German Energieeffizienzhaus retrofits and French Anah social housing renovations. CE marking under the Construction Products Regulation mandates declared permeability values that disqualify non-European producers lacking notified body certification.
- Pharmaceuticals Packaging:Blister foils and cold-formed aluminum laminates for EMA stability testing compliance.
- Electronics Protection:Hermetic pouches for moisture-sensitive OLED displays and lithium-ion cells.
- Automotive Components:Fuel vapor barrier layers for composite fuel tanks and battery enclosure seals.
- Aerospace Sealing:Pressure vessel membranes for satellite propulsion and aircraft emergency oxygen systems.
Construction insulation captures the steepest expansion trajectory as EU Green Deal embodied-carbon thresholds accelerate building envelope upgrades.
Installation Type:
Building physics requirements vary dramatically by envelope position, from hydrostatic pressure resistance below grade to UV stability for exposed roofing.
- Foundation Barriers:Radon and methane-blocking membranes for below-grade concrete slabs require puncture resistance exceeding 200N and lap-sealed joint integrity. Belgian and Austrian building codes now bundle membrane supply with 10-year ingress warranties, concentrating procurement among certified applicator networks rather than distributor stockists.
- Roofing Systems:Vapor control layers positioned above or below insulation per hygrothermal modeling outcomes. German contractors favor polyamide-reinforced membranes for standing seam metal roof assemblies where mechanical fastening demands tear propagation resistance.
- Wall Cladding:Rainscreen cavity membranes with variable vapor permeability.
- Flooring:Damp-proof membranes for screed protection over concrete substrates.
- Underground Structures:Tunnel and basement waterproofing with integrated drainage composites.
- Temporary Enclosures:Construction-phase weather protection with reusable tensioned membrane systems.
Foundation barriers hold the dominant specification volume, while roofing systems are expanding most quickly through Energieeffizienzhaus incentive programs.
End User:
Procurement authority is migrating from general contractors toward specialized installation firms with performance guarantee capabilities.
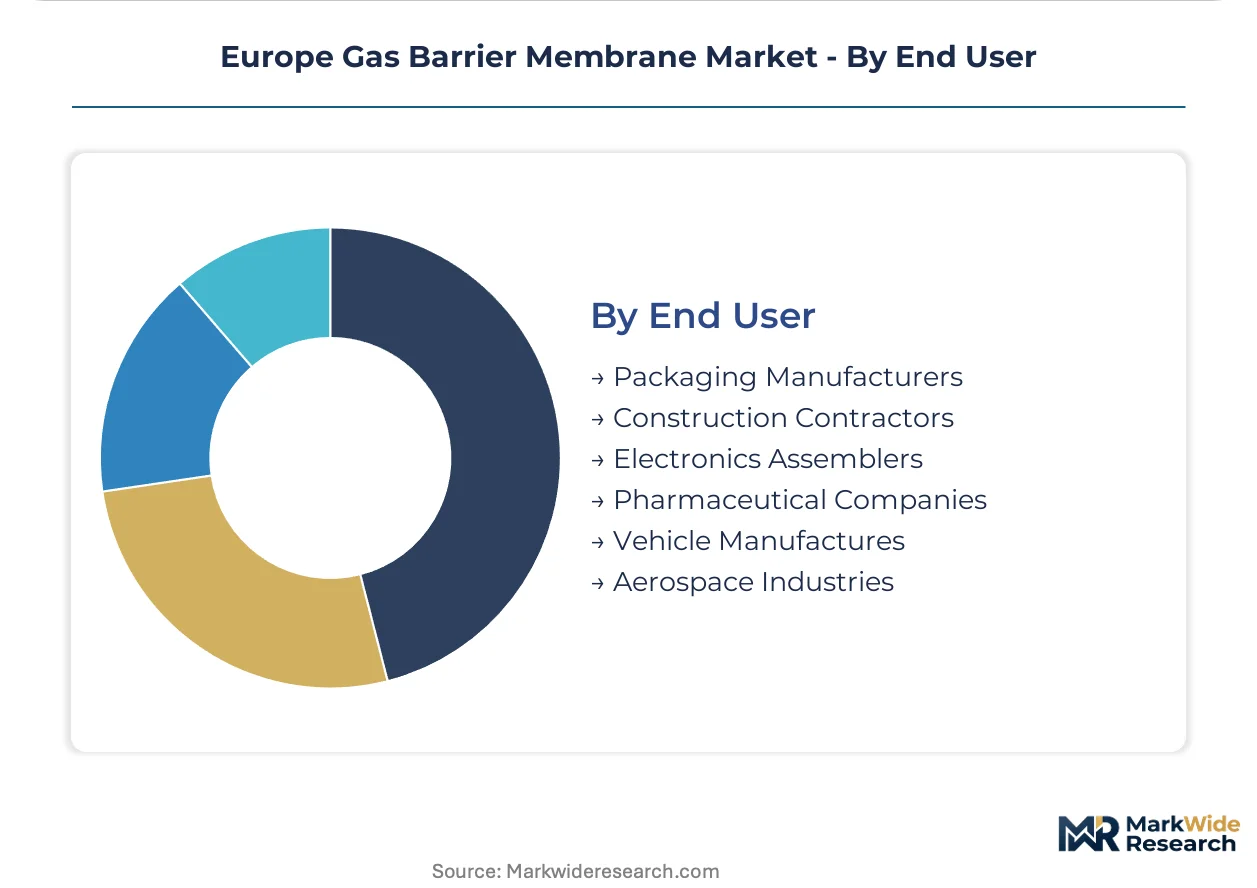
- Construction Contractors:Certified membrane applicators in Germany and France now control specification channels through bundled supply-and-install contracts with long-term warranty obligations. Delta Membranes leverages its UK distribution network to dominate below-grade waterproofing specification through contractor training and quality assurance protocols.
- Pharmaceutical Companies:Primary packaging qualification demands oxygen transmission rate consistency across temperature-humidity cycling that conflicts with construction-grade batch-to-batch variation tolerances. EMA stability testing guidelines create qualification barriers that favor suppliers with dedicated pharmaceutical production lines.
- Packaging Manufacturers:High-volume converters with continuous coextrusion assets.
- Electronics Assemblers:OLED and semiconductor fabs with cleanroom handling requirements.
- Vehicle Manufacturers:Tier-1 suppliers to German and French automotive OEMs.
- Aerospace Industries:Satellite prime contractors and aircraft pressure vessel specialists.
Construction contractors command the dominant procurement volume, while pharmaceutical companies are driving the fastest margin expansion through qualification-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Europe. German residential retrofits demand certified performance regardless of cost, while Polish and Romanian infrastructure programs prioritize specification compliance at competitive price points.
Germany
Energieeffizienzhaus federal renovation programs drive membrane specification for building envelope upgrades. The F-Gas Regulation phase-down accelerates metallized film adoption in cold chain logistics. Vacuum metallization capacity clusters in Bavaria and Baden-Württemberg serve pharmaceutical and electronics packaging demand.
France
Anah and ELAN law social housing frameworks mandate permeability declarations for insulation systems. ECHA restrictions on fluorinated polymer precursors redirect R&D toward polyamide alternatives. Industrial membrane conversion concentrates in the Hauts-de-France region near Lille.
United Kingdom
Below-grade waterproofing specifications increasingly bundle membrane supply with long-term warranties. CE marking under retained EU law maintains construction product compliance barriers. Specialist membrane applicator networks in the Midlands and Southeast England control procurement channels.
Netherlands
Pharmaceutical cold chain logistics demand sub-0.05 cc/m²/day transmission rates for biologics distribution. The CSRD polymer recycling mandate creates qualification advantage for suppliers with verified feedstock chains. Inline spectroscopic monitoring adoption concentrates near Eindhoven semiconductor fabrication clusters.
Poland
EU cohesion fund infrastructure programs specify membrane systems for first-time building envelope upgrades. REACH compliance timelines disadvantage non-European producers lacking notified body certification. Construction activity concentrates in Warsaw and Kraków metropolitan corridors.
Europe Gas Barrier Membrane Market Competitive Landscape
Capability concentration sits with specialized membrane applicators bundling installation with performance guarantees; scale advantage sits with diversified polymer converters serving multi-sector demand. The vendor base spans vertically integrated compounders, regional distribution specialists, and metallized film coaters with aerospace qualification. Strategic archetypes include backward-integrated polymer producers, certified installation networks, and precision metallization specialists. Competitive moves center on contractor certification programs and metallization capacity expansion.
Among UK-based specialists, Delta Membranes and A. Proctor Group Ltd occupy positions at opposite ends of the value chain. Delta Membranes exemplifies the distribution-anchored archetype leveraging specification channel control. A. Proctor Group Ltd represents backward-integrated compounders with captive polymer supply. Industrial Textiles & Plastics Ltd sits within the mid-tier converter segment serving construction and packaging overlap demand.
| Leading Market Players |
|---|
| Delta Membranes |
| Industrial Textiles & Plastics Ltd |
| Permagard Products Limited |
| Monarflex sro |
| A. Proctor Group Ltd |
| Newton Waterproofing |
| RIW Ltd |
| CETCO |
| Berry Global Inc. |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight rates from Rotterdam to Milan directly compress margins for metallized film converters in Bavaria, concentrating pricing power among southern German coaters while forcing Polish distributors to absorb logistics premiums or sacrifice specification tiers.
Pricing Analysis
Aftermarket service revenue from 10-year ingress warranties and remediation contracts now drives lifetime value for certified membrane applicators. Three-tier pricing structure across pharmaceutical-grade, construction-certified, and commodity packaging levels separates EMA-compliant laminates from CE-marked building envelope films from standard coextruded polyethylene. Cost compression in commodity polyethylene tiers is intensifying because REACH fluorinated precursor restrictions force reformulation investments. Pharmaceutical companies exhibit the least price sensitivity, while Polish infrastructure contractors demand specification compliance at competitive price points.
Supply Chain Analysis
Upstream polyamide and metallized polyester feedstock production clusters in Germany, Italy, and the Netherlands. Raw material dependencies center on caprolactam for nylon 6, aluminum ingots for vacuum deposition, and ethylene-vinyl alcohol copolymers for high-barrier laminates. Single-source vulnerability runs through southern German vacuum metallization capacity serving electronics-grade specifications. Distribution runs through certified contractor networks rather than distributor stockists for below-grade and roofing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through CE marking and EMA qualification protocols creates defensive moats that compound over successive approval cycles, locking out non-European competitors and anchoring incumbent pricing power.
For Market Incumbents: Pre-empt qualification pipeline congestion by accelerating metallized film capacity expansion in Bavaria before F-Gas Regulation phase-down tightens refrigerant containment standards. Anchor backward integration into polymer compounding to secure caprolactam supply consistency for aerospace sealing grades. Counter emerging Polish and Romanian specification channels by embedding certified applicator training programs ahead of EU cohesion fund disbursement peaks. For New Entrants and Emerging Players: Pursue Polish and Romanian construction markets where EU cohesion fund infrastructure programs specify membrane systems for first-time building envelope upgrades. Target contractor certification partnerships in Warsaw and Kraków metropolitan corridors where REACH compliance timelines disadvantage non-European producers lacking notified body certification. Lead with bundled supply-and-install contracts featuring 10-year ingress warranties to displace commodity product bidding. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated compounders with captive polymer supply and dedicated pharmaceutical production lines over distribution-anchored specialists. Long-term viability hinges on CSRD-aligned post-industrial polyamide feedstock chains and inline spectroscopic quality verification capabilities. Monitor ECHA enforcement actions on hydrofluorocarbon quotas as inflection indicator for metallized pouch demand acceleration in vaccine distribution networks.| Strategic Initiative | Industry Significance |
|---|---|
| Metallization Capacity Expansion | Bavarian vacuum deposition additions serve Dutch pharmaceutical cold chain and Finnish semiconductor demand. |
| Backward Integration into Polymer Compounding | In-house caprolactam production secures raw material consistency for EMA stability testing compliance. |
| Certified Contractor Network Development | Training programs in Poland and Romania capture EU cohesion fund specification channels. |
| Post-Industrial Feedstock Verification | CSRD-aligned polyamide recycling chains create first-mover advantage in sustainability reporting. |
| Inline Spectroscopic Quality Systems | Real-time permeability certificates displace destructive batch testing for electronics-grade films. |
Research Methodology
Cross-validation between primary interviews with membrane applicators, polymer compounders, and pharmaceutical packaging engineers and secondary validation through EMA stability testing guidelines, REACH restriction updates, and CE marking databases anchors the qualitative findings. Bottom-up triangulation against customs data for polyethylene and polyamide trade flows and top-down reconciliation with EU Green Deal embodied-carbon threshold documentation complete the data architecture.
Calibration against historical qualification timeline patterns and metallization capacity utilization rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, installation method, end-user certification standards, and regional regulatory cluster. CAGRs derive from installed base growth in German residential retrofits and French public housing schemes, cross-checked against pharmaceutical cold chain logistics expansion and electronics protection demand.
Sensitivities concentrate around F-Gas Regulation phase-down acceleration, ECHA enforcement intensity on fluorinated precursors, and EU cohesion fund disbursement timing for eastern member state construction programs. Cross-checking against Cefic polymer production statistics and EMA primary packaging qualification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
Global Spiral Membrane Market
Membrane Materials
Spiral Wound Membrane Market
Membrane Materials
Oxygen Barrier Materials Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Global Gas Separation Membranes Market