
 North America Transparent Conductive Films Market | 2026-2036
North America Transparent Conductive Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America Transparent Conductive Films Market Analytics
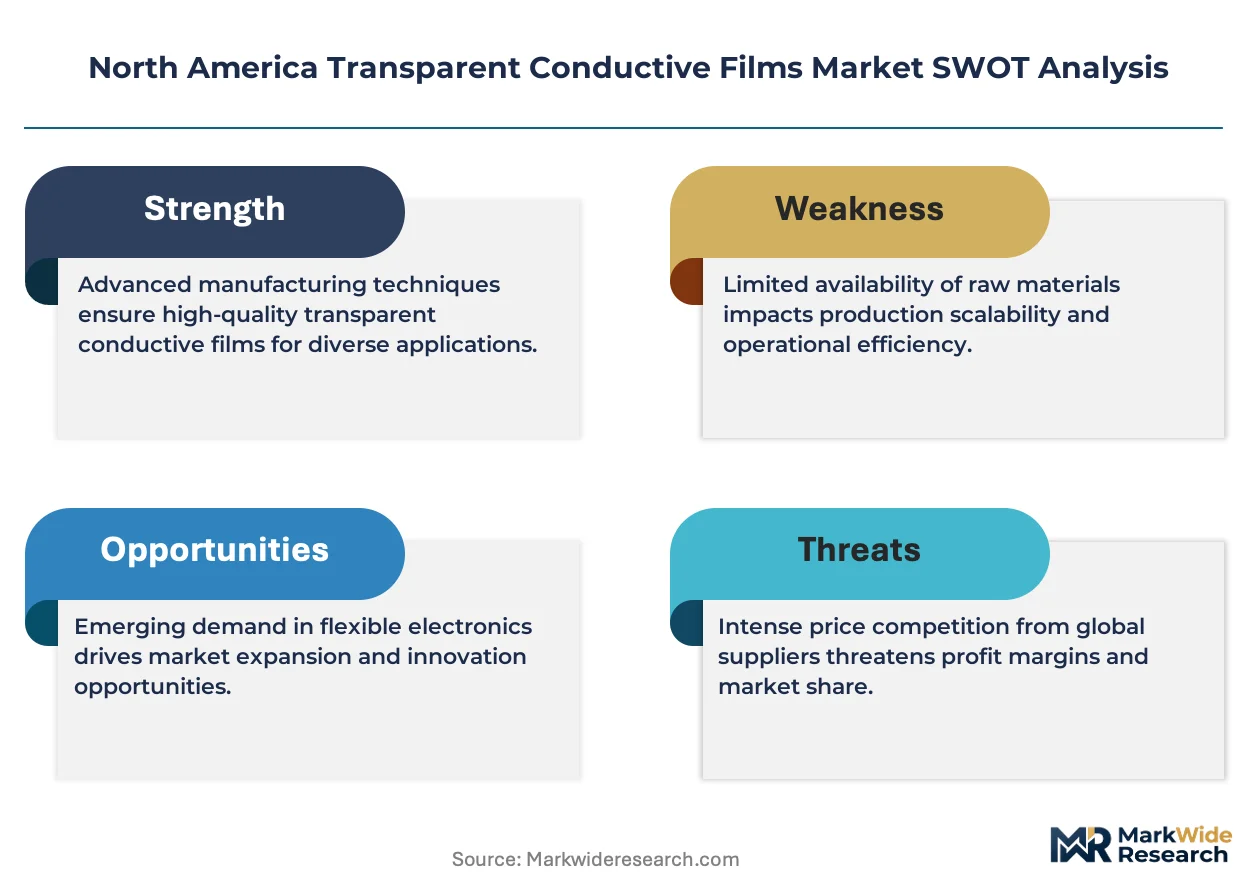
A shift from single-source ITO supply toward multi-source silver nanowire and graphene procurement is restructuring procurement strategies across the value chain. 3M Company leverages its materials science portfolio to sustain dominance in optically clear adhesive-integrated film systems. DuPont de Nemours anchors its position through specialty polymer substrates that compete with traditional glass-based conductors. Cambrios Technologies differentiates via wet-processed silver nanowire inks that occupy niche flexible display segments.
Transparent conductive films are optically clear, electrically conductive substrates typically fabricated from indium tin oxide sputtered onto polyethylene terephthalate or glass, with sheet resistances ranging from 10 to 500 ohms per square depending on application requirements. These films enable capacitive touch sensing, electromagnetic shielding, and transparent electrode functions in displays and photovoltaic devices. ITO films still lead volume shipments across the region, though silver nanowire films represent the fastest-growing product category as foldable device architectures displace rigid form factors. Flexible electronics applications command premium positioning within the value chain, while solar cell integration remains a mature, price-sensitive segment where conductive polymers are gaining technical traction.
FCC electromagnetic compatibility standards and EPA hazardous waste regulations for indium processing shape material selection and manufacturing location decisions across the region. OSHA workplace exposure limits for nanomaterial handling add compliance costs to silver nanowire production facilities in the United States. Stakeholders must monitor how NHTSA automotive safety standards for in-vehicle display durability will redefine performance thresholds for transparent conductors in next-generation cockpit interfaces.
Market Dynamics
Silver nanowire ink deposition is automating production lines across Michigan and Ohio automotive corridors, compressing cycle times while EPA hazardous waste regulations for indium processing force material substitution decisions.
Growth Catalysts
- Automotive Dashboard Integration:Flexible electronics adoption in next-generation cockpit interfaces is pulling film procurement into high-volume manufacturing corridors.
- EPA Emissions Standards:Tightening specifications for display manufacturing equipment are accelerating cleaner material qualification timelines.
- Mexico Electronics Cluster Expansion:Guanajuato's scaling touch panel assembly lines are concentrating regional demand for high-throughput film supply.
Market Restraints
- Indium Supply Concentration:Geographic concentration of primary indium refining creates price volatility exposure for ITO-dependent fabricators.
- OSHA Nanomaterial Compliance:Workplace exposure limits for silver nanowire handling add facility-level costs to US production sites.
- Sheet Resistance Trade-offs:Graphene films face technical limitations achieving sub-100 ohm-per-square performance without multilayer stacking.
Strategic Opportunities
- Foldable Device Architectures:Mechanical stress-tolerant silver nanowire networks are opening premium positioning in emerging flexible smartphone segments.
- NHTSA Safety Mandates:Automotive durability standards for in-vehicle displays are creating certified supplier preference windows.
- Solar Cell Conductive Polymers:Price-sensitive photovoltaic integration represents underpenetrated volume potential against incumbent ITO.
Industry Challenges
- Wet-Processing Expertise Gap:Silver nanowire ink formulation and coating precision requires specialized technical talent scarce in legacy ITO sputtering facilities.
- FCC Certification Timelines:Electromagnetic compatibility testing for new film compositions extends product launch cycles by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Transparent Conductive Films Market |
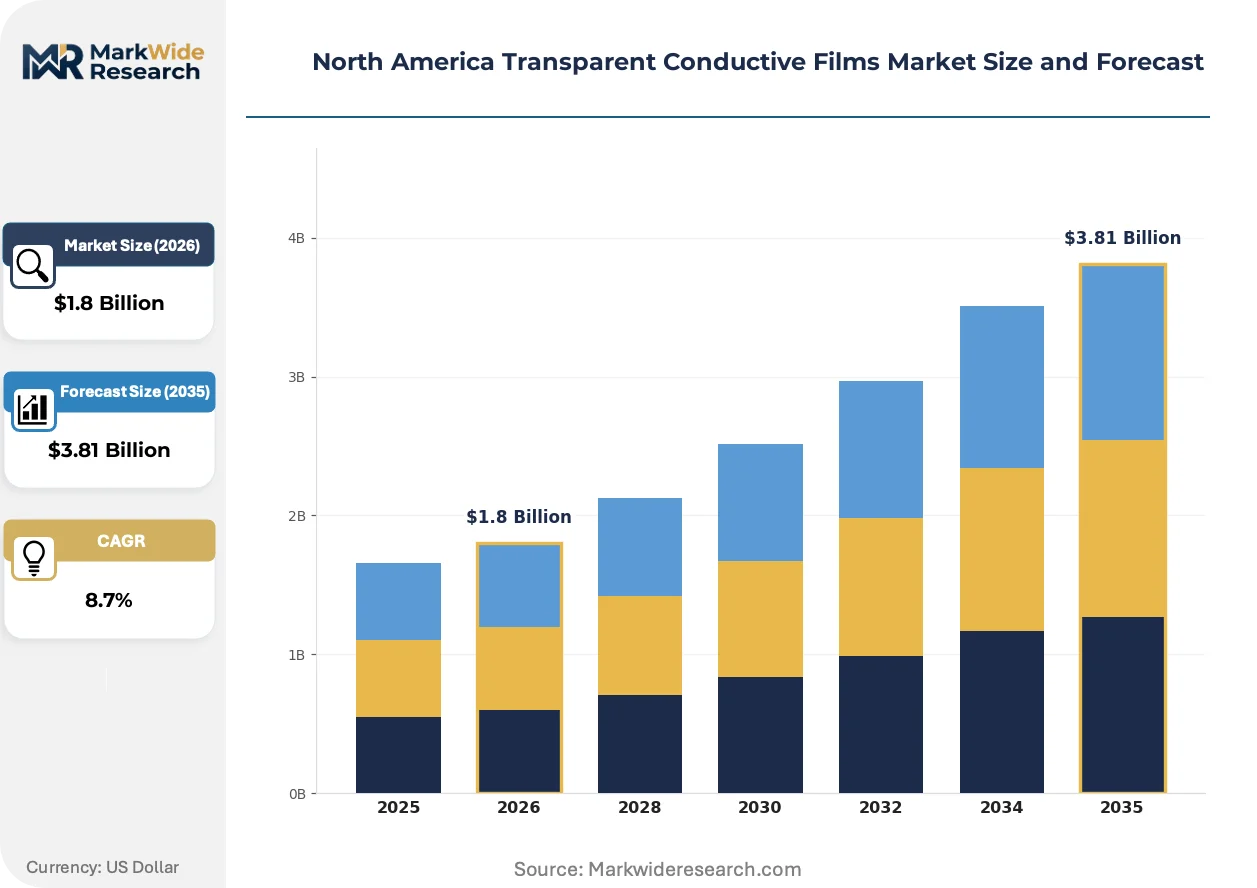
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ITO Films, Graphene Films, Silver Nanowire Films, Conductive Polymers Application: Touch Screens, Solar Cells, OLED Displays, Flexible Electronics End User Industry: Consumer Electronics, Automotive, Aerospace, Healthcare Form Factor: Flexible Sheets, Rigid Panels, Roll-to-Roll, Coatings |
| Companies Covered | 3M Company, DuPont de Nemours, Inc., TE Connectivity Ltd., Nitto Denko Corporation, Cambrios Technologies Corporation, TDK Corporation, Teijin Limited, AGC Inc., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Transparent Conductive Films Market Evolving Landscape
Wet-processed deposition systems are reshaping manufacturing economics while regulatory pressure on indium waste streams accelerates alternative material validation.
Roll-to-roll slot-die coating with silver nanowire inks is automating throughput in flexible electronics fabrication. Tier-one automotive suppliers in Michigan and Ohio are adopting these lines at accelerated capital deployment cycles. The technology is automating labor-intensive steps that previously constrained capacity scaling.
EPA hazardous waste regulations for indium processing are tightening effluent standards at the point of sputtering target manufacturing. Fabricators face facility relocation or closed-loop recycling capital commitments. Display equipment OEMs in the United States are responding with dual-source material qualification programs.
Automotive procurement teams are consolidating film suppliers around NHTSA pre-certified durability tiers. Tier-one cockpit integrators are displacing fragmented spot-buying with multi-year supply agreements. This concentration is most visible in Michigan and Ohio where dashboard production volumes anchor regional demand.
North America Transparent Conductive Films Market Segmentation
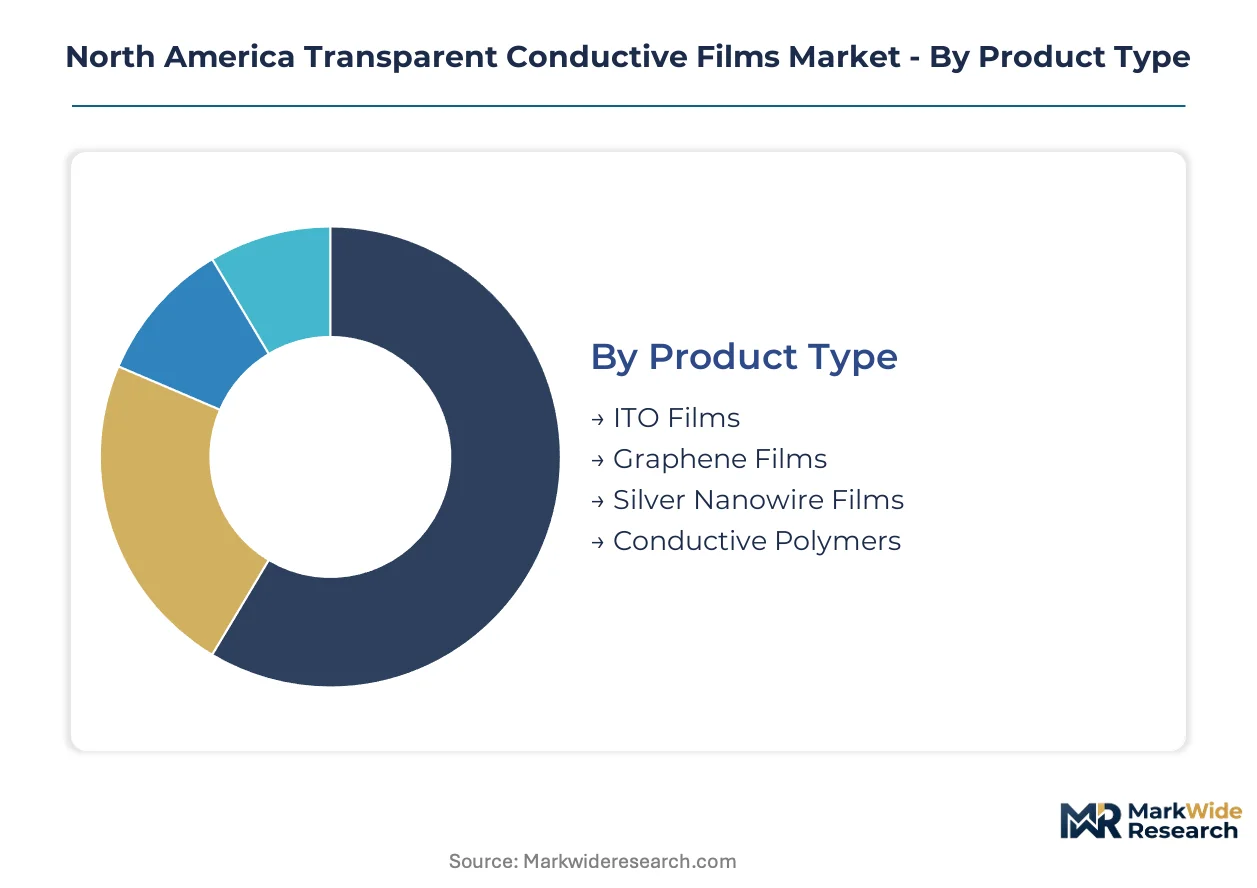
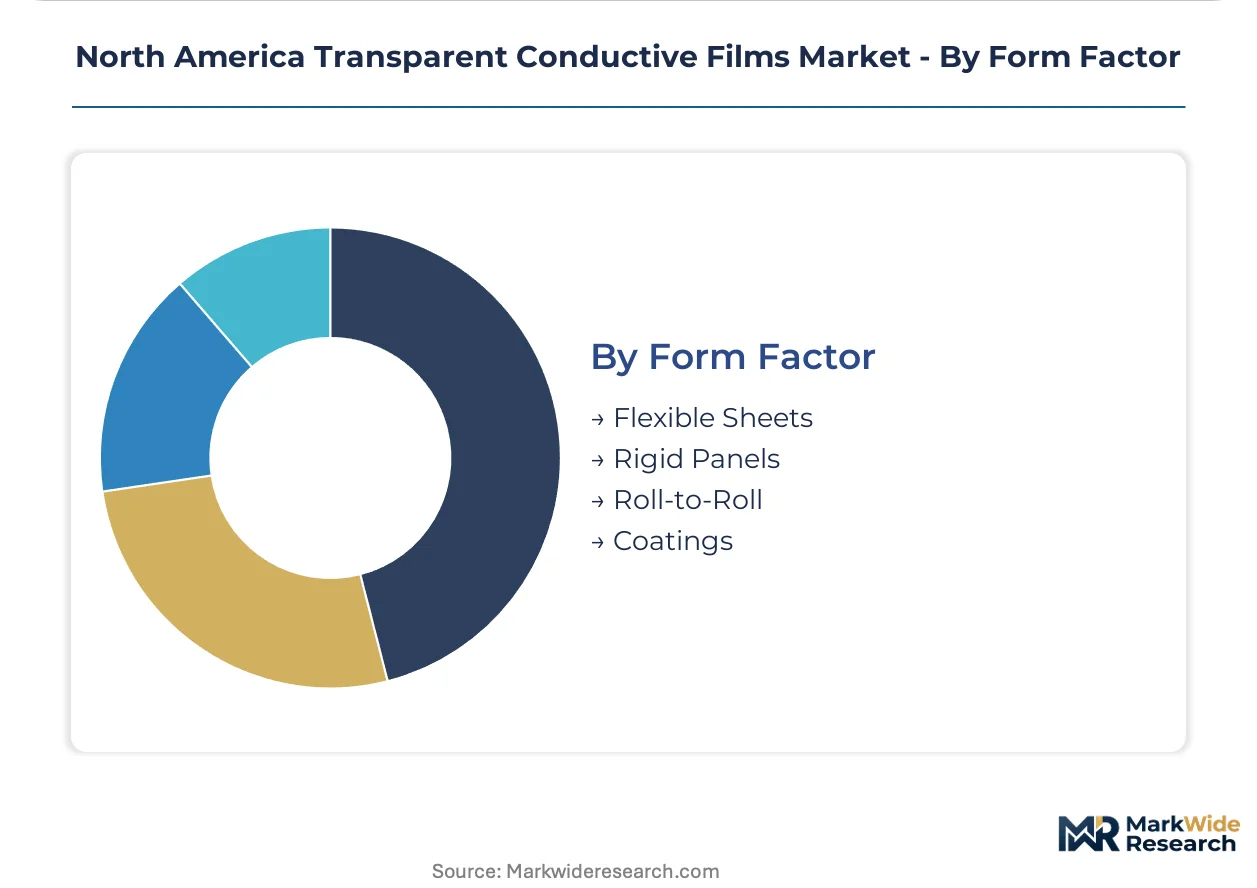
Transparent conductive films fragment across material chemistry, mechanical form, and end-use performance requirements. Procurement teams configure specifications differently for automotive durability mandates versus consumer electronics cost targets. Each segmentation axis reveals distinct supply chain configurations and margin structures.
Product Type:
Customization intensity spans from commodity ITO sputtering to specialized nanomaterial formulation, with standardization highest in legacy glass-based deposition and lowest in emerging flexible alternatives.
- ITO Films:Sputtered indium tin oxide on polyethylene terephthalate or glass substrates delivers sheet resistances of 10-500 ohms per square. Demand concentrates in Mexico's Guanajuato electronics cluster where touch panel assembly lines source high-volume, price-sensitive supply for mature smartphone and tablet architectures.
- Silver Nanowire Films:Wet-processed networks of metallic nanowires enable sub-100 ohm-per-square conductivity with mechanical bend radii under 5mm. Michigan and Ohio automotive corridors are pulling procurement volumes for next-generation dashboard interfaces where NHTSA durability standards favor certified film suppliers.
- Graphene Films:Single or few-layer carbon sheets deposited via chemical vapor deposition or liquid-phase exfoliation. Technical limitations in achieving target sheet resistance without multilayer stacking constrain adoption in premium flexible display segments.
- Conductive Polymers:Organic conductors including PEDOT:PSS formulations processed from solution. Price-sensitive solar cell integration in southwestern US photovoltaic installations represents primary volume uptake against incumbent ITO.
Leading the category by volume: ITO Films. Expanding most quickly: Silver Nanowire Films.
Application:
Cost tier stratification separates premium positioning in foldable architectures from commoditized supply for static installations.
- Touch Screens:Capacitive sensing layers for smartphones, tablets, and automotive interfaces. Guanajuato's scaling assembly lines concentrate North American procurement for standard-format panels.
- Solar Cells:Transparent front electrodes for photovoltaic modules. Southwestern US utility-scale installations drive volume demand where conductive polymers compete on installed cost.
- OLED Displays:Anode layers requiring optical clarity and work function matching. Premium pricing attaches to thin-film encapsulation compatibility in next-generation television and monitor panels.
- Flexible Electronics:Bendable and stretchable circuits for wearable devices and conformable automotive surfaces. Silver nanowire networks capture share fastest as foldable smartphone architectures displace rigid form factors.
Touch Screens anchor volume shipments. Flexible Electronics gain share fastest on mechanical stress tolerance requirements.
End User Industry:
Customer type differentiation separates automotive durability certification from consumer electronics refresh cycles.
- Consumer Electronics:Smartphones, tablets, laptops, and wearable devices requiring optical clarity and touch responsiveness. Mexico's electronics cluster serves as primary supply destination for high-volume, short-lead-time procurement.
- Automotive:Dashboard displays, center consoles, and mirror-integrated screens. Michigan and Ohio manufacturing corridors are consolidating supplier relationships around NHTSA pre-certified film tiers.
- Aerospace:Cockpit displays and cabin entertainment systems demanding electromagnetic interference shielding. FCC certification timelines extend product qualification cycles for specialized film compositions.
- Healthcare:Medical monitors, diagnostic equipment interfaces, and wearable biosensors. FDA device regulations shape material biocompatibility requirements distinct from commercial electronics standards.
Consumer Electronics commands highest shipment volumes. Automotive is climbing fastest on cockpit digitization mandates.
Form Factor:
Supply concentration varies from capital-intensive roll-to-roll coating to discrete panel processing.
- Flexible Sheets:Thin-film substrates capable of bending and conforming to curved surfaces. Silver nanowire deposition on these formats enables foldable device architectures.
- Rigid Panels:Glass-based conductors for static installations. ITO sputtering dominates this mature segment with established supply chains.
- Roll-to-Roll:Continuous web processing enabling high-throughput coating. Tier-one automotive suppliers in Michigan and Ohio are automating these lines to compress cycle times.
- Coatings:Direct deposition onto device substrates or cover lenses. Wet-processed silver nanowire inks enable this format for integrated manufacturing flows.
Flexible Sheets lead by application breadth. Roll-to-Roll is gaining fastest on throughput automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in automotive manufacturing corridors and electronics assembly clusters across three distinct national markets. Each jurisdiction applies unique regulatory pressures that reshape material qualification and supplier certification timelines.
United States
Automotive dashboard digitization pulls film procurement into Michigan and Ohio manufacturing corridors where tier-one cockpit integrators consolidate supply agreements. EPA hazardous waste regulations for indium processing tighten effluent standards at sputtering target facilities, forcing closed-loop recycling capital commitments. OSHA workplace exposure limits for nanomaterial handling add facility-level compliance costs to silver nanowire production sites in these states.
Mexico
Guanajuato's scaling touch panel assembly lines concentrate North American procurement for high-volume smartphone and tablet architectures. The country's electronics cluster benefits from nearshoring mandates that compress lead times for US consumer electronics brands. Local fabricators face pressure to align with EPA-aligned environmental standards as US parent companies enforce cross-border compliance protocols.
Canada
Health Canada regulates material biocompatibility for medical device interfaces using transparent conductive films in diagnostic equipment and wearable biosensors. Ontario-based electronics manufacturers serve as secondary supply nodes for automotive and healthcare applications. Provincial clean technology incentives support pilot production of graphene-based conductors for specialized aerospace and research instrumentation.
North America Transparent Conductive Films Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-one automotive suppliers automate roll-to-roll coating lines across Michigan and Ohio. The vendor base stratifies into three tiers: diversified materials conglomerates with adhesive-substrate integration capabilities, specialty chemical firms anchoring polymer substrate alternatives, and nanomaterial specialists commercializing wet-processed deposition systems. Strategic partnerships between film fabricators and display equipment OEMs accelerate dual-source qualification programs. Geographic expansion into Mexico's Guanajuato cluster represents a second competitive vector as suppliers chase automotive and consumer electronics procurement consolidation.
Among materials science conglomerates, 3M Company and DuPont de Nemours occupy positions exemplifying integrated adhesive-film and polymer substrate archetypes respectively. Cambrios Technologies represents the nanomaterial specialist tier focused on wet-processed silver nanowire systems. These three anchors illustrate the competitive tension between legacy ITO supply chains and emerging flexible electronics architectures.
| Leading Market Players |
|---|
| 3M Company |
| DuPont de Nemours, Inc. |
| TE Connectivity Ltd. |
| Nitto Denko Corporation |
| Cambrios Technologies Corporation |
| TDK Corporation |
| Teijin Limited |
| AGC Inc. |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
NHTSA pre-certified durability mandates for automotive cockpit displays are compressing supplier qualification timelines and forcing procurement teams to consolidate around fewer certified film sources. This buyer consolidation concentrates pricing power with incumbent suppliers who have already navigated the certification gauntlet, while tier-one automotive integrators in Michigan and Ohio absorb premium positioning for compliant supply.
Pricing Analysis
Volume shipments of ITO films for Guanajuato touch panel assembly lines run on thin margins, while silver nanowire supply for NHTSA-certified automotive applications commands substantial premiums. Pricing stratifies across NHTSA certification tier, volume commitment scale, and wet-processing technical capability. Cost compression in commodity ITO intensifies as EPA hazardous waste regulations elevate closed-loop recycling capital requirements. Solar cell integrators in the southwestern United States exhibit highest price sensitivity, whereas automotive cockpit suppliers prioritize durability certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one automotive demand in Michigan and Ohio, while distributor networks serve fragmented consumer electronics procurement in Mexico's Guanajuato cluster. Raw material supply draws from indium refining concentrated in China, silver nanowire precursor chemicals from South Korea and Japan, and PET substrate from domestic chemical producers. Single-source vulnerability in primary indium refining creates price volatility exposure for ITO-dependent fabricators. Distribution runs through regional film converters who slit master rolls to customer-specified formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver nanowire wet-processing capacity scarcity props pricing premiums for automotive-certified supply, creating a supply-constrained environment where qualified output fails to match procurement demand from cockpit digitization programs.
For Market Incumbents: Hedge against indium supply volatility by accelerating dual-source qualification of silver nanowire and graphene alternatives. Secure captive supply of optically clear adhesive substrates through backward integration into polymer film manufacturing. EPA regulatory tightening on hazardous waste streams threatens legacy ITO sputtering economics, making nanomaterial deposition expertise the priority capability anchor.
For New Entrants and Emerging Players: Tier-two automotive suppliers in Michigan and Ohio represent the most penetrable channel entry point for uncertified film sources seeking NHTSA qualification partnerships. Solar cell conductive polymer supply in southwestern US utility installations offers white-space volume against entrenched ITO incumbents. A joint development agreement with established roll-to-roll coating houses accelerates technical credibility without capital-intensive facility buildout.
For Investors and Strategic Acquirers: The window for entry favors wet-processed nanomaterial specialists with existing automotive qualification relationships over greenfield ITO sputtering plays. Long-term viability hinges on foldable device architecture proliferation and automotive cockpit digitization sustaining premium pricing for mechanical stress-tolerant conductors. Watch for NHTSA durability standard revisions as the signal indicating certification barrier height and incumbent pricing power durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Silver Nanowire Capacity Expansion | Automotive procurement consolidation in Michigan and Ohio demands qualified supply scale. |
| Backward Integration into PET Substrates | DuPont and Eastman Chemical captive supply advantages pressure independent film converters. |
| NHTSA Pre-Certification Investment | Tier-one cockpit integrators consolidate supply agreements around certified durability tiers. |
| Closed-Loop Indium Recycling | EPA hazardous waste regulations force capital commitments at sputtering target facilities. |
| Roll-to-Roll Automation Deployment | Slot-die coating compression of cycle times enables high-throughput automotive contract capture. |
Research Methodology
Document review covered SEC 10-K filings of materials science conglomerates, EPA enforcement actions on indium processing facilities, and NHTSA regulatory dockets on automotive display safety standards, complemented by interviews with plant managers at Michigan and Ohio automotive film coating facilities, procurement leads at Guanajuato touch panel assembly lines, technical R&D directors at silver nanowire ink formulators, and distribution channel partners serving the southwestern US solar installation market. Secondary validation drew from customs/trade data on indium and silver precursor imports, ACC chemical industry reports, and FCC electromagnetic compatibility certification databases. Bottom-up capacity assessments and top-down demand aggregation were triangulated to establish market sizing.
Cross-referencing historical shipment patterns against panel input from tier-one automotive suppliers and consumer electronics OEMs anchored the analytical framework. Segmentation modeling covered material chemistry, mechanical form factor, end-use application, and customer industry vertical across the projection horizon. CAGRs were derived from regression analysis of procurement volume trends and capital deployment cycles in roll-to-roll coating automation. Industry-specific forecast inputs included EPA regulatory timeline assumptions for indium waste stream compliance and NHTSA durability standard revision probabilities.
Caveats apply where EPA enforcement intensity on hazardous waste regulations, NHTSA automotive safety standard revisions, or silver nanowire manufacturing yield improvements could materially shift the outlook for material substitution timelines and certified supplier economics. Forecasts reflect documented assumptions about regulatory trajectory and technology cost curves. Periodic stress-testing of base assumptions against actual certification timeline outcomes and automotive platform launch schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Polysulfone Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Nanofiltration Membrane Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Membrane Chemicals Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
PVDF Membrane Market