
 Spiral Wound Membrane Market | 2026-2036
Spiral Wound Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Spiral Wound Membrane Market Analytics
ISO 9001 quality management certification is reorganizing competitive access in the spiral wound membrane sector, raising barriers for unqualified suppliers. DuPont sustains technology leadership through proprietary polyamide thin-film composite chemistry. Toray Industries dominates Japanese supply chains with vertically integrated polymer production. Pentair navigates North American municipal procurement through NSF/ANSI 61 certified product lines.
Spiral wound membranes consist of flat-sheet membrane material enveloped around a permeate collection tube, wound with feed-channel spacers to create a compact cylindrical module typically rated for pressures from 150 to 1,200 psi depending on application class. Reverse osmosis configurations command premium positioning in seawater desalination installations where salt rejection rates exceed 99.5 percent. Nanofiltration segments capture growing share in industrial softening and selective ion removal applications. Pressure driven technology leads unit shipments while membrane bioreactor integration in wastewater recycling represents the fastest-expanding technology pairing.
EPA Safe Drinking Water Act amendments and EU REACH chemical registration requirements shape material selection and manufacturing disclosure obligations across major supply regions. China's MEE enforces stricter wastewater discharge limits that accelerate membrane replacement cycles in industrial facilities. ISO 14001 environmental management standards increasingly gate supplier qualification for multinational engineering firms. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate certification burden shifts and localize production accordingly.
Market Dynamics
EPA Safe Drinking Water Act compliance mandates are forcing municipal water treatment utilities across the United States to accelerate membrane-based filtration capacity expansions, while China's MEE wastewater discharge limits compress industrial replacement cycles in parallel.
Growth Catalysts
- Desalination infrastructure:China's coastal provinces are integrating reverse osmosis spiral wound modules into large-scale seawater desalination projects. The technology addresses freshwater scarcity in dense population corridors.
- REACH chemical registration:EU disclosure obligations are filtering out non-compliant membrane chemistries from European supply chains. Qualified suppliers gain preferential access to industrial procurement.
- Membrane bioreactor pairing:Wastewater recycling facilities are combining spiral wound membranes with biological treatment. This hybrid approach reduces footprint and improves effluent quality for discharge or reuse.
Market Restraints
- Polyamide feedstock concentration:Thin-film composite chemistry relies on specialized aromatic polyamide intermediates. Supply bottlenecks in Asian polymer production create input cost volatility.
- Pressure rating limitations:Standard spiral wound modules top out around 1,200 psi. High-salinity brine applications require energy-recovery device pairing, adding system complexity.
- NSF/ANSI 61 certification timelines:North American municipal procurement gates on drinking water contact certification. Testing protocols extend qualification cycles by 12-18 months for new entrants.
Strategic Opportunities
- Industrial softening pivot:Nanofiltration segments are capturing selective ion removal applications previously served by chemical precipitation. Metal finishing and food processing facilities drive pilot adoption.
- ISO 14001 gating:Multinational engineering firms are requiring environmental management certification for supplier qualification. Early certifiers capture preferred vendor status in EPC contracts.
- Feed-channel spacer innovation:Advanced spacer geometries reduce fouling rates and extend cleaning intervals. Module manufacturers integrating proprietary designs differentiate on total cost of ownership.
Industry Challenges
- Membrane fouling expertise gap:Operating high-rejection reverse osmosis systems requires specialized knowledge of pretreatment chemistry and cleaning protocols. Utilities struggle to retain trained technicians.
- Legacy infrastructure integration:Brownfield water treatment plants face spatial constraints and pressure-vessel incompatibility when retrofitting spiral wound modules. Custom engineering adds project cost and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spiral Wound Membrane Market |
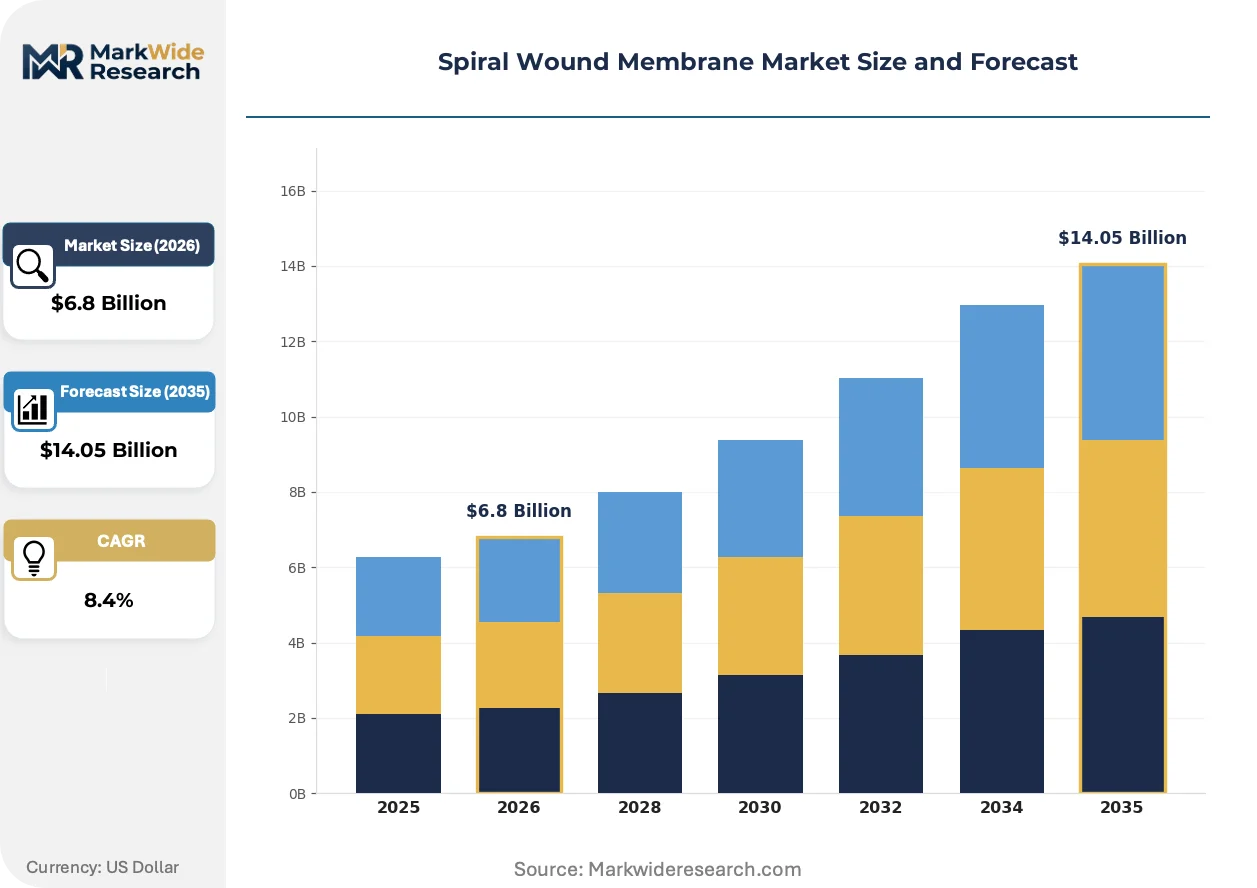
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Nanofiltration, Ultrafiltration, Microfiltration End User: Municipal Water Treatment, Industrial Wastewater Treatment, Food & Beverage, Pharmaceuticals Application: Desalination, Water Purification, Wastewater Recycling, Cooling Water Treatment Technology: Membrane Bioreactors, Pressure Driven, Gravity Driven, Thermal Recovery |
| Companies Covered | Nitto Denko, Koch Separation Solutions, DuPont, Pentair, Alfa Laval, Toray Industries, LG Chem, Toyobo, SUEZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spiral Wound Membrane Market Evolving Landscape
Material science advances and regulatory disclosure requirements are fragmenting competitive positioning across the spiral wound membrane sector, while procurement behavior shifts toward lifecycle cost evaluation rather than upfront module pricing.
Graphene oxide nanocomposite coatings are fragmenting the surface modification landscape for spiral wound membranes. Desalination plant operators in the Middle East are piloting these materials for enhanced chlorine tolerance. The technology is fragmenting traditional polyamide-dominated supply relationships as specialty chemical firms enter the membrane modification value chain.
EU REACH chemical registration requirements are reshaping material selection protocols for membrane manufacturers serving European industrial markets. Substances of very high concern screening now extends to monomers and additives used in thin-film composite production. Nanofiltration product lines face reformulation pressure as certain cross-linking chemistries face authorization sunset dates.
Lifecycle cost modeling is displacing unit-price procurement in municipal water treatment contracts. Engineering procurement construction firms are bundling membrane replacement schedules, chemical consumption forecasts, and energy modeling into 10-15 year service agreements. California water districts pioneered this approach; Texas and Arizona utilities are replicating the structure in recent tenders.
Spiral Wound Membrane Market Segmentation
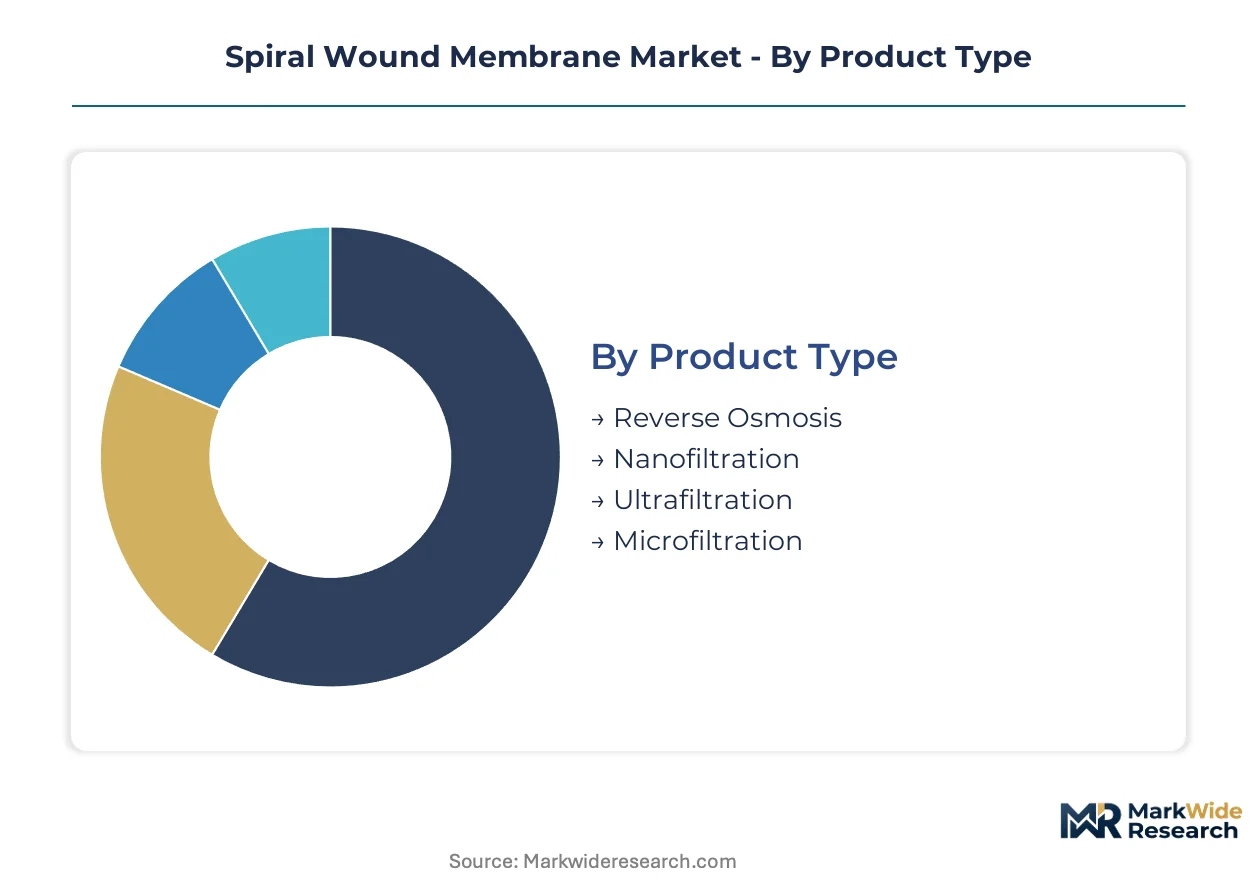
Segmentation in spiral wound membranes reveals how substitution pressures and application-specific performance requirements fragment procurement behavior. Technology choices cascade through end-use specifications, creating distinct competitive arenas with divergent margin structures and certification barriers.
Product Type:
Substitution threats intensify where nanofiltration encroaches on reverse osmosis territory in industrial softening, while ultrafiltration and microfiltration face commoditization from hollow fiber alternatives.
- Reverse Osmosis:Thin-film composite polyamide chemistry achieves salt rejection above 99.5 percent. Seawater desalination plants in China's coastal provinces specify these modules under MEE discharge compliance timelines. Fouling sensitivity and energy intensity constrain deployment in high-particulate feed waters.
- Nanofiltration:Selective ion removal via looser pore structure than reverse osmosis. Metal finishing facilities in Germany's industrial corridors pilot these systems to replace chemical precipitation under REACH substance restrictions. Divalent ion rejection drives adoption in food processing demineralization.
- Ultrafiltration:Pore size range of 0.01-0.1 microns targets macromolecular separation. Wastewater recycling facilities pair these with biological treatment.
- Microfiltration:0.1-10 micron pore rating handles suspended solids and bacteria. Pre-treatment stages in multi-barrier municipal systems deploy these modules.
Reverse osmosis anchors the volume base while nanofiltration gains share at the steepest rate.
End User:
Customer procurement sophistication varies sharply, with municipal utilities demanding lifecycle cost modeling and pharmaceutical buyers enforcing material traceability that industrial wastewater operators rarely match.
- Municipal Water Treatment:EPA Safe Drinking Water Act compliance mandates membrane-based filtration expansions across US utilities. California water districts pioneered 10-15 year service agreements bundling replacement schedules and energy modeling. NSF/ANSI 61 certification gates market access with 12-18 month qualification cycles.
- Industrial Wastewater Treatment:China's MEE wastewater discharge limits compress replacement cycles in chemical and textile clusters. Operating expertise gaps in high-rejection system chemistry constrain uptake among smaller facilities.
- Food & Beverage:Hygienic design standards and FDA food contact compliance shape module selection. Dairy processing and beverage demineralization drive specification.
- Pharmaceuticals:USP Class VI and extractables testing requirements elevate material documentation burdens. Purified water and WFI production systems specify high-integrity membranes.
Municipal water treatment commands the revenue concentration while industrial wastewater treatment climbs the fastest.
Application:
Geographic water stress patterns concentrate demand, with desalination infrastructure investments in coastal zones and wastewater recycling mandates in water-scarce inland regions.
- Desalination:Large-scale seawater reverse osmosis installations dominate capital deployment. Middle Eastern operators pilot graphene oxide nanocomposite coatings for enhanced chlorine tolerance.
- Water Purification:Municipal drinking water treatment and industrial process water preparation. Groundwater remediation with emerging contaminant concerns.
- Wastewater Recycling:Membrane bioreactor integration creates fastest-expanding technology pairing. Zero liquid discharge requirements in power generation and refining.
- Cooling Water Treatment:Side-stream filtration for scale and corrosion control. Thermal power plants and data centers drive specification.
Water purification retains the installed base while wastewater recycling expands most quickly.
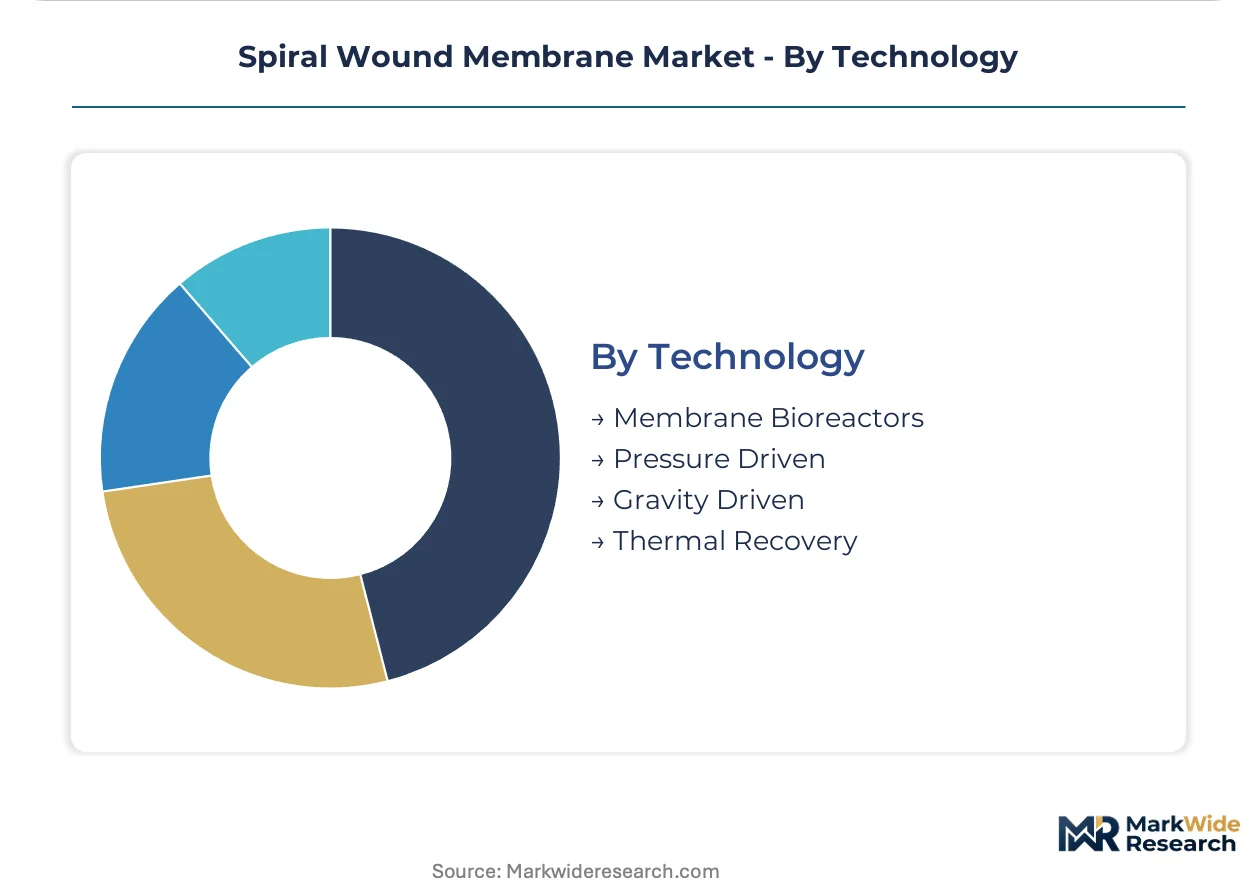
Technology:
Process intensification trends favor hybrid configurations, with pressure driven systems facing energy efficiency scrutiny and thermal recovery remaining niche due to capital intensity.
- Membrane Bioreactors:Biological treatment combined with membrane filtration reduces footprint and improves effluent quality. Wastewater recycling facilities specify these for discharge or reuse compliance.
- Pressure Driven:Dominant unit shipment category spanning reverse osmosis, nanofiltration, and ultrafiltration. Energy recovery device pairing required for high-salinity applications.
- Gravity Driven:Low-energy operation suited to pre-treatment and coarse filtration. Limited by flux rates and module sizing constraints.
- Thermal Recovery:Membrane distillation and related temperature-gradient processes. Concentrated brine and high-value product recovery applications.
Pressure driven technology anchors the volume base while membrane bioreactors gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao seawater desalination corridor underwrites China's commanding position in spiral wound membrane deployment, with coastal infrastructure scaling reverse osmosis capacity under freshwater scarcity pressures.
United States
California water districts bundle 10-15 year membrane service agreements combining replacement schedules with energy modeling. EPA Safe Drinking Water Act amendments drive municipal procurement across the Southwest. Texas utilities replicate California's lifecycle cost structures in recent tenders for brackish groundwater treatment.
China
Shandong and Jiangsu coastal provinces integrate reverse osmosis modules into large-scale desalination plants serving dense population corridors. MEE wastewater discharge limits compress industrial replacement cycles in chemical clusters. Tianjin's membrane manufacturing base supplies domestic project pipelines while exporting to Southeast Asian markets.
Germany
Industrial softening applications in the Ruhr Valley replace chemical precipitation with nanofiltration systems under REACH substance restrictions. ECHA authorization timelines for cross-linking chemistries pressure membrane reformulation. Bavarian food processing facilities specify selective ion removal for demineralization workflows.
Japan
Vertically integrated polymer production in Osaka-Kobe anchors domestic supply chain security for thin-film composite chemistry. METI water security directives accelerate membrane bioreactor adoption in industrial parks. Chubu region semiconductor fabs deploy high-purity water systems with stringent extractables documentation.
Saudi Arabia
Red Sea and Arabian Gulf desalination complexes pilot graphene oxide nanocomposite coatings for enhanced chlorine tolerance. NEOM infrastructure integrates membrane-based water recycling into zero-carbon city planning. Eastern Province petrochemical clusters specify zero liquid discharge configurations for brine management.
Spiral Wound Membrane Market Competitive Landscape
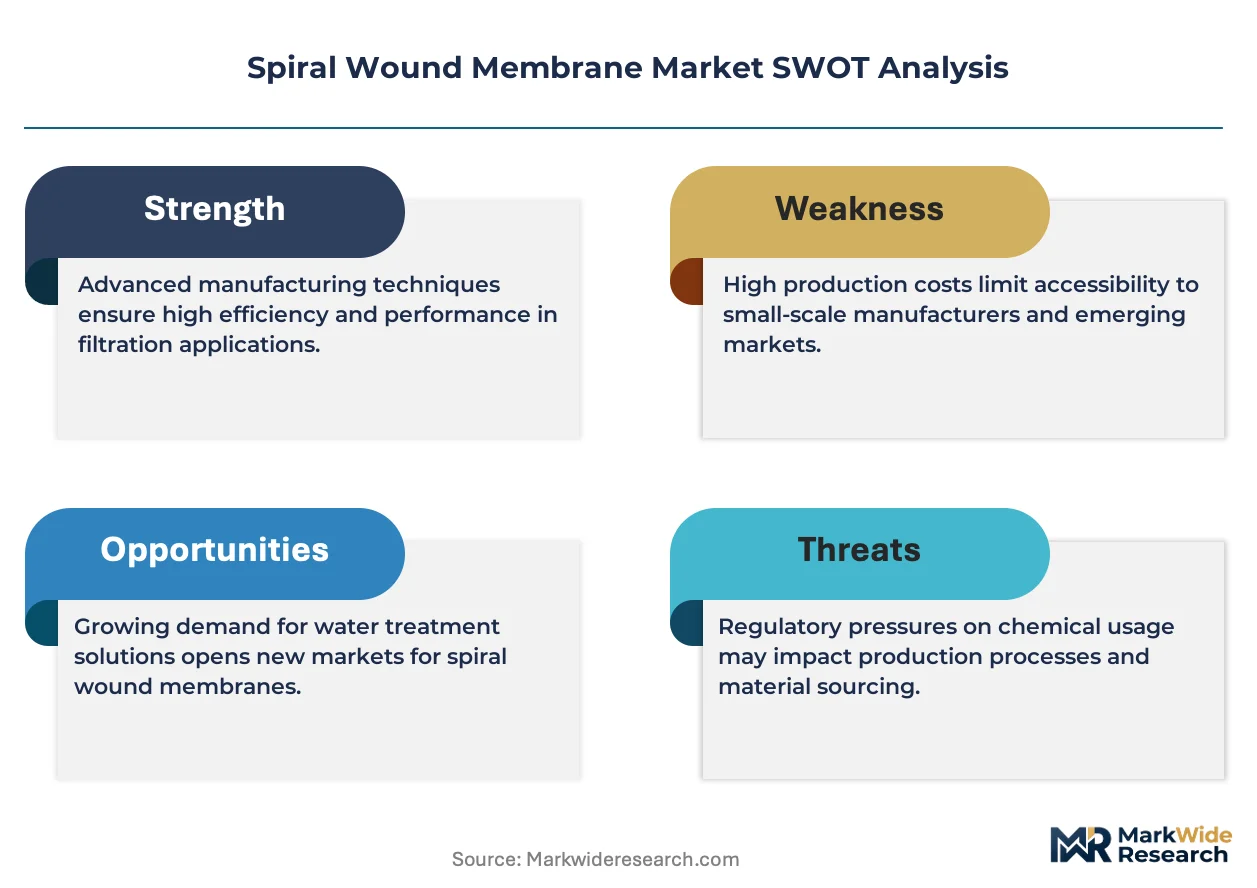
Listed leaders compete with private specialists across certification depth and geographic coverage, creating a tiered structure where scale advantages in polymer production clash with modular innovation from focused engineering houses. Three archetypes dominate: vertically integrated chemical conglomerates with captive resin supply, diversified filtration platforms serving municipal procurement channels, and membrane-specific fabricators concentrating on spacer geometry and surface modification patents. Competitive moves center on ISO 14001 environmental certification gating for multinational EPC contracts and feed-channel spacer innovation to extend cleaning intervals.
Within the chemical conglomerate tier, DuPont and Toray Industries exemplify upstream control over aromatic polyamide intermediates that thin-film composite chemistry requires. Pentair occupies a position in North American municipal procurement through NSF/ANSI 61 certified product lines. Koch Separation Solutions sits within the private specialist category, representing focused engineering capabilities without public market disclosure burdens.
| Leading Market Players |
|---|
| Nitto Denko |
| Koch Separation Solutions |
| DuPont |
| Pentair |
| Alfa Laval |
| Toray Industries |
| LG Chem |
| Toyobo |
| SUEZ |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month NSF/ANSI 61 certification timelines concentrate pricing power among established North American suppliers while compressing margins for aspirants navigating municipal procurement gates. This lead-time asymmetry reinforces tiered supply relationships where certified incumbents capture lifecycle service contracts and uncertified competitors remain trapped in spot-module transactions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with premium tiers commanding differential margins based on ISO 14001 environmental certification and extended warranty bundling. Price differentiation stems from thin-film composite chemistry grades and feed-channel spacer geometry patents. Cost compression in standard-tier reverse osmosis modules is intensifying because Chinese domestic manufacturers are expanding aromatic polyamide production capacity. Municipal water utilities exhibit the highest price sensitivity due to bond-financed capital constraints, while pharmaceutical buyers prioritize extractables documentation over unit cost.
Supply Chain Analysis
Aromatic polyamide intermediate production concentrates in Japan and China, creating single-source vulnerability for thin-film composite chemistry feedstock. Module assembly draws from specialized polymer production in Osaka-Kobe, membrane fabrication in Tianjin, and spacer manufacturing in South Korea. Tariff exposure on Chinese-manufactured modules threatens cost structures for North American municipal contractors. Distribution runs through engineering-procurement-construction firms bundling replacement schedules into decade-long service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spiral wound membrane market is recovering from a cyclical trough driven by deferred municipal capital expenditure during rate-setting delays. Replacement cycle compression under China's MEE discharge limits and EPA Safe Drinking Water Act amendments now restarts procurement velocity.
For Market Incumbents: Compound technology leadership through proprietary feed-channel spacer geometries that extend cleaning intervals and reduce total cost of ownership. Defend position against graphene oxide nanocomposite substitutes by accelerating chlorine-tolerance R&D partnerships with Middle Eastern desalination operators. Prioritize ISO 14001 certification depth to maintain preferred vendor status in multinational EPC contracts.
For New Entrants and Emerging Players: Aftermarket technical service for membrane fouling remediation represents an underserved layer where utilities struggle to retain trained technicians. Target industrial wastewater facilities in China's chemical clusters where MEE compliance deadlines compress replacement cycles and operating expertise gaps constrain incumbent service bandwidth. Pursue pilot-to-contract conversion programs bundling pretreatment chemistry consultation with module supply.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified filtration conglomerates seeking to divest non-core membrane assets amid portfolio rationalization. Long-term viability hinges on exposure to water-stressed geographies with regulatory enforcement credibility. Monitor NEOM infrastructure development and Saudi zero-liquid-discharge mandates as inflection indicators for premium module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Feed-Channel Spacer Patent Development | Proprietary geometries reduce fouling rates and differentiate on lifecycle cost in municipal tenders. |
| ISO 14001 Certification Acceleration | Environmental management certification gates supplier qualification for multinational EPC contracts. |
| Graphene Oxide Coating Partnerships | Pilot programs with Middle Eastern operators address chlorine tolerance limitations in polyamide chemistry. |
| Membrane Bioreactor Integration Programs | Hybrid biological-filtration configurations capture fastest-expanding technology pairing in wastewater recycling. |
| Regional Manufacturing Localization | Tianjin and Osaka-Kobe production bases mitigate tariff exposure and shorten qualification timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, MEE discharge compliance records, and ECHA substance authorization timelines. Primary interviews engaged membrane plant operators, municipal procurement officers, EPC contract managers, and thin-film composite chemists across China, the United States, Germany, and Japan. Secondary validation drew from customs trade data, NSF/ANSI certification registries, and engineering firm supplier qualification documents. Bottom-up module shipment estimates triangulate against top-down desalination capital expenditure tracking.
Segmentation dimensions modeled span product type (reverse osmosis, nanofiltration, ultrafiltration, microfiltration), end-use vertical (municipal water treatment, industrial wastewater, food and beverage, pharmaceuticals), application (desalination, water purification, wastewater recycling, cooling water treatment), and technology configuration (pressure driven, membrane bioreactor, gravity driven, thermal recovery). CAGRs derive from replacement cycle analysis, regulatory compliance deadline mapping, and capacity expansion pipeline tracking across coastal desalination corridors and inland water-scarce regions.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act amendments, EU REACH substance restrictions, and China's MEE discharge limits; material policy shifts would require re-modeling. Specific risks include polyamide feedstock price volatility, graphene oxide nanocomposite substitution acceleration, and municipal bond market disruption affecting capital expenditure timing. Practitioners should keep alternative scenarios live as graphene oxide pilot results and REACH authorization sunset dates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Polysulfone Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Nafion Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Global Ultrafiltration Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Global Membrane Chromatography Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market