
 Middle East Fluoropolymer Market | 2026-2036
Middle East Fluoropolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Fluoropolymer Market Insights
Advanced melt-processable fluoropolymer formulations is reconfiguring component fabrication across Middle East industrial zones, replacing conventional materials in high-temperature process equipment. AGC Inc. leverages its integrated fluorochemical supply chain to serve Saudi petrochemical complexes with tailored resin grades. Daikin Industries Ltd. anchors its regional position through technical service centers in Dubai and localized compounding partnerships. Solvay Group differentiates via specialty PFA and ETFE grades targeting the Emirates' aerospace maintenance, repair, and overhaul sector.
Fluoropolymers comprise carbon-fluorine bonded polymers such as PTFE, FEP, PFA, and ETFE, engineered for thermal stability up to 260°C, chemical inertness, and dielectric performance in aggressive process environments. PTFE dominates volume flows across Middle East chemical processing and refinery applications due to its established supply base and proven lining performance. ETFE represents the fastest-expanding product category, driven by membrane architecture projects in Qatar and the UAE where lightweight, UV-resistant cladding replaces conventional glazing systems. Cable insulation applications command premium pricing through nuclear-grade and offshore-certified product tiers serving Emirates and Saudi energy infrastructure.
Saudi Standards, Metrology and Quality Organization technical regulations align fluoropolymer product certification with Gulf Standardization Organization requirements, creating harmonized market access across GCC member states. SFDA and MOHAP pharmaceutical packaging standards in Saudi Arabia and the UAE respectively drive demand for high-purity PFA in bioprocessing equipment and containment systems. Stakeholders must monitor evolving EU REACH-equivalent chemical registration frameworks under GCC environmental cooperation initiatives, as these will reshape import compliance costs and local testing infrastructure requirements.
Market Dynamics
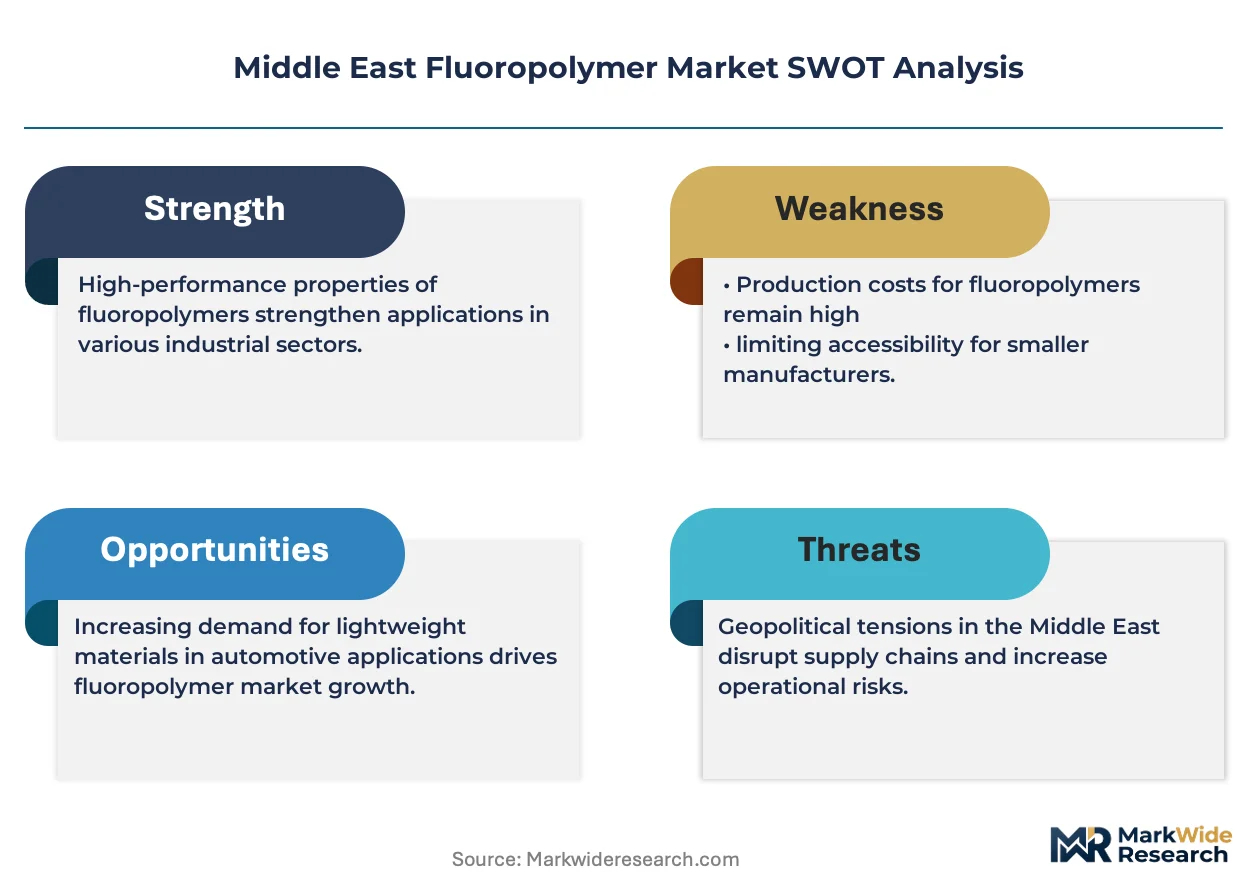
Saudi Arabia's industrial diversification under Vision 2030 is redirecting petrochemical capital toward advanced materials, compressing fluoropolymer qualification timelines as state-backed projects demand faster localization.
Growth Catalysts
- Gulf Standardization Organization harmonization:Unified technical regulations across GCC member states eliminate redundant certification cycles for fluoropolymer producers.
- Jubail and Yanbu industrial clusters:Concentrated specialty chemical production in these Saudi hubs generates localized demand for high-performance lining materials.
- Membrane architecture proliferation:ETFE cladding systems in Qatar and UAE mega-projects displace conventional glazing, opening new specification channels for fluoropolymer suppliers.
Market Restraints
- Fluorosurfactant feedstock concentration:Critical monomer supply chains concentrate in East Asian production bases, exposing Middle East compounders to shipping volatility.
- REACH-equivalent registration friction:Pending GCC chemical inventory frameworks will impose compliance costs on importers before local testing infrastructure matures.
- High-temperature ceramic substitution:Advanced oxide ceramics compete in select refinery applications where thermal cycling exceeds fluoropolymer mechanical limits.
Strategic Opportunities
- Bioprocessing equipment localization:SFDA pharmaceutical packaging standards drive demand for high-purity PFA in Saudi biologics manufacturing.
- Offshore cable certification tiers:Nuclear-grade and subsea-certified insulation products command premium positioning in Emirates energy infrastructure.
- Technical service center networks:Compounding partnerships and localized application engineering address Gulf buyers' demand for faster response times.
Industry Challenges
- Fluoropolymer welding technician scarcity:Specialized fusion welding for PFA and ETFE systems requires certification programs that regional vocational institutions have not yet scaled.
- Multi-standard compliance timelines:Simultaneous adherence to SASO technical regulations, GSO harmonized standards, and customer-specific oilfield certifications extends product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Fluoropolymer Market |
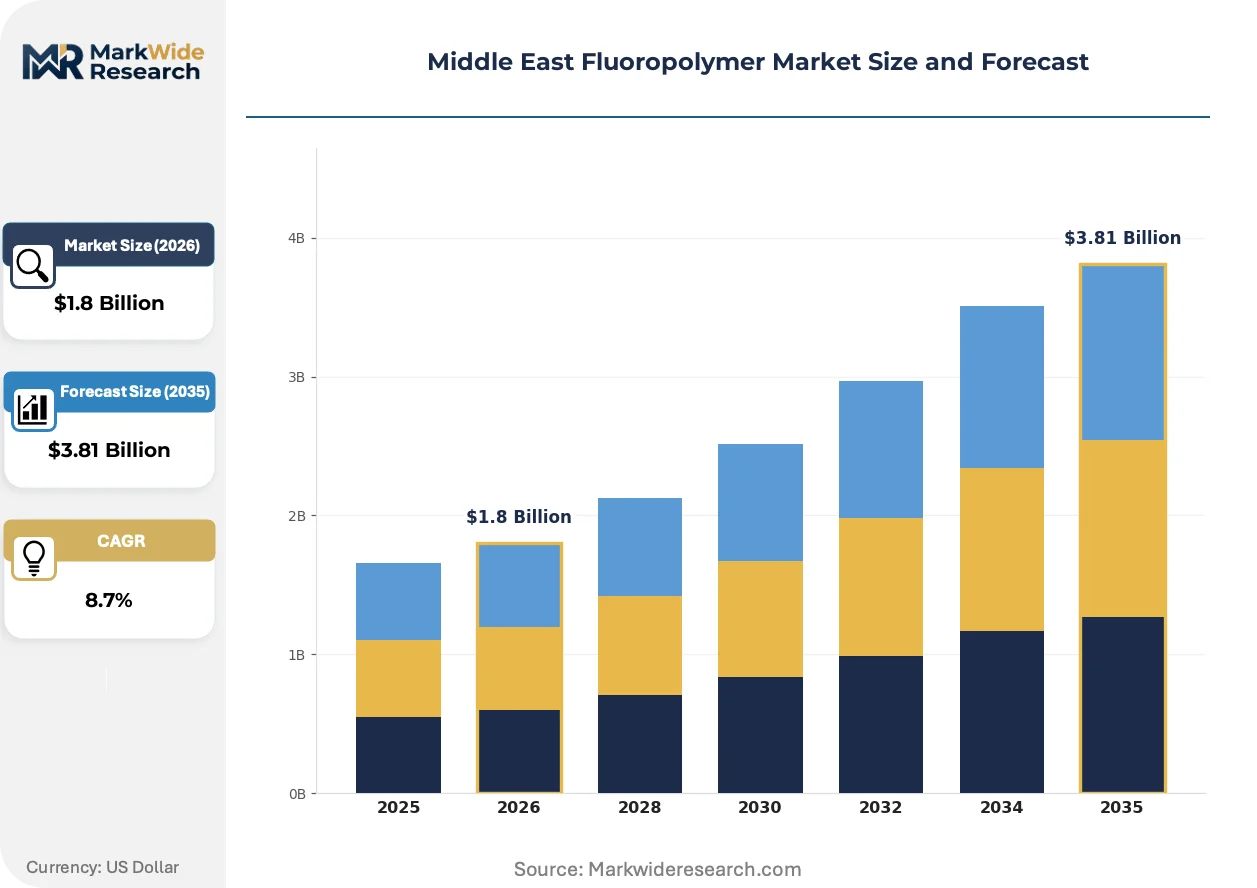
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE End User: Aerospace, Chemical Processing, Electronics, Automotive Application: Cable Insulation, Coatings, Linings, Seals Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | 3M Company, AGC Inc., Arkema S.A., The Chemours Company, Daikin Industries Ltd., Solvay Group, DuPont, Saudi Basic Industries Corporation, Dongyue Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Fluoropolymer Market Trends and Innovations
Melt-processable fluoropolymer formulations are collapsing traditional fabrication boundaries, while regulatory alignment and procurement compression reshape how value flows through Gulf chemical supply chains.
Advanced PFA and ETFE extrusion grades are collapsing the distinction between high-performance fluoropolymers and conventional engineering plastics in process equipment fabrication. Saudi petrochemical operators now specify melt-processable liners for vessels previously requiring machined PTFE components. This shift compresses lead times from weeks to days and enables complex geometries impossible with sintered stock.
Gulf Standardization Organization technical regulations are converging with SASO certification requirements to create unified market access across Saudi Arabia, UAE, Qatar, Kuwait, Bahrain, and Oman. Fluoropolymer importers face reduced redundancy in testing protocols, though transitional compliance costs concentrate on laboratories seeking multi-jurisdiction accreditation. The Emirates' aerospace maintenance sector benefits most directly from streamlined ETFE and PFA grade approvals.
Specification authority is migrating from distributor networks to end-user engineering departments with dedicated materials science functions. Saudi Aramco and ADNOC now maintain centralized fluoropolymer qualification databases, bypassing traditional channel recommendations. This compression of the specification chain concentrates volume with compounders capable of direct technical engagement and batch-level traceability documentation.
Middle East Fluoropolymer Market Segmentation
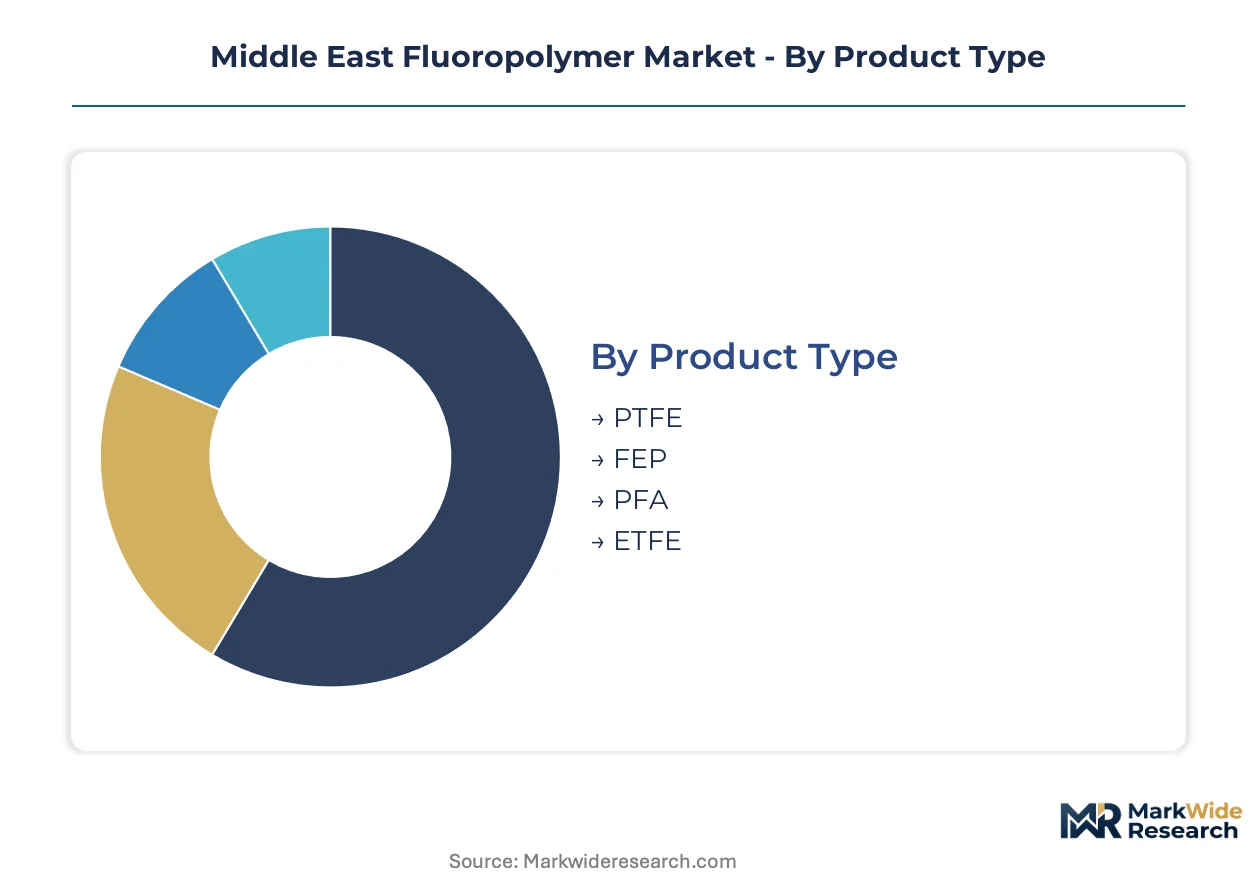
Fluoropolymer procurement patterns across the Middle East diverge sharply by performance tier and end-use criticality. Specification authority concentrates in direct channels for large petrochemical operators while distributors capture fragmented maintenance demand.
Product Type:
Cost tier stratification separates commodity volume grades from specialty formulations commanding qualification premiums.
- PTFE:Polytetrafluoroethylene comprises the foundational fluoropolymer architecture with sintered and granular formulations dominating chemical processing infrastructure. Demand concentrates in Saudi Arabia's Jubail and Yanbu industrial corridors where refinery lining contracts specify virgin resin grades. State-backed petrochemical diversification compresses qualification timelines for domestic PTFE sourcing.
- ETFE:Ethylene-tetrafluoroethylene copolymer delivers the optimal strength-to-weight ratio for tensile membrane architecture. Projects in Qatar and the UAE specify ETFE cladding for stadium and transit infrastructure where UV resistance and self-cleaning surfaces displace conventional glazing. This segment is gaining share fastest as Gulf mega-projects accelerate specification.
- FEP:Fluorinated ethylene propylene provides melt-processability with chemical resistance parity to PTFE.
- PFA:Perfluoroalkoxy resin serves high-purity pharmaceutical and semiconductor process equipment.
PTFE holds installed capacity. ETFE is rotating up the share rankings.
End User:
Application maturity varies dramatically across industrial verticals with aerospace and chemical processing anchoring volume.
- Chemical Processing:Aggressive media containment in Saudi and Emirates refineries drives specification for lined vessels, piping, and heat exchangers. Operators in Jubail Industrial City now mandate batch-level traceability documentation for fluoropolymer linings exposed to hydrofluoric acid and sour gas streams.
- Aerospace:Emirates' maintenance, repair, and overhaul sector consumes specialty PFA and ETFE grades for fuel system components and wiring insulation. Dubai's aviation hub status concentrates demand for FAA-certified materials serving wide-body fleet retrofits.
- Electronics:Cable insulation and connector housings for energy infrastructure.
- Automotive:Sealing and fuel system components for regional vehicle assembly.
Chemical Processing anchors revenue concentration. Aerospace is climbing the fastest.
Application:
Functional performance requirements dictate resin selection with thermal and chemical exposure boundaries determining specification.
- Cable Insulation:Nuclear-grade and subsea-certified insulation tiers command premium positioning in Emirates and Saudi energy infrastructure. Offshore platform specifications require halogen-free, flame-retardant fluoropolymer jackets rated for 150°C continuous operation.
- Linings:Vessel and tank internal protection against corrosive process streams in Gulf petrochemical complexes.
- Coatings:Architectural and industrial surface protection applications.
- Seals:Gasket and O-ring formulations for high-pressure process equipment.
Linings hold installed capacity. Cable Insulation is rotating up the share rankings.
Distribution Channel:
Channel selection correlates directly with buyer scale and technical service requirements.
- Direct Sales:Saudi Aramco and ADNOC procurement functions bypass distributor networks for fluoropolymer volumes above threshold quantities. Centralized qualification databases enable direct compounder engagement with batch-level documentation.
- Distributors:Regional stockists capture maintenance, repair, and operations demand from fragmented process plant operators.
- Online Retail:Emerging channel for standardized grades and technical documentation access.
- Wholesalers:Bulk resin distribution to regional compounders and fabricators.
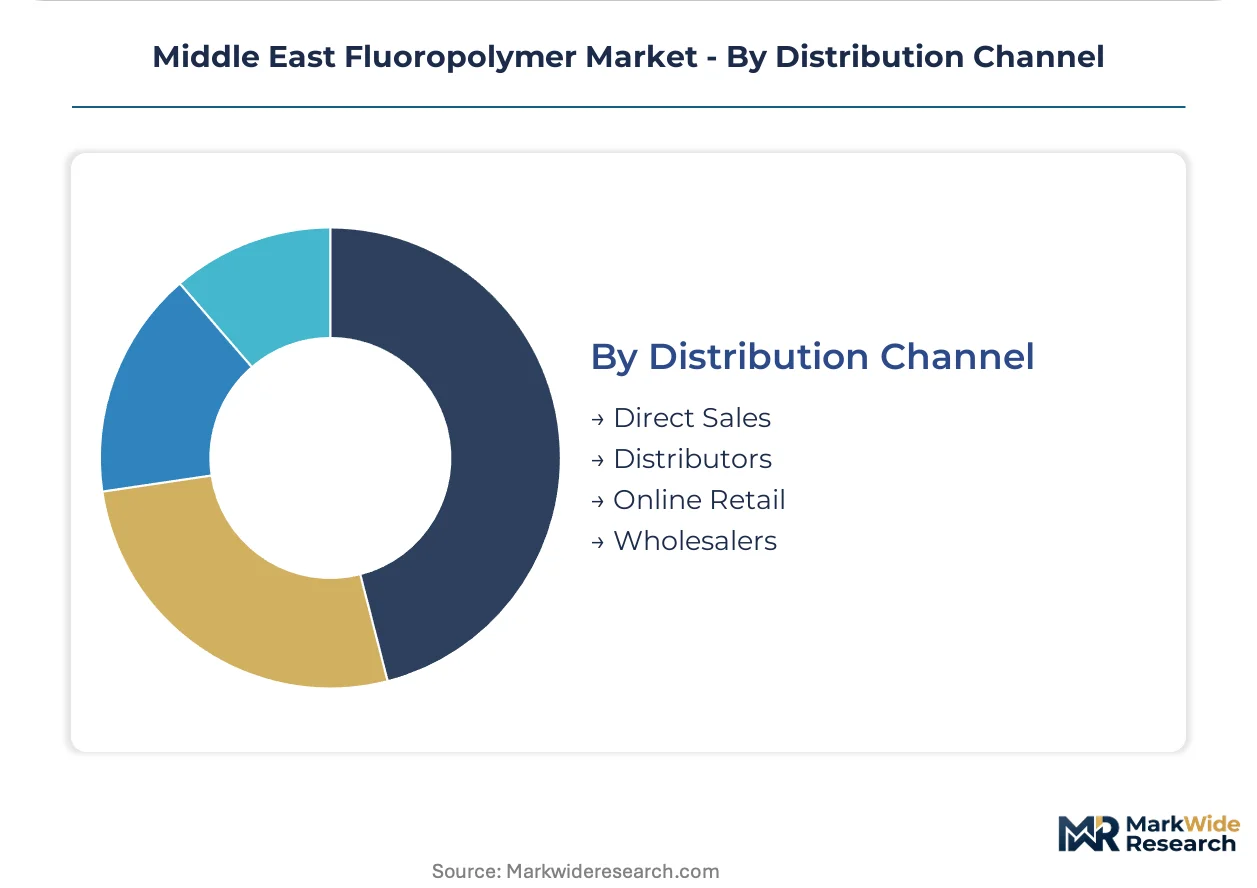
Direct Sales holds revenue concentration. Distributors is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large petrochemical operators in Saudi Arabia and the UAE dominate fluoropolymer procurement through centralized qualification systems. State-backed industrial diversification programs across the Gulf Cooperation Council are compressing supplier timelines. Specification authority is migrating from distributors to end-user engineering departments with dedicated materials science functions.
Saudi Arabia
Jubail and Yanbu industrial clusters drive concentrated demand for PTFE linings in refinery vessels and sour gas processing equipment. Saudi Standards, Metrology and Quality Organization technical regulations align fluoropolymer certification with Gulf Standardization Organization requirements, streamlining multi-jurisdiction market access. Aramco's centralized procurement database now mandates batch-level traceability for all fluoropolymer components exposed to hydrofluoric acid streams.
United Arab Emirates
Dubai's aerospace maintenance, repair, and overhaul sector consumes specialty PFA and ETFE grades for fuel system retrofits and wiring insulation. MOHAP pharmaceutical packaging standards enforce high-purity resin requirements for bioprocessing equipment in Abu Dhabi and Dubai healthcare manufacturing zones. Emirates-based technical service centers from Japanese and European compounders address demand for localized application engineering and faster response times.
Qatar
Stadium and transit infrastructure mega-projects specify ETFE membrane cladding systems where UV resistance and self-cleaning surfaces displace conventional glazing. The country's national building codes now reference Gulf Standardization Organization fluoropolymer standards for architectural applications. Lusail City and Education City developments concentrate specification activity for tensile membrane specialists.
Kuwait
Refinery modernization programs at Al-Zour and Mina Al-Ahmadi complexes generate demand for high-temperature lining materials in aggressive process environments. The country's environmental protection authority is developing chemical inventory frameworks modeled on EU REACH principles. Industrial City of Shuaiba hosts the primary concentration of fluoropolymer fabrication workshops serving downstream petrochemical operators.
Oman
Duqm Special Economic Zone petrochemical investments are creating new specification channels for specialty chemical production infrastructure. The Sultanate's standards and metrology organization participates in Gulf Standardization Organization harmonization initiatives. Sohar Industrial Port complex anchors fluoropolymer demand for desalination and aluminum smelting process equipment.
Middle East Fluoropolymer Market Competitive Landscape
Channel-controlling players compete with product-specialist players for specification authority in Middle East fluoropolymer procurement. The market structure concentrates around integrated fluorochemical producers with captive monomer supply and regional technical service networks. Three archetypes dominate: multinational resin producers with Gulf distribution partnerships, regional compounders serving petrochemical maintenance demand, and specialized fabricators for membrane architecture projects. Competitive moves center on technical service center localization and qualification database positioning for direct engagement with Aramco and ADNOC procurement functions.
Among Japanese industrial conglomerates with fluorochemical heritage, Daikin Industries Ltd. and AGC Inc. occupy positions anchored by technical service infrastructure in Dubai and compounding partnerships across the GCC. Solvay Group represents the European specialty chemicals archetype with differentiated PFA and ETFE grades targeting aerospace and pharmaceutical applications. These three exemplify the premium-tier positioning required for specification in Saudi Arabia's Jubail and Yanbu industrial corridors and the Emirates' aviation maintenance sector.
| Leading Market Players |
|---|
| 3M Company |
| AGC Inc. |
| Arkema S.A. |
| The Chemours Company |
| Daikin Industries Ltd. |
| Solvay Group |
| DuPont |
| Saudi Basic Industries Corporation |
| Dongyue Group |
| Others |
Pricing and Supply Chain Analysis
Jebel Ali Port freight corridors impose volatile landed costs on fluoropolymer resin shipments, compressing margins for regional compounders while enabling Saudi Aramco and ADNOC procurement functions to extract volume-based price concessions from suppliers locked into long-term offtake structures.
Pricing Analysis
Cost-plus contracts indexed to fluorspar and TFE monomer benchmarks dominate procurement between East Asian resin producers and Gulf compounders. Price differentiation hinges on certification grade—SASO-compliant versus GSO-harmonized tiers—and volume scale with annual offtake thresholds. Pricing pressure stems from ceramic substitution threats in refinery applications above 260°C thermal cycling. Maintenance procurement teams at fragmented process plants exhibit highest price sensitivity; Aramco's centralized buyers leverage qualification databases for least.
Supply Chain Analysis
Contract manufacturing concentrates at AGC's Chiba facility and Daikin's Osaka complex for virgin resin production, with compounding partnerships localized across Dubai Industrial City and Jubail. Raw material dependencies center on Chinese fluorspar concentrate, Japanese TFE monomer, and German specialty additive packages. Single-source vulnerability runs through East Asian fluorosurfactant feedstock channels. Distribution runs through direct sales for volumes above Aramco thresholds, with regional distributors capturing MRO fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and application engineering retainers now expand faster than base resin sales, as Gulf petrochemical operators outsource PFA welding certification and ETFE membrane installation supervision to compounders with localized expertise.
For Market Incumbents: Insulate position by deepening backward integration into TFE monomer production or securing captive fluorspar offtake from Chinese suppliers. Invest in multi-jurisdiction laboratory accreditation ahead of GCC REACH-equivalent implementation. Ceramic substitution in high-temperature refinery vessels represents the priority threat requiring defensive R&D spend on hybrid fluoropolymer-ceramic composite liners.
For New Entrants and Emerging Players: Mid-market pharmaceutical packaging compounders in Saudi Arabia's King Abdullah Economic City represent the most penetrable entry point, bypassing entrenched positions in Jubail petrochemical corridors. Bioprocessing equipment localization under SFDA standards offers specification access without Aramco procurement database barriers. Partner with regional vocational institutions to build certified PFA welding technician pipelines as differentiated service attach.
For Investors and Strategic Acquirers: Carve-out targets emerge from Japanese industrial conglomerates seeking to monetize non-core fluorochemical divisions with established Gulf technical service infrastructure. Five-to-ten year viability hinges on GCC chemical inventory framework compliance costs concentrating market share with integrated producers. Monitor Saudi Standards, Metrology and Quality Organization regulatory bulletins for REACH-equivalent implementation timing as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Center Localization | Dubai-based application engineering addresses Gulf buyers' demand for sub-48-hour response times on PFA welding failures. |
| Backward Integration into Fluorspar | Captive concentrate supply from Chinese mining partnerships reduces exposure to shipping volatility through Jebel Ali. |
| Multi-Jurisdiction Laboratory Accreditation | SASO-GSO dual certification streamlines market access across Saudi Arabia and Emirates aerospace maintenance sectors. |
| Bioprocessing Equipment Qualification | SFDA-compliant PFA resin grades unlock Saudi pharmaceutical packaging demand outside Aramco procurement channels. |
| ETFE Membrane Installation Partnerships | Qatar stadium and transit infrastructure projects require certified tensile membrane specialists with localized fabrication capacity. |
Research Methodology
Desk research of customs trade databases, Gulf Standardization Organization technical regulation filings, and SEC 10-K fluorochemical segment disclosures preceded structured interviews with Saudi Aramco procurement directors, ADNOC materials qualification engineers, Dubai-based technical service center managers, and Jubail Industrial City maintenance supervisors. Bottom-up volume estimates from resin import tonnage and top-down value triangulation from petrochemical capital expenditure disclosures were cross-validated against compounder production capacity assessments.
Assumptions held fixed include continued Gulf Standardization Organization regulatory harmonization and sustained Saudi Vision 2030 petrochemical diversification funding; variables tested include GCC REACH-equivalent implementation timing and ceramic substitution rates in refinery applications. Segmentation modeling spanned product grade tier, end-use industry vertical, application functional requirement, and distribution channel structure across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating Jubail and Yanbu cluster expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in oil price benchmarks, GCC sovereign debt financing costs, or Chinese fluorspar export quota policies would shift the trajectory. Quarterly review of SASO regulatory bulletins, Jebel Ali Port container throughput indices, and Aramco procurement database qualification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Global Linear Low Density Polyethylene Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Closed Cell Polyurethane Foam Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Marine-grade Polyurethane Market