
 US Polymethyl Methacrylate Market | 2026-2036
US Polymethyl Methacrylate Market Size, Share, and Industry Trends Forecast 2026-2036
US Polymethyl Methacrylate Market Intelligence
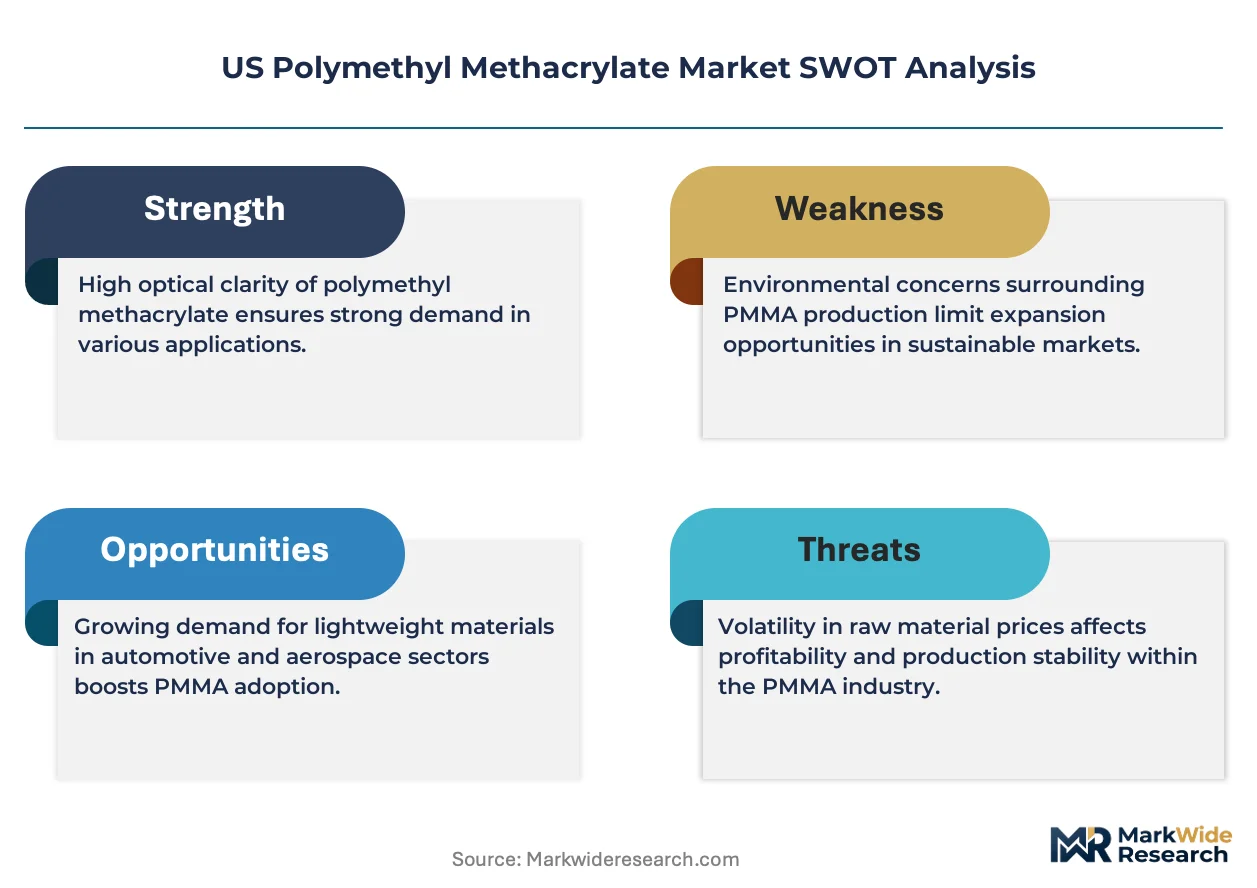
Custom compounding and color-matching services is recalibrating how value gets captured in the US polymethyl methacrylate supply chain. Trinseo leverages its Ohio-based extrusion footprint to anchor automotive glazing programs with domestic OEMs. Röhm GmbH differentiates through proprietary continuous cast technology that sustains optical clarity specifications for medical device manufacturers. Mitsubishi Chemical Group Corporation competes on pellet formulation breadth, positioning its Kentucky operations to supply injection molders across the Southeast.
Polymethyl methacrylate is a thermoplastic acrylic polymer synthesized from methyl methacrylate monomer via bulk polymerization or suspension processes, yielding amorphous structures with light transmittance exceeding 92 percent and density roughly half that of conventional glass. Its primary commercial purpose centers on transparent or translucent components demanding weather resistance, optical purity, and design flexibility across transportation, building, and healthcare applications. Extruded sheet dominates volume flows due to continuous production economics and standard dimensional availability, while cast sheet commands premium positioning in architectural and display segments requiring superior thickness tolerance and surface finish. Pellet formulations represent the fastest-growing product category as compounders seek ready-to-process feedstock for thin-wall electronics housings and LED light guides.
EPA regulations under the Toxic Substances Control Act govern residual monomer thresholds in finished articles, while NHTSA Federal Motor Vehicle Safety Standards dictate impact resistance and optical performance for automotive glazing substitutions. OSHA workplace exposure limits for methyl methacrylate vapor shape manufacturing plant location decisions and automation investments. Stakeholders must monitor state-level extended producer responsibility proposals in California and New York that could impose end-of-life collection obligations on thermoplastic acrylic articles.
Market Dynamics
Automotive OEMs are systematically replacing silicate glass with polymethyl methacrylate to meet NHTSA fuel economy standards, triggering a material substitution wave that concentrates demand in Michigan and Ohio manufacturing corridors.
Growth Catalysts
- EPA emissions compliance:Tier 3 vehicle emission standards pressure OEMs toward lighter transparent substrates. Polymethyl methacrylate delivers roughly half the density of conventional glass.
- LED light guide proliferation:Electronics manufacturers specify pellet formulations for thin-wall housings. Kentucky-based compounders supply injection molders across the Southeast.
- Medical device optics:Continuous cast sheet meets FDA Class II device clarity requirements. Ohio and Massachusetts device clusters source domestically.
Market Restraints
- Methyl methacrylate feedstock volatility:Acetone cyanohydrin route dependency exposes producers to natural gas and ammonia cost swings. Gulf Coast petrochemical disruptions propagate quickly.
- Midwest supply concentration:Extrusion capacity clusters around Ohio and Michigan. Single-source risk elevates for automotive programs with just-in-sequence delivery requirements.
- Impact resistance ceiling:Federal Motor Vehicle Safety Standard 205 glazing specifications limit polymethyl methacrylate to non-structural applications. Laminated glass retains windshield monopoly.
Strategic Opportunities
- Southeast underpenetration:Tennessee and Alabama automotive transplants lack local sheet extrusion. Greenfield compounding investments could capture Mercedes and Hyundai supply chains.
- Extended producer responsibility tailwinds:California and New York draft end-of-life collection mandates for thermoplastic acrylics. Early compliance infrastructure builds competitive moats.
- Photovoltaic backsheet convergence:Solar panel manufacturers test co-extruded polymethyl methacrylate barriers. UV stability specifications overlap with automotive glazing expertise.
Industry Challenges
- Automation engineering scarcity:Continuous cast lines require specialized extrusion technicians. Ohio and Kentucky technical colleges lack dedicated polymer processing curricula.
- OSHA vapor containment capex:Methyl methacrylate workplace exposure limits force enclosed reaction systems. Brownfield retrofit costs deter smaller compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Polymethyl Methacrylate Market |
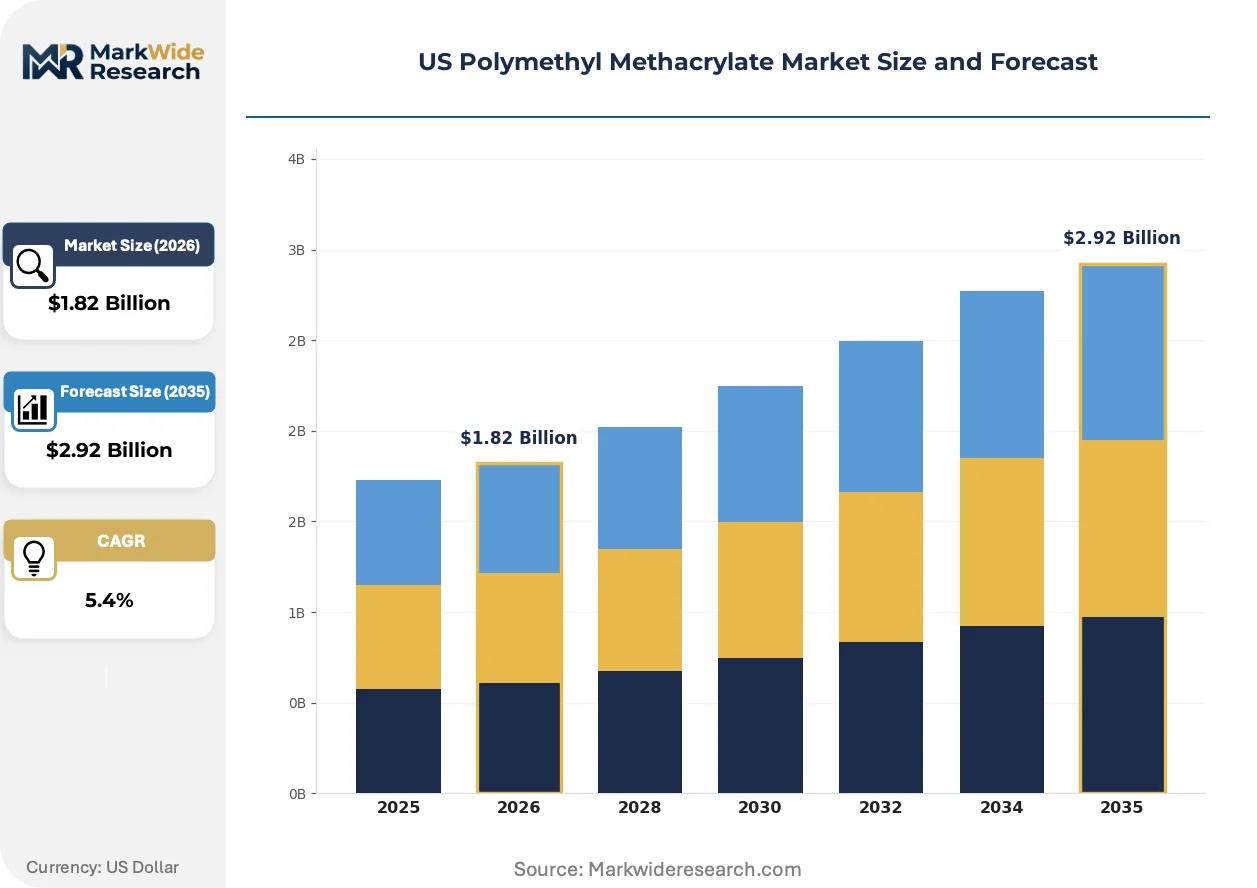
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Sheet, Cast Sheet, Pellets, Powder Application: Automotive, Construction, Electronics, Medical End User: OEMs, Manufacturers, Distributors, Retailers Form: Clear, Colored, Textured, Non-Glare |
| Companies Covered | Trinseo, Röhm GmbH, Mitsubishi Chemical Group Corporation, Altuglas International SAS, Sumitomo Chemical Co., Ltd., CHIMEI Corporation, Mitsubishi Rayon Co., Ltd., Kuraray Group, SABIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Polymethyl Methacrylate Market Strategic Shifts & Innovations
Material scientists and process engineers are converging on optical-grade formulations that bridge automotive, medical, and photovoltaic specifications simultaneously.
Co-extruded multilayer sheet is expanding into photovoltaic backsheet applications. Solar module manufacturers in Arizona and Texas specify UV-stable barriers that match polymethyl methacrylate's weathering performance. This crossover is compressing the traditional separation between automotive glazing and renewable energy material supply chains.
NHTSA Federal Motor Vehicle Safety Standard 205 revision discussions are forcing glazing suppliers to validate impact resistance at expanded temperature ranges. Michigan-based Tier 1 suppliers are accelerating testing protocols. Side-window applications face the strictest scrutiny as regulators weigh optical clarity against occupant ejection protection.
Specification consolidation among Detroit Three procurement departments is elevating certified compounders over spot-market pellet buyers. Tier 2 molders in Indiana and Ohio now face qualification barriers that favor long-term supply agreements. This concentration is most visible in head-up display lens programs where optical tolerances exclude non-certified feedstock.
US Polymethyl Methacrylate Market Segmentation
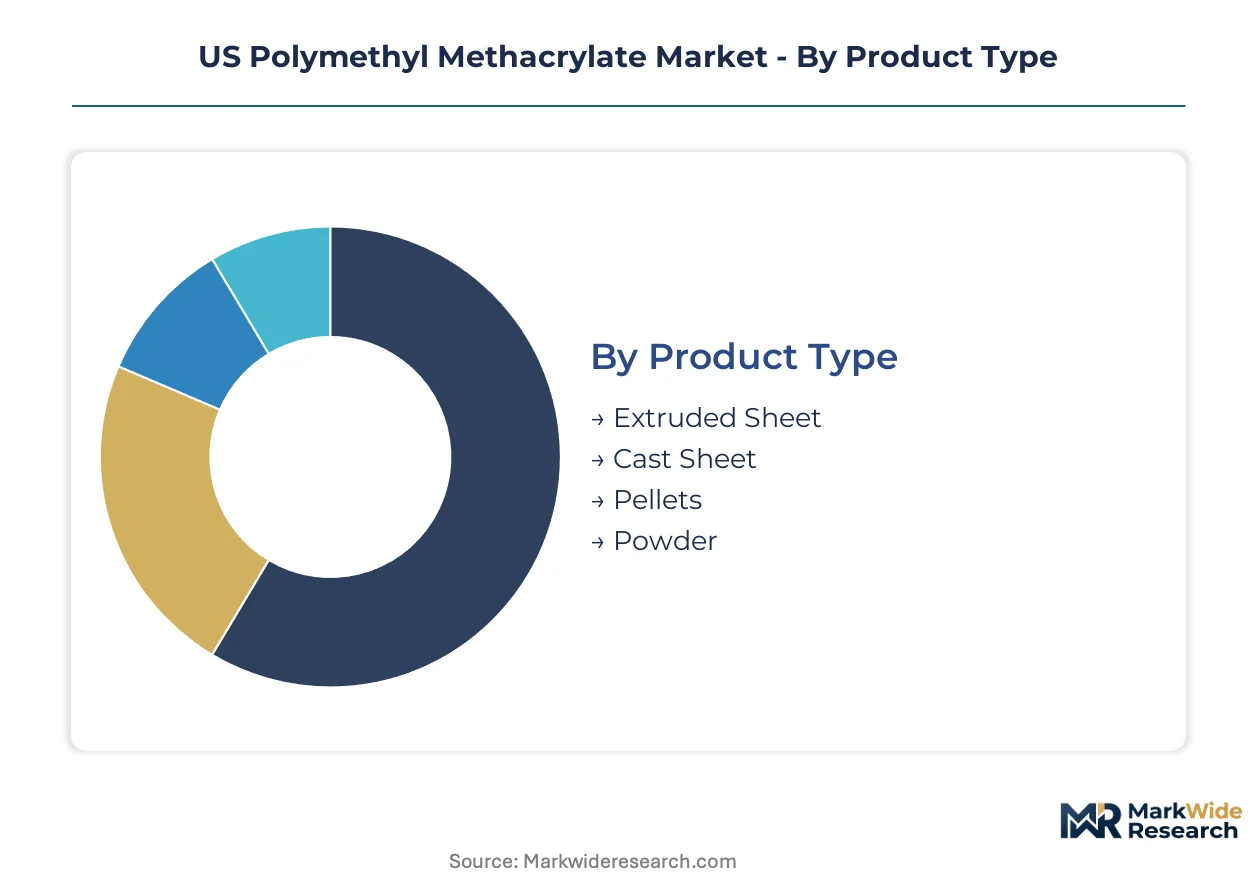
Polymethyl methacrylate demand fragments across specification grades that command divergent margin profiles. Extrusion technology, optical clarity thresholds, and automotive qualification status determine which product formats capture premium positioning versus commodity volume.
Product Type:
Continuous production methods and batch casting economics create distinct cost structures across formats.
- Extruded Sheet:Manufactured via single-screw or twin-screw extrusion with molecular orientation controlled through die geometry and roll-stack cooling. Michigan and Ohio automotive glazing programs consume the majority of domestic extrusion output under NHTSA-certified supply agreements.
- Cast Sheet:Produced through cell casting between glass plates or continuous belt casting, yielding superior thickness tolerance and surface finish. Ohio and Massachusetts medical device clusters specify cast grades for FDA Class II optical components requiring sub-micron surface roughness.
- Pellets:Compounded formulations ready for injection molding and thin-wall processing. Kentucky compounders supply Southeast electronics molders with light-guide-optimized grades.
- Powder:Ground particulate for solvent-based coatings and specialty adhesive formulations. Niche demand concentrates in industrial maintenance coatings.
Mature deployment sits with extruded sheet. Newer deployment is concentrated in pellets.
Application:
End-use specifications diverge sharply on impact resistance, weathering, and regulatory compliance burdens.
- Automotive:Side-window, backlight, and head-up display lens applications dominate value capture. EPA Tier 3 fuel economy standards and NHTSA glazing specifications drive material substitution away from silicate glass in Michigan and Ohio manufacturing corridors.
- Construction:Architectural glazing, signage, and lighting diffusers constitute volume demand. Florida and California building codes specify UV-stability thresholds that exclude lower-grade acrylics.
- Electronics:LED light guides, display covers, and device housings require pellet formulations with precise refractive index control. Southeast injection molders serve consumer electronics assembly.
- Medical:Diagnostic device windows, surgical instrument handles, and dental applications demand cast sheet with biocompatibility certification. Ohio and Massachusetts device clusters source domestically.
Established volume concentrates in construction. Steepest expansion trajectory is visible in automotive.
End User:
Procurement sophistication and qualification barriers stratify the customer base.
- OEMs:Detroit Three automakers and tier-1 glazing suppliers enforce certified compounder requirements with multi-year supply agreements. Specification consolidation elevates entry barriers for non-qualified feedstock.
- Manufacturers:Tier-2 molders and fabricators in Indiana and Ohio purchase pellet and sheet stock for secondary processing. Just-in-sequence delivery requirements favor regional supply proximity.
- Distributors:Stocking intermediaries serve job-shop fabricators and maintenance contractors with standard dimensional inventory.
- Retailers:Hardware chains and specialty plastics suppliers move small-lot sheet and rod for DIY and repair applications.
Contract discipline is tightest among OEMs. Volume flexibility is greatest with retailers.
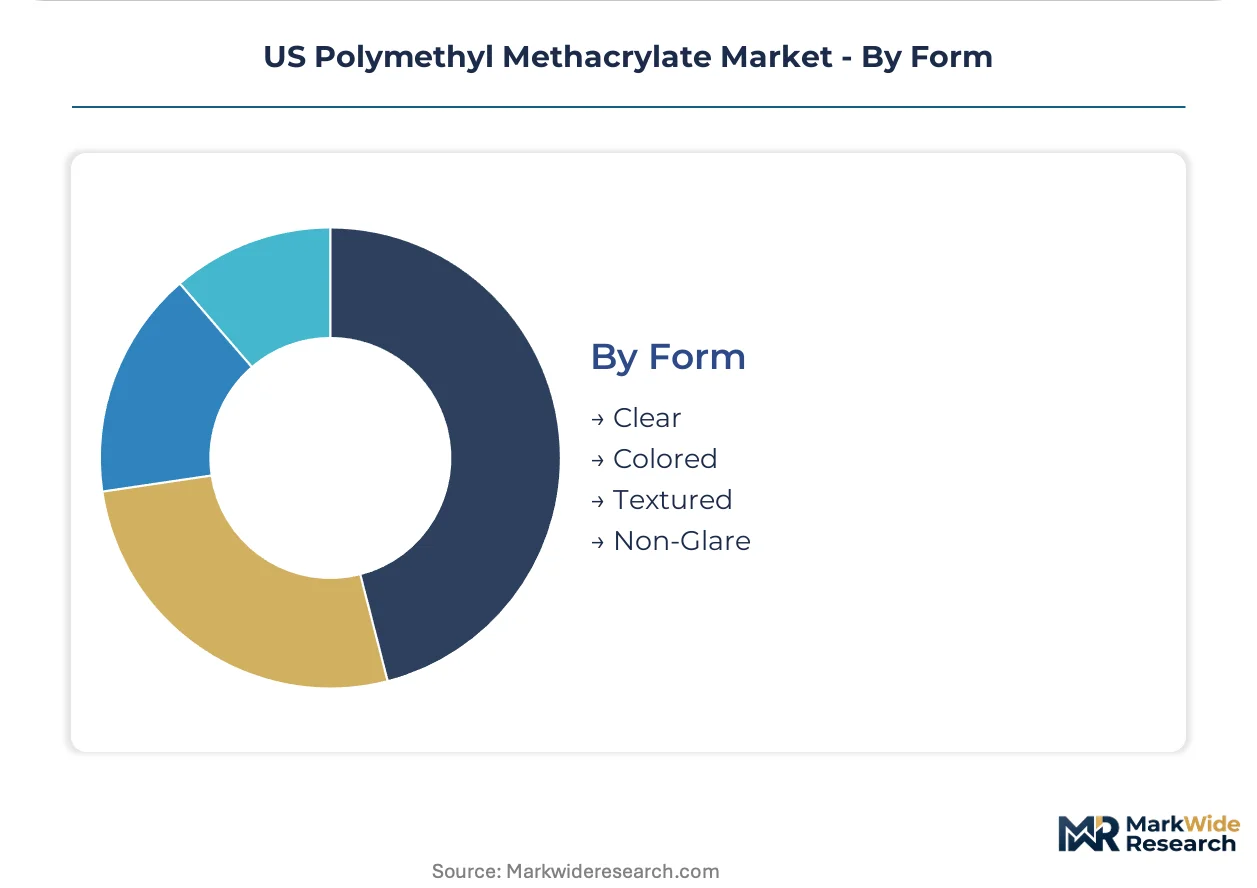
Form:
Surface finish and light-management properties command specification-driven premiums.
- Clear:Unpigmented grades with light transmittance exceeding 92 percent serve optical-critical applications. Automotive glazing and medical device windows specify clear grades exclusively.
- Colored:Pigmented formulations matched to OEM color standards for interior trim and exterior accents. Custom compounding services capture value through batch-to-batch consistency.
- Textured:Embossed or matte surfaces for diffused lighting and anti-fingerprint display covers. Electronics manufacturers specify texture depth for haptic feedback.
- Non-Glare:Chemically etched or coated surfaces reducing specular reflection below 1 percent. Aviation and military display applications drive qualification testing.
Commodity volume flows through clear grades. Premium capture is expanding fastest in non-glare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the Great Lakes corridor while consumption spreads across automotive, medical, and electronics hubs. This geographic mismatch creates freight cost premiums for Southeast and Southwest manufacturers. Regional specialization is hardening around regulatory compliance zones and OEM qualification requirements.
Great Lakes Corridor
Michigan and Ohio anchor automotive glazing demand as Detroit Three OEMs execute material substitution programs. NHTSA Federal Motor Vehicle Safety Standard 205 compliance testing concentrates in Ann Arbor and Detroit metro laboratories. Ohio-based extrusion facilities supply just-in-sequence delivery to assembly plants in Lordstown and Toledo.
Southeast Manufacturing Belt
Tennessee and Alabama automotive transplants from Mercedes and Hyundai generate pellet demand for injection-molded components. EPA Tier 3 emissions standards pressure these facilities toward lightweight transparent substrates. Kentucky compounders in the Ohio River Valley ship formulated grades to electronics molders across Georgia and South Carolina.
Northeast Medical Corridor
Massachusetts and Ohio device clusters source cast sheet for FDA Class II optical components. OSHA workplace exposure limits for methyl methacrylate vapor shape plant automation investments in Worcester and Cincinnati suburbs. Continuous cast technology serves diagnostic window applications requiring sub-micron surface roughness.
Southwest Solar Testing Ground
Arizona and Texas solar module manufacturers pilot co-extruded polymethyl methacrylate backsheet barriers. UV stability specifications from photovoltaic applications overlap with automotive glazing expertise. Field testing in Phoenix and El Paso validates weathering performance against desert exposure conditions.
California Regulatory Laboratory
State-level extended producer responsibility proposals in Sacramento shape end-of-life collection infrastructure investments. Building codes in Los Angeles and San Francisco specify UV-stability thresholds for architectural glazing that exclude lower-grade acrylics. Draft mandates for thermoplastic acrylic recycling create compliance moats for early movers.
US Polymethyl Methacrylate Market Key Industry Players
Top-tier vendors anchor certified automotive supply agreements, while mid-scale compounders compete on pellet formulation breadth and color-matching services. The vendor base stratifies around qualification status with Detroit Three OEMs. Three archetypes dominate: integrated resin-to-sheet producers, regional compounders with custom formulation capabilities, and Asian exporters leveraging cost-positioned commodity grades. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure feedstock access and geographic proximity to automotive clusters.
Within the integrated producer tier, Trinseo and Röhm GmbH occupy positions defined by domestic extrusion footprints and proprietary process technology. Mitsubishi Chemical Group Corporation exemplifies the compounder archetype with pellet formulation breadth positioned for Southeast electronics supply chains. These three entities represent the competitive anchors around which qualification barriers and supply agreements consolidate.
| Leading Market Players |
|---|
| Trinseo |
| Röhm GmbH |
| Mitsubishi Chemical Group Corporation |
| Altuglas International SAS |
| Sumitomo Chemical Co., Ltd. |
| CHIMEI Corporation |
| Mitsubishi Rayon Co., Ltd. |
| Kuraray Group |
| SABIC |
| Others |
Cost & Logistics Intelligence
Continuous cast technology migration toward higher optical grades is compressing cost curves for certified automotive glazing while simultaneously concentrating production among extrusion-capable compounders in Ohio and Kentucky. This dual effect elevates pricing power for NHTSA-qualified suppliers while squeezing spot-market pellet buyers dependent on commodity-grade feedstock.
Pricing Analysis
Cost-down pressure on injection molding grades accelerates because Southeast electronics manufacturers consolidate procurement around volume-scale contracts. Three-tier pricing structure across optical-certified, automotive-qualified, and commodity-standard levels separates NHTSA-compliant sheet from FDA-cast grades from undifferentiated pellets. Price differentiation hinges on certification tier and geographic delivery cost to automotive corridors. Tier-2 molders in Indiana exhibit highest price sensitivity; Detroit Three OEMs prioritize optical consistency over unit cost.
Supply Chain Analysis
End-of-life collection infrastructure for thermoplastic acrylics remains embryonic, with California and New York draft mandates forcing producers to model reverse-logistics costs before pricing long-term contracts. Feedstock draws from Gulf Coast petrochemical complexes, Ohio-based extrusion facilities, and Kentucky compounders. Methyl methacrylate monomer, acetone cyanohydrin, and specialized UV stabilizers constitute critical input dependencies. Single-source vulnerability elevates for just-in-sequence automotive programs. Distribution runs through certified compounder direct sales, regional distributors, and spot-market pellet brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US polymethyl methacrylate market sits at a technology-transition inflection as co-extruded multilayer sheet displaces conventional glazing substrates in photovoltaic and automotive applications simultaneously.
For Market Incumbents: To counter Southeast underpenetration by Asian pellet exporters, deepen captive supply of methyl methacrylate monomer through Gulf Coast feedstock partnerships and expand continuous cast capacity in Tennessee to capture Mercedes and Hyundai glazing programs. Certification investment in NHTSA-expanded temperature-range testing represents the critical defensive moat. For New Entrants and Emerging Players: EPA Tier 3 emissions standards in the United States open a window for lightweight transparent substrate specialists to establish greenfield compounding operations in Alabama and Georgia serving automotive transplants. Target medical device optics in Massachusetts and Ohio with cast sheet differentiated by sub-micron surface roughness specifications. Partner with Kentucky-based technical colleges to secure automation engineering talent before incumbent lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated resin producers seeking geographic proximity to Detroit Three assembly plants. Long-term viability favors compounders with backward integration into monomer supply and certified automotive qualification status. Monitor NHTSA Federal Motor Vehicle Safety Standard 205 revision timing as inflection signal for glazing substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Gulf Coast petrochemical partnerships insulate producers from acetone cyanohydrin route volatility. |
| Greenfield Compounding Investment | Tennessee and Alabama facilities capture Mercedes and Hyundai supply chains lacking local extrusion. |
| Extended Producer Responsibility Infrastructure | California and New York compliance moats reward early movers in thermoplastic acrylic collection. |
| Continuous Cast Technology Expansion | Ohio and Massachusetts medical device clusters demand sub-micron surface roughness specifications. |
| NHTSA Certification Investment | Ann Arbor and Detroit metro laboratories validate expanded temperature-range impact resistance. |
Research Approach
Document review covered SEC 10-K filings, customs and trade data from the US International Trade Commission, and American Chemistry Council reports, complemented by interviews with plant managers at extrusion facilities, procurement leads at Tier 1 automotive glazing suppliers, distribution channel partners, and technical R&D directors at compounders. Bottom-up volume modeling triangulated against top-down industry association estimates.
Historical shipment data cross-referenced against panel input from automotive platform engineers and medical device manufacturers anchored the analytical framework. Segmentation dimensions modeled include product format, application sector, end-user procurement tier, and regional manufacturing cluster. CAGRs derived from trend extrapolation adjusted for EPA regulatory phase-ins and NHTSA standard revisions. Forecast inputs incorporated LED light guide penetration rates and solar backsheet adoption curves.
The model assumes a particular technology adoption path for co-extruded multilayer sheet; alternative pathways for laminated glass-polymethyl methacrylate hybrid glazing would alter the outlook for automotive volume. Practitioners should monitor NHTSA rulemaking dockets and California extended producer responsibility legislative calendars for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market