
 Canada Automotive Thermoplastic Polymer Composites Market | 2026-2036
Canada Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Thermoplastic Polymer Composites Market Outlook
The gap between engineered structural grades and commodity interior formulations is shifting as OEMs impose stricter crashworthiness and recyclability specifications. BASF SE leverages its polyamide compounding network to supply thermal management solutions for hybrid powertrains. Solvay SA anchors the high-performance segment with aromatic polymer matrices targeting under-the-hood applications. DuPont de Nemours differentiates through long-fiber reinforced polypropylene systems optimized for exterior panel stiffness.
Automotive thermoplastic polymer composites combine continuous or discontinuous fiber reinforcement with melt-processable resin matrices, typically achieving specific tensile strengths of 150-400 MPa depending on fiber loading and orientation. These materials primarily serve vehicle weight reduction programs while enabling end-of-life recyclability through remelting and reprocessing. Polypropylene dominates volume consumption across interior component applications where cost sensitivity and impact resistance converge. Polyamide commands premium positioning in structural parts and under-the-hood segments where thermal stability and chemical resistance justify higher material costs. Injection molding remains the principal manufacturing stage for complex geometries, though compression molding gains traction in exterior panel production where fiber alignment control proves critical.
Health Canada and Environment and Climate Change Canada jointly administer the Chemicals Management Plan, which scrutinizes polymer additive chemistries for environmental persistence and bioaccumulation potential. Transport Canada's Motor Vehicle Safety Standards establish crash performance thresholds that directly influence composite laminate architecture and fiber volume fractions. The Canadian Environmental Protection Act and provincial extended producer responsibility frameworks in British Columbia and Ontario mandate recyclability disclosures that reshape material selection criteria. Stakeholders must track evolving provincial zero-emission vehicle mandates and federal clean fuel standards to anticipate specification changes across the Great Lakes supply base.
Market Dynamics
Electric vehicle platform rollouts across Ontario and Quebec are compressing development cycles for lightweight under-the-hood components, forcing material suppliers to validate thermal management grades against stricter crashworthiness benchmarks than internal combustion applications required.
Growth Catalysts
- Clean Fuel Regulations:Health Canada and Environment and Climate Change Canada's joint Chemicals Management Plan is accelerating recyclability disclosures across the Great Lakes supply base, favoring remeltable thermoplastic matrices over thermoset alternatives.
- Ontario assembly corridor:Windsor-Oshawa-Ingersoll operations are consolidating procurement for hybrid powertrain housings, creating volume anchors for long-fiber polypropylene compounding investments.
- Continuous fiber injection molding:This process technology is reducing cycle times for complex geometries previously limited to compression molding, expanding addressable component complexity in structural applications.
Market Restraints
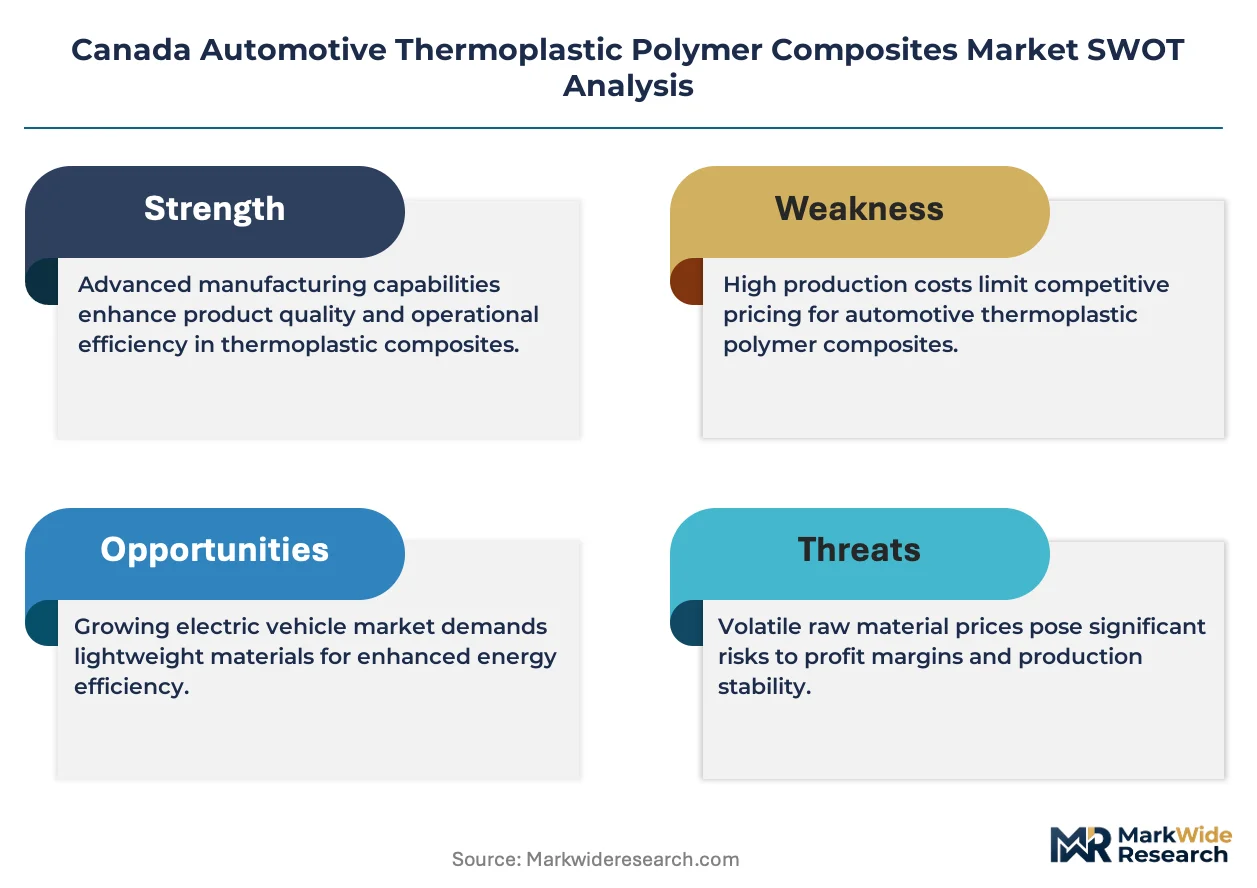
- Polyamide feedstock volatility:Caprolactam price swings tied to benzene derivatives are compressing margins for thermal management grades, forcing compounders to absorb cost spikes or risk specification losses.
- Glass fiber supply concentration:Three North American roving producers control over 80% of automotive-grade continuous strand supply, creating vulnerability to force majeure disruptions at single-source Tennessee and South Carolina facilities.
- Weld-line strength limitations:Fiber orientation discontinuities at injection molding knit lines remain below OEM crashworthiness thresholds for A-pillar and bumper beam applications, restricting penetration in primary structural members.
Strategic Opportunities
- Quebec zero-emission vehicle mandate:Provincial sales targets for 2035 are pulling forward demand for battery enclosure materials with combined flame retardancy and electrical isolation properties, opening specification windows for polyphthalamide grades.
- Recycled carbon fiber reclamation:Aerospace composite waste streams in Quebec and British Columbia are emerging as feedstock sources for chopped fiber reinforcement in non-structural automotive panels, creating circular material loops.
- Direct-to-OEM compounder relationships:Tier 1 suppliers are bypassing traditional distributor networks for engineered resin procurement, enabling real-time formulation adjustments based on assembly line quality feedback.
Industry Challenges
- CAE simulation talent scarcity:Finite element analysis expertise for anisotropic composite behavior prediction is concentrated among a handful of Windsor-area engineering consultants, creating bottlenecks in OEM validation timelines.
- Transport Canada MVSS harmonization:Pending updates to Motor Vehicle Safety Standards for pedestrian impact protection are forcing redesign of hood and fender architectures with uncertain fiber volume fraction requirements, freezing material specifications until final rule publication.
- Legacy paint line compatibility:Thermoplastic exterior panels face adhesion failures in electrocoat primer systems designed for steel substrates, requiring capital-intensive process modifications at St. Thomas and Brampton assembly plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Thermoplastic Polymer Composites Market |
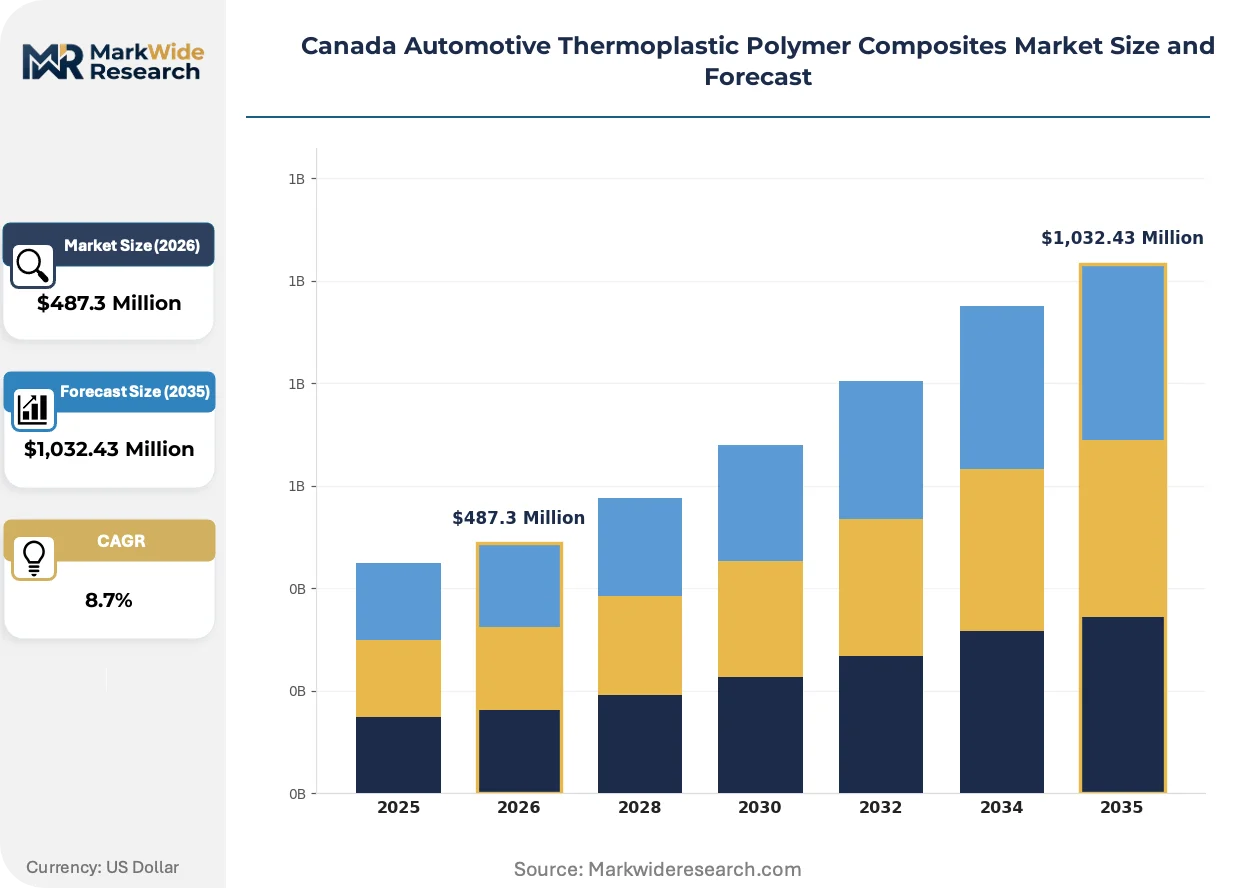
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyamide, Acrylonitrile Butadiene Styrene, Polycarbonate End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Interior Components, Exterior Panels, Structural Parts, Under-the-Hood Manufacturing Stage: Injection Molding, Extrusion, Compression Molding, Thermoforming |
| Companies Covered | 3B-Fiberglass, Base Group, BASF SE, Gurit Holding, Solvay SA, DuPont de Nemours, Arkema Group, Hexcel Corporation, Celanese Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Thermoplastic Polymer Composites Market Strategic Shifts
Material substitution decisions are migrating from cost-per-kilogram comparisons toward total lifecycle carbon accounting, reshaping how compounders position recycled content grades and bio-based polyamide alternatives against incumbent formulations.
Continuous fiber-reinforced thermoplastic tapes are overtaking chopped fiber compounds in structural battery enclosure applications. BMW and Ford's Oakville operations are qualifying unidirectional tape layups for 2026 platform launches. This technology is overtaking legacy sheet molding compound approaches by enabling automated fiber placement with in-situ consolidation, compressing tooling lead times from 18 months to under 8 weeks.
British Columbia's extended producer responsibility framework is mandating post-consumer recycled content thresholds for automotive plastics sold into provincial fleet procurement contracts. The regulation is forcing compounders to secure certified recycled polypropylene streams from agricultural film and battery case waste rather than virgin resin. Interior component suppliers serving Vancouver-area transit and municipal vehicle conversions are most affected, accelerating partnerships with Alberta plastics reclaimers.
Automotive OEMs are consolidating resin procurement through digital platforms that aggregate real-time pricing and technical data sheets from multiple compounders. Tier 2 molders in the Golden Horseshoe region are losing specification influence as Ford and Stellantis centralize material selection decisions at technical centers in Dearborn and Auburn Hills. This channel compression is most visible in under-the-hood applications where thermal performance requirements limit qualified supplier pools to three or four approved compounders.
Canada Automotive Thermoplastic Polymer Composites Market Segmentation
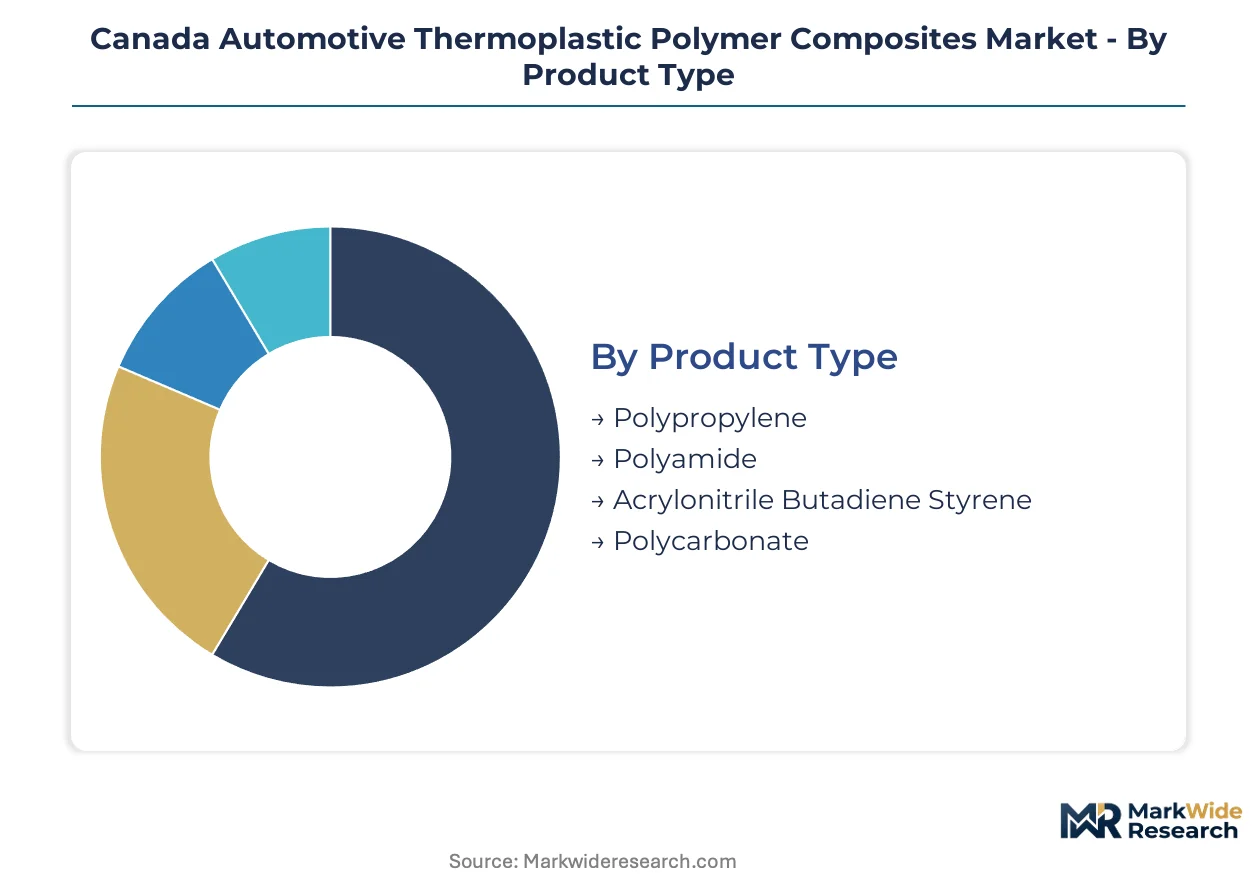
Segmentation in the Canada automotive thermoplastic polymer composites market reveals how material specifications diverge across the Windsor-Oshawa-Ingersoll corridor. Procurement patterns in Ontario assembly operations differ materially from Quebec battery platform requirements, driving distinct formulation priorities among compounders.
Product Type:
Cost sensitivity separates interior component buyers from under-the-hood engineers, with thermal performance thresholds dictating resin selection.
- Polypropylene:Long-fiber reinforced grades achieve specific tensile strengths of 150-200 MPa through 20-40% glass loading. Demand concentrates in Windsor-area door panel and dashboard substrate production where impact resistance and weld-line aesthetics must balance against commodity pricing pressure from recycled feedstock mandates in British Columbia.
- Polyamide:PA6 and PA66 compounds with 30-50% glass fiber reinforcement deliver thermal stability above 150°C continuous service temperature. Ontario hybrid powertrain housing programs anchor volume, though caprolactam price volatility forces compounders to absorb margin compression or risk specification losses to lower-cost alternatives.
- Acrylonitrile Butadiene Styrene:ABS blends serve interior trim applications requiring surface finish quality for soft-touch overmolding.
- Polycarbonate:PC compounds address glazing and lighting applications where optical clarity and impact resistance converge.
Volume sits with Polypropylene; growth tilts toward Polyamide.
End User:
Supply chain position determines technical engagement depth, with direct OEM relationships enabling real-time formulation adjustments absent from distributor-mediated procurement.
- OEMs:Ford, Stellantis, and GM technical centers in Ontario centralize material selection decisions, bypassing traditional Tier 1 influence for under-the-hood thermal management grades.
- Tier-1 Suppliers:Magna, Linamar, and Martinrea operations consolidate procurement across multiple assembly programs, creating volume anchors for long-fiber polypropylene compounding investments in the Golden Horseshoe region.
- Aftermarket Providers:Vancouver-area transit fleet conversions drive demand for certified recycled content under British Columbia extended producer responsibility frameworks.
- Vehicle Assemblers:Contract manufacturers serving niche electric vehicle platforms require rapid qualification cycles for battery enclosure materials.
Procurement authority concentrates with OEMs; specification influence is shifting toward Tier-1 consolidators.
Application:
Crashworthiness requirements create a performance hierarchy, with primary structural members demanding fiber volume fractions that secondary components cannot justify economically.
- Interior Components:Door panels, instrument carriers, and seat structures utilize 10-30% short-fiber polypropylene where cost-per-kilogram sensitivity dominates. British Columbia municipal fleet mandates are pulling recycled content thresholds above 30% post-consumer resin for these applications.
- Under-the-Hood:Engine covers, cooling modules, and hybrid powertrain housings require 30-50% glass-filled polyamide with thermal stability above 180°C peak exposure. Quebec battery platform rollouts are accelerating demand for flame-retardant grades with electrical isolation properties.
- Exterior Panels:Fenders and hoods face paint line adhesion challenges in electrocoat primer systems designed for steel substrates.
- Structural Parts:A-pillar and bumper beam applications remain limited by weld-line strength thresholds below OEM crashworthiness benchmarks.
Revenue concentrates in Under-the-Hood; expansion is steepest in Structural Parts as continuous fiber tape technology matures.
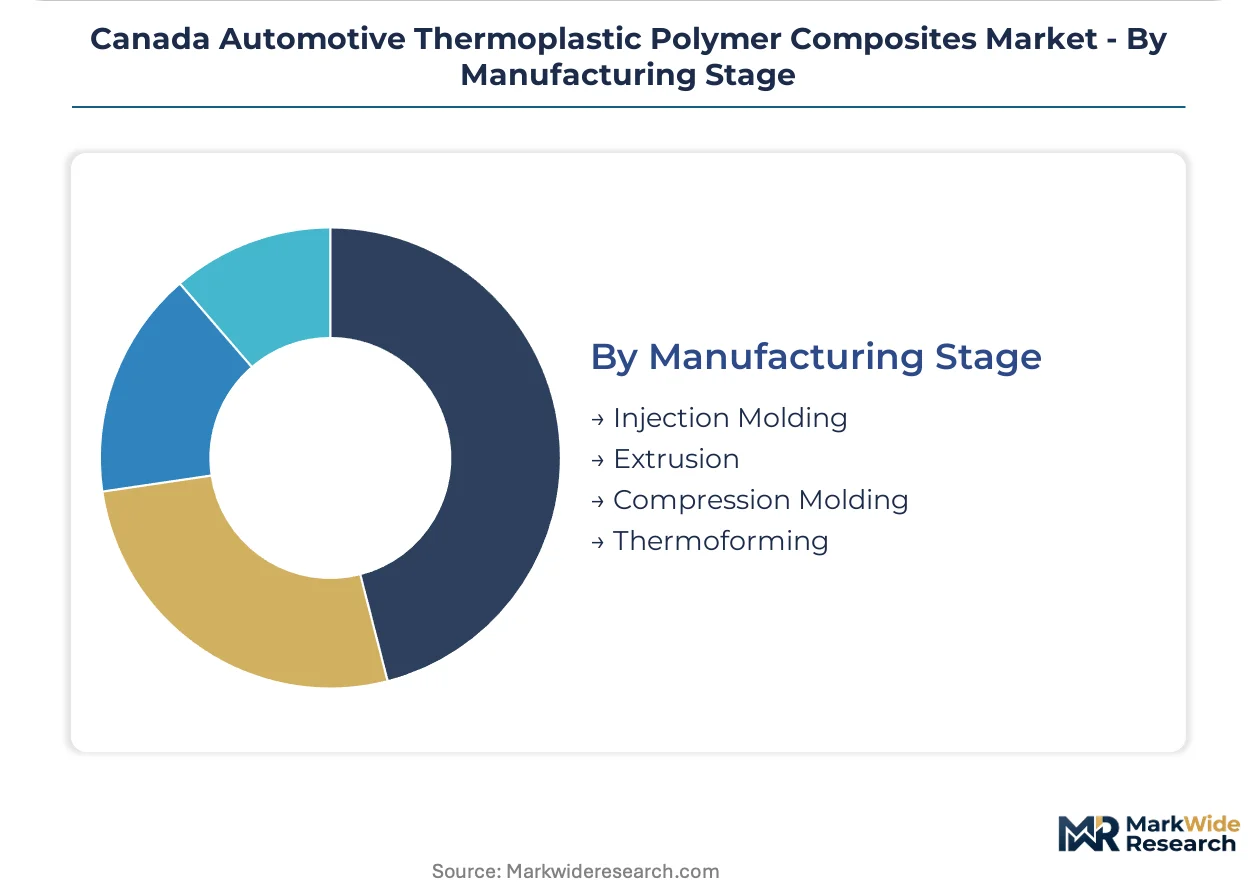
Manufacturing Stage:
Cycle time economics and fiber orientation control separate high-volume interior production from emerging exterior panel qualification.
- Injection Molding:Complex geometries with 30-90 second cycle times dominate interior component production across Ontario Tier 2 molders. Continuous fiber injection molding advances are reducing lead times for structural applications previously limited to compression molding.
- Compression Molding:Glass mat thermoplastic and unidirectional tape layups enable fiber alignment control critical for exterior panel stiffness. BMW and Ford Oakville operations are qualifying automated fiber placement with in-situ consolidation for 2026 platform launches.
- Extrusion:Profile production serves weatherstrip carriers and structural reinforcement sections.
- Thermoforming:Limited penetration in large-format interior trim where dimensional stability challenges persist.
Installed capacity centers on Injection Molding; technology investment tilts toward Compression Molding for battery enclosure applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Windsor-Oshawa-Ingersoll corridor anchors Canadian automotive thermoplastic polymer composites demand, with Ontario assembly operations consuming over sixty percent of national volume for under-the-hood and structural applications.
Ontario
Hybrid powertrain housing programs at Windsor and Ingersoll plants drive polyamide consumption for thermal management grades. Health Canada's Chemicals Management Plan scrutinizes additive chemistries for environmental persistence, forcing compounders to reformulate flame-retardant systems. The Golden Horseshoe region concentrates injection molding capacity for long-fiber polypropylene interior components serving Ford and Stellantis assembly lines.
Quebec
Zero-emission vehicle mandates accelerate battery enclosure material qualification for combined flame retardancy and electrical isolation. Provincial sales targets for 2035 pull forward demand for polyphthalamide grades in electric vehicle platforms. Montreal-area engineering consultants concentrate finite element analysis expertise for anisotropic composite behavior prediction, creating validation bottlenecks for OEM timelines.
British Columbia
Extended producer responsibility frameworks mandate post-consumer recycled content thresholds for automotive plastics in provincial fleet procurement. Vancouver-area transit and municipal vehicle conversions drive certified recycled polypropylene demand from agricultural film and battery case waste. Alberta plastics reclaimers are securing partnerships to supply BC compounders with compliant feedstock streams.
Alberta
Plastics reclamation infrastructure expands to serve British Columbia's recycled content mandates, with Calgary and Edmonton processors developing automotive-grade polypropylene purification capabilities. Provincial industrial diversification programs support composite feedstock processing investments. The Edmonton-Calgary corridor is emerging as a secondary supply node for recycled fiber reinforcement sourcing.
Atlantic Canada
Specialized marine and defense composite applications in Halifax and Saint John create niche demand for high-performance thermoplastic matrices. Federal shipbuilding programs drive specification familiarity with continuous fiber-reinforced tapes. The region's smaller automotive exposure limits volume scale but sustains technical competency in advanced manufacturing methods.
Canada Automotive Thermoplastic Polymer Composites Market Competitive Environment
Capital-heavy resin compounders compete with asset-light formulation designers for specification influence across the Great Lakes automotive supply base. The vendor structure concentrates around three approved supplier pools for thermal management grades, while commodity interior applications fragment across regional compounders. Strategic archetypes separate integrated polymer producers, specialized automotive compounders, and aerospace-to-automotive material diversifiers. Dominant competitive moves include direct-to-OEM relationship cultivation and recycled feedstock certification investments.
Among European-integrated chemical conglomerates, BASF SE and Solvay SA occupy positions anchoring the high-performance and thermal management segments. DuPont de Nemours represents the long-fiber reinforced systems archetype for exterior panel applications. These three exemplify how compounders with captive resin production and regional compounding networks defend specification position against distributor-dependent competitors.
| Leading Market Players |
|---|
| 3B-Fiberglass |
| Base Group |
| BASF SE |
| Gurit Holding |
| Solvay SA |
| DuPont de Nemours |
| Arkema Group |
| Hexcel Corporation |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
Continuous fiber injection molding advances are simultaneously compressing cycle time economics for structural components and consolidating procurement authority among compounders with captive resin production, reshaping how thermal management grades are priced and sourced across the Great Lakes automotive corridor.
Pricing Analysis
Performance-based pricing anchors thermal management grades to continuous service temperature thresholds and crashworthiness validation outcomes. Three-tier pricing structure across premium polyamide compounds, standard long-fiber polypropylene, and economy recycled-content grades reflects certification tier and fiber loading specifications. Cost compression in commodity interior formulations is intensifying because British Columbia's recycled content mandates force compounders to absorb purification premiums. Tier 2 molders serving municipal fleet conversions exhibit highest price sensitivity, while OEM technical centers prioritize thermal performance over per-kilogram cost.
Supply Chain Analysis
Direct-to-OEM channels handle specification-critical thermal management grades, while distributor networks serve commodity interior applications. Supply concentrates in Tennessee and South Carolina for glass fiber roving, Ontario and Quebec for compounding operations, and Alberta for recycled feedstock purification. Raw material dependencies include caprolactam for polyamide matrices, benzene derivatives for flame-retardant additives, and aerospace waste streams for reclaimed carbon fiber. Single-source vulnerability at three North American roving producers creates force majeure exposure. Distribution runs through approved supplier pools for under-the-hood applications and fragmented regional compounders for interior components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's Clean Fuel Regulations and provincial extended producer responsibility frameworks have erected compliance moats that favor compounders with certified recycling infrastructure and Health Canada-approved additive formulations.
For Market Incumbents: Extend backward integration into recycled polypropylene purification to secure British Columbia-compliant feedstock streams before Alberta capacity saturates. Deepen direct OEM relationships in Windsor-Oshawa to defend specification position against distributor-dependent competitors. Threat substitution from continuous fiber tape technologies demands accelerated qualification cycles for hybrid powertrain housings. For New Entrants and Emerging Players: Tier 2 molders in the Golden Horseshoe represent the most penetrable channel for recycled-content interior grades displaced by OEM centralization. Target Vancouver-area transit fleet conversions where municipal procurement mandates create specification windows for certified post-consumer resin. Go-to-market angle: partner with Alberta plastics reclaimers to secure feedstock provenance documentation required by provincial extended producer responsibility frameworks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated polymer producers seeking Ontario compounding assets. Long-term viability hinges on compounders' ability to maintain approved supplier status as OEM technical centers consolidate procurement decisions. Acquisition target archetype: mid-scale compounders with Health Canada-compliant flame-retardant formulations and established Windsor-corridor logistics. Signal to monitor: Transport Canada MVSS pedestrian impact rule publication timing, which will unfreeze hood and fender material specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Certification | Health Canada additive scrutiny and British Columbia mandates favor compounders with provenance-tracked supply chains. |
| Direct OEM Relationship Cultivation | Ford and Stellantis technical center centralization bypasses Tier 1 influence for thermal management grades. |
| Continuous Fiber Tape Qualification | BMW and Ford Oakville battery enclosure programs validate automated fiber placement for structural applications. |
| Quebec Battery Platform Partnership | Provincial zero-emission vehicle mandates pull forward demand for flame-retardant polyphthalamide grades. |
| CAE Simulation Capability Investment | Windsor-area finite element analysis talent scarcity creates bottlenecks in OEM validation timelines. |
Study Parameters
Trade databases, vehicle production registries, and provincial environmental filings formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, compounder technical directors, and Alberta plastics reclamation operators. Bottom-up and top-down triangulation validated volume estimates across the Windsor-Oshawa-Ingersoll corridor and Quebec battery platform operations.
Bottom-up modeling anchored forecasts to platform-level content-per-vehicle assumptions across propulsion architecture, vehicle class, and regional production cluster dimensions. Top-down validation cross-referenced federal clean fuel standard implementation timelines against provincial zero-emission vehicle mandate trajectories. CAGRs were derived from segment-level growth rate reconciliation across the projection horizon. Industry-specific inputs included caprolactam price volatility indices and glass fiber roving capacity utilization rates.
Several conditions sit outside the modeled scope, including pending Transport Canada MVSS pedestrian impact rule specifications and potential force majeure disruptions at Tennessee and South Carolina glass fiber facilities. Forecasts reflect assumptions about OEM platform launch timing and recycled feedstock certification pathway clarity. Practitioners should monitor Health Canada Chemicals Management Plan additive restriction proposals and Quebec battery enclosure qualification timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
EVA Foam Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Soft PVC Sealing Strip Market