
 Wind Turbine Blade Repair Material Market | 2026-2036
Wind Turbine Blade Repair Material Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Blade Repair Material Market Analytics
China is rewriting competitive dynamics in wind turbine blade repair materials through massive domestic turbine installation and localization mandates for aftermarket supply chains. Henkel AG & Co. KGaA leverages its adhesive technology portfolio to serve both OEM bonding and field repair applications across Asian and European wind corridors. Scott Bader Company Ltd. anchors its position in vinyl ester formulations optimized for marine-environment blade leading-edge erosion. Gurit Holding AG specializes in prepreg and core material systems that extend structural repair lifecycles in offshore installations.
Wind turbine blade repair materials encompass structural adhesives, surface coatings, and composite patches formulated to restore aerodynamic performance and load-bearing integrity to fiber-reinforced polymer blades. Epoxy systems dominate structural repair applications due to their shear strength above 30 MPa and compatibility with glass and carbon fiber substrates, while polyurethane coatings compete aggressively in leading-edge protection where flexibility and impact resistance outweigh absolute strength. Independent Service Providers represent the fastest-growing end-user channel as turbine OEMs outsource maintenance to specialized contractors with rope-access capabilities and blade-specific repair certifications. Thermal curing technology leads installation-scale repairs, though ultraviolet curing systems are displacing conventional methods for minor surface damage where downtime minimization drives purchasing decisions.
Germany's Federal Network Agency, the EU F-Gas Regulation, and REACH compliance requirements collectively shape material specifications by restricting volatile organic compounds and mandating recyclability disclosures in composite repair systems. The EU AI Act and national drone inspection standards are accelerating automated damage detection, which reroutes material demand toward precision-applied repair kits matched to algorithmic defect mapping. Stakeholders must monitor how blade lifetime extension warranties interact with repair material traceability requirements, as insurers and certifiers tighten documentation standards for structural interventions without full component replacement.
Market Dynamics
Rotor diameter scaling beyond 150 meters is forcing material suppliers to reformulate structural adhesives and erosion coatings for cyclic loading regimes that exceed legacy certification thresholds. This dimensional inflection compresses repair cycle intervals and elevates performance specifications for offshore blade maintenance programs.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating demand for low-global-warming-potential coating systems in blade leading-edge protection across North Sea installations.
- Rope-access ISP certification:Specialized contractors with blade-specific repair credentials are expanding addressable market volume by enabling nacelle-level repairs without crane mobilization.
- Ultraviolet curing systems:Field-applied UV-curable resins are compressing minor damage repair downtime from thermal cure cycles, particularly attractive for revenue-sensitive offshore operators.
Market Restraints
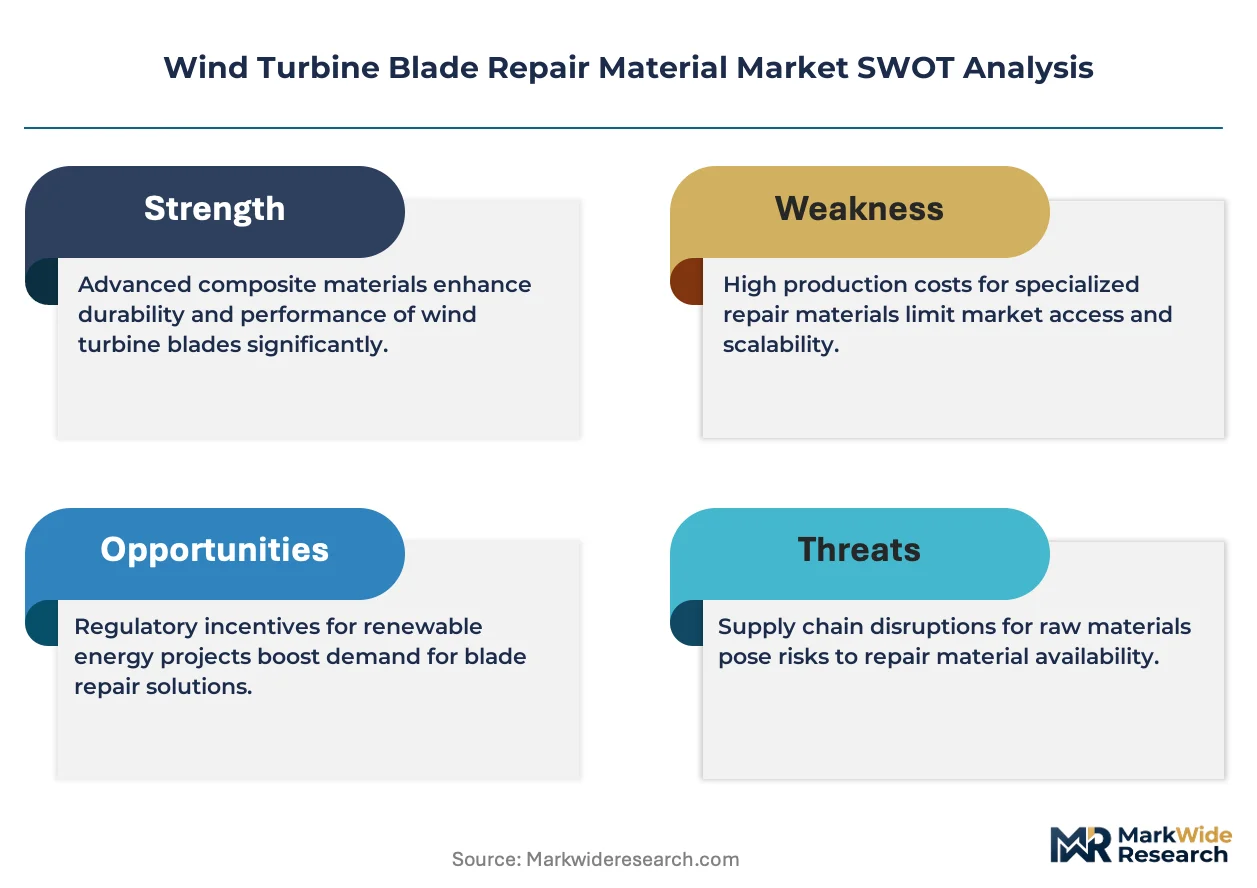
- Bisphenol A epoxy feedstock volatility:Petrochemical input cost swings compress formulation margins and destabilize long-term supply agreements for structural adhesive producers.
- German supply concentration:Aging onshore fleet maintenance demand clusters in a single jurisdiction, creating geographic revenue vulnerability and regulatory single-point-of-failure exposure.
- REACH substance authorization delays:Extended chemical safety assessment timelines block novel repair material commercialization, trapping innovators in multi-year compliance pipelines.
Strategic Opportunities
- Drone-guided precision repair kits:Automated damage detection algorithms from the EU AI Act compliance ecosystem are creating matched material-application workflows for defect-specific intervention protocols.
- China offshore localization mandates:Domestic turbine installation scale is forcing aftermarket supply chain indigenization, opening captive demand for regional material formulators with GB standard certification.
- Blade lifetime extension warranties:Insurer documentation requirements for structural interventions without full replacement are spawning traceable repair material subscription services.
Industry Challenges
- Rope-access technician scarcity:Certified blade repair specialists with composite laminate and adhesive injection competencies command premium wages that inflate ISP operational costs.
- Thermal cure equipment capex:Offshore vessel-mounted heating systems for large-scale structural repairs require capital deployment that strains independent service provider balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Blade Repair Material Market |
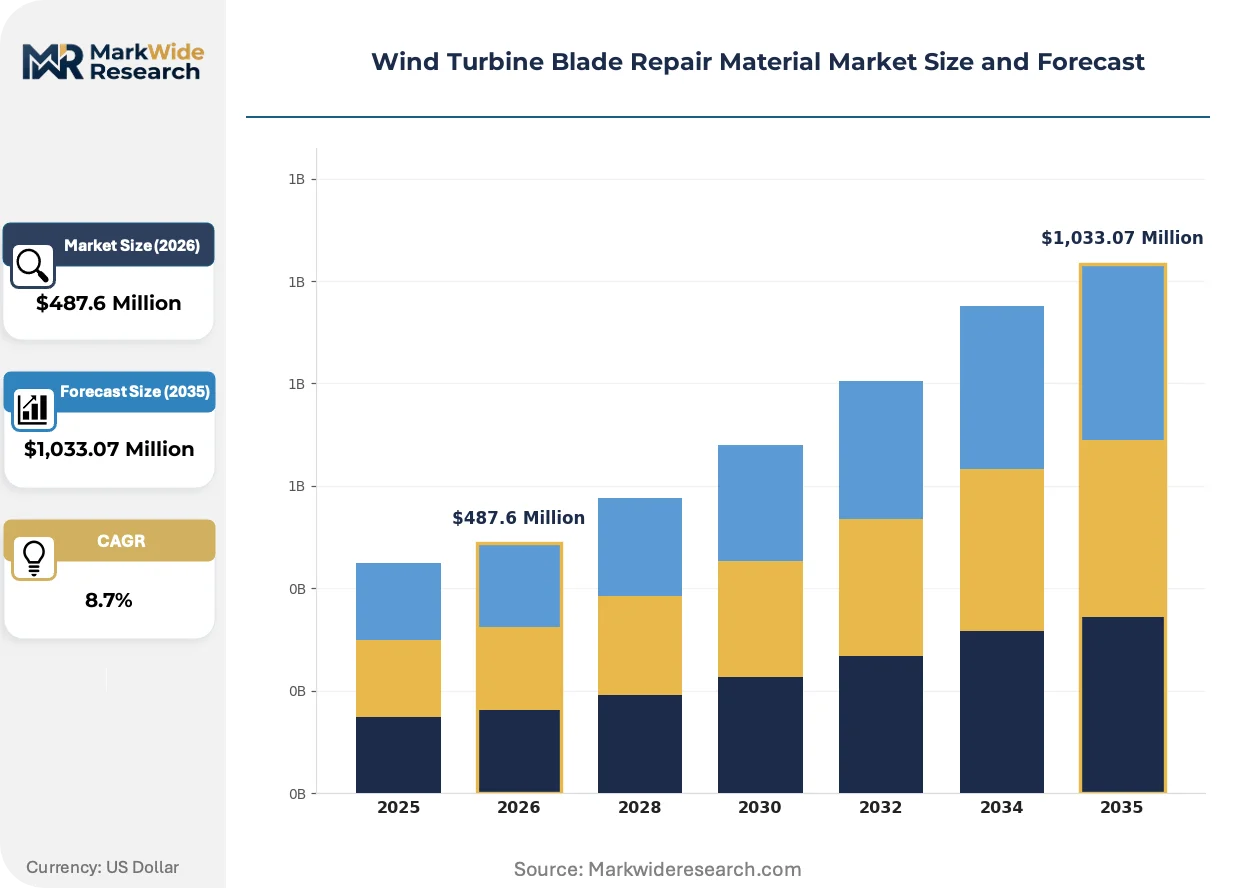
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Epoxy, Polyurethane, Vinyl Ester, Polyester Application: Structural Repair, Surface Coating, Component Replacement, Moisture Sealing Technology: Thermal Curing, Ultraviolet Curing, Injection Molding, Hand Lay-Up End User: OEMs, Independent Service Providers, Energy Companies, Maintenance Contractors |
| Companies Covered | Henkel AG & Co. KGaA, Scott Bader Company Ltd., 3M Company, BASF SE, Hexcel Corporation, Sika AG, Huntsman Corporation, Dow Inc., Gurit Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Blade Repair Material Market Evolving Landscape
Digital inspection infrastructure is collapsing the latency between damage detection and material deployment, compressing procurement cycles and demanding just-in-time repair kit logistics. This convergence is reconfiguring supplier-customer relationships around predictive intervention rather than scheduled maintenance.
Ultraviolet-curable polyurethane coatings are virtualizing minor surface damage repair workflows by eliminating thermal equipment mobilization. Offshore operators with floating turbine assets are adopting these systems for leading-edge erosion remediation during weather windows too brief for conventional cure cycles. The technology is virtualizing geographic constraints on repair scheduling, enabling distributed maintenance capacity without fixed infrastructure.
The EU F-Gas Regulation and parallel national carbon-neutral frameworks are tightening material performance standards for repair cycle durability. Formulators must now demonstrate 20-year service life predictions for coating systems under accelerated marine-environment testing. German certification bodies are extending evaluation protocols, forcing material suppliers to front-load R&D expenditure before market access.
Independent Service Providers are consolidating procurement authority previously held by turbine OEM after-sales divisions. Specialized contractors with blade-specific repair certifications are negotiating direct supply relationships with adhesive and coating manufacturers, disintermediating legacy distribution channels. This concentration is most visible in the North Sea corridor, where ISP fleet scale justifies volume commitments that reshape supplier prioritization.
Wind Turbine Blade Repair Material Market Segmentation

Segmentation in blade repair materials determines procurement workflows, certification requirements, and margin structures across the aftermarket value chain. Material selection, application method, and end-user channel each impose distinct technical and commercial constraints on supplier relationships.
Material Type:
After-sales-service intensity varies sharply by material chemistry, with structural repairs demanding specialized technician certification and environmental controls that surface treatments do not.
- Epoxy:High-shear thermoset systems formulated for load-bearing composite restoration, typically achieving 30+ MPa shear strength on glass and carbon fiber substrates. German North Sea offshore clusters and aging Spanish onshore fleets drive specification intensity, constrained by bisphenol-A feedstock volatility that compresses formulation margins.
- Polyurethane:Elastomeric coating systems optimized for leading-edge erosion protection where flexibility and impact resistance outweigh absolute tensile strength. Danish and UK offshore operators specify these for rotor diameters exceeding 150 meters, with UV-curable variants compressing repair downtime during brief weather windows.
- Vinyl Ester:Marine-grade formulations delivering superior hydrolytic stability for blade leading-edge restoration in salt-laden environments.
- Polyester:Cost-optimized thermoset resins for non-structural cosmetic repairs and temporary protective coatings.
By volume, epoxy leads. By growth pace, polyurethane UV-curable systems are expanding most quickly.
Application:
Cost tier stratification separates structural interventions requiring engineered load-path restoration from surface treatments addressing aerodynamic degradation.
- Structural Repair:Laminate restoration and adhesive bonding of spar caps, shear webs, and root joints using prepreg or vacuum-infusion techniques. German certification bodies extend evaluation protocols for these interventions, forcing 20-year service life demonstrations under accelerated marine testing.
- Surface Coating:Leading-edge protection and cosmetic refinishing systems applied via spray, brush, or robotic deposition. Chinese offshore localization mandates are reshaping specification authority as domestic turbine OEMs indigenize aftermarket supply chains.
- Component Replacement:Prefabricated patch installation for damaged aerodynamic add-ons and lightning protection systems.
- Moisture Sealing:Barrier restoration for blade interiors and root joints to prevent osmotic blistering and core degradation.
Structural repair commands premium pricing. Surface coating shows the steepest expansion trajectory as automated damage detection enables precision intervention.
Technology:
Customer type concentration in Independent Service Providers favors field-deployable curing methods over capital-intensive fixed infrastructure.
- Thermal Curing:Conventional heat-activated polymerization for large-scale structural repairs requiring controlled temperature ramps and post-cure cycles. Offshore vessel-mounted heating systems strain ISP balance sheets with capital deployment demands that OEM service divisions absorb more readily.
- Ultraviolet Curing:Photo-initiated polymerization eliminating thermal equipment mobilization for minor surface damage. Revenue-sensitive North Sea operators adopt these systems for floating turbine maintenance during constrained weather windows.
- Injection Molding:Resin transfer processes for prefabricated repair patch manufacturing.
- Hand Lay-Up:Manual composite lamination for low-volume or access-constrained repair scenarios.
Thermal curing retains volume leadership. UV curing climbs the fastest as drone-guided damage detection matches precision repair kits to algorithmic defect mapping.
End User:
Supply concentration in specialized contractors with rope-access capabilities is disintermediating legacy OEM after-sales channels.
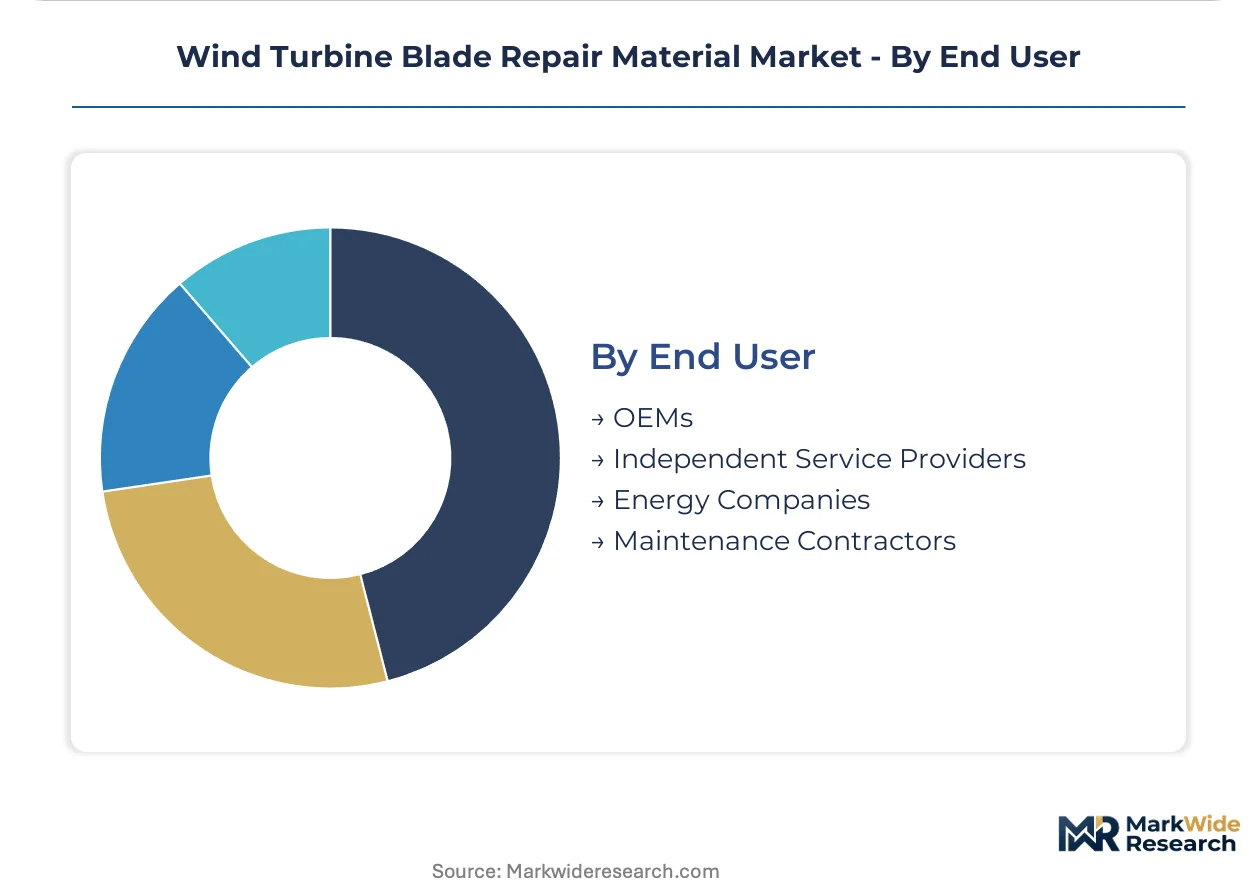
- Independent Service Providers:Specialized contractors with blade-specific repair certifications and rope-access capabilities negotiating direct supply relationships with adhesive and coating manufacturers. ISP fleet scale in the North Sea corridor justifies volume commitments that reshape supplier prioritization.
- OEMs:Turbine manufacturers retaining control over warranty-covered repairs and major component replacements through captive service divisions.
- Energy Companies:Utility and independent power producer self-perform programs for routine maintenance in mature onshore fleets.
- Maintenance Contractors:General wind farm service providers subcontracting blade-specific work to certified specialists.
By procurement volume, OEMs lead. By channel growth, ISPs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand for compliant coating systems, while China's GB standard mandates reshape aftermarket supply chains. Turbine fleet aging and offshore scaling concentrate procurement authority in distinct regional clusters.
Germany
Aging onshore fleets and North Sea offshore clusters drive structural adhesive demand for blades exceeding 150-meter rotor diameters. The Federal Network Agency and REACH compliance requirements mandate 20-year service life demonstrations for marine-environment coating systems. Repair material procurement concentrates in Hamburg and Lower Saxony, where ISP fleet scale justifies direct supply relationships with formulators.
China
Massive domestic turbine installation and localization mandates for aftermarket supply chains are rewriting competitive dynamics. MIIT's GB standard certification requirements and dual carbon goals force regional material formulators to indigenize production. Yangtze River Delta manufacturing clusters are absorbing captive demand as domestic OEMs consolidate specification authority.
United States
Great Plains wind corridors and Gulf of Mexico offshore lease areas require specialized leading-edge protection systems for cyclic loading regimes. FAA coordination protocols for drone inspection standards and state-level renewable portfolio standards shape procurement timelines. Texas and Iowa host the densest concentrations of ISP operations with rope-access capabilities.
United Kingdom
Floating turbine deployments in Scottish waters and Dogger Bank installations compress repair cycle intervals for revenue-sensitive operators. The UK offshore wind sector deal and Maritime and Coastguard Agency safety protocols govern technician certification requirements. Aberdeen and Grimsby anchor the North Sea corridor's ISP fleet consolidation.
Denmark
Legacy onshore turbine maintenance and Baltic Sea offshore expansion sustain demand for UV-curable polyurethane systems. Danish Energy Agency permitting frameworks and national carbon-neutral targets tighten material performance specifications. Copenhagen and Esbjerg host specialized contractors with blade-specific repair certifications.
Wind Turbine Blade Repair Material Market Competitive Landscape
Specialized adhesive formulators and diversified chemical conglomerates split the market between application-specific expertise and feedstock-integrated scale. The vendor base organizes around three strategic archetypes: European engineering specialists with marine-environment certification depth, Asian integrated chemical producers leveraging domestic installation scale, and North American diversified materials groups with aerospace-adjacent composite capabilities. Competitive moves concentrate on capacity co-location with offshore wind clusters and technology licensing for UV-curable formulations.
Within the European specialist tier, Henkel AG & Co. KGaA and Gurit Holding AG exemplify archetypes anchored in adhesive technology and prepreg systems respectively. Scott Bader Company Ltd. occupies a position among marine-grade formulation specialists with vinyl ester expertise. These entities represent distinct competitive vectors: KGaA-structured German industrials with OEM bonding heritage, Swiss holding-company organizations with offshore structural lifecycle extension focus, and UK-limited specialists with salt-environment optimization.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Scott Bader Company Ltd. |
| 3M Company |
| BASF SE |
| Hexcel Corporation |
| Sika AG |
| Huntsman Corporation |
| Dow Inc. |
| Gurit Holding AG |
| Others |
Value Network & Pricing Analysis
Rotterdam-Hamburg barge freight corridors transmit petrochemical feedstock cost volatility directly into epoxy formulation margins, concentrating pricing power among German and Belgian adhesive producers while forcing North Sea offshore operators into premium-tier procurement for certified marine-grade systems.
Pricing Analysis
Geographic price spreads of 15-25% separate German North Sea contracts from Mediterranean spot purchases, reflecting certification-grade differentiation and logistics premiums. Three-tier pricing structure across OEM-certified, ISP-standard, and economy-refurbishment levels anchors the market, with REACH compliance tier and volume scale as primary differentiation drivers. Cost compression in economy-grade polyester resins is intensifying because Chinese domestic capacity expansion feeds export spot markets. Independent Service Providers exhibit highest price sensitivity due to balance-sheet constraints, while floating-turbine operators show lowest sensitivity given revenue-at-risk from downtime.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate supplier-finance arrangements for Independent Service Providers, straining working capital across formulation tiers. Manufacturing concentrates in Germany, China, and the Netherlands, with bisphenol-A, carbon fiber prepreg, and UV photoinitiators as critical input dependencies. Single-source vulnerability haunts marine-grade vinyl ester supply following consolidation among European specialty chemical producers. Distribution runs through direct OEM partnerships and ISP consortium buying groups, bypassing traditional industrial chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: REACH and EU F-Gas compliance creates decade-long certification pipelines that lock out unqualified competitors.
For Market Incumbents: Harden marine-environment certification depth by acquiring UV-curable formulation specialists before Chinese GB-standard competitors consolidate Yangtze Delta capacity. Threat substitution from thermoplastic repair patches demands accelerated R&D in hybrid epoxy-urethane systems. Channel control through captive ISP training academies secures specification authority. For New Entrants and Emerging Players: Establish a beachhead in drone-guided precision repair kits matched to automated damage detection protocols, the most penetrable white-space segment. Target Baltic Sea floating turbine maintenance where UV-curable polyurethane demand outpaces established supply. Go-to-market through direct ISP fleet partnerships rather than OEM after-sales channels. For Investors and Strategic Acquirers: Regional formulators with GB-standard certification and existing MIIT relationships present the optimal acquisition archetype for China offshore localization mandates. Long-term viability hinges on 20-year coating lifecycle demonstration capabilities under accelerated marine testing. Signal to monitor: EU AI Act enforcement timelines driving precision-repair kit procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A Feedstock | Henkel and BASF SE secure margin stability against petrochemical volatility through captive epoxy precursor supply. |
| UV-Curable Formulation Licensing | Gurit Holding AG accelerates technology transfer to Chinese partners under MIIT localization mandates. |
| ISP Certification Academy Expansion | Scott Bader Company Ltd. locks in specification authority through rope-access technician training pipelines. |
| Drone-Guided Repair Kit Development | 3M Company matches precision material deployment to EU AI Act-compliant defect mapping algorithms. |
| North Sea Logistics Hub Consolidation | Sika AG reduces lead times for offshore vessel-mounted thermal cure equipment through Hamburg port co-location. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including blade repair technicians with rope-access certifications, procurement directors at Independent Service Providers, adhesive formulation chemists, and offshore wind farm operations managers. Secondary validation drew from ECHA substance authorization databases, EU F-Gas Regulation implementation reports, customs trade flows for epoxy resin imports, and SEC filings from listed chemical conglomerates. Bottom-up repair volume estimates triangulated against top-down turbine fleet aging models.
Calibration against historical repair cycle frequencies and rotor diameter scaling curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass material chemistry tier, application type, curing technology, and end-user channel concentration. CAGRs derived from installer growth rates, fleet age distribution shifts, and regulatory compliance cost pass-through assumptions. Offshore vessel-day rates and technician wage inflation served as industry-specific forecast inputs.
Stress conditions across bisphenol-A price volatility, REACH authorization delays, and rope-access labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about turbine OEM warranty structures and ISP consolidation trajectories. Macroeconomic contraction, accelerated EU F-Gas phase-down schedules, or breakthrough thermoplastic repair technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Polycarbonate Composites Market
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market
Composite Materials
Global Carbon Fiber Resin Market
Composite Materials
Case Material Market
Composite Materials
Composite Cans Market
Composite Materials
High Performance Composites Market
Composite Materials
Tow Prepreg Market
Composite Materials
Composite Market
Composite Materials
Composite Drums Market
Composite Materials
Metal Matrix Composites (Mmcs) Market
Composite Materials
Plastic Composites Market
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Isostatic Graphite Market
Composite Materials
Hybrid Composites Market
Composite Materials
Wood Plastic Composite (WPC) Market