
 Turbine Blade Material Market | 2026-2036
Turbine Blade Material Market Size, Share, and Industry Trends Forecast 2026-2036
Turbine Blade Material Market Analytics
Modular blade architecture is shifting how OEMs configure material packages, with some suppliers bundling resin systems, fiber preforms, and adhesive kits into integrated sub-assemblies rather than selling raw materials separately. Toray Industries leverages its carbon fiber leadership to anchor premium composite supply chains for next-generation offshore blades. Evonik sustains competitive differentiation through specialized thermoplastic resin formulations that reduce cycle times in blade molding operations.
Turbine blade materials encompass engineered substances—superalloys, fiber-reinforced composites, titanium alloys, and coated steels—selected for fatigue resistance, aerodynamic efficiency, and dimensional stability under cyclic mechanical and thermal loads, serving primarily to convert wind or gas flow into rotational energy with minimal mass penalty. Superalloys dominate land-based gas turbine hot sections where creep resistance at elevated temperatures governs service life, while composites represent the fastest-expanding category as rotor diameters exceed 100 meters and mass reduction becomes critical for hub loading. Additive manufacturing remains nascent for blade production but commands disproportionate R&D investment due to its potential for geometric optimization in root fittings and leading-edge erosion shields.
The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in blade manufacturing processes, while China's MIIT enforces GB standards for wind turbine component recyclability that reshape material selection criteria. The FAA and EMA frameworks indirectly influence aerospace turbine blade certification requirements that propagate into material traceability standards. Stakeholders must monitor evolving extended producer responsibility mandates that could obligate blade manufacturers to finance end-of-life material recovery infrastructure.
Market Dynamics
Offshore wind farm developers are demanding blade lengths exceeding 120 meters, forcing material suppliers to reconfigure fiber-resin systems for stiffness-to-weight ratios that earlier land-based designs never required.
Growth Catalysts
- EU Green Deal:Binding emissions caps on turbine manufacturing are accelerating composite adoption over metallic alternatives in European supply chains.
- China's dual carbon goals:Provincial renewable energy targets are concentrating blade production capacity in Jiangsu and Guangdong provinces.
- Hybrid carbon-glass fiber layups:These engineered preforms are enabling 15-20% mass reduction in root sections without sacrificing fatigue performance.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations are compressing margins for blade molders locked into fixed-price supply contracts.
- Carbon fiber supply concentration:Japanese and Korean precursor producers control 70% of aerospace-grade fiber output, creating allocation risk for wind energy buyers.
- Recyclability technical limits:Thermoset composites cannot be remelted, forcing landfill disposal or energy recovery for end-of-life blades.
Strategic Opportunities
- India's offshore wind auctions:The Ministry of New and Renewable Energy's 30 GW target by 2030 opens virgin territory for blade material suppliers.
- Thermoplastic resin systems:Evonik and Arkema formulations enable welding rather than adhesive bonding, cutting cycle times and repair complexity.
- Extended producer responsibility mandates:Germany's packaging law model is propagating to blade components, creating closed-loop material recovery services.
Industry Challenges
- Non-destructive testing technician shortage:Ultrasonic and thermography inspection of 80-meter-plus blades requires specialized certification that training programs have not scaled.
- Type certification timelines:DNV and TÜV Rheinland validation protocols for new material systems extend 18-24 months, delaying commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbine Blade Material Market |
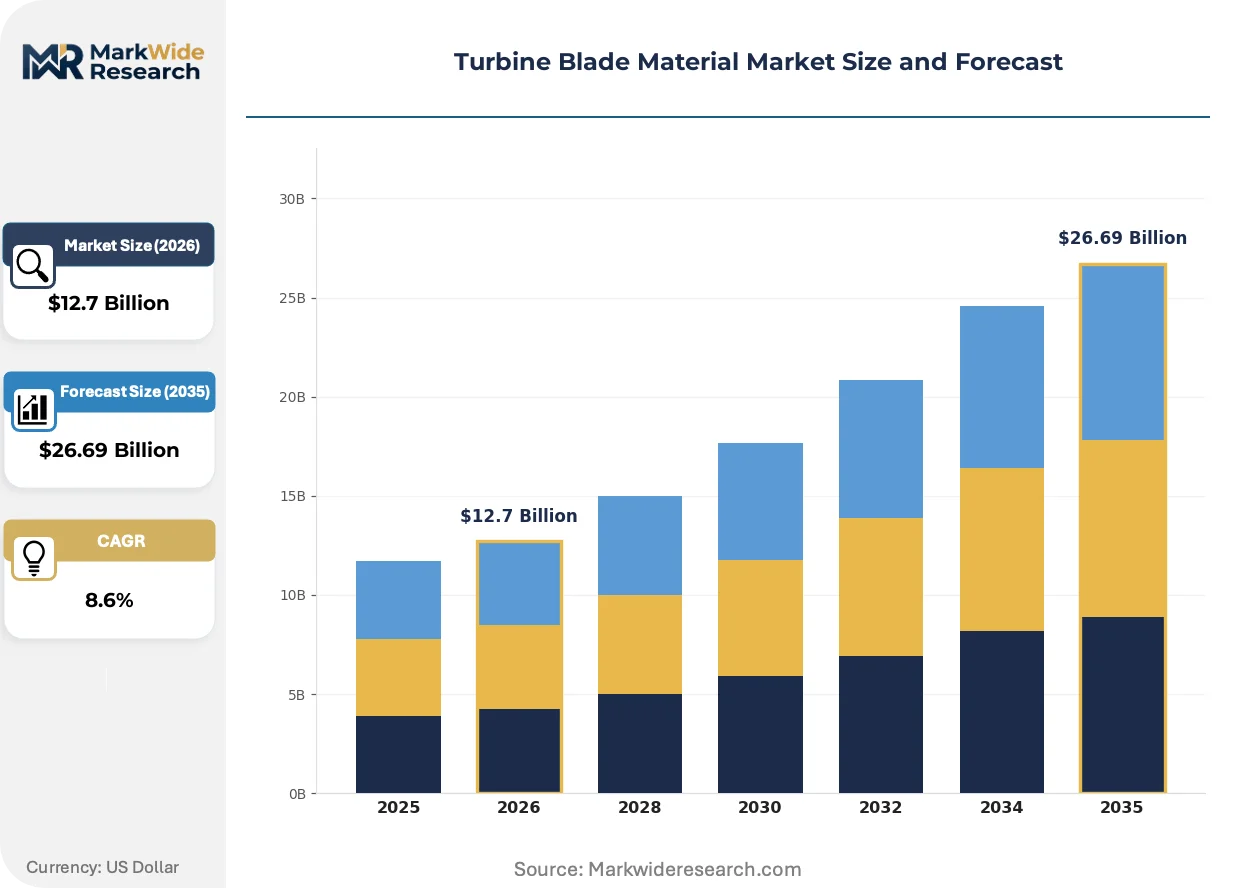
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Superalloys, Composites, Titanium Alloys, Steel End Use Industry: Aerospace, Power Generation, Marine, Industrial Manufacturing Process: Additive Manufacturing, Casting, Forging, Machining Coating Type: Thermal Barrier, Corrosion-Resistant, Wear-Resistant, Others |
| Companies Covered | Toray Industries, Exxon Mobil Corporation, Evonik, China Jushi Co., Ltd., China National Building Material Group Corporation, Henkel Group, Sika AG, 3M, Gurit Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbine Blade Material Market Evolving Landscape
Material innovation is bifurcating between incremental composite optimization for immediate offshore deployment and radical thermoplastic architectures that promise end-of-life circularity.
Preform manufacturing is consolidating around automated fiber placement systems that deposit unidirectional tapes with precision exceeding hand layup. Vestas and Siemens Gamesa are qualifying these systems for 14-meter root diameter blades. This consolidation is compressing the supplier base from hundreds of regional preformers to a dozen automated production lines.
China's MIIT GB standards for wind turbine component recyclability are forcing OEMs to document material composition down to the resin formulation level. Blade manufacturers must now submit end-of-life recovery plans before type certification. European suppliers with established recycling partnerships are capturing premium positioning in Chinese joint ventures.
Buyers are unbundling blade supply contracts from turbine installation agreements, creating direct procurement relationships with material specialists. Goldwind and Envision are negotiating resin and fiber pricing separately from blade molding services. This disintermediation is most advanced in Denmark, where developer Orsted maintains approved supplier lists for sub-component tiers.
Turbine Blade Material Market Segmentation
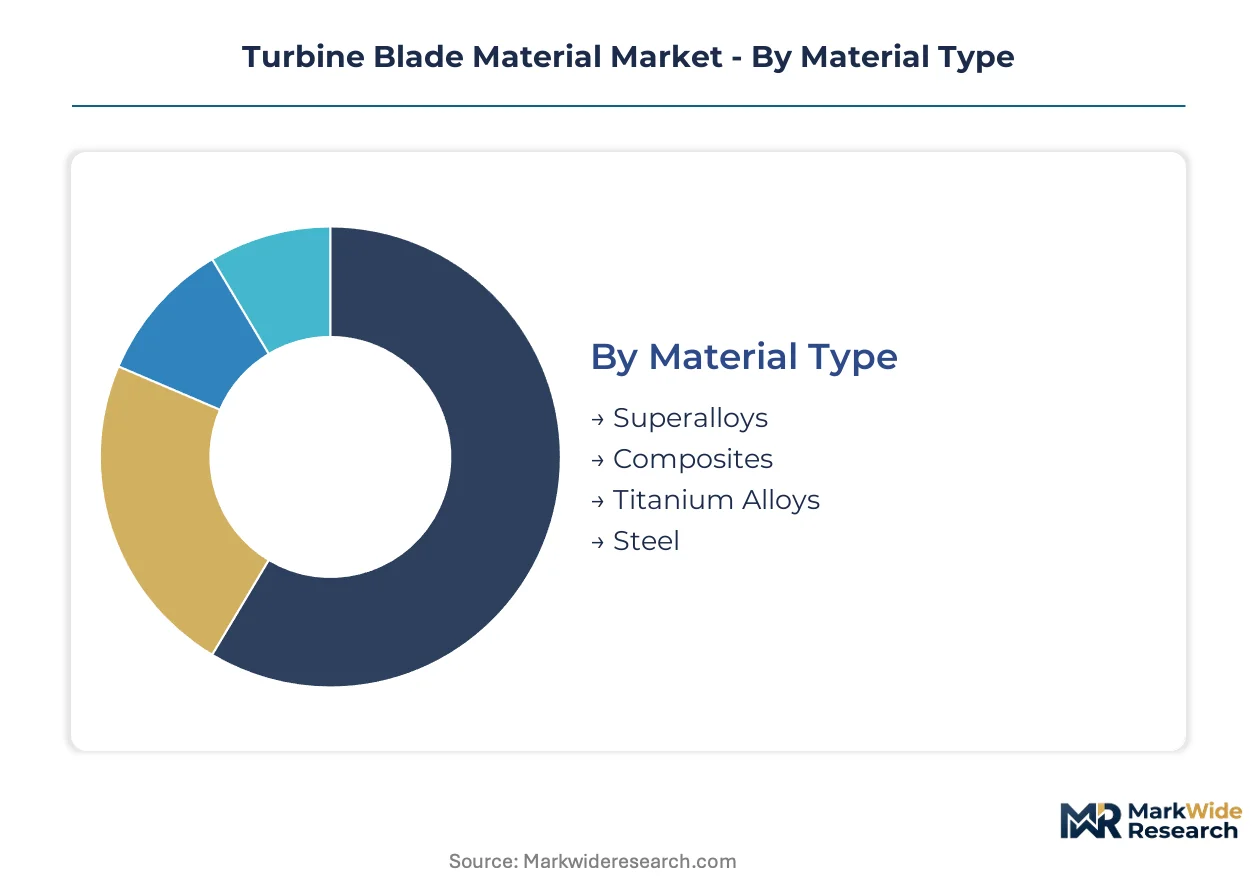
Material selection in turbine blades governs fatigue life, thermal limits, and recyclability obligations that now shape procurement decisions. Segmentation reveals where premium performance commands price premiums versus where volume throughput drives supplier economics.
Material Type:
Volume applications favor cost-engineered solutions while premium niches absorb advanced formulations that extend service intervals.
- Superalloys:Nickel-cobalt matrices deliver creep resistance above 800°C in gas turbine hot sections. Power Generation in the United States and Germany absorbs the majority of demand as combined-cycle plants extend firing temperatures for efficiency gains.
- Composites:Glass and carbon fiber reinforced polymers dominate rotor diameters exceeding 100 meters where mass reduction becomes critical for hub loading. Offshore wind developers in China and Denmark are specifying hybrid carbon-glass layups for 120-meter-plus blades to manage tip deflection without structural failure.
- Titanium Alloys:Alpha-beta microstructures provide intermediate density for aerospace compressor stages where temperature exposure stays below superalloy thresholds. Boeing and Airbus engine programs specify Ti-6Al-4V for intermediate-pressure rotors.
- Steel:Martensitic and precipitation-hardened grades retain cost advantage for root fittings and bearing housings where dimensional stability outweighs weight penalties. Industrial gas turbine manufacturers in India specify forged steel for frames below 50 MW output.
Today's leader: Composites. Tomorrow's challenger: Superalloys in hydrogen-fired turbine retrofits.
End Use Industry:
Application requirements diverge sharply between cyclic fatigue regimes and steady-state thermal exposure.
- Aerospace:FAA and EMA certification protocols mandate material traceability through melt-to-blade documentation. Narrow-body engine programs concentrate procurement with Safran and GE Aviation supply chains.
- Power Generation:Combined-cycle operators specify thermal barrier coatings for blades facing 1,400°C firing temperatures. China's MIIT enforces GB standards for component recyclability that reshape alloy selection in provincial manufacturing clusters.
- Marine:Salt-laden environments demand corrosion-resistant coatings on high-strength substrates. Shipbuilders in South Korea specify duplex stainless steel for naval gas turbine applications.
- Industrial:Mechanical drive turbines for oil and gas compression prioritize availability over peak efficiency. Saudi Aramco maintenance schedules favor standardized steel grades with regional forging capacity.
Aerospace commands the highest specification density. Power Generation offers the steepest expansion trajectory as renewable intermittency drives gas turbine cycling.
Manufacturing Process:
Process selection balances geometric freedom against production velocity and metallurgical integrity.
- Additive Manufacturing:Powder bed fusion enables topology-optimized root geometries impossible with conventional methods. Repair operations for aerospace blades adopt directed energy deposition for tip restoration.
- Casting:Directional solidification and single-crystal growth dominate high-pressure turbine airfoils where grain boundaries initiate creep failure. Howmet and PCC Structurals operate the majority of aerospace-qualified vacuum casting capacity.
- Forging:Closed-die hammer and press forging align grain flow with stress trajectories in rotating components. Japan's JSW and Korea's Doosan supply forged discs for GE and Siemens heavy-duty gas turbines.
- Machining:Five-axis milling finishes near-net shapes to aerodynamic tolerances below 25 microns. Grinding operations for fir-tree root forms require specialized creep-feed equipment concentrated in Germany and Switzerland.
Casting retains aerospace dominance. Additive Manufacturing is gaining share fastest in repair and prototyping workflows.
Coating Type:
Surface engineering extends base material capability without redesigning bulk substrates.
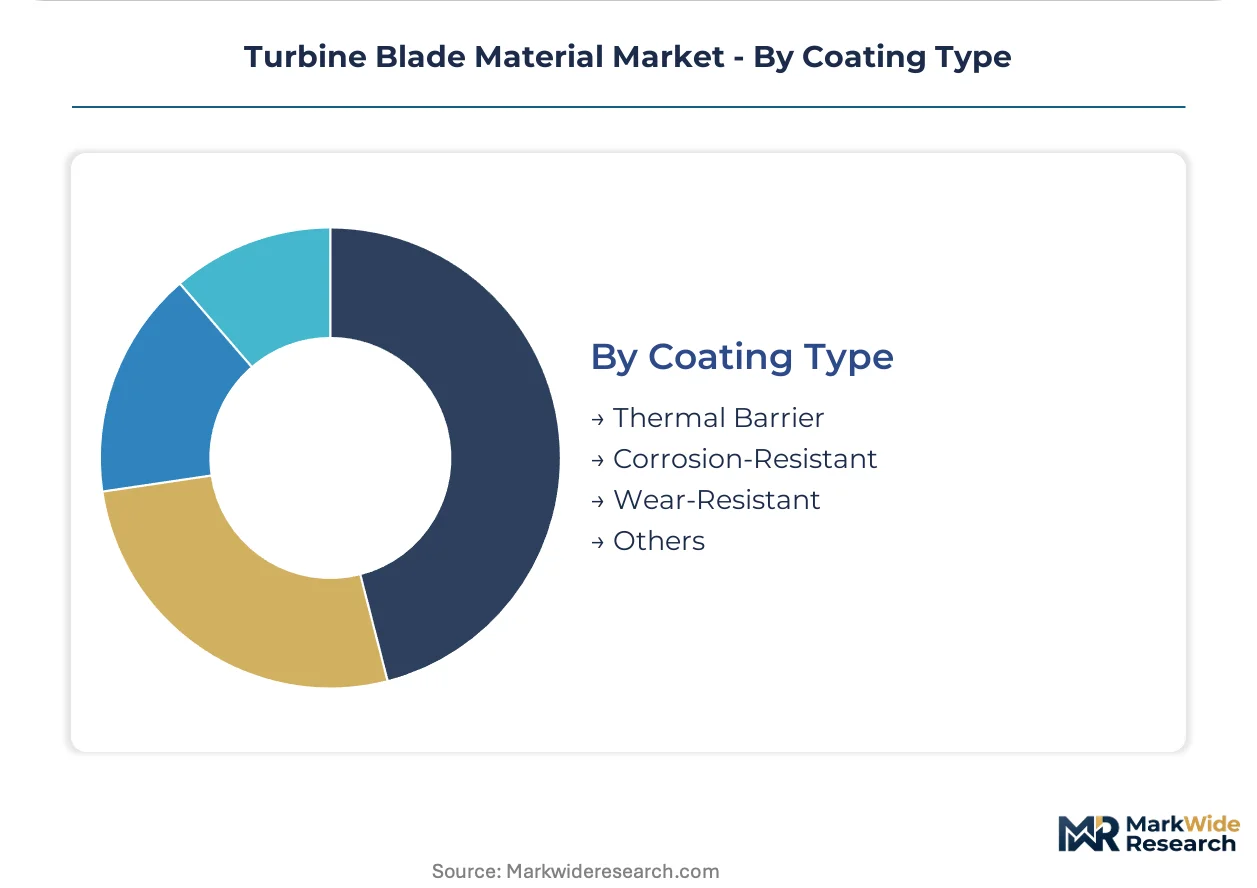
- Thermal Barrier:Yttria-stabilized zirconia ceramic topcoats reduce metal temperature by 100-150°C in combustion-exposed blades. EB-PVD and plasma spray processes compete for aerospace and power generation contracts.
- Corrosion-Resistant:Aluminide and MCrAlY bond coats protect against hot corrosion from sulfur and vanadium in residual fuel oils. Marine and industrial turbines in coastal environments specify multi-layer systems.
- Wear-Resistant:Hard chrome alternatives and diamond-like carbon reduce erosion in compressor stages facing particulate ingestion. Offshore wind blade leading edges adopt polyurethane erosion shields.
- Others:Environmental barrier coatings for ceramic matrix composites and anti-fouling treatments for underwater applications fill specialized niches. NASA programs test rare-earth silicate coatings for next-generation turbofans.
Thermal Barrier coatings command the premium pricing tier. Corrosion-Resistant formulations are expanding most quickly as sour gas and biomass firing spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark pioneered commercial wind turbine manufacturing in the 1970s, establishing the material specifications and certification protocols that now govern blade production across three continents. German and Chinese industrial clusters subsequently scaled composite manufacturing to meet utility-scale deployment timelines.
China
Provincial renewable energy targets in Jiangsu and Guangdong are concentrating blade molding capacity along the eastern seaboard. MIIT enforces GB standards for component recyclability that require OEMs to document resin formulations prior to type certification. The Yangtze River Delta hosts the majority of carbon fiber preform manufacturing partnerships between domestic developers and European material suppliers.
Germany
Offshore wind auctions in the North Sea and Baltic are specifying 120-meter-plus blade lengths that exceed domestic mold capacity. The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in manufacturing processes, accelerating thermoplastic resin qualification programs. Lower Saxony and Schleswig-Holstein anchor the supply chain for hybrid carbon-glass fiber root sections.
United States
IRA production tax credits are reshoring blade manufacturing to serve Great Plains and Gulf Coast wind farms. The FAA maintains material traceability standards that propagate into utility-scale turbine certification through DNV validation protocols. Texas and Iowa host the primary mold fabrication facilities for domestic OEM supply chains.
Denmark
Orsted's direct procurement model disintermediates material specialists from blade molders, creating approved supplier lists for resin and fiber tiers. The country's national energy regulator enforces extended producer responsibility mandates that obligate manufacturers to finance end-of-life recovery infrastructure. Copenhagen and Aalborg retain concentrated R&D activity for thermoplastic welding technologies.
India
The Ministry of New and Renewable Energy's 30 GW offshore wind target by 2030 is attracting material suppliers to virgin territory without established blade manufacturing infrastructure. The Central Electricity Authority mandates component localization thresholds that reshape import strategies for fiber and resin systems. Gujarat and Tamil Nadu are emerging as the primary coastal clusters for initial fabrication capacity.
Turbine Blade Material Market Competitive Landscape
Premium-margin players sit above commodity-margin players across resin formulation sophistication and fiber grade certification. The market exhibits tiered concentration: a handful of Japanese and Korean precursor producers control aerospace-grade carbon fiber output, while hundreds of regional preformers compete on glass fiber volume. Three strategic archetypes dominate: integrated chemical conglomerates with captive resin production, specialized composite material formulators, and diversified industrial adhesives suppliers. Capacity expansion and strategic partnerships constitute the primary competitive moves, with OEMs unbundling blade contracts to negotiate directly with material tiers.
Among Japanese industrial conglomerates, Toray Industries anchors premium composite supply chains through carbon fiber leadership. German specialty chemical players Evonik and Henkel occupy positions across thermoplastic resin and adhesive formulation tiers. Chinese state-affiliated building material groups exemplify scale-driven volume supply for domestic wind farm deployment.
| Leading Market Players |
|---|
| Toray Industries |
| Exxon Mobil Corporation |
| Evonik |
| China Jushi Co., Ltd. |
| China National Building Material Group Corporation |
| Henkel Group |
| Sika AG |
| 3M |
| Gurit Holding AG |
| Others |
Value Network & Pricing Analysis
Carbon fiber precursor costs cascade through aerospace-grade certification tiers into blade root section pricing, with Japanese and Korean producers anchoring premium quotations while Chinese glass fiber suppliers compete on volume throughput for 80-meter land-based rotors.
Pricing Analysis
Three-tier pricing structure across aerospace-grade carbon fiber, industrial-grade glass fiber, and commodity steel root fittings governs procurement negotiations. Price differentiation hinges on DNV type certification status and volume scale, with offshore developers absorbing premium resin formulations for 120-meter blades. Cost compression in glass fiber preforms intensifies as Jiangsu molders expand automated fiber placement capacity. Utility-scale wind farm operators exhibit highest price sensitivity, while aerospace turbine OEMs prioritize fatigue performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated material sub-assemblies, bypassing regional preformer networks. Supply concentrates in Japan, South Korea, and China for carbon fiber precursor, epoxy resin, and glass fiber roving respectively. Raw material dependencies encompass acrylonitrile feedstock, bisphenol-A derivatives, and boron-free E-glass formulations. Single-source vulnerability in aerospace-grade carbon fiber allocation creates procurement risk for offshore wind developers competing with aviation programs. Distribution runs through approved supplier lists maintained by Orsted and domestic Chinese developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal emissions caps and China's MIIT recyclability mandates are accelerating material substitution timelines beyond organic demand curves.
For Market Incumbents: To counter thermoplastic resin disruption from Evonik and Arkema, Toray Industries and Henkel should deepen backward integration into precursor manufacturing and secure DNV certification for 14-meter root diameter preforms. Captive supply of carbon fiber tow and adhesive formulation R&D investment represent critical defensive levers against cycle time compression. For New Entrants and Emerging Players: Launch via direct procurement relationships with India's MNRE offshore wind auction winners, targeting Gujarat and Tamil Nadu coastal clusters lacking established blade infrastructure. Thermoplastic welding technology partnerships and end-of-life recovery service bundling offer the most penetrable entry angles against thermoset incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where automated fiber placement capacity scarcity meets 120-meter-plus blade demand from North Sea developers. Long-term viability favors specialists with MIIT GB standard compliance and European recycling partnerships. Watch for inflection signals in India's 30 GW offshore wind tender awards as capacity allocation indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Toray Industries secures aerospace-grade fiber allocation against wind energy buyer competition. |
| Thermoplastic Resin Qualification Programs | Evonik reduces blade molding cycle times under EU F-Gas Regulation constraints. |
| Automated Fiber Placement Scale-Up | Vestas and Siemens Gamesa compress supplier base from hundreds to dozen production lines. |
| End-of-Life Recovery Infrastructure Buildout | Orsted's extended producer responsibility mandates create closed-loop material services in Denmark. |
| Indian Joint Venture Formation | European suppliers capture premium positioning in Gujarat and Tamil Nadu coastal clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blade OEM procurement directors, resin formulator R&D leads, carbon fiber precursor plant managers, and offshore wind farm developers with secondary validation against customs trade data, MIIT GB standard filings, DNV certification registries, and SEC disclosures from listed material suppliers. Bottom-up volume estimates from individual production facilities reconciled against top-down demand projections from national renewable energy targets.
Comparable historical periods anchored growth trajectory assumptions across the projection horizon, with segmentation modeling across material type, end-use industry, manufacturing process, and coating specification dimensions. CAGRs derived from regression analysis of capacity expansion announcements and procurement contract volumes. Industry-specific inputs encompassed blade length specifications from offshore auction documentation and resin formulation disclosures required under Chinese recyclability standards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios or carbon fiber allocation shocks to aerospace programs. Periodic stress-testing of base assumptions is recommended given regulatory momentum behind extended producer responsibility mandates and thermoplastic substitution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
China Marine Composites Market
Composite Materials
Structural Composites Market
Composite Materials
Global FRP Vessels Market
Composite Materials
Phenolic Panel Market
Composite Materials
Composite Cans Market
Composite Materials
Global Wind Turbine Composites Material Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Global Sports Composites Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Carbon Composites Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market