
 Thermoplastics Market | 2026-2036
Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastics Market Analysis
Multi-source resin procurement is recalibrating how compounders manage price volatility and supply security across the value chain. BASF SE leverages its integrated Verbund production system to sustain margin stability in engineering-grade polyamides. SABIC anchors its position through petrochemical feedstock control and specialized high-heat polycarbonate grades for automotive electrification. Covestro AG differentiates via optical-grade polycarbonate leadership and regional production flexibility.
Thermoplastics are polymers that soften upon heating and harden when cooled, enabling repeated melt-processing through injection molding, extrusion, or blow molding without cross-linking degradation; their molecular structure consists of linear or branched polymer chains with melt temperatures typically ranging from 120°C to 340°C depending on resin chemistry. Polypropylene dominates volume demand across packaging films and automotive interior components due to its balance of stiffness, chemical resistance, and low density. Polyethylene, split between high-density and linear low-density grades, occupies mature commodity positions where margin pools concentrate in metallocene-catalyzed premium copolymers for flexible packaging. Injection molding as a processing method leads value capture in precision automotive and electronics applications, while 3D printing represents the fastest-growing processing avenue for customized healthcare implants and aerospace brackets.
The US EPA oversees volatile organic compound emissions from thermoplastics processing facilities under Clean Air Act provisions, while the EU REACH regulation restricts phthalate plasticizers and certain flame retardants in consumer-facing applications. China's SAMR enforces GB standards for food-contact plastics and builds compliance costs into import specifications. Japan's METI promotes chemically recyclable thermoplastics through its Green Innovation Fund, redirecting R&D budgets toward closed-loop polymer systems. Stakeholders must monitor how diverging chemical safety thresholds between jurisdictions fragment formulation strategies and force regional SKU proliferation.
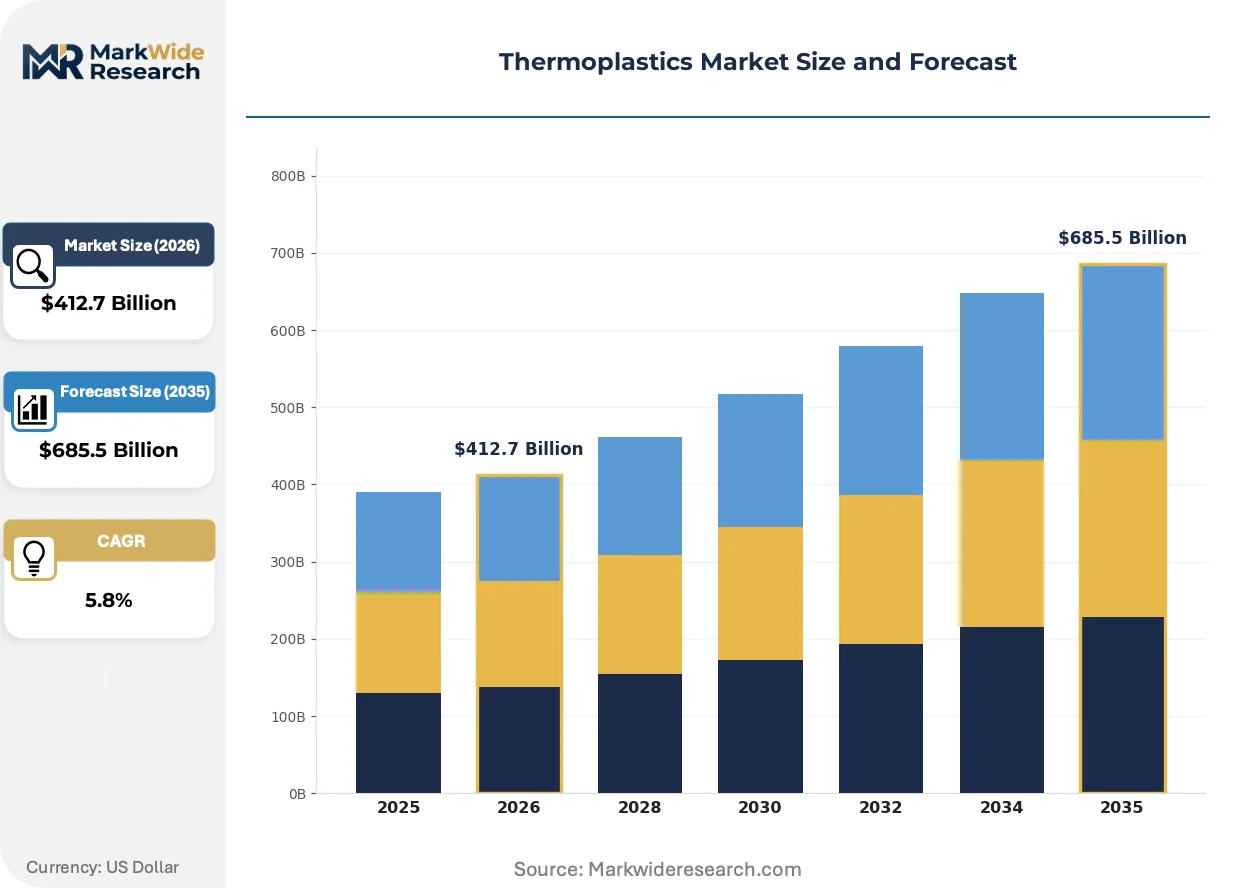
Market Dynamics
Automotive lightweighting mandates are compressing metal-to-plastic substitution timelines as OEMs face fleet emission targets, while China's petrochemical capacity expansion concentrates feedstock supply in East Asian manufacturing corridors.
Growth Catalysts
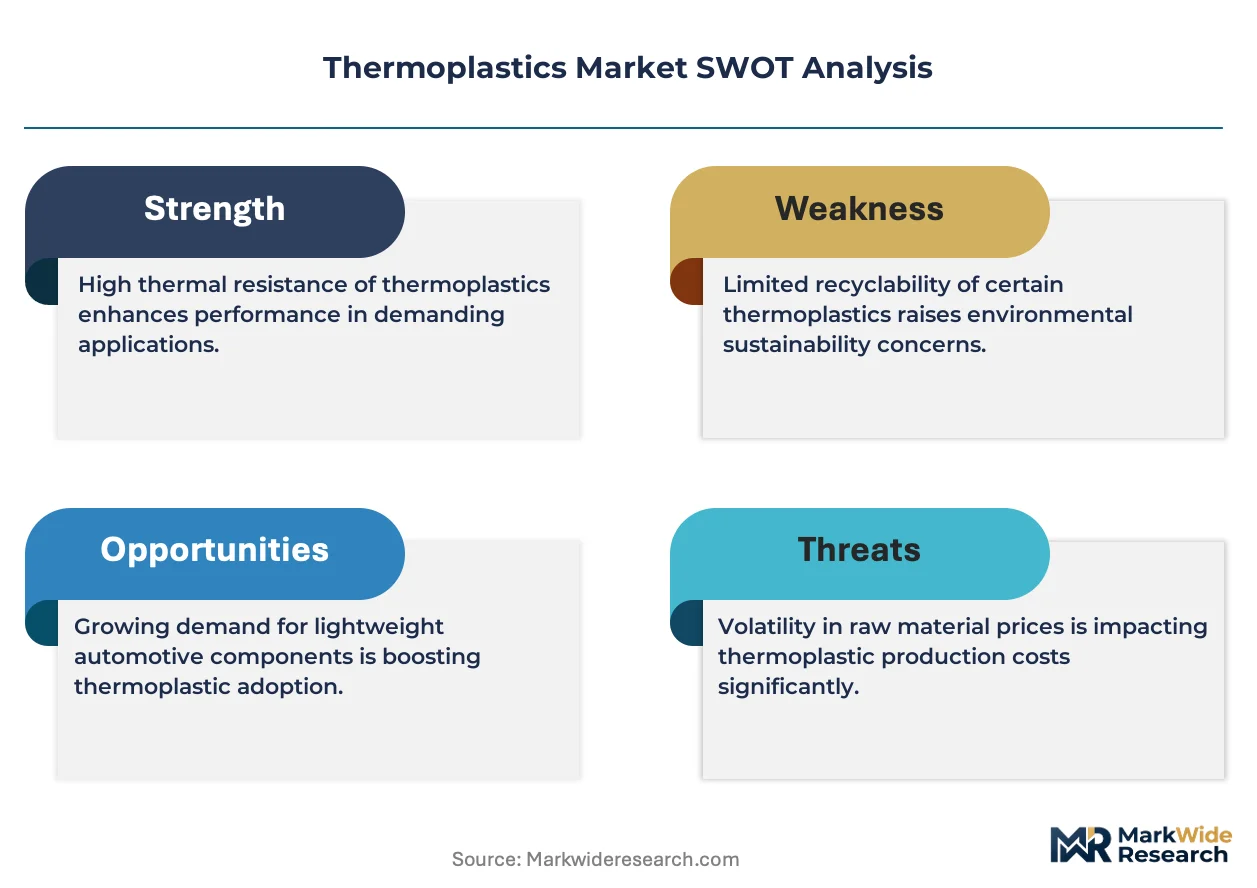
- REACH chemical safety framework:The EU's tightening restrictions on legacy plasticizers and flame retardants are accelerating formulation upgrades toward compliant high-performance grades in consumer electronics.
- Injection molding precision:Automotive electrification modules demand tighter tolerances, pulling capital toward advanced process control systems that reduce cycle times.
- Yangtze River Delta cluster:Concentrated polymer compounding capacity in China's petrochemical corridor lowers logistics costs for Asian automotive and appliance manufacturers.
Market Restraints
- Crude oil volatility:Naphtha feedstock costs swing with energy markets, compressing margin predictability for commodity polyethylene and polypropylene producers.
- Medical-grade certification timelines:China's NMPA biocompatibility testing protocols extend qualification periods for healthcare thermoplastics by 18-24 months versus industrial grades.
- Aluminum battery enclosures:Electric vehicle thermal management systems favor metal solutions where heat dissipation exceeds polymer capabilities above 150°C continuous operation.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are drawing compounding investments to serve smartphone and appliance molding demand.
- 3D printing filament:Aerospace bracket and dental implant applications favor laser-sintered polyamide powders over subtractive machining for complex geometries.
- METI Green Innovation Fund:Japan's chemically recyclable thermoplastics program redirects R&D budgets toward closed-loop polymer systems with depolymerization pathways.
Industry Challenges
- Process technician scarcity:Advanced twin-screw extrusion and reactive compounding require specialized training that outpaces vocational pipeline output in mature economies.
- Multi-jurisdiction formulation:Diverging GB standards, REACH restrictions, and FDA food-contact rules force regional SKU proliferation that fragments production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastics Market |
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $685.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polystyrene, Polyvinyl Chloride, Polyethylene Application: Automotive Components, Consumer Goods, Packaging, Electronics End User: Construction, Healthcare, Aerospace, Household Processing Method: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | BASF SE, SABIC, Celanese Corporation, DuPont de Nemours, Inc., LyondellBasell Industries NV, Covestro AG, Arkema Group, Asahi Kasei Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastics Market Emerging Trajectories
Digital manufacturing integration and circular material flows are restructuring how compounders design, produce, and reclaim thermoplastic products across automotive, healthcare, and packaging value chains.
Advanced process simulation software is unifying mold flow analysis with real-time cavity pressure monitoring. Tier-one automotive suppliers deploy these integrated platforms to reduce warpage defects in glass-filled polyamide engine covers. The technology is unifying design and production engineering functions that previously operated in sequential silos, compressing development cycles.
REACH Annex XVII restrictions on short-chain chlorinated paraffins entered enforcement phases during 2023-2024. Compounders serving wire and cable applications face reformulation mandates for halogen-free flame retardant systems. European appliance manufacturers are qualifying phosphorus-nitrogen intumescent alternatives ahead of downstream compliance deadlines.
Direct polymer procurement from integrated petrochemical producers is displacing distributor intermediaries in high-volume automotive programs. Tier-two molders in Germany and the US Midwest now negotiate resin supply agreements that bypass traditional compounder channels. This pattern concentrates most visibly in polypropylene bumper and interior trim supply chains where annual offtake volumes exceed 5,000 metric tons.
Thermoplastics Market Segmentation
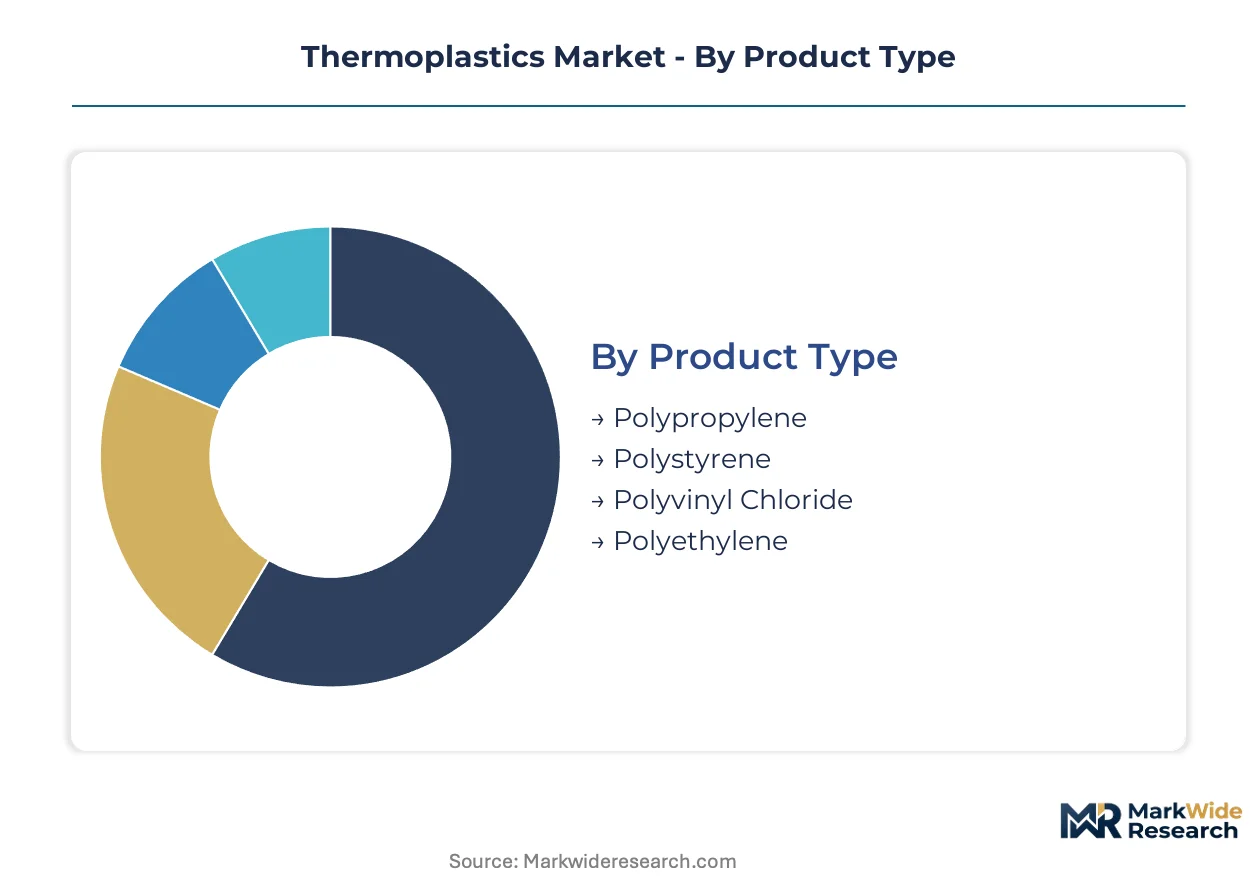
Thermoplastics demand fragments across resin chemistry, conversion technology, and end-use specifications that dictate thermal performance and regulatory compliance requirements. Buyers prioritize density-to-stiffness ratios, chemical resistance thresholds, and processing cycle economics when selecting grades.
Product Type:
Cost tiers separate commodity volume resins from engineering grades with specialized additive packages.
- Polypropylene:Linear polymer chains with melt temperatures near 160°C enable thin-wall injection molding for automotive interior panels. Appliance manufacturers in China's Yangtze River Delta cluster specify glass-filled grades for washing machine tubs facing hot water cycling.
- Polyethylene:Split between high-density rigidity and linear low-density flexibility, this resin dominates flexible packaging films where metallocene-catalyzed copolymers command premium pricing. German beverage bottlers specify HDPE for dairy containers requiring cold-chain durability.
- Polystyrene:Amorphous structure delivers optical clarity for disposable cutlery and CD jewel cases, though brittleness limits structural applications.
- Polyvinyl Chloride:Chlorinated backbone provides inherent flame retardancy for wire insulation and medical tubing, with plasticizer selection determining flexibility grades.
Volume sits with Polyethylene; growth tilts toward Polypropylene.
Application:
End-use performance specifications determine whether buyers source commodity grades or invest in custom compounding.
- Automotive Components:Metal-to-plastic substitution programs specify glass-reinforced polyamides for under-hood applications facing 150°C continuous operation. BMW and Tesla procurement teams qualify suppliers on warpage control metrics for electric vehicle battery module housings.
- Packaging:Barrier-layer coextrusion demands precise melt flow index matching across polyethylene and polypropylene grades. Nestlé and Unilever sustainability mandates are accelerating mono-material designs that simplify mechanical recycling streams.
- Consumer Goods:Appliance housings balance aesthetic surface finish with impact resistance for drop-testing protocols.
- Electronics:Halogen-free flame retardant formulations serve laptop and smartphone chassis requiring UL-94 V-0 ratings.
Volume concentrates in Packaging; Automotive Components are expanding most quickly.
End User:
Regulatory intensity varies sharply across sectors, with medical and aerospace imposing qualification timelines that commodity suppliers cannot meet.
- Healthcare:US FDA and China NMPA biocompatibility testing protocols extend resin qualification to 24 months for implantable devices. Becton Dickinson and Fresenius specify medical-grade polycarbonates for dialysis equipment facing repeated sterilization cycles.
- Construction:PVC pipe and siding applications prioritize weathering resistance over precision tolerances, with volume flowing through distributor channels.
- Aerospace:FAA flame-smoke-toxicity certifications restrict thermoplastics to interior non-structural components where weight reduction justifies premium pricing.
- Household:Commodity polypropylene serves storage containers and furniture where cost minimization dominates specification.
Volume sits with Construction; growth tilts toward Healthcare.
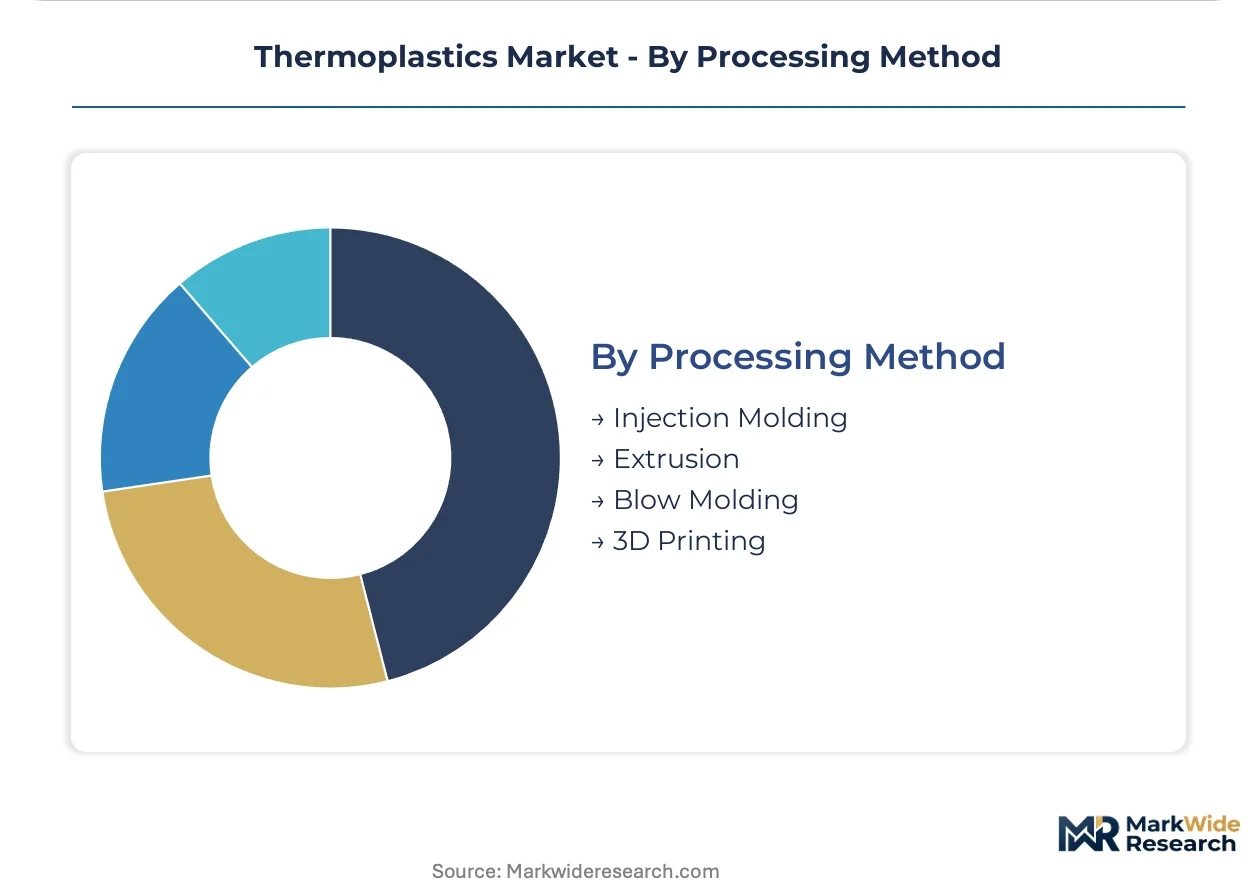
Processing Method:
Capital equipment requirements and cycle economics separate high-volume conversion from specialized additive manufacturing.
- Injection Molding:Multi-cavity tooling and real-time cavity pressure monitoring enable automotive suppliers to hold ±0.05mm tolerances on powertrain components. Engel and KraussMaffei machine deployments concentrate in Germany's automotive supplier corridor.
- 3D Printing:Laser-sintered polyamide powders produce aerospace brackets and dental implants with topology-optimized geometries impossible through subtractive machining. Stratasys and EOS system sales are climbing fastest in medical device prototyping.
- Extrusion:Continuous profile production serves pipe, sheet, and film applications where throughput economics favor dedicated lines.
- Blow Molding:Stretch-blow and extrusion-blow variants produce hollow containers for beverage and industrial chemical packaging.
Volume concentrates in Injection Molding; 3D Printing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta petrochemical corridor concentrates the densest compounding capacity, while automotive OEM procurement teams in Germany and the United States qualify suppliers on warpage control metrics for electrification modules.
China
Automotive lightweighting programs and appliance manufacturing pull polypropylene demand through the Yangtze River Delta cluster. SAMR enforces GB standards for food-contact plastics that extend import qualification timelines. Ningbo and Shanghai host integrated compounding facilities serving BYD and Haier molding operations.
Germany
BMW and Volkswagen procurement specifications drive glass-reinforced polyamide adoption for under-hood electrification components. ECHA REACH Annex XVII restrictions on halogenated flame retardants force reformulation toward phosphorus-nitrogen systems. The automotive supplier corridor between Stuttgart and Munich concentrates injection molding capacity for precision powertrain housings.
United States
Tesla and Ford battery module programs qualify polycarbonate grades for thermal management housings facing 150°C continuous operation. EPA Clean Air Act provisions govern volatile organic compound emissions from extrusion and blow molding facilities. The Midwest manufacturing belt spanning Michigan and Ohio anchors Tier-two molder procurement of direct polymer supply agreements.
Japan
Automotive and electronics OEMs specify chemically recyclable thermoplastics under METI Green Innovation Fund directives. PMDA and JIS standards restrict biocompatibility pathways for implantable device resins. The Nagoya-Toyota industrial corridor concentrates reactive compounding capacity for hybrid vehicle powertrain components.
India
Smartphone and appliance molding demand accelerates under the PLI scheme for electronics manufacturing. BIS certification requirements extend resin qualification periods for food-contact and medical applications. The Gujarat petrochemical complex near Vadodara hosts polyethylene and polypropylene production serving domestic packaging converters.
Thermoplastics Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated petrochemical producers add compounding lines to capture downstream margin. The vendor base separates into three tiers: multinational resin producers with captive feedstock, regional compounders serving automotive qualification programs, and specialized distributors managing spot resin trading. Strategic archetypes include backward-integrated petrochemical giants, automotive-focused engineering-grade specialists, and distributor intermediaries under pressure from direct procurement. M&A activity concentrates in European flame-retardant compounders facing REACH compliance deadlines, while strategic partnerships link resin producers with 3D printing filament manufacturers.
Within the integrated petrochemical tier, BASF SE and SABIC exemplify backward-integrated structures that control naphtha-to-polymer value chains. Covestro AG occupies a position among optical-grade polycarbonate specialists serving precision electronics and medical device segments. These three entities represent distinct competitive vectors: Verbund production systems, feedstock-anchored commodity scale, and regional production flexibility for high-specification grades.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| Celanese Corporation |
| DuPont de Nemours, Inc. |
| LyondellBasell Industries NV |
| Covestro AG |
| Arkema Group |
| Asahi Kasei Corporation |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII chemical safety mandates gate qualified supply and premium-tier pricing access, forcing compounders to absorb reformulation costs for halogen-free flame retardant systems while OEM procurement teams qualify suppliers on compliance tier rather than commodity spot price alone.
Pricing Analysis
Volume concentrates in commodity polyethylene and polypropylene grades where naphtha feedstock volatility compresses margin predictability, while engineering-grade polyamides and optical polycarbonates sustain premium pricing through REACH compliance certification and automotive qualification timelines. Price differentiation hinges on UL-94 V-0 flame retardant rating and ISO 10993 biocompatibility tier for medical applications. Cost compression in commodity resins is intensifying because China's petrochemical capacity expansion floods spot markets. Appliance manufacturers in the Yangtze River Delta cluster exhibit highest price sensitivity; implantable device OEMs facing 24-month FDA qualification cycles show least.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns that position compounders within 500 kilometers of major automotive and appliance molding clusters. Feedstock supply draws from Saudi Arabia, South Korea, and the United States for naphtha and propylene monomer. Single-source vulnerability concentrates in metallocene catalyst systems for premium polyethylene copolymers. Distribution runs through direct polymer procurement agreements that displace distributor intermediaries in high-volume automotive programs exceeding 5,000 metric tons annual offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser-sintered polyamide powders for 3D-printed aerospace brackets and dental implants are displacing subtractive machining, compressing development cycles and redirecting R&D budgets toward topology-optimized geometries impossible through conventional injection molding.
For Market Incumbents: Anchor backward integration into naphtha cracking and metallocene catalyst production to defend margin stability against feedstock volatility. Compounders must secure REACH-compliant halogen-free flame retardant formulation capacity ahead of downstream appliance manufacturer qualification deadlines. BASF SE's Verbund production system exemplifies captive feedstock control that sustains pricing power in engineering-grade polyamides. For New Entrants and Emerging Players: Mid-volume healthcare device manufacturers facing 18-24 month China NMPA biocompatibility timelines represent an underserved buyer archetype hungry for qualified medical-grade polycarbonate supply with sterilization cycle documentation. India's PLI scheme for electronics manufacturing draws compounding investments to serve smartphone and appliance molding demand with localized technical service. Partner with 3D printing filament distributors to bypass capital-intensive twin-screw extrusion scale-up. For Investors and Strategic Acquirers: European compounders acquiring phosphorus-nitrogen intumescent flame retardant specialists ahead of REACH Annex XVII enforcement deadlines is the leading indicator that regulatory compliance capabilities will command acquisition premiums. Long-term viability centers on chemically recyclable thermoplastics with depolymerization pathways under Japan's METI Green Innovation Fund directives. Target European flame-retardant compounders facing reformulation mandates. Watch for direct polymer procurement agreements displacing distributor channels in German and US Midwest automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | BASF SE's Verbund system captures margin through captive propylene supply for polyamide production. |
| REACH-Compliant Flame Retardant Reformulation | European appliance manufacturers qualify phosphorus-nitrogen systems ahead of Annex XVII deadlines. |
| 3D Printing Filament Partnership | Stratasys and EOS system sales climb fastest in medical device prototyping applications. |
| Chemically Recyclable Polymer R&D | Japan's METI Green Innovation Fund redirects budgets toward closed-loop depolymerization pathways. |
| Direct Polymer Procurement Agreements | Tier-two molders in Germany and Michigan bypass compounder channels for polypropylene bumper supply. |
Methodological Framework
Trade databases, SEC 10-K filings, and ECHA REACH registration dossiers formed the secondary backbone, cross-referenced with primary interviews involving plant managers at integrated petrochemical facilities, procurement leads at Tier 1 automotive suppliers, distribution channel partners managing spot resin trading, and technical R&D directors overseeing reactive compounding operations. Bottom-up resin demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Bottom-up volume estimates derived from injection molding machine deployment data, automotive platform content-per-vehicle specifications, and packaging film extrusion line capacity announcements, while top-down approaches anchored in petrochemical feedstock consumption trends and customs import-export flows. Segmentation dimensions spanned resin chemistry grade tier, end-use industry application, processing method technology, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections incorporating automotive lightweighting penetration rates and medical device sterilization cycle requirements.
Revisions become necessary when crude oil price volatility exceeds historical bands, REACH enforcement timelines accelerate, or China's petrochemical capacity expansion disrupts regional supply-demand balances. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Bio-Based Polypropylene Market