
 Polyurethane (PU) Microspheres Market | 2026-2036
Polyurethane (PU) Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane (PU) Microspheres Market Analytics
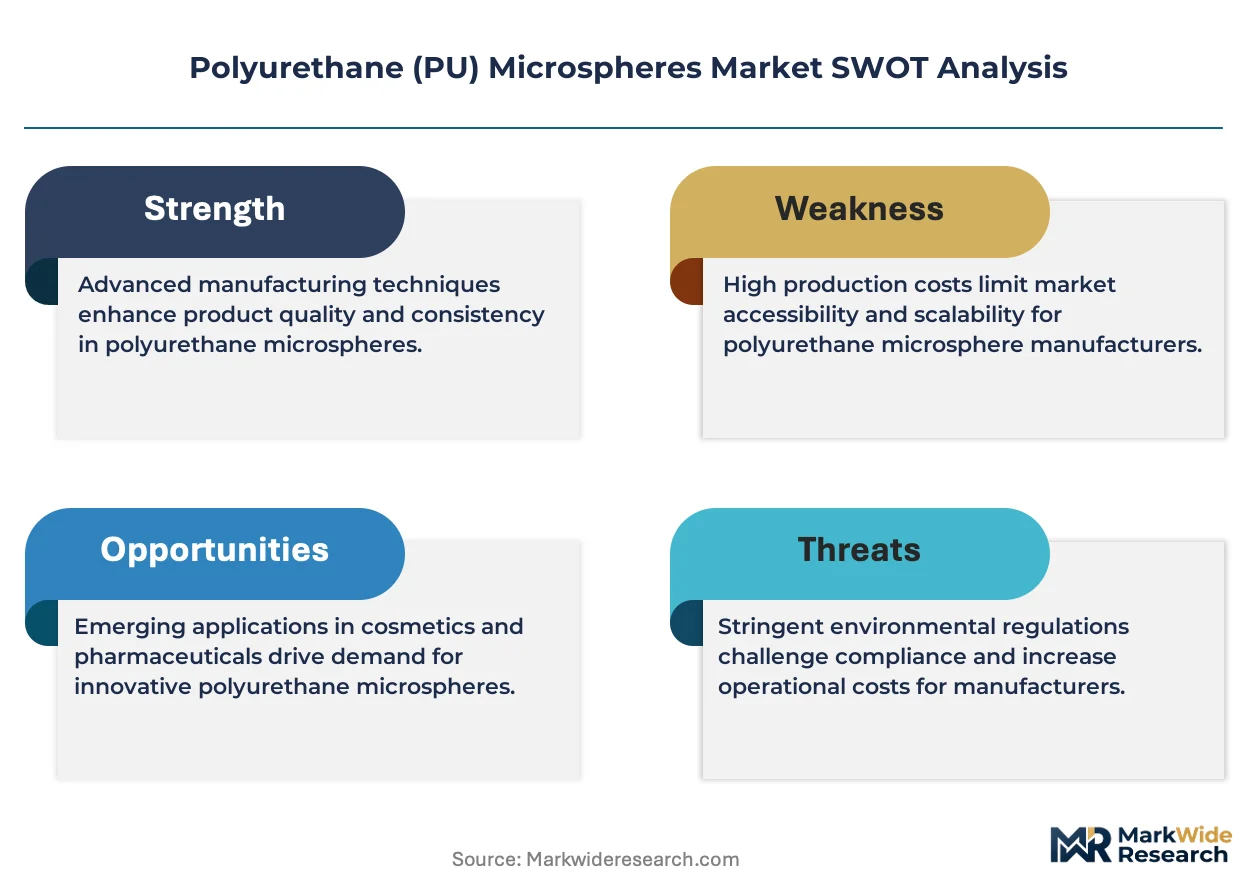
Buyer concentration among automotive OEMs is recalibrating procurement volumes for PU microspheres across tier-1 coating suppliers. Covestro AG leverages its backward integration into isocyanate precursors to secure feedstock cost advantages. Kolon Industries Inc anchors its position through specialized solid microsphere production for Asian electronics coating houses. Sanyo Chemical Industries Ltd differentiates via aqueous dispersion technologies that reduce solvent handling costs for Japanese applicators.
Polyurethane microspheres are spherical particles synthesized from polyol-isocyanate reactions, typically ranging from one to one hundred micrometers in diameter, engineered for controlled density, elasticity, and surface functionality in industrial formulations. These particles serve primarily as rheology modifiers, matting agents, and mechanical property enhancers in coating and adhesive systems where uniform particle distribution determines finish quality. Solid microspheres command the largest volume share across coating applications due to their established supply chains and predictable performance in high-solids formulations. Hollow microspheres represent the fastest-expanding category, driven by lightweighting imperatives in aerospace primers and automotive seam sealers where density reduction translates directly to fuel efficiency gains. Uncoated variants retain margin pools in commodity adhesive markets, while coated microspheres capture premium positioning in pharmaceutical controlled-release and cosmetic texture-engineering segments.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne coating systems, redirecting formulation investment toward water-dispersible PU microsphere platforms. REACH registration requirements and the EU Green Deal's chemical sustainability benchmarks impose substance transparency obligations that favor suppliers with documented lifecycle data. FDA oversight of pharmaceutical-grade microspheres for oral dosage forms adds a compliance layer that limits market access to validated manufacturers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these intersect with surface-modification chemistries used in next-generation microsphere coatings.
Market Dynamics
Automotive OEM procurement consolidation is compressing supplier margins while simultaneously demanding higher performance specifications for lightweight underbody coatings, forcing coating formulators to renegotiate long-term PU microsphere supply agreements.
Growth Catalysts
- REACH substance transparency mandates:ECHA registration requirements under the EU Green Deal favor suppliers with documented lifecycle data, redirecting procurement toward validated European compounders.
- Hollow microsphere lightweighting technology:Aerospace primer and automotive sealer applications adopt density-reducing particles to meet fuel efficiency targets, expanding addressable coating volumes.
- Rhine-Ruhr industrial clustering:German automotive paint shops and adhesive compounders concentrate demand along this corridor, creating localized procurement efficiencies and technical service proximity.
Market Restraints
- Isocyanate feedstock volatility:Polyol-isocyanate precursor costs fluctuate with petrochemical pricing, squeezing margin pools for non-integrated formulators lacking backward integration into raw materials.
- Asian electronics coating concentration:Solid microsphere supply chains anchor heavily in Korean and Japanese electronics coating houses, creating geographic dependency risk for European and North American buyers.
- Aqueous dispersion technical ceiling:Water-dispersible PU microsphere platforms face performance gaps in high-solids industrial coatings where solvent-borne systems still dominate durability benchmarks.
Strategic Opportunities
- Indian pharmaceutical controlled-release expansion:CDSCO oversight of oral dosage form microspheres remains underpenetrated by validated Western suppliers, creating first-mover positioning for compliant entrants.
- Per- and polyfluoroalkyl substance restriction tailwinds:Evolving EPA and ECHA constraints on PFAS surface modifications open substitution demand for next-generation microsphere coating chemistries.
- Cosmetic texture-engineering channel innovation:Direct-to-formulator digital platforms bypass traditional distributor markups for coated microsphere sales into premium skincare and color cosmetic houses.
Industry Challenges
- Pharmaceutical-grade FDA validation timelines:Oral dosage form microsphere certification requires multi-year stability studies and manufacturing site inspections, delaying revenue recognition for new entrants.
- Coating-applicator technical skill gaps:Water-dispersible platform adoption demands retraining of shop-floor technicians accustomed to solvent-borne handling protocols, slowing formulation conversion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane (PU) Microspheres Market |
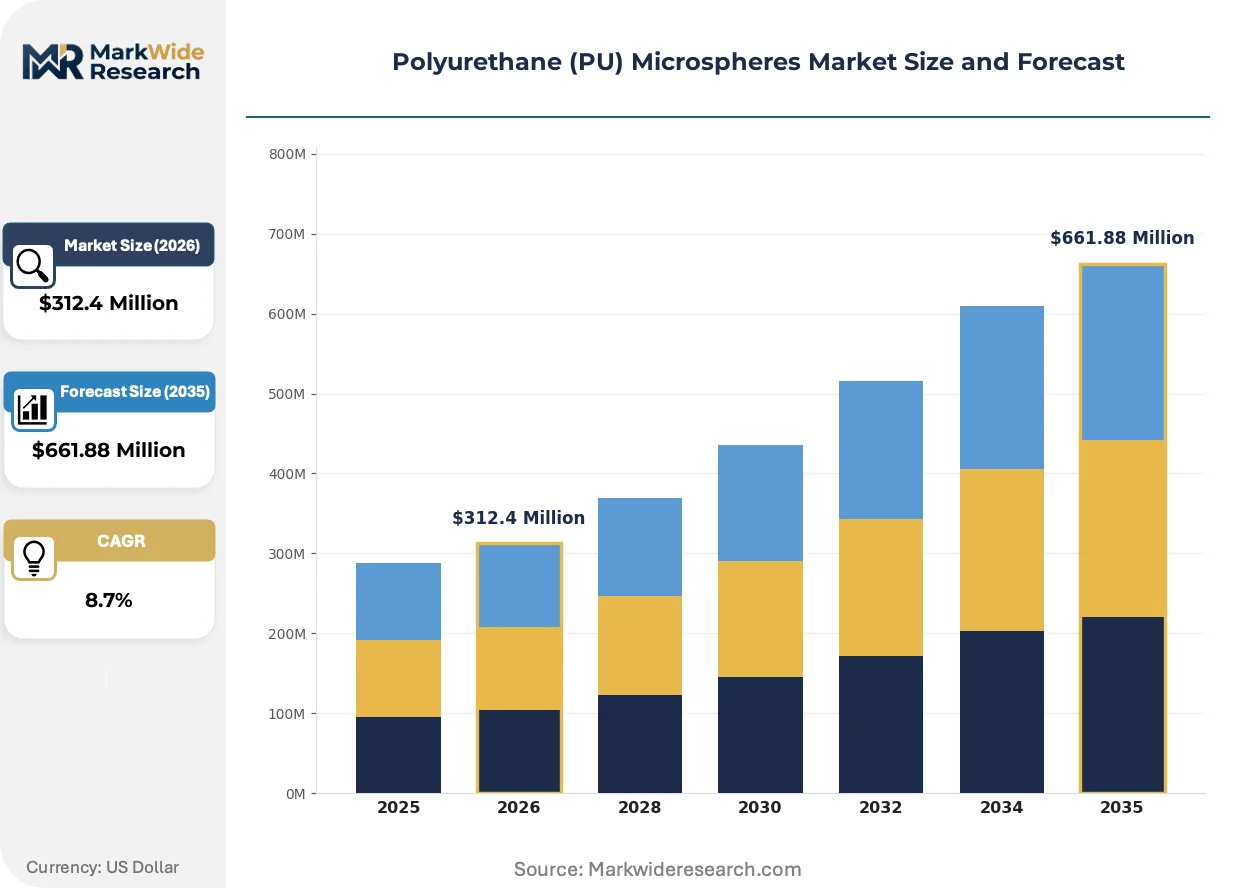
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Microspheres, Uncoated Microspheres, Hollow Microspheres, Solid Microspheres Application: Coatings, Adhesives, Cosmetics, Pharmaceuticals End User: Aerospace, Automotive, Healthcare, Consumer Goods Packaging Type: Bags, Drums, Boxes, Bulk Containers |
| Companies Covered | Microchem, Covestro AG, Chase Corp, Sanyo Chemical Industries Ltd, Kolon Industries Inc, Heyo Enterprises Co Ltd, Supercolori SpA, Bayer MaterialScience LLC, EPRUI Biotech Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane (PU) Microspheres Market Evolving Landscape
Formulation chemistry and procurement architecture are simultaneously evolving, with regulatory pressure and end-use performance demands intersecting to reshape how PU microspheres are specified, supplied, and applied across industrial coating systems.
Aqueous dispersion technology is consolidating its position in automotive and industrial coating formulations. Japanese applicators lead adoption of water-dispersible PU microsphere platforms to reduce solvent handling infrastructure costs. This consolidation is compressing demand for conventional solvent-borne matting agents and forcing incumbent suppliers to reconfigure manufacturing assets toward water-compatible chemistries.
EPA National Emission Standards for Hazardous Air Pollutants are tightening permissible VOC thresholds for coating systems. Industrial finishers face capital expenditure requirements for emission control equipment or formulation reformulation toward compliant platforms. Automotive OEM paint shops in Michigan and Ohio are accelerating water-dispersible procurement to preempt enforcement actions and avoid production line shutdowns.
Buyer concentration among tier-1 coating suppliers is compressing negotiation cycles and demanding outcome-based performance guarantees. Automotive OEMs now specify PU microsphere inclusion rates and finish quality metrics rather than purchasing raw materials directly. This specification-driven procurement is most visible in Germany, where Volkswagen and BMW consolidate coating supply agreements with single-source formulators who assume microsphere procurement risk.
Polyurethane (PU) Microspheres Market Segmentation
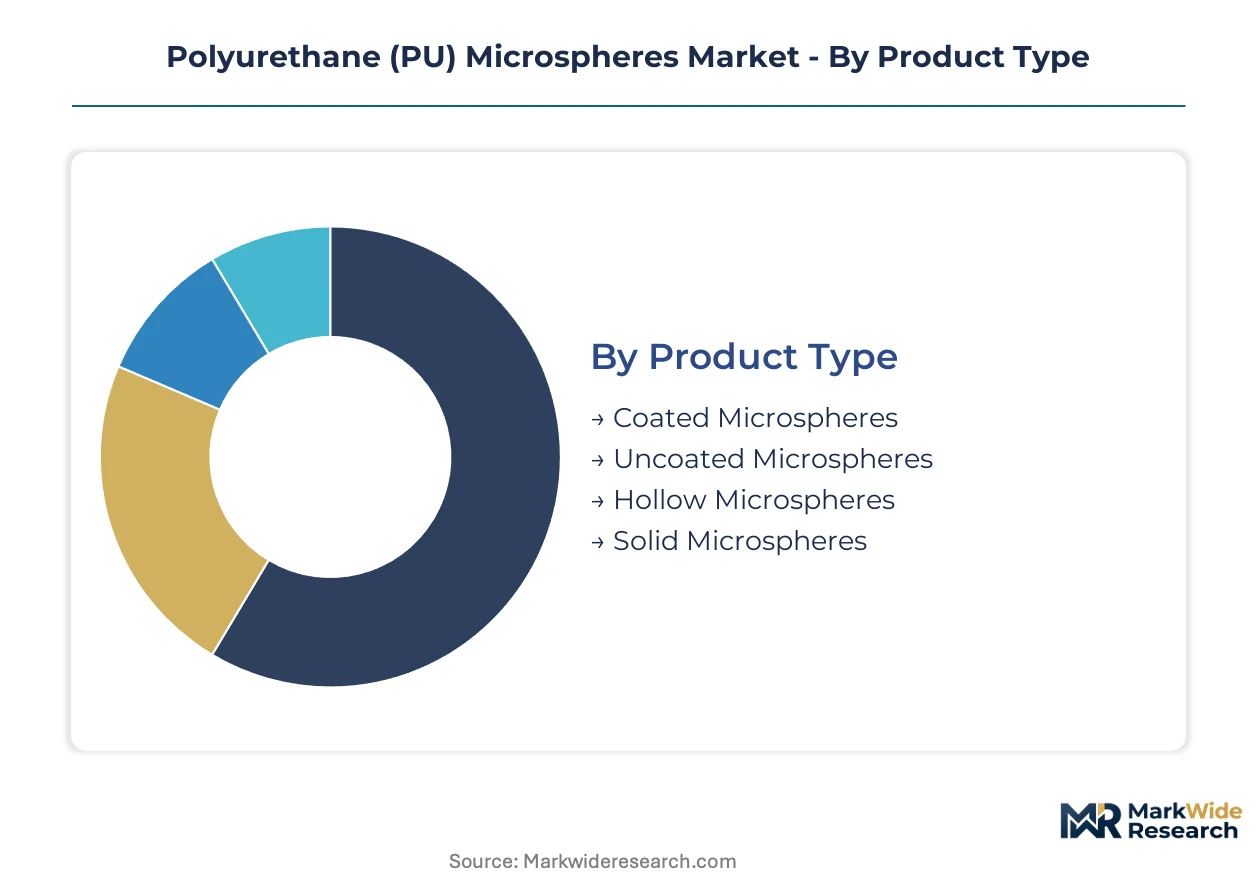
Segmentation in PU microspheres reveals how regulatory certification burdens concentrate profitability in specific tiers. Pharmaceutical and aerospace end-uses demand validated manufacturing documentation that commodity coating segments rarely require.
Product Type:
Solid microspheres carry minimal certification overhead for industrial coatings, while hollow variants face aerospace material qualification protocols and coated grades trigger pharmaceutical FDA validation timelines.
- Solid Microspheres:Dense polyol-isocyanate reaction products with uniform particle distribution serve established automotive underbody coating formulations. Procurement concentrates among German automotive paint shops along the Rhine-Ruhr corridor where REACH substance transparency mandates favor documented European supply chains.
- Hollow Microspheres:Gas-filled shells engineered for density reduction below 0.5 g/cm³ enable lightweight aerospace primers and automotive seam sealers. Boeing and Airbus primer specifications in Washington State and Toulouse drive qualification demand, though isocyanate feedstock volatility squeezes non-integrated suppliers.
- Coated Microspheres:Surface-functionalized particles for controlled-release pharmaceutical oral dosage forms require FDA stability studies and manufacturing site inspections.
- Uncoated Microspheres:Base particles retain margin pools in commodity adhesive markets with minimal regulatory documentation requirements.
Leading the category by volume: Solid Microspheres. Growing fastest: Hollow Microspheres.
Application:
Cost tier stratification separates capital-intensive pharmaceutical validation from commodity coating procurement with minimal technical service overhead.
- Coatings:Automotive OEM specification-driven procurement demands outcome-based performance guarantees for finish quality metrics. Michigan and Ohio paint shops accelerate water-dispersible platform adoption to preempt EPA National Emission Standards enforcement actions.
- Pharmaceuticals:Oral dosage form microspheres for controlled-release APIs require multi-year stability studies under FDA oversight, limiting market access to validated manufacturers with documented lifecycle data.
- Adhesives:Industrial bonding applications in construction and electronics assembly utilize commodity-grade microspheres with standard technical data sheets.
- Cosmetics:Premium skincare and color cosmetic texture-engineering segments command coated microsphere positioning through direct-to-formulator digital platforms.
Highest margin concentration: Pharmaceuticals. Steepest volume expansion: Coatings.
End User:
Customer type determines technical service intensity, with aerospace and healthcare demanding embedded formulation support that automotive procurement increasingly rejects.
- Automotive:OEM procurement consolidation compresses supplier margins while demanding lightweight underbody coating specifications. Volkswagen and BMW single-source formulator agreements in Germany shift microsphere procurement risk to tier-1 coating suppliers.
- Healthcare:Pharmaceutical-grade microsphere consumption for controlled-release dosage forms concentrates among validated Western suppliers facing CDSCO oversight expansion in India.
- Aerospace:Boeing and Airbus primer specifications drive hollow microsphere qualification with density reduction targets tied to fuel efficiency mandates.
- Consumer Goods:Cosmetic and personal care applications utilize coated microspheres for texture engineering with shorter formulation development cycles.
Dominant procurement volume: Automotive. Most rapid qualification expansion: Healthcare.
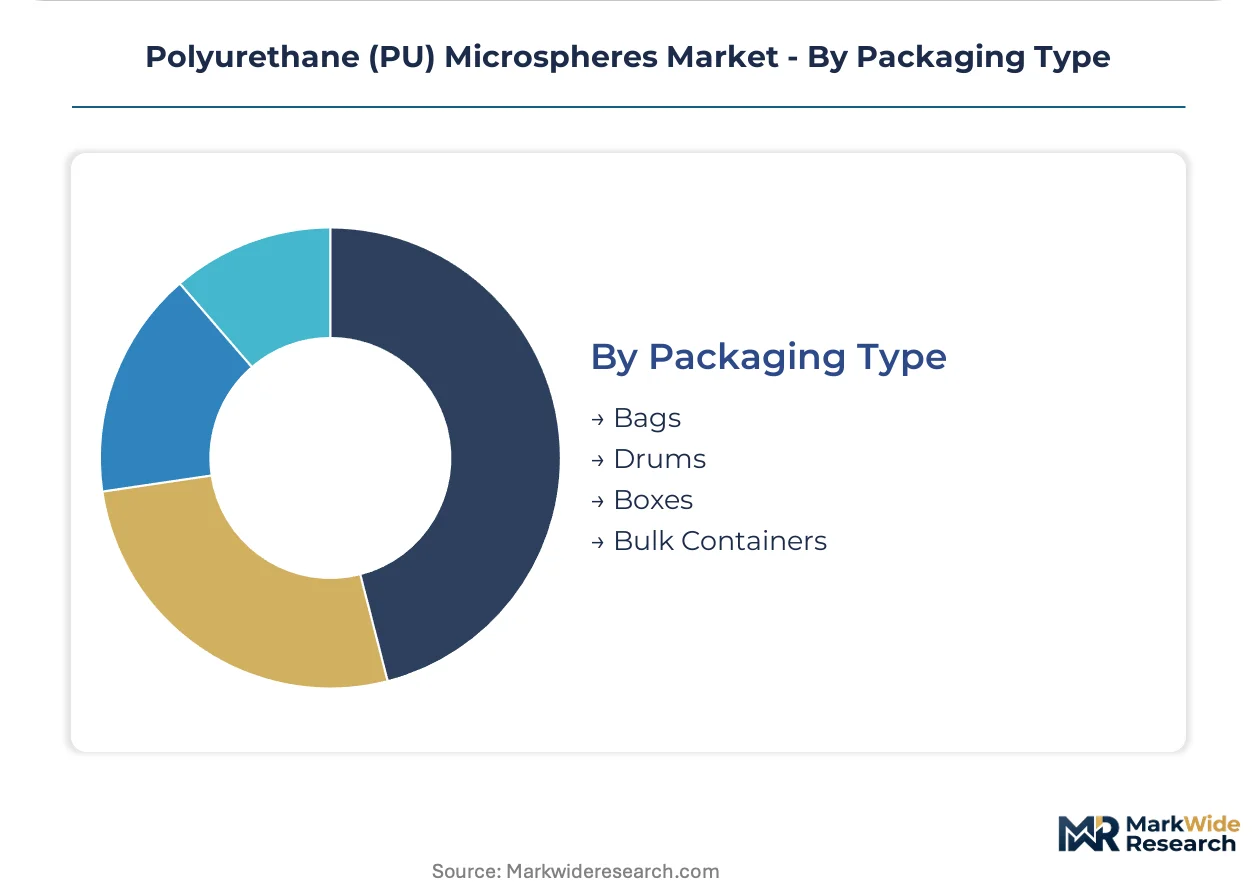
Packaging Type:
Supply chain configuration directly shapes packaging selection, with bulk logistics favoring integrated compounders and specialized grades requiring protective smaller-unit distribution.
- Bulk Containers:Tanker and tote configurations serve high-volume automotive coating formulators with dedicated supply agreements and just-in-time delivery contracts.
- Drums:Standard 200-liter steel and plastic drums dominate mid-volume coating and adhesive procurement through established chemical distributor networks.
- Bags:Multi-layer moisture-barrier packaging protects pharmaceutical-grade and cosmetic microspheres from humidity degradation during extended storage.
- Boxes:Corrugated fiberboard with desiccant inserts supports laboratory-scale sampling and specialty electronics coating house procurement.
Primary volume handler: Bulk Containers. Fastest packaging innovation: Bags with active moisture control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in Germany's Rhine-Ruhr corridor, where Volkswagen and BMW consolidate coating supply agreements. Japanese electronics coating houses anchor solid microsphere demand across East Asia. EPA enforcement in Michigan and Ohio accelerates water-dispersible platform adoption.
United States
Automotive paint shops in Michigan and Ohio accelerate water-dispersible PU microsphere procurement to preempt EPA National Emission Standards enforcement. The EPA constrains solvent-borne coating systems under hazardous air pollutant regulations. Detroit-area OEM facilities cluster procurement volumes with tier-1 formulators who assume supply risk.
Germany
REACH substance transparency mandates redirect procurement toward validated European compounders with documented lifecycle data. ECHA registration requirements under the EU Green Deal impose chemical sustainability benchmarks. Automotive paint shops and adhesive compounders concentrate along the Rhine-Ruhr industrial corridor, creating localized technical service proximity.
Japan
Electronics coating houses drive solid microsphere consumption for Asian semiconductor and display manufacturing. METI industrial standards shape formulation chemistry investments. Osaka and Nagoya-based applicators lead adoption of aqueous dispersion platforms to reduce solvent handling infrastructure costs.
India
Pharmaceutical controlled-release expansion creates first-mover positioning for validated Western suppliers. CDSCO oversight of oral dosage form microspheres remains underpenetrated, extending validation timelines for new entrants. Maharashtra and Gujarat-based API manufacturers cluster demand for compliant microsphere supply.
South Korea
Electronics coating concentration anchors solid microsphere supply chains for display and semiconductor applications. MFDS pharmaceutical regulations intersect with cosmetic texture-engineering demand for coated variants. Seoul and Gyeonggi Province house specialized production facilities serving regional electronics houses.
Polyurethane (PU) Microspheres Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade validation and specialty coating segments. The supplier base stratifies across integrated petrochemical conglomerates, specialized microsphere fabricators, and regional compounders serving niche end-uses. Three archetypes dominate: backward-integrated precursors specialists, aqueous dispersion technology leaders, and solid microsphere volume producers. Competitive moves concentrate on capacity reconfiguration toward water-compatible chemistries and geographic expansion into underpenetrated pharmaceutical regulatory jurisdictions.
Among European-based integrated producers, Covestro AG exemplifies the backward-integrated archetype through captive isocyanate precursor supply. Kolon Industries Inc and Sanyo Chemical Industries Ltd represent Asian specialists occupying distinct technology positions—solid microsphere production and aqueous dispersion platforms respectively. These three anchors illustrate how supplier differentiation maps to end-use performance requirements and regional regulatory compliance burdens.
| Leading Market Players |
|---|
| Microchem |
| Covestro AG |
| Chase Corp |
| Sanyo Chemical Industries Ltd |
| Kolon Industries Inc |
| Heyo Enterprises Co Ltd |
| Supercolori SpA |
| Bayer MaterialScience LLC |
| EPRUI Biotech Co Ltd |
| Others |
Value Network & Pricing Analysis
EU Green Deal chemical sustainability benchmarks gate qualified supply access and premium-tier pricing for polyurethane microsphere producers, forcing non-compliant compounders into commodity margin pools while validated European suppliers capture pharmaceutical-grade premiums. REACH substance transparency mandates impose documentation costs that stratify the supplier base, with ECHA-registered producers commanding pricing power in automotive coating procurement.
Pricing Analysis
Volume concentrates in solid microsphere commodity tiers while margin pools accrue to hollow and coated pharmaceutical grades. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated oral dosage form microspheres from REACH-compliant automotive grades and uncoated adhesive commodity variants. Pricing pressure stems from automotive OEM procurement consolidation demanding outcome-based performance guarantees. Tier-1 coating suppliers exhibit highest price sensitivity due to single-source formulator agreements, while pharmaceutical houses accept premium positioning for validated manufacturing documentation.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade microspheres require temperature-controlled returns handling and stability-monitoring refurbishment protocols that add cost layers absent from industrial coating supply chains. Geographic concentration centers on Germany, Japan, and South Korea, with Rhine-Ruhr automotive paint shops, Osaka electronics coating houses, and Seoul display manufacturers anchoring regional demand clusters. Isocyanate precursor supply draws from petrochemical feedstocks subject to commodity price volatility. Single-source vulnerability runs through Asian electronics coating concentration for solid microsphere supply. Distribution runs through bulk tanker configurations for high-volume automotive formulators and specialized multi-layer barrier bags for pharmaceutical-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA validation timelines for pharmaceutical-grade microspheres create a multi-year barrier-to-entry moat protecting incumbent positioning against commodity entrants.
For Market Incumbents: Deploy backward integration into isocyanate precursors to defend margin pools against petrochemical feedstock volatility squeezing non-integrated formulators. Capture channel control through direct-to-formulator digital platforms bypassing distributor markups in cosmetic texture-engineering segments. Capacity addition in aqueous dispersion technologies preempts EPA enforcement acceleration in Michigan and Ohio automotive paint shops. For New Entrants and Emerging Players: CDSCO-registered pharmaceutical compounders in Maharashtra and Gujarat represent the most penetrable white-space target, as Western validated suppliers remain underpenetrated in Indian oral dosage form microspheres. Cosmetic direct-to-formulator digital platforms offer a go-to-market angle with shorter qualification cycles than pharmaceutical validation timelines. Target aqueous dispersion technology licensing to Japanese electronics coating houses seeking solvent handling cost reduction. For Investors and Strategic Acquirers: Hollow microsphere aerospace qualification announcements from Boeing or Airbus primer specifications are the leading indicator that density-reduction technology is crossing from development to revenue recognition. Long-term viability favors backward-integrated producers with captive isocyanate supply and documented lifecycle data for REACH compliance. Acquisition target archetype: aqueous dispersion technology leaders with established Japanese electronics coating relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Precursors | Covestro AG leverages captive feedstock supply to secure cost advantages against volatile petrochemical pricing. |
| Aqueous Dispersion Platform Expansion | Sanyo Chemical Industries Ltd reduces solvent handling infrastructure costs for Osaka-based automotive applicators. |
| Pharmaceutical-Grade FDA Validation Investment | Multi-year stability studies and manufacturing site inspections limit market access to documented Western suppliers. |
| Direct-to-Formulator Digital Channel Launch | Coated microsphere sales bypass traditional distributor markups in premium skincare and color cosmetic houses. |
| Long-Term Supply Agreement with Automotive OEM | Volkswagen and BMW single-source formulator agreements in Germany shift procurement risk to tier-1 coating suppliers. |
Research Methodology
Independent corroboration across plant managers at polyurethane microsphere production facilities, procurement leads at German automotive OEMs, distribution channel partners in Asian electronics coating supply chains, and technical R&D directors at coating formulators underwrites the qualitative findings. Secondary validation draws from ECHA registration databases, EPA National Emission Standards enforcement records, FDA pharmaceutical master file submissions, and customs trade data for isocyanate precursor flows. Bottom-up segment sizing triangulates against top-down market reconstruction across product type, application, and end-user dimensions.
Comparable-period anchoring to historical automotive coating procurement cycles and pharmaceutical validation timeline benchmarks structures the forecast window. The analytical framework models solid, hollow, coated, and uncoated product tiers against coatings, pharmaceuticals, adhesives, and cosmetics applications through the projection horizon. CAGRs derive from segment-level volume trajectories weighted by automotive lightweighting imperatives, aerospace fuel efficiency mandates, and pharmaceutical controlled-release expansion. Forecast inputs incorporate REACH substance transparency compliance rates and aqueous dispersion technology adoption curves.
Caveats apply where EPA enforcement acceleration, isocyanate feedstock price spikes, or PFAS restriction expansion could materially shift the outlook. Forecasts reflect assumptions about automotive OEM procurement consolidation continuity and pharmaceutical validation timeline stability. Practitioners should monitor CDSCO regulatory expansion announcements and Boeing-Airbus hollow microsphere qualification decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Polylysine Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Polyphenylene Oxide (PPO) Market
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Bio-Based Epoxy Resin Market