
 Global Blow Molding Resins Market | 2026-2036
Global Blow Molding Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blow Molding Resins Market Analysis
Competitive Landscape
The capital-intensity gap between integrated petrochemical majors and standalone resin distributors is collapsing as feedstock volatility compresses trading margins. LyondellBasell Industries N.V. leverages its Houston-based polypropylene technology center to sustain proprietary catalyst advantages in high-clarity grades. Exxon Mobil Corporation anchors its position through backward integration into Gulf Coast ethane crackers, while Braskem S.A. differentiates via bio-based polyethylene capacity at its Triunfo complex.
Product Architecture
Blow molding resins comprise thermoplastic polymers formulated for extrusion or injection blow molding processes, with melt flow index and density specifications determining parison stability and wall thickness distribution in hollow article production. Polyethylene dominates volume demand in bottle manufacturing applications where moisture barrier and stress-crack resistance govern material selection, while polypropylene captures expanding share in automotive parts as OEMs pursue weight reduction targets. Medical grade formulations command premium positioning within the grade taxonomy due to USP Class VI validation requirements and extractables testing protocols that constrain supplier qualification.
Regulatory Environment
The EPA oversees resin manufacturing emissions under Clean Air Act Title V permitting, while REACH registration obligations in Europe constrain phthalate plasticizer incorporation in polyvinyl chloride compounds destined for food-contact packaging. FDA food additive regulations and EU Commission Regulation 10/2011 establish migration limits that directly determine formulation viability for converters serving the Food & Beverage Industry. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions that will increasingly mandate recycled content minimums across packaging applications.
Market Dynamics
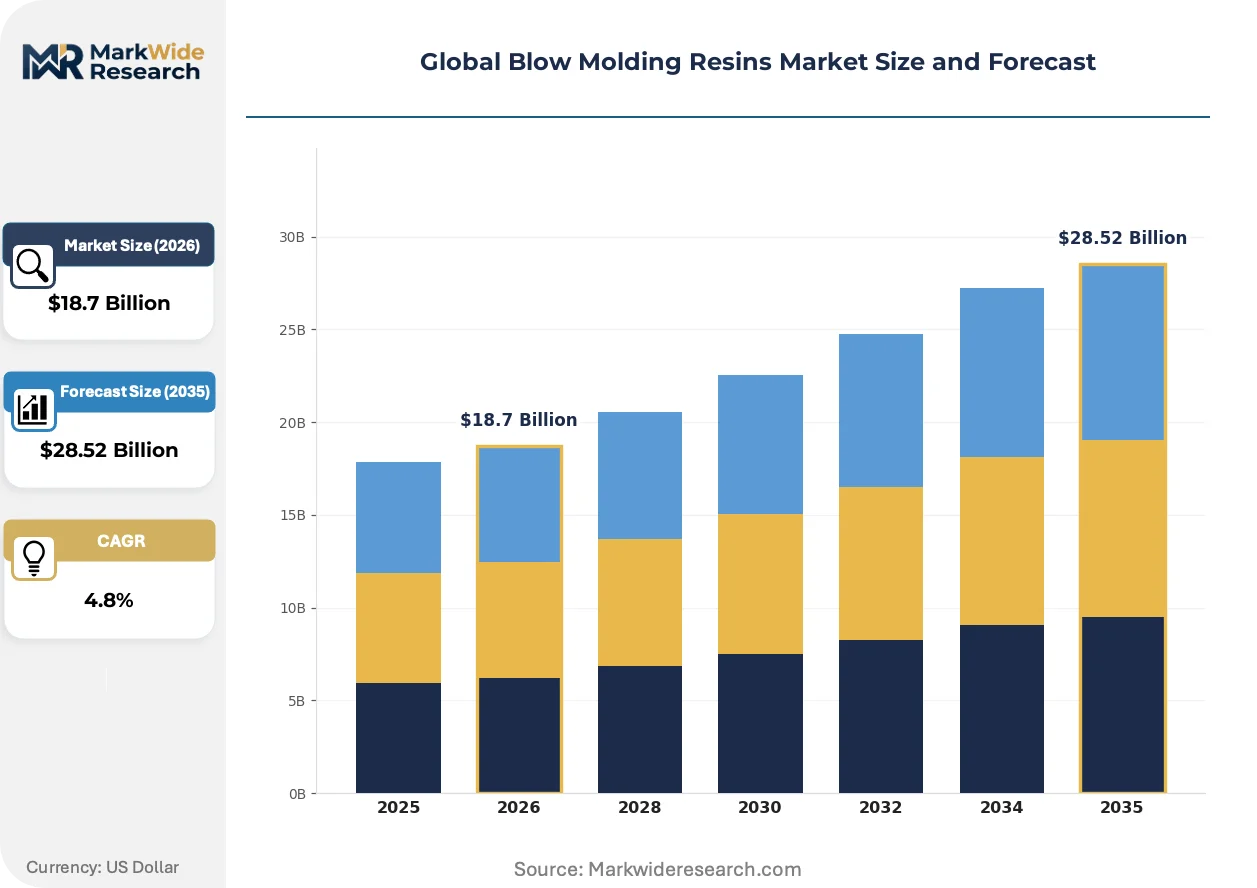
Feedstock volatility is compressing trading margins across the blow molding resins value chain, forcing converters to consolidate procurement positions and locking in long-term offtake agreements with integrated petrochemical producers.
Growth Catalysts
- Asia-Pacific beverage packaging expansion:China's coastal petrochemical clusters are scaling integrated resin-to-bottle operations to serve carbonated soft drink and bottled water demand.
- EU F-Gas Regulation compliance:REACH registration obligations are accelerating material substitution away from phthalate plasticizers in food-contact polyvinyl chloride compounds.
- Automotive lightweighting mandates:OEMs in Germany and Japan are specifying high-flow polypropylene grades for underhood blow-molded reservoirs and ducting systems.
Market Restraints
- Ethane price volatility:Gulf Coast cracker economics swing with natural gas liquid differentials, eroding margin predictability for polyethylene producers.
- Medical grade qualification barriers:USP Class VI validation and extractables testing protocols limit supplier pools for pharmaceutical packaging applications.
- Recycled content contamination risk:FDA and EU Commission Regulation 10/2011 migration limits constrain post-consumer resin incorporation rates in food-contact applications.
Strategic Opportunities
- India packaging underpenetration:FSSAI compliance infrastructure is maturing, enabling multinational converters to establish blow-molded dairy and edible oil container production.
- Extended producer responsibility tailwinds:EU Green Deal mandates and emerging state-level frameworks in California and New York will create mandated demand for certified recycled content resins.
- Bio-based polyethylene scale-up:Braskem's Triunfo complex demonstrates commercial viability, with sugarcane ethanol feedstock offering scope 3 emissions advantages for brand-owner sustainability commitments.
Industry Challenges
- Catalyst technology talent scarcity:High-clarity polypropylene formulation expertise concentrates at legacy technology centers in Houston and Amsterdam, constraining new entrant R&D capabilities.
- Multi-jurisdiction certification timelines:Simultaneous FDA food additive petitions, EU 10/2011 amendments, and China's GB standard compliance extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blow Molding Resins Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Grade: Food Grade, Industrial Grade, Medical Grade, Recycled Grade Application: Bottle Manufacturing, Packaging Solutions, Automotive Parts, Consumer Goods End User: Food & Beverage Industry, Healthcare Sector, Cosmetics, Electronics |
| Companies Covered | The Dow Chemical Company, Formosa Plastics Corporation, LyondellBasell Industries N.V., Borealis AG, Braskem S.A., Exxon Mobil Corporation, Chevron Phillips Chemical Company, INEOS Group AG, Saudi Basic Industries Corporation (SABIC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blow Molding Resins Market Emerging Trajectories
Advanced catalyst systems and mechanical recycling infrastructure are converging to redefine grade specifications and supplier qualification criteria across beverage, automotive, and medical packaging end-uses.
Metallocene polyethylene is displacing conventional Ziegler-Natta grades in premium beverage bottle applications. Brand owners in Germany and Japan specify metallocene resins for enhanced clarity and drop-impact performance. This shift is displacing commodity HDPE from high-margin personal care and premium water segments, compressing margin pools for non-specialized producers.
REACH registration obligations are tightening phthalate restrictions in PVC compounds destined for food-contact packaging. ECHA substance evaluation is driving converters toward citrate and trimellitate plasticizer alternatives. Blow-molded dairy and edible oil containers for European export markets face reformulation deadlines that favor suppliers with pre-validated compliant grade portfolios.
Direct converter-petrochemical producer partnerships are replacing distributor intermediation in volume procurement. Large beverage bottlers in China and Mexico now negotiate resin offtake directly with integrated producers, bypassing traditional trading houses. This disintermediation is most visible in high-volume polyethylene terephthalate preform and bottle operations where supply security outweighs price discovery value.
Global Blow Molding Resins Market Segmentation
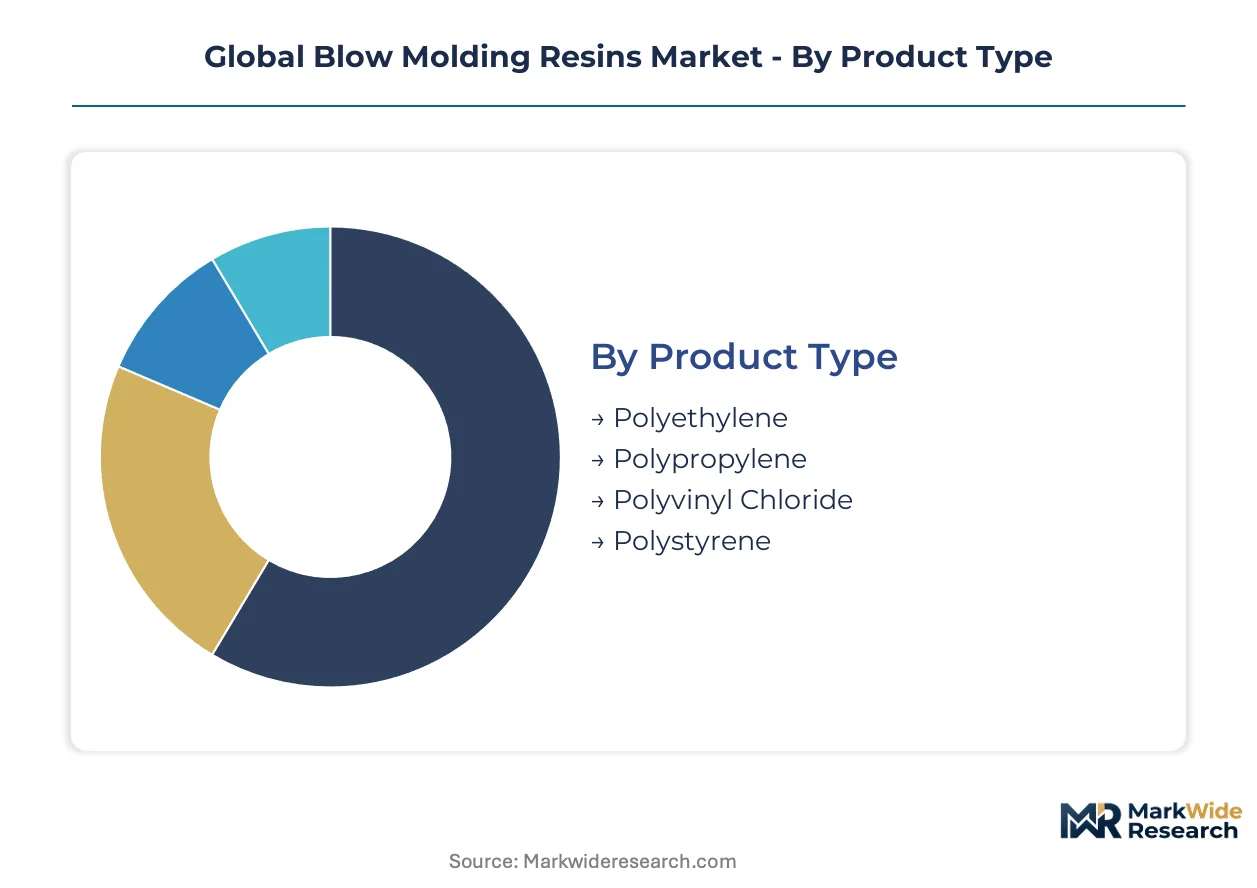
Blow molding resins segment along polymer chemistry, performance certification, and end-use specifications that determine converter procurement criteria. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier qualification requirements.
Product Type:
Polyethylene dominates domestic consumption in China's coastal manufacturing clusters, while polypropylene serves export-oriented automotive supply chains into Germany and Japan.
- Polyethylene:Linear low-density and high-density grades formulated for moisture barrier performance and stress-crack resistance in hollow article production. Demand concentrates in China's integrated resin-to-bottle operations serving carbonated soft drink and bottled water markets, where parison stability requirements favor metallocene catalyst systems.
- Polypropylene:High-flow grades with controlled crystallinity for underhood automotive reservoirs and HVAC ducting systems. OEM specifications in Germany and Japan are accelerating displacement of metal and engineering polymer alternatives, with Braskem's bio-based capacity capturing sustainability-linked procurement mandates.
- Polyvinyl Chloride:Rigid and plasticized compounds for chemical containers and construction profiles, facing REACH-driven reformulation away from phthalate plasticizers in European export applications.
- Polystyrene:Crystal and high-impact grades for consumer goods and display packaging, constrained by recycling infrastructure limitations in multi-layer food-contact applications.
Polyethylene commands the established base. The steepest expansion runs through polypropylene.
Grade:
Cost tier stratification separates commodity industrial grades from premium medical and food-contact certifications that command 40-60% price premiums.
- Food Grade:Compliant with FDA food additive regulations and EU Commission Regulation 10/2011 migration limits for direct food-contact packaging. China's GB standard alignment is accelerating domestic qualification for dairy and edible oil container exports.
- Medical Grade:USP Class VI validated formulations with extractables testing protocols for pharmaceutical packaging and medical device components. Supplier pools remain constrained by 18-24 month qualification timelines and limited compounding capacity.
- Industrial Grade:General-purpose formulations for non-critical applications including chemical containers and automotive non-structural parts, sourced through distributor channels with compressed trading margins.
- Recycled Grade:Post-consumer and post-industrial resins with certified content for extended producer responsibility compliance, facing FDA and EU migration limit constraints that cap incorporation rates in food-contact applications.
Food grade captures volume leadership. Medical grade delivers margin expansion.
Application:
Application mix varies sharply by geography—bottle manufacturing concentrates in Asia-Pacific manufacturing hubs, while automotive parts production anchors European and North American demand.
- Bottle Manufacturing:Carbonated soft drink, bottled water, and personal care containers requiring clarity, drop-impact performance, and barrier properties. China's coastal petrochemical clusters have achieved 80%+ captive integration from resin production through preform molding.
- Packaging Solutions:Industrial containers, drums, and intermediate bulk containers for chemical and agricultural chemical distribution, with multi-trip durability specifications favoring HDPE over alternative polymers.
- Automotive Parts:Underhood reservoirs, ducting, and fuel system components where OEM lightweighting mandates specify high-flow polypropylene grades with heat-aging resistance.
- Consumer Goods:Toys, furniture components, and household articles with lower performance requirements and price-sensitive procurement through distributor channels.
Bottle manufacturing anchors revenue scale. Automotive parts generate the fastest margin expansion.
End User:
Customer type determines specification intensity—food and beverage converters demand batch-level certification, while cosmetics buyers prioritize aesthetic performance over regulatory documentation.
- Food & Beverage Industry:Multinational bottlers in China, Mexico, and India negotiating direct resin offtake agreements with integrated petrochemical producers. FSSAI compliance infrastructure maturation is enabling dairy and edible oil container expansion in India.
- Healthcare Sector:Pharmaceutical packaging and medical device manufacturers requiring USP Class VI validation, extractables testing, and ISO 13485 quality system certification from resin suppliers.
- Cosmetics:Premium personal care and fragrance brands specifying metallocene polyethylene for enhanced clarity and surface aesthetics in European and Japanese markets.
- Electronics:Anti-static and conductive formulations for component packaging and cleanroom applications, with JIS standard compliance required for Japanese electronics supply chains.
Food and beverage commands procurement volume. Healthcare delivers the steepest certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's coastal petrochemical clusters while European converters absorb REACH compliance premiums. Gulf Coast ethane economics swing North American producer margins with natural gas liquid differentials.
China
Integrated resin-to-bottle operations in Zhejiang and Guangdong provinces serve carbonated soft drink demand from Coca-Cola and Pepsi bottling partners. GB standard alignment under SAMR accelerates food-contact certification for dairy container exports. Ningbo-Zhoushan petrochemical hubs achieve 80% captive integration from ethylene cracking through preform molding.
United States
Gulf Coast ethane crackers supply high-density polyethylene to beverage bottlers in Texas and Georgia. EPA Title V permitting constrains emissions from Baytown and Lake Charles resin complexes. Houston hosts proprietary catalyst R&D centers serving North American automotive blow-molding specifications.
Germany
OEM lightweighting mandates in Bavaria and Baden-Württemberg specify high-flow polypropylene for underhood reservoirs. ECHA substance evaluation drives citrate plasticizer substitution in PVC compounds for dairy packaging. Ludwigshafen and Cologne chemical clusters anchor European medical grade resin qualification.
India
FSSAI compliance infrastructure maturation enables multinational converters to establish dairy and edible oil container production in Maharashtra and Gujarat. DGFT import duty structures favor domestic polyethylene capacity expansion. Mundra and Hazira port zones concentrate integrated resin-to-packaging investments.
Brazil
Sugarcane ethanol feedstock at Triunfo complex supplies bio-based polyethylene for European sustainability-linked procurement. ANVISA pharmaceutical packaging regulations constrain medical grade resin qualification timelines. São Paulo state chemical parks serve Latin American beverage bottler demand.
Global Blow Molding Resins Market Vendor Landscape
Concentration sits with integrated petrochemical majors possessing captive ethylene cracking capacity. Standalone resin distributors face compressed trading margins as feedstock volatility erodes arbitrage opportunities. Two strategic archetypes dominate: Gulf Coast ethane-integrated producers leveraging natural gas liquid economics, and European specialty compounders with validated medical grade portfolios. Competitive moves center on backward integration into cracker assets and direct converter partnerships bypassing distribution intermediaries.
Among North American ethane-integrated producers, Exxon Mobil Corporation and Chevron Phillips Chemical Company exemplify the scale-driven archetype with Gulf Coast cracking positions. LyondellBasell Industries N.V. occupies a technology-differentiated tier through proprietary catalyst systems. Braskem S.A. represents the bio-based specialization vector with sugarcane ethanol feedstock integration. These three anchors demonstrate how geographic feedstock access and technology ownership stratify competitive positioning across beverage, automotive, and medical packaging end-uses.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Formosa Plastics Corporation |
| LyondellBasell Industries N.V. |
| Borealis AG |
| Braskem S.A. |
| Exxon Mobil Corporation |
| Chevron Phillips Chemical Company |
| INEOS Group AG |
| Saudi Basic Industries Corporation (SABIC) |
| Others |
Supply Flow & Price Mechanics
Captive ethylene cracking at China's Ningbo-Zhoushan and US Gulf Coast complexes compresses unit costs below standalone distributor breakeven, concentrating pricing power among integrated producers while forcing trading houses toward specialty grade arbitrage. This scale asymmetry feeds directly into procurement behavior: large beverage bottlers now negotiate direct offtake agreements, bypassing intermediaries whose margins cannot survive feedstock volatility.
Pricing Analysis
Configured-to-order pricing for medical grade formulations commands 40-60% premiums over standard industrial grades due to USP Class VI validation and extractables testing protocols. Contract-based long-term offtake agreements dominate volume procurement, with price differentiation driven by certification level and volume scale. Cost compression in commodity polyethylene is intensifying because metallocene catalyst displacement erodes Ziegler-Natta grade margins. Industrial converters show highest price sensitivity, while pharmaceutical packaging buyers accept premium positioning for validated supply security.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compound inbound logistics costs for European converters sourcing specialty grades from Chinese petrochemical clusters. Supply concentrates in China, the United States, and Germany, with ethane feedstock from Gulf Coast crackers and naphtha from European refineries anchoring regional production. Raw material dependencies include ethylene monomer, catalyst systems, and plasticizer additives. Single-source vulnerability in metallocene catalyst technology concentrates at Houston and Amsterdam technology centers. Distribution runs through direct converter-producer partnerships displacing traditional trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in bio-based polyethylene and certified recycled content grades offers penetration runway as EU Green Deal mandates and brand-owner sustainability commitments accelerate material substitution. India's FSSAI compliance maturation enables first-mover positioning in dairy and edible oil container markets.
For Market Incumbents: Consolidate catalyst technology advantages through proprietary R&D investment at Houston and Amsterdam centers, while locking in long-term offtake agreements with Chinese beverage bottlers before feedstock volatility forces further margin compression. Backward integration into Gulf Coast ethane crackers or Brazilian sugarcane ethanol feedstock secures cost position against emerging bio-based competitors. For New Entrants and Emerging Players: Medical grade compounding capacity scarcity in Europe and India offers white-space entry where USP Class VI validation timelines constrain incumbent expansion. Target India's Maharashtra and Gujarat packaging corridors where FSSAI infrastructure maturation enables dairy container production without legacy distributor relationships. Pursue toll-compounding partnerships with established resin producers to bypass capital-intensive cracker investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty compounders with validated medical grade portfolios over commodity polyethylene producers facing metallocene displacement pressure. Long-term viability rests on certification asset durability and regional regulatory alignment rather than scale economics alone. Monitor ECHA substance evaluation timelines for phthalate restrictions as inflection indicator for plasticizer substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Assets | Gulf Coast ethane economics anchor cost position against naphtha-based European competitors. |
| Medical Grade Certification Investment | USP Class VI validation opens pharmaceutical packaging procurement with 18-24 month supplier lock-in. |
| Bio-based Capacity Scale-Up | Braskem's Triunfo complex demonstrates sugarcane ethanol feedstock viability for EU sustainability mandates. |
| Direct Converter Partnership Agreements | Large Chinese bottlers now bypass distributors for resin offtake security. |
| Recycled Content Certification Program | Extended producer responsibility frameworks in California and New York mandate post-consumer resin incorporation. |
Methodological Framework
Cross-validation between executive interviews at integrated petrochemical producers and customs trade data anchors the qualitative findings in observable material flows. Primary discussions with plant managers, procurement leads at beverage bottlers, distribution channel partners, and technical R&D directors combined with secondary analysis of SEC filings, ACC and Cefic industry reports, and resin trade databases. Bottom-up grade-level demand modeling and top-down ethylene derivative consumption estimates triangulate volume figures.
Sensitivity analysis around feedstock price scenarios and regulatory compliance timelines shapes the projection framework across the analysis window. Segmentation dimensions include polymer chemistry, grade certification tier, end-use application, and regional production hub. CAGRs derive from ethylene derivative demand elasticity modeling and capacity utilization forecasts at named cracker complexes. Industry-specific inputs encompass catalyst technology diffusion rates and REACH amendment probability assessments.
Forecasts assume regulatory continuity in EU REACH and FDA food additive regimes; material policy shifts would require re-modeling. Specific risk factors include ethane price volatility at Gulf Coast crackers, ECHA substance evaluation acceleration for phthalate restrictions, and FSSAI implementation pace in India. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Middle East Polyethylene Market