
 Global Acrylic Solid Surface Market | 2026-2036
Global Acrylic Solid Surface Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Solid Surface Market Foresight
Market Context
Healthcare facility renovation spending is shifting toward antimicrobial surface specifications, pulling acrylic solid surface demand from traditional residential channels. LG Hausys leverages its Korean manufacturing base to dominate hospitality supply chains across Asia-Pacific. DuPont sustains technology leadership through proprietary resin formulations that command specification-grade positioning. Aristech Surfaces LLC anchors North American distribution through captive fabrication networks and architect-direct relationships.
Technical Definition and Segment Structure
Acrylic solid surface denotes a non-porous composite material comprising mineral fillers suspended in acrylic resin, typically thermoformed at temperatures between 160°C and 180°C to create continuous, repairable surfaces for hygienic environments. Non-patterned formulations occupy the volume base in residential kitchen countertops where cost sensitivity governs procurement, while shell particle variants capture margin pools in hospitality vanity applications where visual differentiation commands specification premiums. Custom fabricated installations lead the commercial interiors segment as architects prioritize joint-free aesthetic continuity in retail outlet fit-outs, though modular systems are gaining traction in corporate office rollouts where speed-to-occupancy drives contractor selection.
Regulatory Environment
REACH substance restrictions in Europe and EPA formaldehyde emission standards in the United States constrain resin formulation choices and elevate compliance costs for cross-border suppliers. China's GB standards for interior building materials and Japan's JIS certification requirements create layered market access barriers that favor producers with in-house testing laboratories and regional technical staff. Stakeholders must monitor evolving ESG disclosure rules under the EU CSRD, which will soon require documented supply chain chemical transparency from surface material vendors serving European corporate office and retail outlet developers.
Market Dynamics
Healthcare facility renovation spending is pulling acrylic solid surface demand toward antimicrobial specifications, while hospitality procurement in Southeast Asia prioritizes seamless installation aesthetics over cost minimization.
Growth Catalysts
- EPA Indoor Air Quality Guidelines:Tightening formaldehyde emission standards in the United States are disqualifying conventional laminate competitors from specification-grade projects, opening procurement lanes for low-VOC acrylic alternatives in school and hospital renovations.
- China's Urban Residential Retrofit Cycle:Premium kitchen countertop replacement intervals are compressing in Shanghai, Beijing, and Shenzhen as middle-class homeowners prioritize hygiene and visual refresh over durability longevity.
- Thermoforming Process Advances:Temperature-controlled molding between 160°C and 180°C now enables complex curved geometries for hospitality vanities, differentiating acrylic solid surface from quartz and natural stone in luxury hotel procurement.
Market Restraints
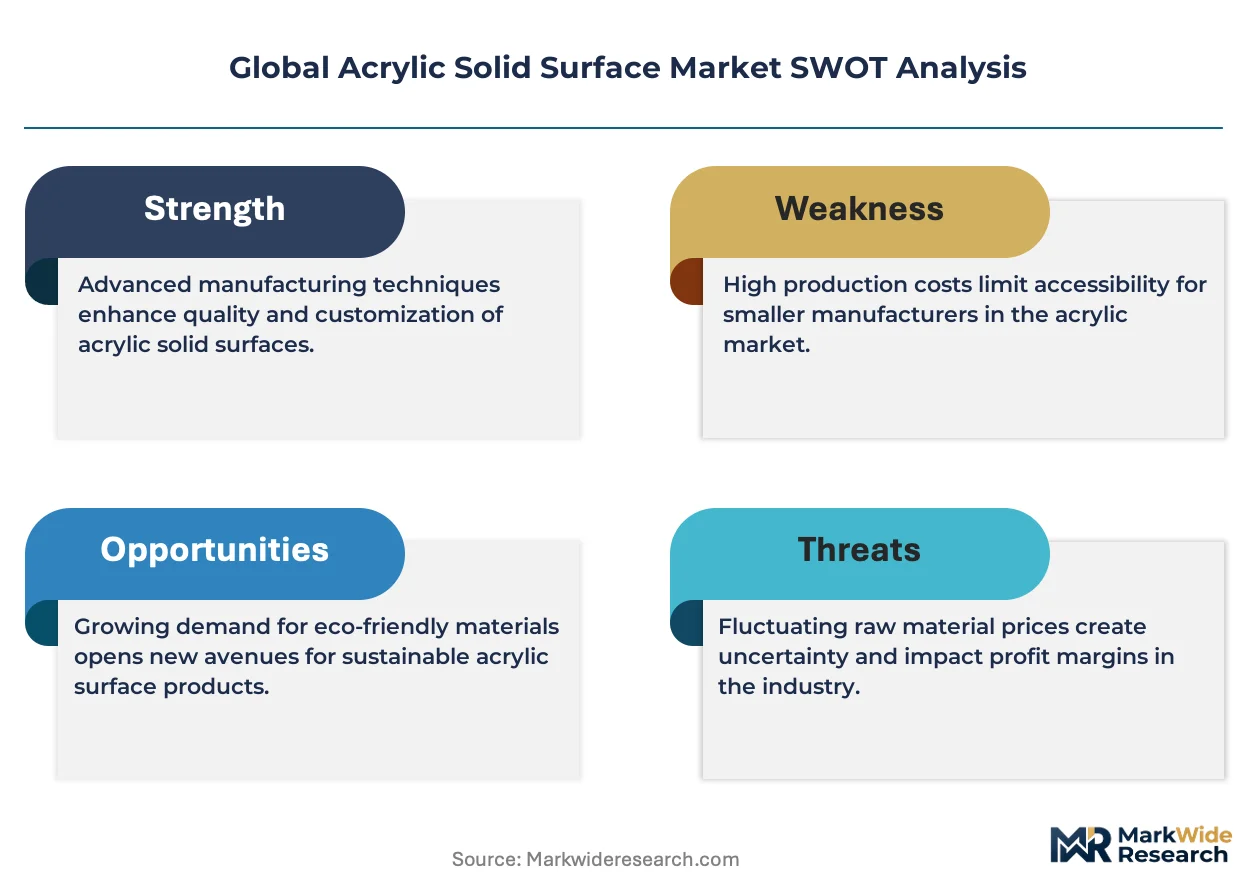
- MMA Monomer Price Volatility:Methyl methacrylate feedstock costs fluctuate with crude oil derivatives and acetone cyanohydrin supply, compressing margin predictability for mid-tier fabricators without long-term resin contracts.
- Korean Supply Concentration:LG Hausys maintains dominant position in Asia-Pacific hospitality supply chains, creating single-source vulnerability for project developers seeking specification diversity and competitive tension.
- Quartz Surface Substitution:Engineered stone with higher Mohs hardness ratings continues displacing acrylic solid surface in residential kitchen segments where scratch resistance outweighs repairability preferences.
Strategic Opportunities
- India's Commercial Interior Build-Out:Underpenetrated corporate office and retail outlet markets in Mumbai, Bangalore, and Hyderabad present white space for modular acrylic systems as speed-to-occupancy pressures intensify.
- EU CSRD Chemical Transparency Mandate:Documented supply chain disclosure requirements create competitive wedge for producers with in-house testing laboratories and regional technical staff serving European corporate developers.
- Antimicrobial Additive Integration:Silver-ion and copper-infused resin formulations are opening specification pathways in healthcare renovation projects where surface hygiene protocols exceed residential standards.
Industry Challenges
- Skilled Thermoforming Technician Scarcity:Complex curved installations require specialized fabricators capable of precision temperature control and seamless joint execution, constraining project scalability in emerging markets.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with REACH substance restrictions, EPA formaldehyde standards, China's GB interior material codes, and Japan's JIS requirements extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Solid Surface Market |
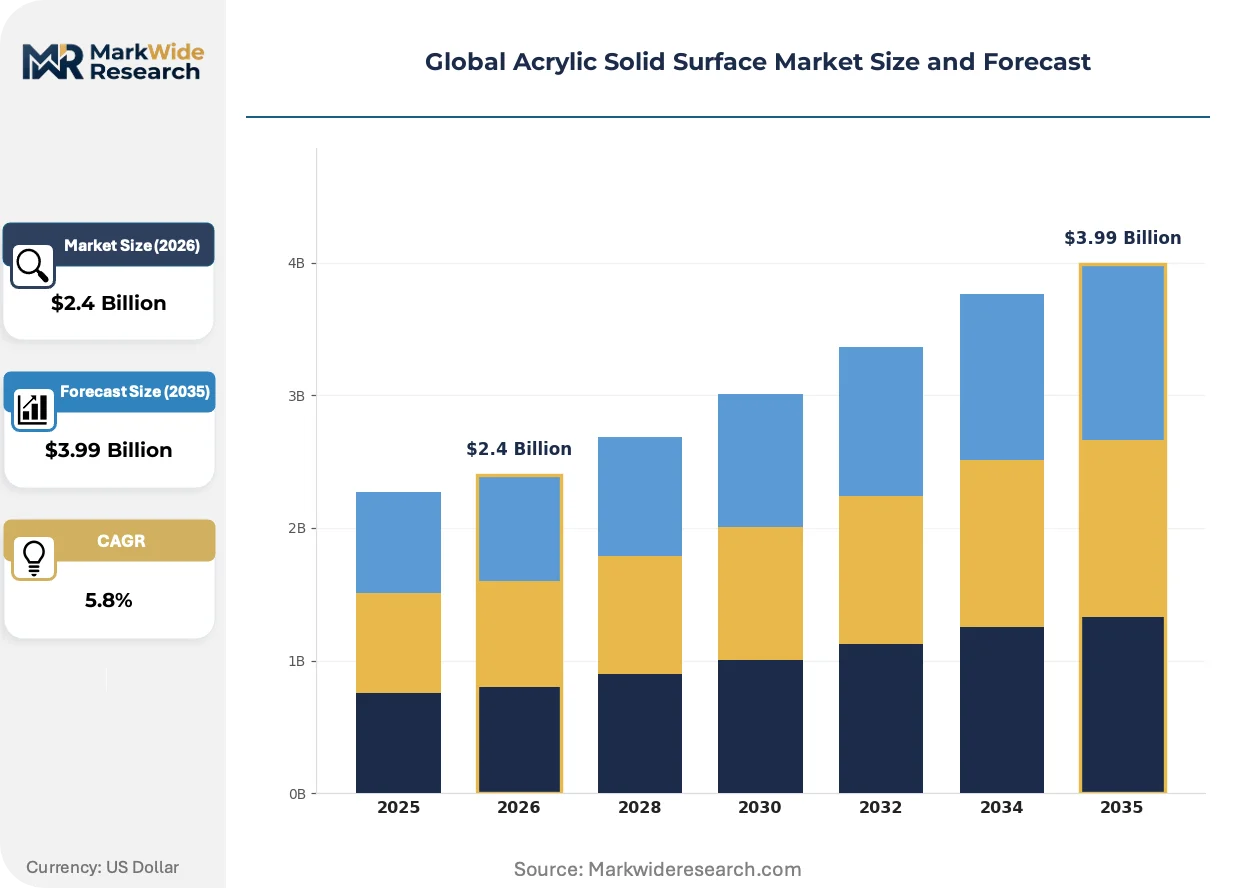
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Patterned, Patterned, Shell Particle, Metallic Flake Application: Kitchen Countertops, Bathroom Vanities, Furniture, Wall Cladding, Commercial Interiors Installation Type: Seamless, Prefabricated, Custom Fabricated, Modular End User Industry: Residential, Hospitality, Retail Outlets, Corporate Offices |
| Companies Covered | Guangzhou Gelandy New Material Co., Ltd, LG Hausys, Durasein, Hyundai L&C, DuPont, Aristech Surfaces LLC, Kingkonree International China Surface Industrial Co., Ltd, LOTTE Chemical Corporation, Wilsonart LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Solid Surface Market Shifts & Advancements
Digital fabrication and regulatory chemistry transparency are reshaping competitive positioning in surface materials, compressing traditional supply chain advantages while opening specification pathways for technically differentiated producers.
Photopolymer resin formulations with embedded shell particles are electrifying hospitality vanity applications, enabling visual depth effects that quartz and natural stone cannot replicate. Luxury hotel developers in Thailand, Vietnam, and Indonesia specify these variants at accelerating rates for guest bathroom renovations. The technology is electrifying margin structures by decoupling pricing from commodity resin cost curves and anchoring value to aesthetic differentiation.
REACH substance restrictions under ECHA oversight are constraining phthalate plasticizer and certain cross-linker chemistries in European-bound production, forcing reformulation investments and elevating compliance documentation burdens. Manufacturers serving EU corporate office and retail outlet developers must maintain dual resin inventories or abandon the region entirely. Healthcare and food-service segments face the tightest scrutiny, with ECHA SVHC candidate list expansion accelerating substitution timelines.
Architect-direct specification models are compressing traditional distributor influence in commercial interiors, with design firms sourcing fabricated components directly from certified workshops. Contractor selection criteria now emphasize digital templating accuracy and installation speed over historical distributor relationships. This pattern concentrates in Southeast Asian hospitality rollouts where international design houses coordinate fit-outs across multiple property portfolios simultaneously.
Global Acrylic Solid Surface Market Segmentation
Material specification in acrylic solid surface procurement hinges on visual differentiation requirements, installation complexity tolerance, and hygiene protocol stringency across end-use environments. Architects, contractors, and facility managers navigate these dimensions simultaneously when selecting product grades and installation methods.
Product Type:
Cost sensitivity governs residential specification patterns, while visual differentiation commands premium positioning in hospitality and luxury commercial applications.
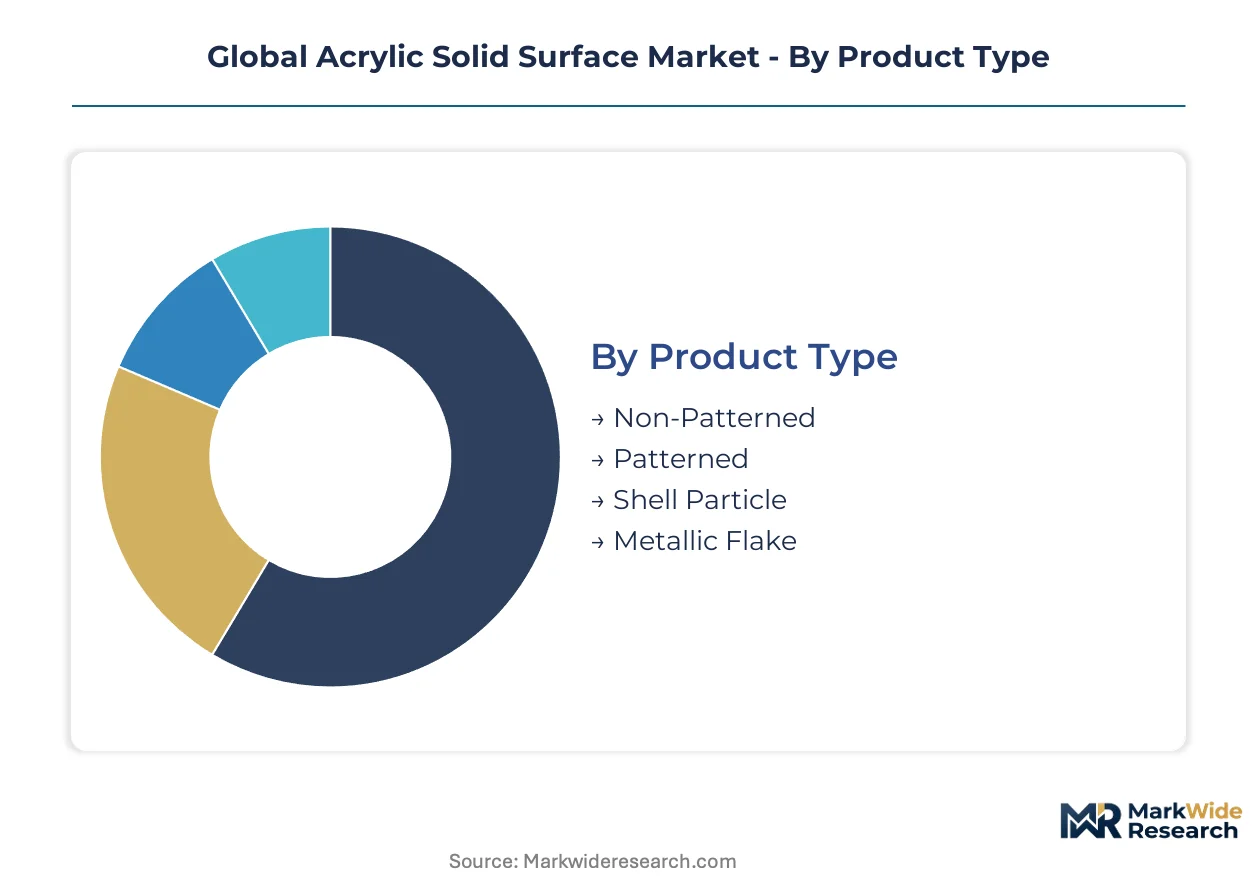
- Non-Patterned:Uniform mineral-acrylic composite without decorative inclusions dominates volume procurement for residential kitchen countertops where budget constraints override aesthetic complexity. Mass-market fabricators in China's urban retrofit corridors standardize on this grade for rapid-turnover replacement cycles.
- Shell Particle:Embedded marine-derived fragments create iridescent depth effects achievable only through proprietary resin suspension techniques. Luxury hotel developers in Thailand, Vietnam, and Indonesia specify these formulations for guest bathroom vanities where Instagram-ready surfaces drive booking premiums.
- Patterned:Engineered veining mimics natural stone aesthetics at lower fabrication cost, capturing mid-market hospitality renovation budgets.
- Metallic Flake:Aluminum or mica inclusions deliver reflective surfaces for nightclub, casino, and flagship retail concepts seeking theatrical material statements.
Non-Patterned leads on scale; Shell Particle leads on momentum.
Application:
Surface area exposure and moisture contact frequency determine material thickness, jointing strategy, and warranty positioning across installation categories.
- Kitchen Countertops:Heat-resistant formulations withstand direct cookware contact in China's premium residential retrofit market, where Shanghai and Shenzhen homeowners prioritize hygiene refresh over durability longevity. Replacement cycles compress as middle-class disposable income rises.
- Bathroom Vanities:Seamless integral sinks eliminate grout lines where moisture penetration risks microbial colonization. Southeast Asian hospitality procurement prioritizes these specifications for luxury hotel renovation portfolios.
- Furniture:Thermoformed tabletops and reception desks exploit acrylic repairability in high-traffic corporate environments.
- Wall Cladding:Vertical surface installations leverage lightweight panels for elevator lobbies and corridor applications.
- Commercial Interiors:Joint-free aesthetic continuity drives architect specification in retail outlet fit-outs across India's underpenetrated metropolitan markets.
Kitchen Countertops anchor volume; Commercial Interiors expand most quickly.
Installation Type:
Speed-to-occupancy pressures and skilled labor availability dictate contractor selection between factory-controlled and site-finished methodologies.
- Custom Fabricated:Workshop-based digital templating and precision thermoforming at 160°C to 180°C enable complex curved geometries for hospitality vanities. Architect-direct specification models concentrate this value chain in Southeast Asian luxury hotel rollouts.
- Seamless:Site-welded joints create continuous surfaces for healthcare and food-service environments where hygiene protocols prohibit microbial harborage points.
- Prefabricated:Standardized dimensions reduce field labor for residential kitchen replacement projects.
- Modular:Panel-and-clip systems accelerate corporate office build-outs in Mumbai, Bangalore, and Hyderabad where lease commencement deadlines drive procurement decisions.
Custom Fabricated dominates specification-grade positioning; Modular gains share fastest.
End User Industry:
Procurement authority structures—homeowner-direct versus architect-led versus facilities manager—shape pricing tolerance and certification documentation requirements.
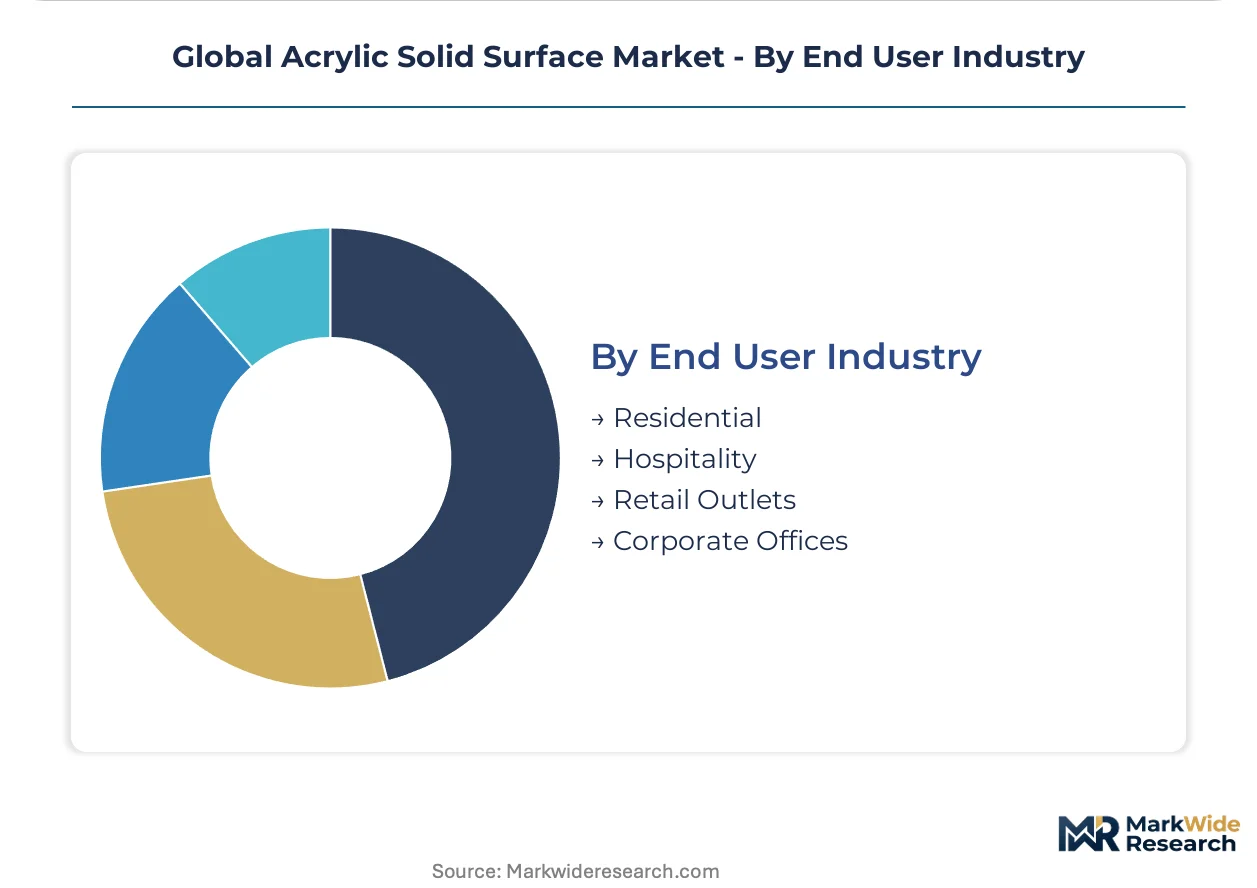
- Hospitality:International design houses coordinate multi-property fit-outs across Thailand, Vietnam, and Indonesia, prioritizing visual differentiation and seamless installation aesthetics over first-cost minimization. Shell particle variants capture specification premiums in this channel.
- Residential:China's urban middle-class homeowners in Beijing, Shanghai, and Shenzhen drive countertop replacement demand through hygiene and aesthetic refresh motivations.
- Retail Outlets:Brand-consistent surface specifications across franchise networks require standardized material grades with regional fabrication support.
- Corporate Offices:ESG disclosure rules under EU CSRD elevate supply chain chemical transparency requirements for European-bound development projects.
Residential supplies volume foundation; Hospitality commands margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors acrylic solid surface manufacturing capacity, with Shanghai and Jiangsu province fabricators supplying both domestic retrofit demand and export orders to Southeast Asian hospitality developers. Regional procurement patterns diverge sharply between mature replacement markets and greenfield commercial construction corridors.
United States
Healthcare facility renovation spending in Texas and Florida drives antimicrobial surface specifications, pulling demand from traditional residential channels. EPA formaldehyde emission standards under the Toxic Substances Control Act constrain laminate competitors, opening procurement lanes for low-VOC acrylic alternatives in school and hospital projects. Fabrication clusters in Georgia and North Carolina serve southeastern commercial construction corridors.
China
Premium kitchen countertop replacement cycles compress in Shanghai, Beijing, and Shenzhen as middle-class homeowners prioritize hygiene refresh over durability longevity. GB standards for interior building materials administered by SAMR elevate compliance documentation burdens for cross-border suppliers. Guangdong province fabricators dominate export supply chains to Thailand and Vietnam hospitality markets.
Germany
REACH substance restrictions under ECHA oversight constrain phthalate plasticizer formulations in European-bound production, forcing reformulation investments. Corporate office developers in Frankfurt and Munich face escalating ESG disclosure requirements under EU CSRD chemical transparency mandates. Bavarian fabricators maintain dual resin inventories to serve both domestic and export specifications.
India
Underpenetrated corporate office and retail outlet markets in Mumbai, Bangalore, and Hyderabad present white space for modular acrylic systems as speed-to-occupancy pressures intensify. BIS certification requirements for interior building materials create market access barriers favoring producers with in-house testing laboratories. Maharashtra-based fabricators scale capacity to capture western India commercial construction demand.
Japan
JIS certification requirements for interior surface materials layer compliance burdens on foreign suppliers seeking market entry. Healthcare renovation spending in Tokyo and Osaka metropolitan areas prioritizes seamless installation aesthetics for hygienic environments. Chubu region fabricators specialize in precision thermoforming for complex curved hospitality vanities serving domestic and export markets.
Global Acrylic Solid Surface Market Competitive Landscape
Capacity expansion dominates the current landscape as Asia-Pacific producers scale fabrication networks to capture Southeast Asian hospitality procurement. The vendor base stratifies across three tiers: Korean and Japanese conglomerates with captive resin production, Chinese mass-market fabricators serving residential replacement cycles, and North American specialists anchored to architect-direct specification channels. Strategic archetypes include vertically integrated chemical producers, regional fabrication networks, and premium-tier specification houses. M&A activity concentrates among mid-tier Chinese fabricators seeking scale, while technology licensing agreements transfer thermoforming process expertise to Indian market entrants.
Among Korean conglomerates, LG Hausys and Hyundai L&C exemplify the integrated-producer archetype with upstream control over resin formulation and downstream fabrication networks. DuPont represents the specification-grade technology leader, anchoring premium positioning through proprietary chemistry. Chinese fabricators including Guangzhou Gelandy New Material Co., Ltd and Kingkonree International China Surface Industrial Co., Ltd occupy the scale-driven tier, serving compressed replacement cycles in urban residential markets through standardized production platforms.
| Leading Market Players |
|---|
| Guangzhou Gelandy New Material Co., Ltd |
| LG Hausys |
| Durasein |
| Hyundai L&C |
| DuPont |
| Aristech Surfaces LLC |
| Kingkonree International China Surface Industrial Co., Ltd |
| LOTTE Chemical Corporation |
| Wilsonart LLC |
| Others |
Supply & Pricing Matrix
Korean conglomerate-owned producers anchor acrylic solid surface manufacturing, their captive resin operations and fabrication networks enforcing pricing discipline across specification-grade and mass-market tiers while compressing margin variability for independent fabricators.
Pricing Analysis
Distributor margin layers separate specification-grade acrylic from mass-market alternatives, with architect-direct procurement bypassing traditional markups for hospitality projects in Thailand and Vietnam. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and thermoforming complexity. Cost compression in mid-tier residential channels intensifies as Chinese fabricators scale standardized production platforms. Residential retrofit buyers in Shanghai and Shenzhen exhibit highest price sensitivity, while luxury hotel developers prioritize visual differentiation over first-cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from Southeast Asian hospitality developers mandate multi-supplier qualification, constraining LG Hausys dominance while elevating Japanese and Chinese alternatives. Manufacturing gravity centers on China, South Korea, and Japan, with Guangdong and Jiangsu province fabricators feeding regional retrofit demand and export orders. Feedstock dependencies rest on methyl methacrylate monomer, mineral filler supply, and antimicrobial additive formulations. Single-source vulnerability around Korean resin supply creates project-level risk for developers seeking specification diversity. Distribution runs through captive fabrication networks for premium tiers and regional distributors for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in antimicrobial additive integration and shell particle formulation premiums, with thermoforming process advances compressing fabrication costs for complex geometries.
For Market Incumbents: To counter quartz surface substitution in residential kitchens, LG Hausys and DuPont should deepen backward integration into proprietary resin formulations while expanding certified fabrication workshops in India to capture corporate office build-out demand. Certification investment in EU CSRD chemical transparency documentation creates competitive moats against mid-tier Chinese competitors. For New Entrants and Emerging Players: Architect-direct specification channels in Southeast Asian hospitality offer the most penetrable entry point, with modular system partnerships targeting Mumbai and Bangalore corporate office deadlines. Silver-ion antimicrobial formulation specialization opens healthcare renovation pathways where incumbents lack dedicated product lines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Chinese fabricators lacking vertical resin control but possessing regional distribution scale. Long-term viability favors producers with in-house testing laboratories spanning REACH, EPA, and GB standard compliance. Watch MMA monomer price volatility as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Additive Integration | Silver-ion formulations unlock healthcare specification pathways exceeding residential hygiene standards. |
| Backward Integration into Resin Production | Captive methyl methacrylate supply insulates margin predictability from feedstock volatility. |
| Modular System Development | Panel-and-clip architectures accelerate Mumbai and Hyderabad corporate office occupancy timelines. |
| EU CSRD Compliance Documentation | Chemical transparency mandates create competitive wedge for producers with in-house testing laboratories. |
| Digital Templating Capability Expansion | Precision measurement technology compresses installation timelines for Southeast Asian hospitality rollouts. |
Research Methodology
Bottom-up residential and commercial modeling reconciled against top-down fabrication capacity tracking forms the analytical core of this study. Primary interviews with hospitality procurement directors, architect specification leads, acrylic fabricator plant managers, and antimicrobial additive suppliers combined with secondary validation from SAMR GB standard filings, ECHA REACH substance registrations, and EPA Toxic Substances Control Act guidance documents. Triangulation across these sources ensures segmentation accuracy across product type, installation method, and end-use industry dimensions.
Input-output matrices map methyl methacrylate feedstock availability through thermoforming capacity to end-use demand across the projection horizon. Segmentation dimensions modeled include material grade tier, installation complexity, regional regulatory cluster, and procurement authority structure. CAGRs derive from regression analysis against construction spending indices and countertop replacement cycle data. Forecast inputs incorporate hospitality renovation pipeline tracking and healthcare facility antimicrobial surface specification trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MMA monomer price volatility, REACH substance restriction expansion, and quartz surface substitution acceleration in premium residential segments. Deviation in Korean supply chain concentration or EPA formaldehyde standard tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Long-Chain Polyamide Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Agar Resin Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market