
 Polymer Memory Market | 2026-2036
Polymer Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Memory Market Analytics
A shortage of organic electronics chemists and thin-film process engineers is unwinding the pace of commercial scale-up across the polymer memory value chain. Intel leverages its advanced packaging expertise to anchor polymer memory integration with conventional CMOS logic. Samsung dominates flexible substrate R&D through captive OLED fabrication knowledge. Fujitsu Ltd navigates niche industrial sensor deployments where polymer memory's low-temperature processing proves decisive.
Polymer memory stores data through resistance or phase states in organic or organometallic thin films rather than silicon-based charge traps, with switching speeds typically spanning microseconds to milliseconds and operating voltages below five volts. Its primary purpose is enabling conformal, lightweight storage for flexible electronics where silicon die brittleness disqualifies conventional alternatives. Non-volatile memory leads product type revenue as wearable and medical patch applications require zero standby power. Conductive polymer technology sustains the fastest technology trajectory due to solution-processability advantages in roll-to-roll manufacturing. Edge computing deployment concentrates margin pools where latency requirements preclude cloud retrieval of trained model parameters.
REACH and RoHS frameworks in Europe restrict halogenated solvents and heavy metals in polymer memory precursor chemistries, elevating compliance costs for non-European suppliers. The EPA and OSHA in the United States enforce workplace exposure limits for aromatic solvents used in spin-coating and inkjet deposition processes. ISO 10993 biocompatibility standards govern polymer memory adoption in wearable medical devices, creating a certification bottleneck that filters out unqualified entrants. Stakeholders must monitor how EU AI Act data localization rules redirect edge storage procurement toward verifiably compliant polymer memory suppliers.
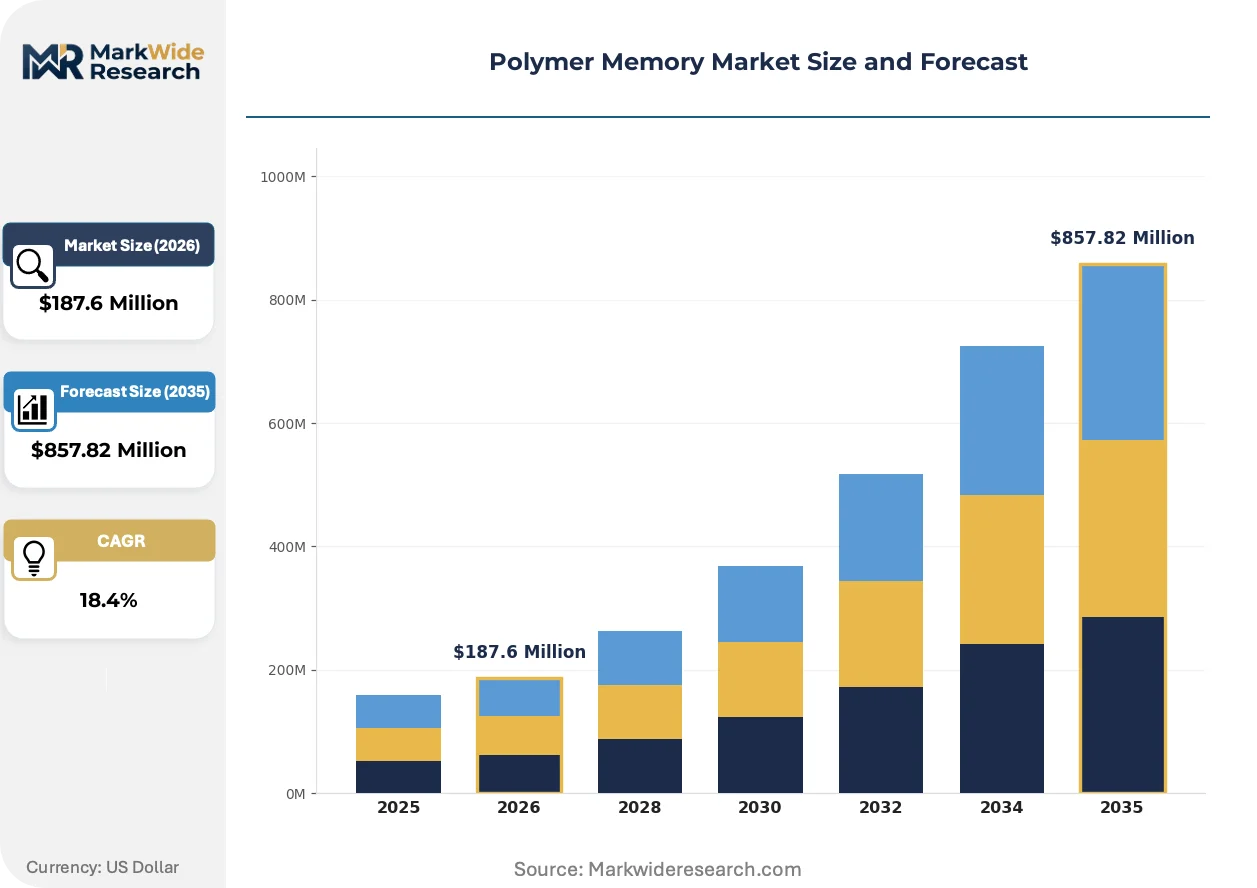
Market Dynamics
The polymer memory market is reshaping around thin-film process chemistry bottlenecks and the geographic concentration of OLED fabrication expertise. South Korean captive production lines are pulling solution-processable memory technology toward roll-to-roll manufacturing scale, while European material disclosure rules force precursor supply chain reconfiguration.
Growth Catalysts
- Automotive ADAS integration:OEMs specify polymer memory for conformal sensor modules where silicon die rigidity creates failure modes. Lightweight substrate requirements in electric vehicle architectures accelerate procurement.
- EU Green Deal material mandates:The framework's circular economy provisions favor organic semiconductor pathways over rare-earth dependent alternatives, redirecting public R&D funding.
- Solution-processable conductive polymers:Inkjet and slot-die coating methods achieve deposition uniformity without vacuum equipment, collapsing capital barriers for new fabrication entrants.
Market Restraints
- Aromatic solvent cost volatility:Toluene and xylene feedstock prices track crude oil indices, compressing margin predictability for spin-coating operations.
- South Korean supply concentration:Dedicated fabrication lines at Samsung and LG Display create single-source dependency risk for flexible substrate capacity.
- Microsecond switching latency ceiling:Resistance-state transition kinetics in organic thin films impose hard performance boundaries against SRAM in edge inference applications.
Strategic Opportunities
- Medical patch wearables:ISO 10993 biocompatibility certification opens chronic disease monitoring applications where zero standby power eliminates battery bulk.
- EU AI Act edge localization:Data sovereignty requirements redirect trained model parameter storage toward verifiably compliant polymer memory suppliers.
- Hybrid CMOS-polymer integration:Advanced packaging architectures converge silicon logic with organic memory layers, enabling three-dimensional circuit density without thermal budget conflicts.
Industry Challenges
- Organic electronics chemist scarcity:Thin-film synthesis expertise concentrates in university laboratories, creating hiring bottlenecks for commercial scale-up teams.
- ISO 10993 certification timelines:Biocompatibility testing protocols extend product qualification cycles by months, filtering out capital-constrained entrants.
- Legacy CMOS integration complexity:Voltage level translation and interface protocol adaptation consume significant design engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Memory Market |
| Market Size in 2026 | $187.6 Million |
| Market Size in 2035 | $857.82 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-volatile Memory, RAM, Flash Memory, Embedded Memory Technology: Phase Change, Electrowetting, Conductive Polymer, Organic Semiconductor End User: Consumer Electronics, Automotive, Industrial, Telecommunications Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Thin Film Technologies, Advanced Micro Devices, Coatue, Intel, Cornerstone Research Group, Samsung, LG Display, Fujitsu Ltd, Micron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Memory Market Evolving Landscape
Roll-to-roll manufacturing economics are compressing polymer memory unit costs while regulatory chemistry restrictions force precursor reformulation. Solution-processable deposition methods are displacing vacuum-based alternatives across multiple end-use verticals.
Conductive polymer technology is bifurcating the memory fabrication landscape. PEDOT:PSS and related organometallic compounds enable room-temperature processing for flexible substrates. Automotive Tier-1 suppliers are adopting these materials for conformal sensor modules at accelerating procurement velocity. The technology is bifurcating production scale between high-volume roll-to-roll lines and precision inkjet patterning for medical devices.
REACH and RoHS frameworks in Europe now restrict halogenated solvents and heavy metals in precursor chemistries. ECHA substance evaluation protocols are elevating compliance documentation burdens for non-European material suppliers. Organic semiconductor vendors are responding by reformulating dopant compounds to eliminate restricted substances before 2027 sunset clauses activate.
Buyer procurement patterns are fragmenting across application-specific certification tiers. Medical device OEMs now require ISO 10993 biocompatibility documentation as a gating criterion, compressing vendor qualification pools. Automotive buyers prioritize IATF 16949 quality system certification over unit cost minimization. This bifurcation is most visible in Germany, where KBA type-approval requirements for vehicle-integrated memory create distinct procurement channels from consumer electronics buyers.
Polymer Memory Market Segmentation
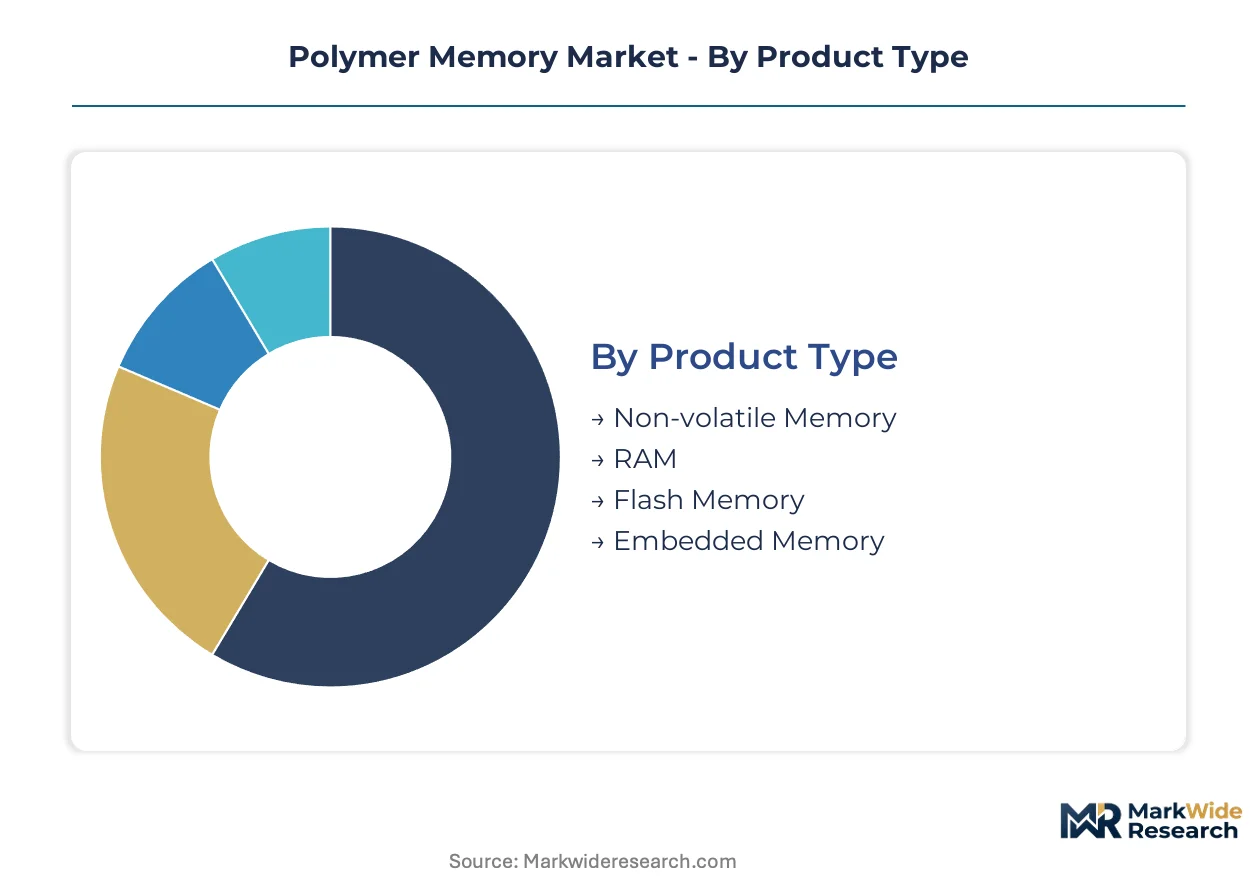
Polymer memory segmentation reflects divergent certification burdens and process chemistry requirements across end-use verticals. Automotive and medical buyers impose distinct qualification protocols that filter supplier pools differently than consumer electronics procurement.
Product Type:
REACH and RoHS substance restrictions elevate compliance costs disproportionately for memory architectures requiring heavy-metal dopants or halogenated precursors.
- Non-volatile Memory:Resistance-state retention in organic thin films eliminates standby power draw, making this architecture mandatory for wearable medical patches where battery bulk compromises patient compliance. ISO 10993 biocompatibility certification timelines extend qualification cycles, filtering out capital-constrained entrants from chronic disease monitoring contracts.
- RAM:Volatile polymer memory architectures sacrifice retention for switching speed, finding niche deployment in industrial sensor buffers where power cycling frequency exceeds data persistence requirements. Microsecond latency ceilings constrain penetration against silicon SRAM in edge inference applications.
- Flash Memory:Charge-trap analogs in organometallic thin films face ECHA substance evaluation protocols for precursor reformulation.
- Embedded Memory:Monolithic integration with flexible substrates suits automotive conformal modules where KBA type-approval mandates traceable supply chains.
Established volume favors Non-volatile Memory; emerging adoption favors Embedded Memory.
Technology:
Capital intensity separates solution-processable methods from vacuum-dependent alternatives, with roll-to-roll manufacturing collapsing unit costs for inkjet-compatible chemistries.
- Conductive Polymer:PEDOT:PSS and related organometallic compounds enable room-temperature deposition without vacuum equipment, anchoring high-volume production for flexible substrate applications. Samsung and LG Display have established dedicated fabrication lines in South Korea, pulling solution-processable technology toward manufacturing scale.
- Phase Change:Thermal cycling endurance in chalcogenide-organic hybrids addresses industrial temperature extremes where resistance-state stability determines field reliability.
- Electrowetting:Droplet manipulation architectures require precision coating uniformity that constrains scaling beyond laboratory demonstration.
- Organic Semiconductor:Purified small-molecule thin films compete on carrier mobility benchmarks against amorphous silicon alternatives.
Conductive Polymer commands dominant volume share; Phase Change is gaining share fastest in industrial sensor deployments.
End User:
Procurement authority concentrates differently across verticals, with automotive Tier-1 suppliers prioritizing IATF 16949 certification over unit cost minimization.
- Automotive:OEM specifications for conformal ADAS sensor modules exploit polymer memory substrate flexibility where silicon die rigidity creates thermal cycling failure modes. Electric vehicle lightweighting requirements accelerate procurement velocity for grams-sensitive storage architectures.
- Consumer Electronics:Wearable device form factors demand conformal storage that accommodates skin-contact curvature without encapsulation bulk.
- Industrial:Low-temperature processing enables polymer memory integration with temperature-sensitive substrates in distributed sensor networks.
- Telecommunications:Edge computing latency requirements redirect trained model parameter storage toward localized polymer memory layers.
Consumer Electronics sustains established volume; Automotive shows the steepest expansion trajectory.
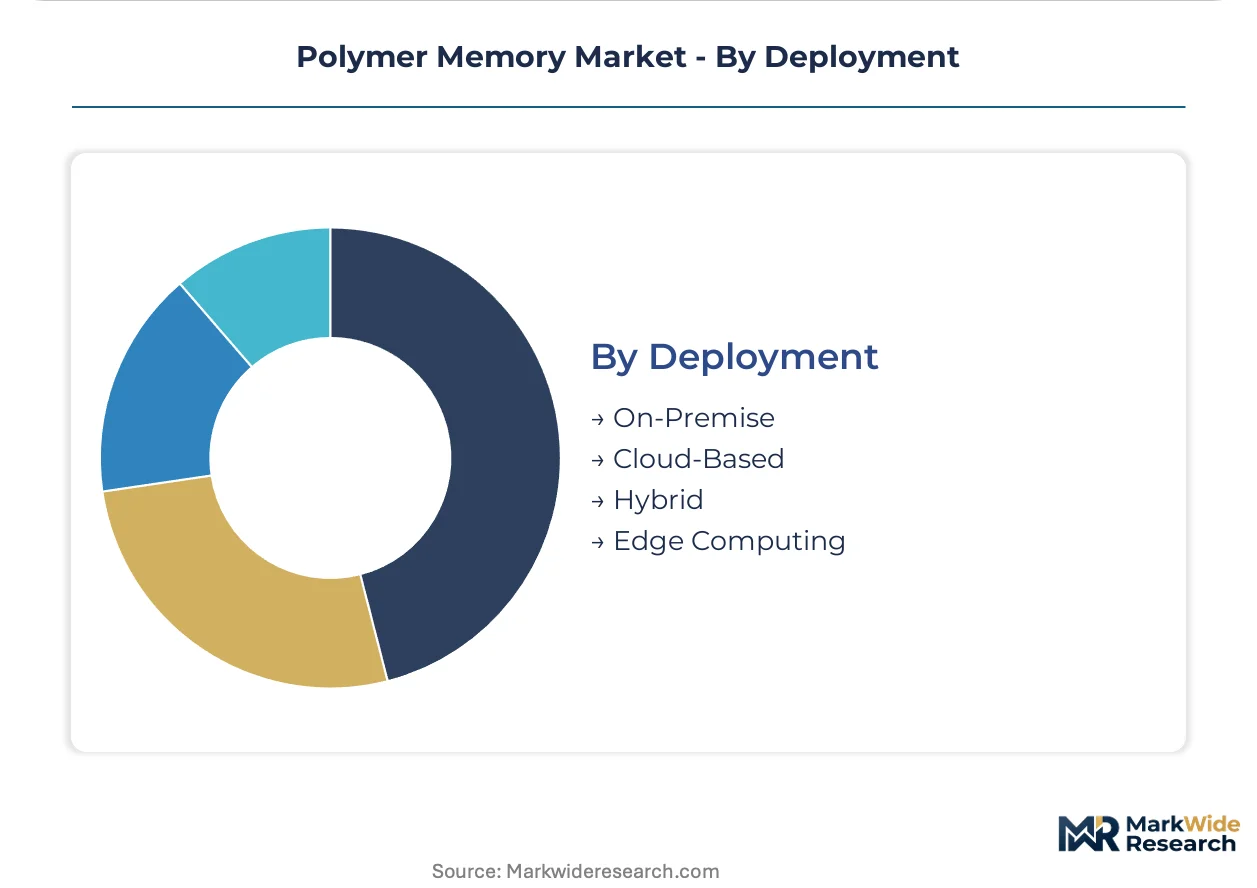
Deployment:
Data sovereignty regulations fragment procurement patterns, with EU AI Act localization rules redirecting edge storage toward verifiably compliant suppliers.
- Edge Computing:Inference-at-the-edge architectures require microsecond-retrieval storage for trained model parameters where cloud latency disqualifies remote retrieval. Polymer memory's non-volatile retention eliminates standby power draw in distributed nodes without grid connectivity.
- Hybrid:Tiered storage hierarchies combine polymer memory cache layers with conventional NAND for cost-optimized capacity.
- On-Premise:Enterprise data center deployments face EPA workplace exposure limits for aromatic solvents in module manufacturing.
- Cloud-Based:Hyperscaler procurement prioritizes bit-density economics that polymer memory currently cannot match at data center scale.
On-Premise retains incumbent volume; Edge Computing represents the fastest-climbing adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. South Korea deploys polymer memory primarily for flexible display integration, while Germany prioritizes automotive conformal modules under KBA type-approval mandates. The United States concentrates procurement in medical wearables requiring FDA and ISO 10993 alignment.
South Korea
Samsung and LG Display operate dedicated fabrication lines for solution-processable polymer memory in the Seoul Capital Area. MFDS biocompatibility guidelines govern medical wearable exports, accelerating certification investments. The Busan-Ulsan corridor hosts thin-film coating equipment suppliers scaling roll-to-roll deposition systems.
Germany
Automotive OEMs in Bavaria specify polymer memory for ADAS sensor modules where substrate flexibility prevents thermal cycling failures. REACH substance disclosure rules force precursor supply chain reconfiguration for ECHA compliance deadlines. The Stuttgart industrial cluster concentrates Tier-1 supplier procurement authority under IATF 16949 quality mandates.
United States
Medical device manufacturers in the Boston and San Francisco metros demand ISO 10993-certified polymer memory for chronic disease monitoring patches. FDA enforcement of biocompatibility documentation extends product qualification timelines. EPA workplace exposure limits for aromatic solvents in spin-coating operations constrain manufacturing site selection.
China
MIIT industrial policy directs public R&D funding toward organic semiconductor alternatives to silicon-dependent memory architectures. GB standards for flexible electronics create domestic certification pathways distinct from ISO frameworks. The Yangtze River Delta hosts pilot production lines integrating polymer memory with OLED backplane fabrication.
Japan
METI technology roadmaps prioritize low-temperature processing for polymer memory integration with temperature-sensitive substrates. JIS standards for flexible electronics create procurement specifications for industrial sensor networks. The Kansai region concentrates thin-film process engineering expertise from captive OLED and printed electronics supply chains.
Polymer Memory Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in polymer memory supply. Samsung and Intel anchor the upper tier through captive fabrication and advanced packaging integration respectively. The middle tier fragments across conductive polymer specialists, phase-change material vendors, and thin-film deposition equipment suppliers. Two competitive moves dominate: strategic partnerships bridging CMOS logic with organic memory layers, and geographic expansion into South Korean and German automotive supply chains.
Within the integrated tier, Samsung, Intel, and Fujitsu Ltd occupy distinct positioning vectors. Samsung exemplifies display-captive verticality, leveraging OLED fabrication knowledge for flexible substrate R&D. Intel represents advanced packaging convergence, anchoring polymer memory integration with conventional CMOS logic. Fujitsu Ltd sits within the niche industrial deployment archetype, where low-temperature processing requirements filter supplier pools. These three entities collectively illustrate how technology trajectories bifurcate between high-volume roll-to-roll manufacturing and precision application-specific qualification.
| Leading Market Players |
|---|
| Thin Film Technologies |
| Advanced Micro Devices |
| Coatue |
| Intel |
| Cornerstone Research Group |
| Samsung |
| LG Display |
| Fujitsu Ltd |
| Micron |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between South Korean display manufacturers and aromatic solvent suppliers lock in feedstock access and price visibility for conductive polymer precursor production, insulating roll-to-roll fabrication lines from crude oil index volatility that compresses spot-market margins for European spin-coating operations.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Samsung, LG Display, and their precursor chemical suppliers, with price differentiation driven by ISO 10993 biocompatibility certification tier and volume scale commitments. Premium pricing attaches to medical-grade conductive polymers qualifying for FDA-cleared wearable patches, while automotive Tier-1 buyers under IATF 16949 mandates absorb cost premiums for traceable supply chains. Cost compression in standard-grade conductive polymers intensifies as Chinese pilot production lines achieve deposition uniformity benchmarks. Consumer electronics OEMs exhibit highest price sensitivity, whereas medical device manufacturers prioritize certification documentation over unit cost minimization.
Supply Chain Analysis
South Korea and Germany anchor polymer memory fabrication, with the Seoul Capital Area hosting dedicated roll-to-roll lines and Bavaria concentrating automotive conformal module assembly. Precursor chemistry draws from toluene and xylene feedstocks, PEDOT:PSS organometallic compounds, and flexible polyimide substrates. Single-source vulnerability concentrates in South Korean OLED backplane integration capacity, where Samsung and LG Display control flexible substrate throughput. Distribution runs through Tier-1 automotive suppliers in Germany and direct OEM relationships in medical device clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer memory is approaching a platform-economics inflection where hybrid CMOS-polymer integration architectures create interoperability moats, with Intel's advanced packaging roadmap and Samsung's OLED backplane expertise establishing competing ecosystem standards that will determine which process chemistry achieves manufacturing scale.
For Market Incumbents: Fortify captive fabrication advantages by deepening backward integration into conductive polymer precursor synthesis and securing dedicated capacity reservations with South Korean coating equipment suppliers. The threat of microsecond-latency silicon SRAM in edge inference applications demands defensive patent positioning around three-dimensional hybrid integration architectures, while REACH substance disclosure deadlines elevate compliance investment as a competitive filter. For New Entrants and Emerging Players: Anchor in ISO 10993-certified medical wearable segments where biocompatibility documentation requirements compress incumbent vendor pools and create qualification bottlenecks for capital-constrained rivals. Industrial sensor networks in Japan's Kansai region represent underpenetrated white space where low-temperature processing requirements filter supplier pools. A go-to-market angle emphasizing room-temperature deposition compatibility with temperature-sensitive substrates bypasses vacuum-equipment capital barriers. For Investors and Strategic Acquirers: Capital is best deployed toward thin-film process engineering specialists with captive university laboratory pipelines and established ECHA compliance documentation, given the five-to-ten-year window required for organic electronics chemist talent scarcity to unwind. The signal to watch is South Korean government funding announcements for domestic precursor chemical synthesis capacity, which would indicate ecosystem maturation toward mass production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | ECHA REACH compliance deadlines elevate vertical control over restricted substance elimination. |
| ISO 10993 Certification Investment | FDA-cleared medical wearable procurement channels filter out unqualified conductive polymer entrants. |
| Hybrid CMOS-Polymer Packaging Partnership | Intel's advanced packaging expertise anchors ecosystem standard-setting for logic-memory integration. |
| Roll-to-Roll Manufacturing Scale-Up | Samsung and LG Display captive lines in South Korea compress unit costs for flexible substrate applications. |
| EU AI Act Compliance Positioning | Data localization requirements redirect edge storage procurement toward verifiably compliant organic memory suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the polymer memory value chain, including thin-film process engineers at OLED fabrication facilities, procurement leads at automotive Tier-1 suppliers, regulatory affairs specialists navigating ECHA substance evaluation protocols, and biomedical engineers designing chronic disease monitoring patches. Secondary validation drew from SEC filings of advanced packaging semiconductor firms, ECHA substance restriction updates, MFDS biocompatibility guideline revisions, and IHS Markit vehicle production databases. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Across the analysis window, the forecasting framework modeled revenue and volume trajectories by product type, technology, end-user vertical, and deployment architecture, with additional segmentation by regional regulatory cluster and certification tier. CAGRs were derived from logistic diffusion curves fitted to adoption velocity in automotive ADAS and medical wearable applications. Key inputs included aromatic solvent price indices, OLED backplane capacity utilization rates, and ISO 10993 certification pipeline data.
Underlying assumptions cover REACH substance restriction implementation timelines and South Korean fabrication capacity expansion schedules, with deviation risk concentrated in organic electronics chemist hiring bottlenecks and microsecond switching latency ceilings constraining edge inference penetration. Recalibration cycles align with material shifts in EU AI Act enforcement patterns and ECHA sunset clause activations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Calendering Resins Market