
 Polyphenylene Sulfide (PPS) Resin Market | 2026-2036
Polyphenylene Sulfide (PPS) Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenylene Sulfide (PPS) Resin Market Analytics
China is reshaping regional supply dynamics through expanded PPS polymerization and compounding investments. Celanese Corporation leverages its integrated acetyls chain to secure precursor supply for captive PPS output. Toray Industries anchors Japanese high-grade resin production for semiconductor equipment and EV powertrains. SK Chemicals differentiates through specialty compounding capabilities serving Korean battery OEMs.
Polyphenylene sulfide resin is a semi-crystalline thermoplastic composed of aromatic rings linked by sulfur atoms, exhibiting continuous service temperatures above 200°C, inherent flame retardancy, and resistance to automotive fluids and strong acids. Manufacturers produce it primarily through the reaction of p-dichlorobenzene with sodium sulfide in polar solvents, yielding polymers that replace metals and thermosets in precision-engineered components. Glass-filled formulations dominate volume consumption due to their stiffness-to-cost ratio in under-hood automotive and electrical housing applications. Powder grades for coating and film extrusion represent faster-growing niches as industrial equipment makers seek corrosion protection without VOC-emitting alternatives.
EPA fuel economy standards and NHTSA safety regulations in the United States push automakers toward lighter thermal-resistant polymers, while China's MEE enforces stricter VOC limits that favor PPS powder coatings over solvent-based systems. REACH restrictions on halogenated flame retardants in Europe reinforce PPS adoption where inherent fire resistance eliminates additive requirements. Stakeholders must monitor feedstock sulfur and benzene derivative costs alongside evolving automotive platform electrification timelines to calibrate capacity and formulation investments.
Market Dynamics
Automotive electrification is compressing design cycles for thermal-resistant polymers, forcing compounders to synchronize PPS formulation development with battery platform roadmaps rather than traditional model-year schedules.
Growth Catalysts
- EPA fuel economy mandates:NHTSA-aligned standards push automakers toward under-hood metal replacement to achieve weight targets, directly expanding glass-filled PPS consumption in charge air coolers and water pump housings.
- China's dual carbon framework:MEE enforcement of industrial VOC limits accelerates powder coating substitution for solvent-based systems across chemical processing equipment and power transmission infrastructure.
- Semiconductor equipment fabrication:Wafer handling components and chamber hardware demand ultra-high-purity PPS grades capable of withstanding aggressive plasma chemistries during etch and deposition processes.
Market Restraints
- Sodium sulfide supply concentration:Precursor availability clusters with Chinese petrochemical complexes, exposing non-integrated compounders to input volatility and sulfur price swings.
- High-temperature thermoset competition:Polyimide and bismaleimide resins retain cost advantages in aerospace structural applications above 250°C continuous service requirements.
- REACH substance evaluation:ECHA scrutiny of residual chlorinated impurities in polymerization-grade PPS creates compliance documentation burdens for European compounders serving medical device OEMs.
Strategic Opportunities
- Indian specialty chemical manufacturing:PLI scheme incentives for advanced materials localization attract PPS compounding investments serving domestic automotive and electrical component demand.
- Hydrogen infrastructure deployment:Electrolyzer stack frames and fuel cell bipolar plates require chemically resistant, dimensionally stable thermoplastics in emerging European and Korean hydrogen hub projects.
- Film extrusion for 5G base stations:Low-dielectric-loss PPS films enable high-frequency circuit substrates as telecom infrastructure expands across Japanese and US metropolitan corridors.
Industry Challenges
- Polymerization process engineering talent:Captive PPS resin production requires expertise in high-pressure nucleophilic substitution chemistry that concentrates among aging specialists at Japanese and German chemical conglomerates.
- Automotive qualification timelines:OEM validation protocols for new under-hood materials extend 24-36 months, mismatching PPS development cycles with accelerating EV platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenylene Sulfide (PPS) Resin Market |
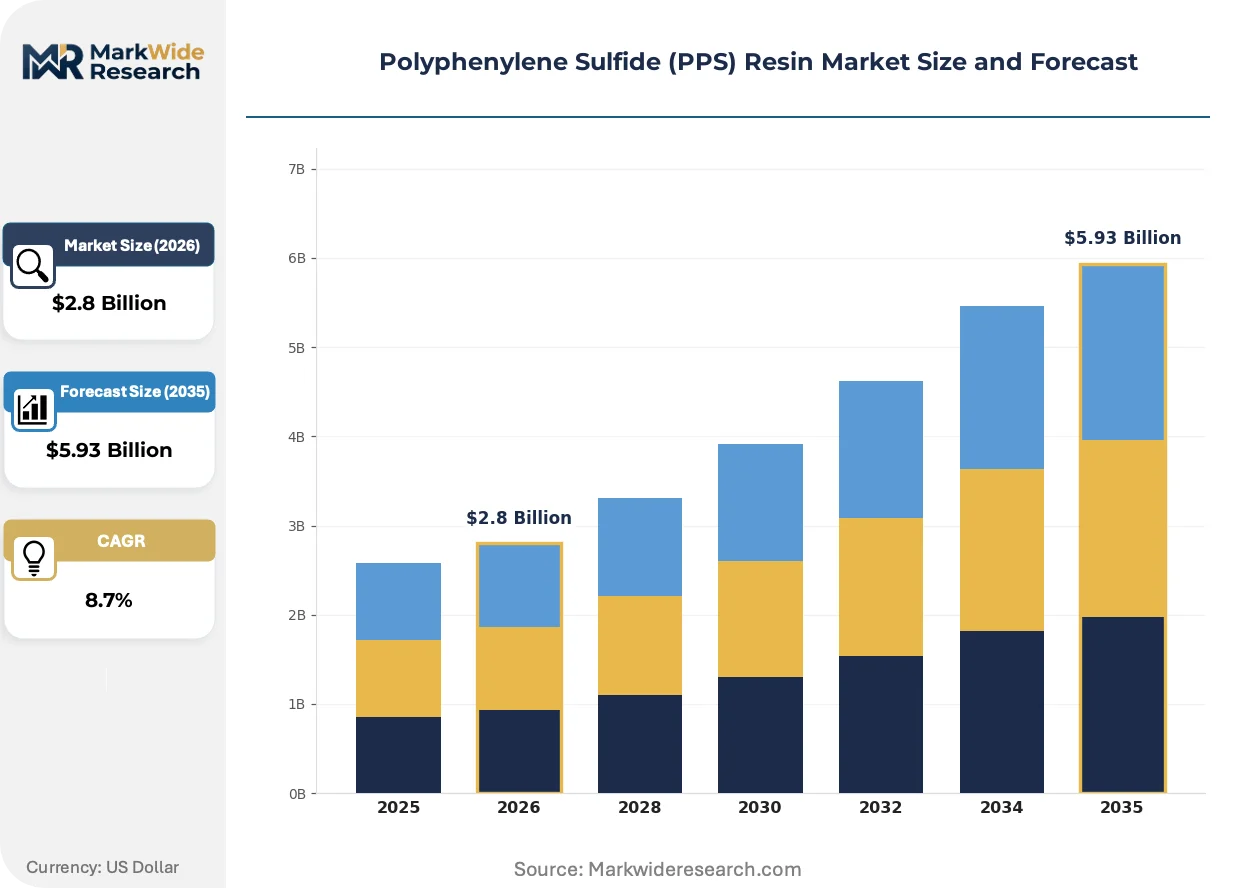
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfilled, Glass-Filled, Mineral-Filled, Carbon-Filled Application: Electrical Components, Automotive Parts, Industrial Equipment, Consumer Goods End Use Industry: Aerospace, Electronics, Automotive, Healthcare Form: Pellets, Powder, Film, Sheets |
| Companies Covered | Celanese Corporation, SABIC, Toray Industries, Inc., BASF SE, SK Chemicals, DIC Corporation, NHU Materials Co., Ltd., Huntsman Corporation, Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenylene Sulfide (PPS) Resin Market Evolving Landscape
Material science advances and regulatory pressure are converging to expand PPS from traditional automotive and electrical enclosures into precision-engineered films, coatings, and structural composites requiring tailored property profiles.
Long-fiber thermoplastic (LFT) PPS compounds are migrating from injection-molded automotive brackets to structural battery module frames and electric motor housings. Tier-1 suppliers in Germany and Japan are qualifying these materials for crash-load-bearing applications previously reserved for aluminum castings. The shift is compressing the traditional metals-to-plastics substitution timeline by integrating structural simulation directly into resin formulation development.
REACH restrictions on halogenated flame retardants are eliminating additive-dependent thermoplastics from European electrical housing markets. ECHA enforcement of substance restrictions favors inherently flame-resistant PPS in server chassis, EV charging connectors, and industrial control enclosures. Compounders are responding by expanding unfilled and mineral-filled grades that meet UL 94 V-0 without brominated or phosphorus-based additives.
Japanese battery OEMs are consolidating supplier bases around compounders offering integrated material-recycling programs. SK Chemicals and Toray Industries now bundle closed-loop PPS recovery with virgin resin supply contracts, displacing spot-market procurement for Korean and Chinese cell manufacturers. The model concentrates volume with vertically integrated compounders capable of mechanical recycling and re-compounding at scale.
Polyphenylene Sulfide (PPS) Resin Market Segmentation
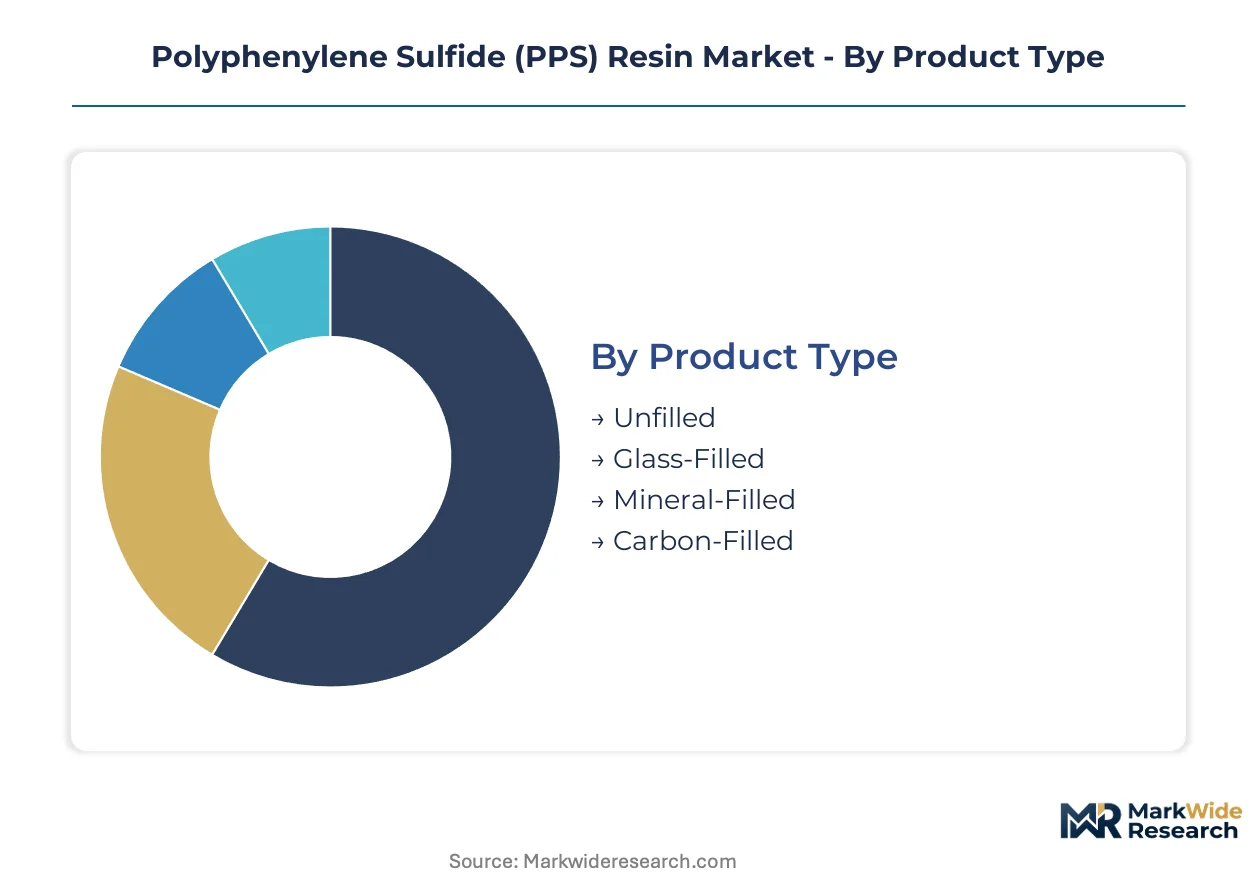
PPS resin formulations diverge sharply across thermal, mechanical, and electrical specifications. Each segment serves distinct qualification protocols and procurement economics.
Product Type:
Cost tier stratification determines compounding complexity and raw material loading ratios.
- Glass-Filled:Incorporates 30-40% chopped or milled glass fiber to achieve flexural modulus above 10 GPa and HDT exceeding 250°C. Demand clusters in charge air coolers and water pump housings for US and Chinese automakers facing NHTSA and MIIT fuel economy mandates. EPA-aligned weight reduction programs expand consumption faster than other grades.
- Unfilled:Virgin polymer without reinforcement offers superior surface finish and dimensional stability for precision-molded electrical connectors. Japanese semiconductor equipment fabricators specify ultra-high-purity unfilled grades for wafer handling components exposed to fluorinated plasma chemistries.
- Mineral-Filled:Talc or calcium carbonate loading reduces warpage and improves isotropic shrinkage for large housings.
- Carbon-Filled:Conductive formulations target electromagnetic shielding applications in 5G base station infrastructure and EV charging systems.
Glass-filled holds installed capacity. Carbon-filled is rotating up the share rankings.
Application:
Application scope tracks directly against regulatory pressure points and platform electrification timelines.
- Automotive Parts:Under-hood metal replacement dominates volume, with battery module frames and thermal management hardware consuming long-fiber thermoplastic compounds. Chinese dual carbon enforcement and tightening MEE emissions standards accelerate substitution of aluminum castings in East Asian manufacturing corridors.
- Electrical Components:Relay housings, connector bodies, and circuit breaker architectures exploit inherent UL 94 V-0 flame resistance without halogenated additives. REACH restrictions on brominated flame retardants in Europe displace competing thermoplastics from server chassis and industrial control enclosures.
- Industrial Equipment:Chemical processing pumps, valves, and filtration housings leverage PPS corrosion resistance against strong acids and hot aqueous environments.
- Consumer Goods:Small appliance housings and cookware components represent price-sensitive demand with lower specification thresholds.
Automotive parts command formulation priority. Electrical components are climbing the fastest.
End Use Industry:
Customer type maturity shapes qualification duration and contract structure.
- Automotive:OEM validation protocols extend 24-36 months, locking compounders into platform-specific development cycles. Korean and Chinese battery manufacturers now bundle closed-loop recycling contracts with virgin resin procurement.
- Electronics:Semiconductor equipment fabricators demand sub-ppm metallic contamination specifications and lot-to-lot consistency certificates.
- Aerospace:Structural applications above 250°C continuous service face polyimide and bismaleimide competition on cost.
- Healthcare:ECHA scrutiny of residual chlorinated impurities creates compliance documentation burdens for European compounders serving medical device OEMs.
Automotive anchors volume commitment. Electronics is gaining share fastest.
Form:
Supply concentration varies by processing technology and capital intensity.
- Pellets:Standard injection molding feedstock dominates compounding output. Automotive tier-1 suppliers in Germany and Japan specify pellet grades with optimized melt flow for thin-wall electrical housings.
- Powder:Fluidized bed and electrostatic coating applications expand with China's MEE enforcement of industrial VOC limits. Powder grades substitute for solvent-based systems across chemical processing equipment and power transmission infrastructure.
- Film:Low-dielectric-loss extruded substrates enable high-frequency circuit boards for 5G deployment in Japanese and US metropolitan corridors.
- Sheets:Compression-molded plate stock serves prototype and low-volume fabrication.
Pellets hold installed capacity. Powder is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT emissions mandates and China's dual carbon framework anchor East Asian demand concentration for PPS resin. EPA fuel economy standards and NHTSA safety regulations in the United States compress automotive qualification timelines for thermal-resistant polymers. REACH substance restrictions in Europe redirect electrical housing procurement toward inherently flame-retardant thermoplastics.
China
Automotive electrification and industrial powder coating substitution drive PPS consumption across the Yangtze River Delta manufacturing corridor. MEE enforcement of VOC limits accelerates solvent-based system replacement in chemical processing equipment. Zhejiang and Jiangsu provinces host expanding polymerization investments serving domestic battery OEMs and export-oriented automotive tier-1 suppliers.
United States
EPA-aligned weight reduction programs expand glass-filled PPS consumption in under-hood components and thermal management modules. NHTSA safety regulations push automakers toward metal replacement in crash-load-bearing applications. Michigan and Ohio automotive clusters concentrate compounding partnerships synchronized with Detroit Three EV platform roadmaps.
Japan
Semiconductor equipment fabricators in the Chubu region demand ultra-high-purity unfilled grades for wafer handling components. METI industrial policy supports domestic high-grade resin production for plasma-resistant applications. Nagoya and Osaka manufacturing corridors anchor Toray Industries' specialty compounding operations serving precision electronics OEMs.
Germany
REACH restrictions on halogenated flame retardants displace additive-dependent thermoplastics from server chassis and industrial control enclosures. ECHA substance evaluation creates compliance documentation requirements for medical device compounders. Bavaria and Baden-Württemberg automotive clusters qualify long-fiber thermoplastic compounds for structural battery module frames.
South Korea
Battery OEMs consolidate supplier bases around compounders offering closed-loop recycling programs bundled with virgin resin contracts. MFDS regulatory alignment with international standards shapes medical-grade PPS qualification protocols. Busan-Ulsan and Seoul Capital Area manufacturing corridors concentrate SK Chemicals' specialty compounding serving domestic cell manufacturers.
Polyphenylene Sulfide (PPS) Resin Market Competitive Landscape
Capability concentration sits with integrated petrochemical conglomerates; scale advantage sits with diversified materials multinationals. The vendor base stratifies across three tiers: captive resin producers with backward integration into sulfur chemistry, independent compounders serving regional automotive clusters, and specialty formulators targeting semiconductor and medical device OEMs. Dominant competitive moves include capacity expansion synchronized with EV platform launches and strategic partnerships bundling material supply with mechanical recycling services.
Among integrated chemical producers, Celanese Corporation exemplifies the acetyls-chain-integrated archetype with captive precursor supply. Toray Industries anchors Japanese high-grade production for precision electronics applications. SK Chemicals occupies a position within the specialty compounding tier serving Korean battery OEMs with bundled recycling contracts.
| Leading Market Players |
|---|
| Celanese Corporation |
| SABIC |
| Toray Industries, Inc. |
| BASF SE |
| SK Chemicals |
| DIC Corporation |
| NHU Materials Co., Ltd. |
| Huntsman Corporation |
| Solvay S.A. |
| Others |
Value Network & Pricing Analysis
Sodium sulfide supply concentration in Chinese petrochemical corridors determines both pricing tier spreads and supply chain shape for non-integrated compounders exposed to sulfur price swings and input volatility.
Pricing Analysis
East Asian spot markets trade at premiums to European contract offtake due to freight differentials and tariff exposure. Pricing stratifies across premium, standard, and economy tiers based on purity grade and UL 94 V-0 certification status. Cost compression in standard glass-filled grades is intensifying because Korean battery OEMs are consolidating procurement around bundled recycling contracts. Automotive tier-1 suppliers show least price sensitivity; consumer goods molders exhibit highest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for North American compounders. Production gravity centers on China, Japan, and South Korea, with p-dichlorobenzene feedstock drawing from integrated acetyls chains in Zhejiang and Jiangsu provinces. Single-source vulnerability concentrates in sodium sulfide precursors tethered to sulfur recovery operations. Distribution runs through regional compounding hubs synchronized with automotive platform launches.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification is fragmenting demand across battery chemistry variants and thermal management architectures, creating specialist formulation niches that favor targeted entrants over generalist incumbents.
For Market Incumbents: Build captive precursor supply moats through backward integration into sulfur chemistry or long-term offtake agreements with Chinese petrochemical complexes. Celanese Corporation's acetyls-chain integration exemplifies this defensive posture. Add compounding capacity in Michigan and Ohio corridors to match Detroit Three EV platform roadmaps. Secure UL 94 V-0 certification breadth to defend against REACH-driven substitution in European electrical housings.
For New Entrants and Emerging Players: Establish a beachhead in Indian specialty chemical manufacturing under PLI scheme incentives for advanced materials localization. Target powder coating formulations for chemical processing equipment serving China's MEE VOC enforcement. Penetrate through technical partnership models with domestic automotive tier-1 suppliers rather than direct OEM qualification.
For Investors and Strategic Acquirers: REACH substance evaluation timelines reshaping the acquisition landscape toward compounders with pre-validated ECHA documentation for medical-grade PPS. Long-term viability rests on hydrogen infrastructure deployment trajectories and 5G base station film demand. Target acquisition archetype: specialty formulators with integrated mechanical recycling capabilities. Signal to monitor: Korean battery OEM supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Chemistry | Celanese Corporation's acetyls chain secures p-dichlorobenzene supply against Chinese precursor volatility. |
| Long-term Supply Agreement | Bundled virgin resin and closed-loop recycling contracts align SK Chemicals with Korean battery OEM procurement consolidation. |
| Capacity Expansion | Zhejiang and Jiangsu polymerization investments serve domestic Chinese battery manufacturers and export automotive tier-1s. |
| Green Manufacturing Transition | Powder grade expansion substitutes solvent-based coatings under China's MEE VOC enforcement. |
| Joint Venture | German-Japanese LFT compound partnerships accelerate structural battery frame qualification for crash-load-bearing applications. |
Research Methodology
Operator-level perspectives from polymerization plant managers, automotive tier-1 procurement leads, battery OEM materials engineers, and specialty chemical distribution channel partners anchored the qualitative base. These primary insights combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and MIIT production statistics. Bottom-up resin consumption modeling and top-down thermoplastic substitution analysis were triangulated to cross-verify volume estimates.
Scenario bracketing around automotive electrification timelines and hydrogen infrastructure deployment shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry, form factor, and regional production hub. CAGRs derived from weighted average substitution rates for metal components and platform-specific content-per-vehicle assumptions. Forecast inputs incorporated EPA fuel economy mandate stringency and REACH substance evaluation progression.
Stress conditions across sodium sulfide price volatility, sulfur derivative availability, and automotive qualification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EV platform launch synchronization and regulatory enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Thermoplastic Polyimide Market