
 Thermoplastic Polyimide Market | 2026-2036
Thermoplastic Polyimide Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyimide Market Analytics
High-temperature specification grades above 300°C continuous service temperature is rotating procurement patterns across the Thermoplastic Polyimide Market. DuPont leverages its fluoropolymer heritage to sustain premium positioning in circuit board substrates. Ube Industries anchors Japanese supply through captive monomer production. Kaneka Corporation differentiates via optical-grade film specialization for flexible display manufacturing.
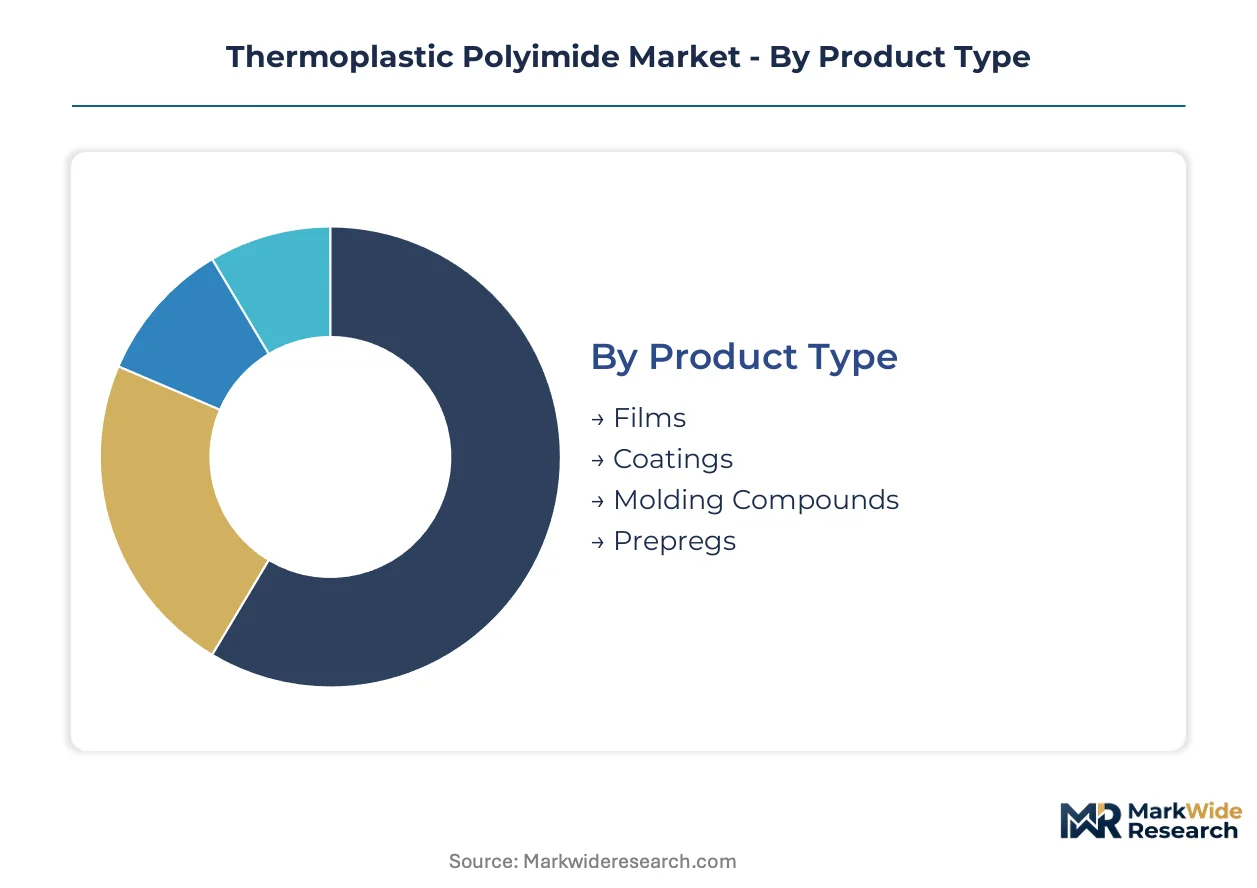
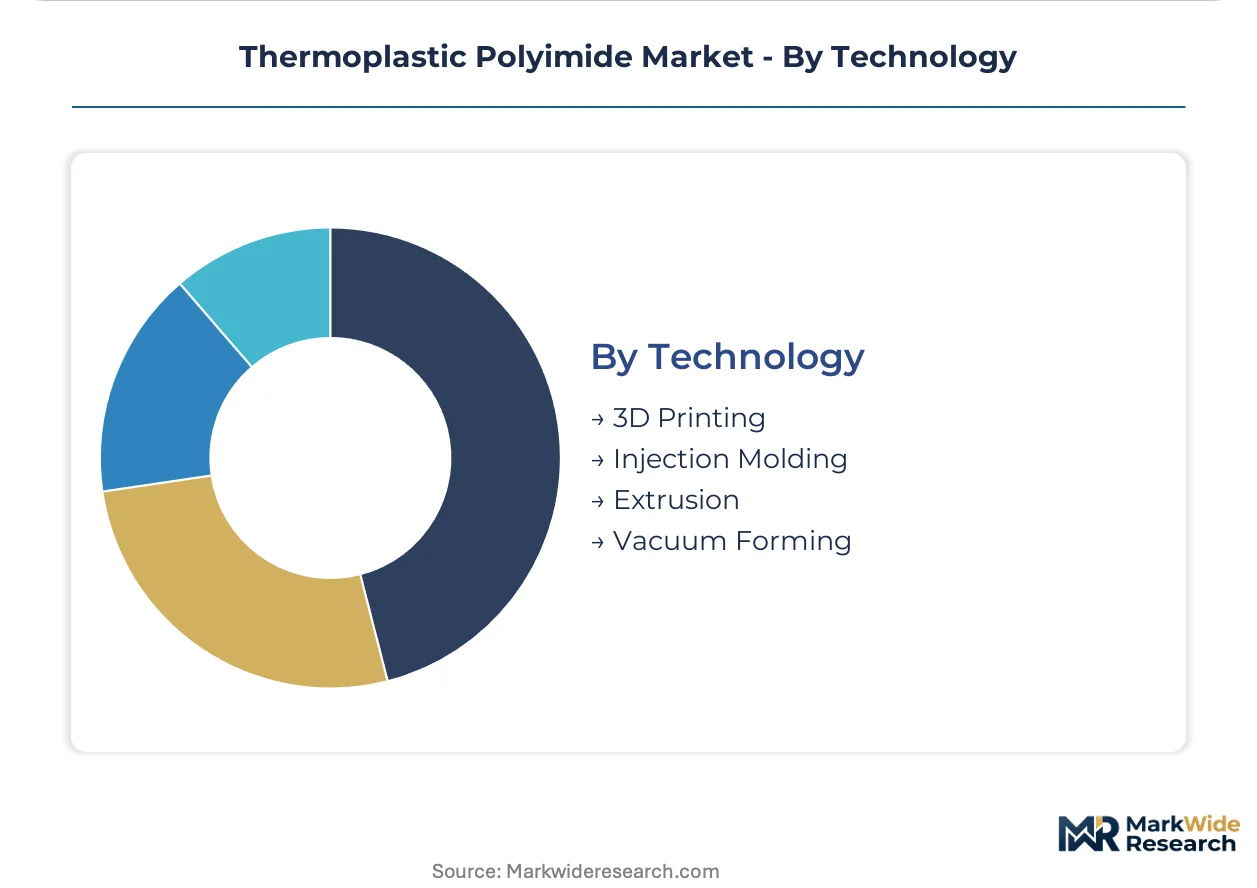
Thermoplastic polyimide denotes a melt-processable aromatic heterocyclic polymer retaining mechanical integrity above 250°C, synthesized typically from dianhydrides and aromatic diamines via two-step imidization. Its primary purpose centers on replacing thermoset polyimides and metals in weight-critical, thermally stressed assemblies. Films leads product type revenue owing to dielectric stability in 5G antenna substrates, while molding compounds represents the fastest-growing category as automotive electrification multiplies connector and housing demand. Injection molding dominates technology adoption for complex geometries, though 3D printing gains traction in aerospace prototyping workflows.
EPA regulations on perfluorinated compound emissions constrain fluorinated polyimide variants in US manufacturing, while REACH authorization requirements in Europe restrict certain dianhydride precursors. Japan's METI enforces JIS standards for electronic material flammability that directly shape product certification pathways. Stakeholders must monitor evolving semiconductor packaging standards and polymer recycling mandates as these frameworks increasingly determine market access eligibility and formulation R&D allocation.
Market Dynamics
The Thermoplastic Polyimide Market pivots on automotive electrification forcing material substitution decisions across connector and housing specifications. OEMs now mandate continuous service temperatures above 250°C for powertrain components, compressing qualification timelines and elevating formulation complexity requirements.
Growth Catalysts
- Automotive electrification:Battery pack interconnects and charging inlets require flame-retardant thermoplastics rated for 300°C continuous operation. Tier-1 suppliers in Germany and Japan are qualifying polyimide grades for 800V architectures.
- REACH authorization pathways:European ECHA restrictions on legacy dianhydride precursors are accelerating investment in bio-based monomer alternatives. Formulators achieving SVHC-compliant certification capture premium positioning in medical device supply chains.
- 5G antenna substrate demand:Dielectric stability requirements at millimeter-wave frequencies is rotating procurement toward fluorinated polyimide films. Chinese base station deployment schedules are compressing supplier qualification cycles.
Market Restraints
- Dianhydride feedstock concentration:Pyromellitic dianhydride supply concentrates among Japanese and Chinese chemical producers. Geopolitical friction disrupts spot pricing visibility for European compounders.
- Fluorinated precursor cost volatility:Perfluorinated monomer prices track fluoropolymer feedstock indices with 40-60% quarterly variance. EPA emission constraints on fluorinated compound manufacturing limit US domestic sourcing options.
- Thermoset polyimide substitution resistance:Aerospace structural applications retain thermoset grades for Tg exceeding 400°C. Melt-processable alternatives face qualification barriers in FAA-certified assemblies.
Strategic Opportunities
- Optical-grade film for flexible displays:Kaneka Corporation's specialization in transparent polyimide substrates for foldable OLED panels creates a template for capacity expansion. Korean and Chinese display manufacturers are qualifying second-source suppliers.
- India electronics manufacturing:PLI scheme incentives for semiconductor packaging and mobile device assembly are attracting compounder joint ventures. BIS certification requirements for electronic material flammability favor early entrants.
- Chemical recycling mandates:EU Green Deal circularity targets for high-performance polymers will require closed-loop imide recovery processes. Pyrolysis-based monomer regeneration represents unclaimed intellectual property territory.
Industry Challenges
- Imidization process engineering talent:Two-step polycondensation expertise resides among retiring specialists at legacy Japanese producers. University polymer programs in Europe and North America have narrowed aromatic heterocyclic synthesis training.
- Automotive qualification timelines:OEM material approval cycles for under-hood applications extend 36-48 months. Concurrent engineering pressures compress validation protocols without compromising JIS flame-retardancy certification.
- Patent thickets around fluorinated variants:DuPont's fluoropolymer heritage created dense intellectual property barriers. New entrants face freedom-to-operate analysis costs exceeding formulation development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyimide Market |
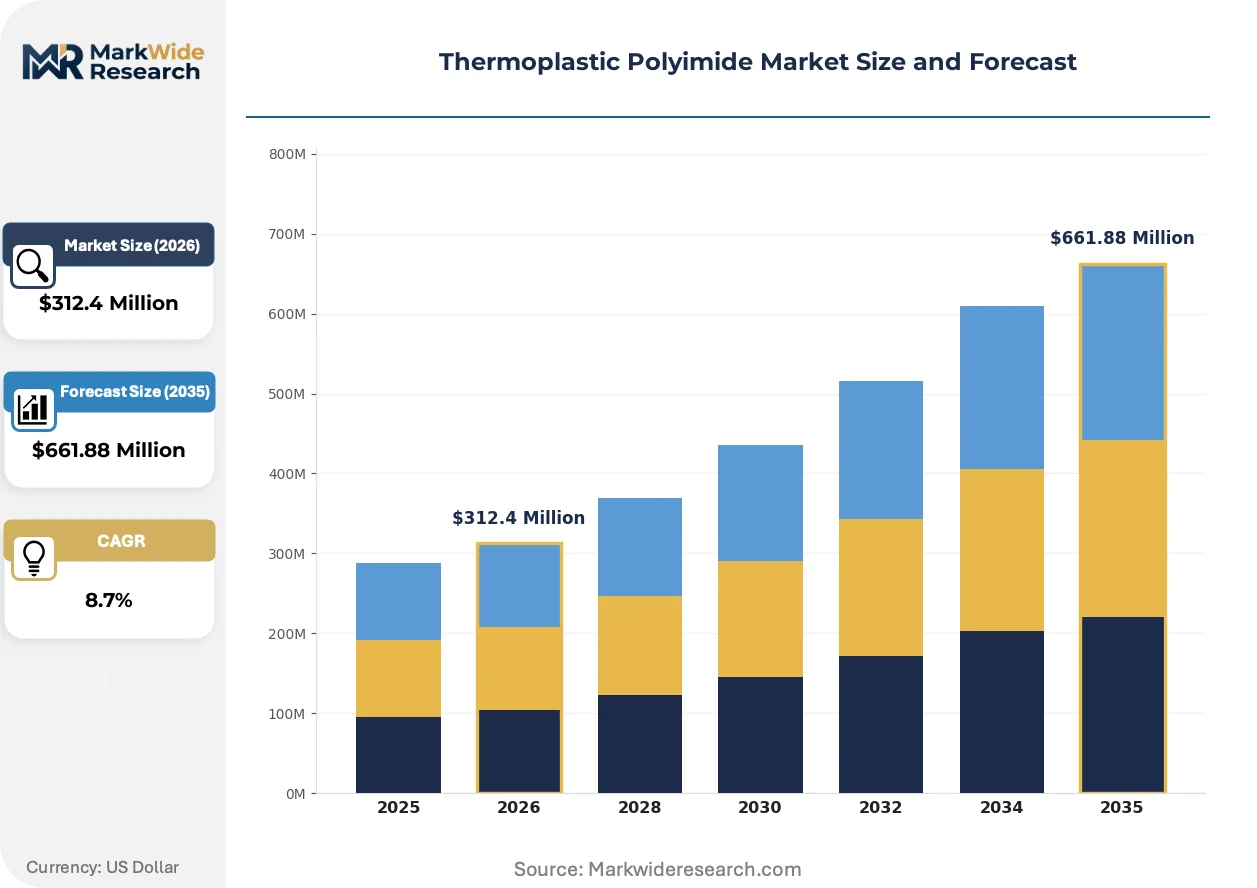
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Coatings, Molding Compounds, Prepregs End User: Aerospace, Electronics, Automotive, Industrial Application: Insulation, Circuit Boards, Connectors, Structural Components Technology: 3D Printing, Injection Molding, Extrusion, Vacuum Forming |
| Companies Covered | DuPont, Ube Industries, Kaneka Corporation, Mitsui Chemicals, PI Advanced Materials Co., Ltd., Taimide Tech. Inc., SKC Kolon PI, Mitsubishi Gas Chemical, Asahi Kasei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyimide Market Evolving Landscape
Material science advances and regulatory stringency are compressing traditional qualification paradigms. Three developments are restructuring competitive positioning across synthesis, processing, and end-use specification.
Additive manufacturing of polyimide feedstocks is displacing subtractive machining for aerospace prototyping workflows. Stratasys and specialized compounders have qualified fused filament fabrication grades rated for 280°C service. Boeing and Airbus engineering teams are compressing bracket and duct development cycles from months to weeks, forcing traditional injection molders to defend fixture economics against digital inventory models.
Japan's METI enforcement of revised JIS C 3005 flammability standards for electronic substrates is redirecting formulation priorities toward phosphorus-based synergists. Halogen-free certification requirements now gate access to automotive connector supply chains. Compounders without Tokyo-based testing partnerships face 6-12 month delays in obtaining PSE conformity marks for power distribution components.
Consolidated procurement by Chinese battery manufacturers is compressing supplier margins and elevating volume-commitment requirements. CATL and BYD now specify annual minimums exceeding 500 metric tons for qualified polyimide grades. European compounders without Shanghai or Shenzhen technical service presence are losing specification influence to regional competitors offering integrated molding support and just-in-time delivery from bonded warehouses.
Thermoplastic Polyimide Market Segmentation
Thermoplastic polyimide procurement rotates on specification-grade differentiation. Each segment category carries distinct regulatory certification pathways and performance thresholds that determine supplier qualification and pricing power.
Product Type:
REACH authorization requirements in Europe and JIS flammability standards in Japan create divergent formulation priorities across product formats. ECHA restrictions on legacy dianhydrides favor grades with bio-based monomer documentation, while METI-enforced electronic material standards elevate phosphorus-synergist formulations.
- Films:Dielectrically stable aromatic heterocyclic sheets retain mechanical integrity above 250°C. 5G antenna substrate demand in China compresses qualification cycles for fluorinated variants rated for millimeter-wave frequencies. REACH-compliant optical-grade films command premium positioning in medical device supply chains.
- Molding Compounds:Melt-processable granular formulations enable complex geometries in powertrain components. Automotive electrification in Germany and Japan drives qualification for 800V-rated grades with continuous service temperatures exceeding 300°C. EPA emission constraints on fluorinated precursors limit US domestic sourcing options.
- Coatings:Solvent-borne or powder systems provide thermal barrier protection for metal substrates.
- Prepregs:Reinforced resin-impregnated sheets serve aerospace structural prototyping workflows.
Films handles the majority of throughput; molding compounds is the fastest mover on share.
End User:
Customer concentration shapes margin structures and technical service requirements. Volume-commitment thresholds and just-in-time delivery capabilities separate qualified suppliers from specification influencers.
- Electronics:Circuit board and flexible display manufacturers specify dielectric stability at elevated frequencies. Chinese base station deployment and Korean OLED panel production concentrate demand for optical-grade substrates. BIS certification requirements in India favor early entrants with local technical service presence.
- Automotive:OEM material approval cycles for under-hood applications extend 36-48 months. Tier-1 suppliers in Germany and Japan qualify polyimide grades for battery pack interconnects and charging inlets. Concurrent engineering pressures compress validation protocols without compromising flame-retardancy certification.
- Aerospace:Prototyping workflows favor additive manufacturing grades rated for 280°C service.
- Industrial:Process equipment and chemical handling applications require corrosion-resistant formulations.
Electronics captures the dominant revenue position; automotive is expanding most quickly as electrification multiplies connector and housing demand.
Application:
Functional performance requirements determine processing technology selection and formulation complexity. Thermal management and electrical isolation specifications create distinct procurement patterns.
- Insulation:Wire and cable jacketing systems require continuous operation above 250°C without mechanical degradation. Power distribution component demand in China and Germany elevates volume requirements for halogen-free certified grades. JIS C 3005 flammancy compliance gates access to automotive connector supply chains.
- Circuit Boards:Substrate materials must maintain dimensional stability through multiple thermal cycles. 5G infrastructure deployment accelerates qualification of low-loss dielectric films. EU RoHS and REACH restrictions redirect formulation priorities toward SVHC-compliant alternatives.
- Connectors:Precision-molded housings for high-voltage architectures demand flame-retardant thermoplastics.
- Structural Components:Load-bearing brackets and ducts in aerospace applications balance weight reduction with thermal stress resistance.
Insulation processes the highest volume throughput; circuit boards is gaining share fastest on 5G substrate demand.
Technology:
Processing method selection reflects part complexity, production scale, and lead-time compression requirements. Digital manufacturing capabilities are restructuring traditional fixture economics.
- Injection Molding:High-pressure processing of complex geometries dominates automotive and electronics component manufacturing. Tooling investments and cycle time optimization separate high-volume compounders from specialty suppliers. Shanghai and Shenzhen technical service presence determines specification influence for Chinese battery manufacturers.
- 3D Printing:Fused filament fabrication grades rated for 280°C service displace subtractive machining in aerospace prototyping. Boeing and Airbus engineering teams compress bracket and duct development cycles from months to weeks. Stratasys and specialized compounders have qualified feedstocks for production workflows.
- Extrusion:Continuous profile production serves film and sheet applications with tight thickness tolerances.
- Vacuum Forming:Thermoforming of pre-extruded sheets enables large-format parts with moderate dimensional precision.
Injection molding handles the majority of throughput; 3D printing is climbing the fastest on aerospace prototyping adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyromellitic dianhydride supply concentrates among Japanese and Chinese chemical producers, creating pricing volatility for European compounders. Germany, Japan, and China host the dominant electronics and automotive production clusters driving specification-grade demand.
China
CATL and BYD battery manufacturers specify annual minimums exceeding 500 metric tons for qualified polyimide grades. MIIT enforces GB standards for electronic material flammability that shape product certification pathways. Shanghai and Shenzhen technical service presence determines specification influence for compounders serving integrated molding support and just-in-time delivery from bonded warehouses.
Japan
METI enforces revised JIS C 3005 flammability standards for electronic substrates that redirect formulation priorities toward phosphorus-based synergists. Halogen-free certification requirements gate access to automotive connector supply chains. Kanto and Kansai industrial corridors concentrate captive monomer production and optical-grade film specialization for flexible display manufacturing.
Germany
Tier-1 suppliers qualify polyimide grades for 800V battery pack interconnects and charging inlets. ECHA REACH authorization requirements restrict certain dianhydride precursors and accelerate investment in bio-based monomer alternatives. Bavaria and Baden-Württemberg automotive clusters compress OEM material approval cycles through concurrent engineering pressures without compromising flame-retardancy certification.
United States
EPA regulations on perfluorinated compound emissions constrain fluorinated polyimide variants in domestic manufacturing. Boeing and Airbus engineering teams compress bracket and duct development cycles through additive manufacturing adoption. California and Pacific Northwest aerospace prototyping workflows favor fused filament fabrication grades rated for 280°C service.
India
PLI scheme incentives for semiconductor packaging and mobile device assembly attract compounder joint ventures. BIS certification requirements for electronic material flammability favor early entrants with local technical service presence. Maharashtra and Karnataka electronics manufacturing corridors concentrate demand for dielectrically stable substrates in 5G infrastructure deployment.
Thermoplastic Polyimide Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized polymer compounders. The vendor base spans Japanese keiretsu-affiliated producers, Korean display-material specialists, and Western fluoropolymer heritage firms. Three archetypes dominate: captive monomer-integrated producers, optical-grade film specialists, and fluorinated variant patent holders. Capacity expansion in China and strategic partnerships for Indian market entry represent the dominant competitive moves.
Within the keiretsu-affiliated tier, Ube Industries and Mitsubishi Gas Chemical exemplify backward-integrated producers controlling dianhydride supply chains. DuPont occupies a position reflecting fluoropolymer heritage in circuit board substrate specifications. Kaneka Corporation sits within the optical-grade specialization archetype, representing transparent substrate capabilities for foldable display manufacturing. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning across specification-grade procurement.
| Leading Market Players |
|---|
| DuPont |
| Ube Industries |
| Kaneka Corporation |
| Mitsui Chemicals |
| PI Advanced Materials Co., Ltd. |
| Taimide Tech. Inc. |
| SKC Kolon PI |
| Mitsubishi Gas Chemical |
| Asahi Kasei |
| Others |
Value Network & Pricing Analysis
Thirty-six-to-forty-eight-month OEM qualification timelines compress inventory flexibility for compounders, concentrating pricing power among Japanese and Chinese producers with captive dianhydride supply. This lead-time rigidity forces European compounders to absorb feedstock volatility or sacrifice specification influence.
Pricing Analysis
REACH authorization dictates the pricing tier structure across European procurement, separating SVHC-compliant bio-based grades from legacy formulations facing regulatory sunset. Three-tier pricing structure across premium optical-grade, standard electronic-grade, and economy industrial-grade levels reflects certification burden and monomer origin documentation. Cost compression in standard-grade compounds intensifies because Chinese battery manufacturers consolidated procurement around 500-metric-ton annual minimums. Automotive OEMs exhibit lowest price sensitivity due to 36-48 month qualification lock-in, while industrial processors face highest sensitivity to fluorinated precursor volatility.
Supply Chain Analysis
Japan and China anchor pyromellitic dianhydride production, with Ube Industries and Chinese state-affiliated chemical groups controlling upstream monomer supply. European compounders draw from spot markets or long-term offtake agreements with Japanese keiretsu partners. Single-source vulnerability concentrates around fluorinated precursor availability, where EPA emission constraints limit US domestic manufacturing options. Distribution runs through technical service hubs in Shanghai, Shenzhen, and Stuttgart, with bonded warehouses enabling just-in-time delivery to automotive and electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic polyimide sits in early-cycle expansion as automotive electrification forces material substitution decisions across 800V architectures. Battery pack interconnect demand represents the primary penetration vector for melt-processable alternatives to thermosets and metals.
For Market Incumbents: Consolidate specification influence by deepening captive monomer production in Kanto and Kansai corridors, and secure halogen-free JIS C 3005 certification ahead of METI enforcement deadlines. Emerging Chinese compounders with integrated molding support threaten premium positioning in Asian battery supply chains. Backward integration into bio-based dianhydride alternatives defends margin structure against REACH authorization cost pass-through. For New Entrants and Emerging Players: BIS certification fast-track for electronic material flammability opens procurement access to Maharashtra and Karnataka electronics manufacturing corridors under India's PLI scheme. Optical-grade film for flexible displays presents the most penetrable white-space, with Korean and Chinese display manufacturers actively qualifying second-source suppliers. Partner with regional compounders for technical service presence rather than greenfield capacity investment. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because qualification barriers and patent thickets around fluorinated variants protect incumbent returns while regulatory stringency accelerates formulation R&D spend. Target mid-cap compounders with automotive OEM approval status and incomplete geographic coverage. Watch for inflection when Chinese battery manufacturers relax 500-metric-ton minimums or when EU chemical recycling mandates mature to commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dianhydride Production | Captive monomer supply insulates margin structure from Japanese-Chinese feedstock concentration. |
| Halogen-Free JIS C 3005 Certification Investment | Phosphorus-synergist formulations gate automotive connector supply chain access under METI enforcement. |
| Technical Service Hub Expansion in Shanghai and Shenzhen | Integrated molding support determines specification influence for CATL and BYD procurement decisions. |
| Optical-Grade Film Capacity Addition | Transparent substrate specialization captures foldable OLED panel demand from Korean and Chinese display manufacturers. |
| Joint Venture for Indian Market Entry | PLI scheme incentives and BIS certification requirements favor early entrants with local production presence. |
Research Methodology
A standing panel of polymer plant managers, Tier 1 automotive procurement leads, electronics OEM material engineers, and distribution channel partners provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, Japanese METI chemical industry reports, SEC 10-K filings of diversified chemical conglomerates, and ECHA authorization documentation. Bottom-up segment modeling triangulated against top-down macroeconomic drivers across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including regional automotive production databases, 5G base station deployment schedules, and flexible display manufacturing capacity announcements. The analytical framework modeled grade tier, end-use industry, regional production hub, and certification status segmentation throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating fluorinated precursor cost indices and regulatory compliance cost trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained automotive electrification investment and stable REACH authorization timelines; material deviation in battery chemistry shifts or regulatory acceleration would warrant model refresh. Recalibration cycles align with material shifts in OEM qualification protocols, Chinese battery manufacturer procurement consolidation, and EU circular economy mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Bismaleimide Monomer Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market