
 Global Polymer Dispersion Market | 2026-2036
Global Polymer Dispersion Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymer Dispersion Market Outlook
ISO 14001 environmental management certification is bifurcating the competitive landscape into qualified suppliers and excluded challengers. BASF SE leverages its integrated petrochemical network to sustain feedstock cost advantages across European production sites. Dow anchors North American supply through Gulf Coast manufacturing scale and deepwater logistics access. Arkema differentiates via specialty acrylic dispersions for high-performance coatings.
Polymer dispersion refers to a stable colloidal system of polymer particles suspended in a continuous liquid phase, typically water, with particle sizes ranging from 0.01 to 10 micrometers and solids content between 40% and 60% by weight, manufactured through emulsion polymerization or mechanical dispersion processes to deliver film-forming, binding, or protective functions. Aqueous dispersions dominate volume due to regulatory pressure on solvent emissions, while pigment dispersions command margin premiums in inkjet printing and automotive coating formulations where color consistency specifications are tightest. Emulsification technology leads capital deployment as manufacturers seek finer particle size distribution control for nanocoating applications.
EPA VOC regulations in the United States, REACH in Europe, and China's MEE emission standards collectively restrict solvent-based formulation sales and redirect R&D spending toward compliant aqueous alternatives. The EU Green Deal carbon border adjustments will further penalize high-emission dispersion imports into European coating supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and misaligned product registration investments.
Market Dynamics
REACH compliance and China's MEE emission standards are redirecting formulation investments toward aqueous polymer systems, compressing solvent-based capacity while concentrating procurement among certified suppliers.
Growth Catalysts
- Waterborne automotive refinishing:Germany's KBA type-approval requirements for low-VOC coatings are accelerating aqueous dispersion adoption across vehicle repair networks.
- Textile treatment demand:India's BIS certification mandates for formaldehyde-free fabric finishes are pulling acrylic dispersions into apparel manufacturing clusters around Surat and Tiruppur.
- Emulsion polymerization advances:Finer particle size distribution control below 100 nanometers is enabling nanocoating applications in electronics protection.
Market Restraints
- Feedstock volatility:Acrylic monomer prices tied to propylene derivatives expose formulators to petrochemical cycle swings.
- European supply concentration:BASF SE and Arkema control integrated production corridors along the Rhine, creating single-source risk for specialty grades.
- Freeze-thaw stability limits:Aqueous systems require formulated additives for cold-chain logistics, adding cost versus solvent alternatives.
Strategic Opportunities
- Vietnam industrialization:Footwear and furniture manufacturing expansion around Ho Chi Minh City is creating unmet demand for water-based adhesives and coatings.
- EU Green Deal carbon border adjustments:Import penalties on high-emission dispersions will privilege local aqueous production and certified low-carbon formulations.
- Digital inkjet convergence:Pigment dispersion quality requirements for high-speed textile printing are opening margin premiums in fashion supply chains.
Industry Challenges
- ISO 14001 certification timelines:Environmental management system audits create 12-18 month qualification delays for new suppliers entering European coating supply chains.
- Legacy solvent infrastructure:Capital equipment replacement costs for aqueous-compatible spray systems slow conversion rates among small automotive refinishers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymer Dispersion Market |
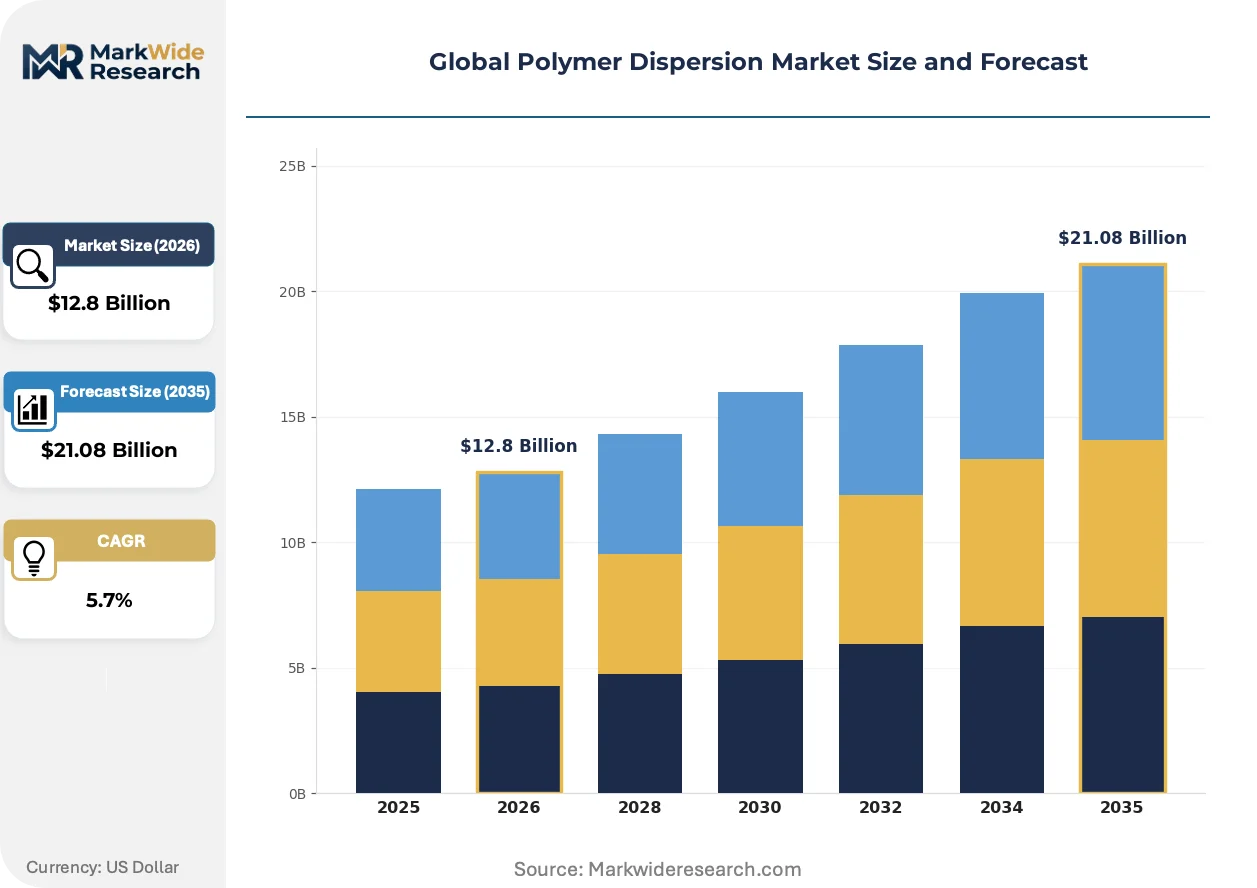
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Dispersions, Solvent-based Dispersions, Pigment Dispersions, Additive Dispersions End Use Industry: Coatings, Adhesives, Inks, Textiles Application: Surface Coating, Inkjet Printing, Textile Treatment, Paper Coating Technology: High-shear Mixing, Ultrasonication, Milling, Emulsification |
| Companies Covered | Wacker Chemie AG, DIC Corporation, BASF SE, Evonik Industries AG, Covestro AG, Dow, Synthomer, Celanese Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymer Dispersion Market Strategic Shifts
Formulation chemistry and regulatory enforcement are actively reshaping competitive positioning, with particle engineering and compliance architecture becoming primary differentiators.
Hybrid acrylic-urethane dispersion technology is bifurcating the high-performance coatings segment. Automotive OEMs in Germany and Japan are specifying these systems for exterior plastic components requiring both flexibility and weathering resistance. The technology is bifurcating supplier tiers into integrated resin producers capable of molecular architecture control versus commodity dispersion blenders.
REACH authorization requirements for N-methyl-2-pyrrolidone are forcing reformulation of polyurethane dispersions across European industrial coating applications. Manufacturers are accelerating substitution with dipolar aprotic solvent alternatives. Germany's coating sector is responding fastest, with several large automotive suppliers completing transitions ahead of 2025 sunset dates.
Direct mill-base supply contracts are displacing distributor intermediaries in large-volume packaging ink applications. Brand owners in beverage and personal care sectors are consolidating procurement through approved supplier lists with embedded technical service requirements. This pattern is most visible in North American folding carton converters serving multinational CPG accounts.
Global Polymer Dispersion Market Segmentation
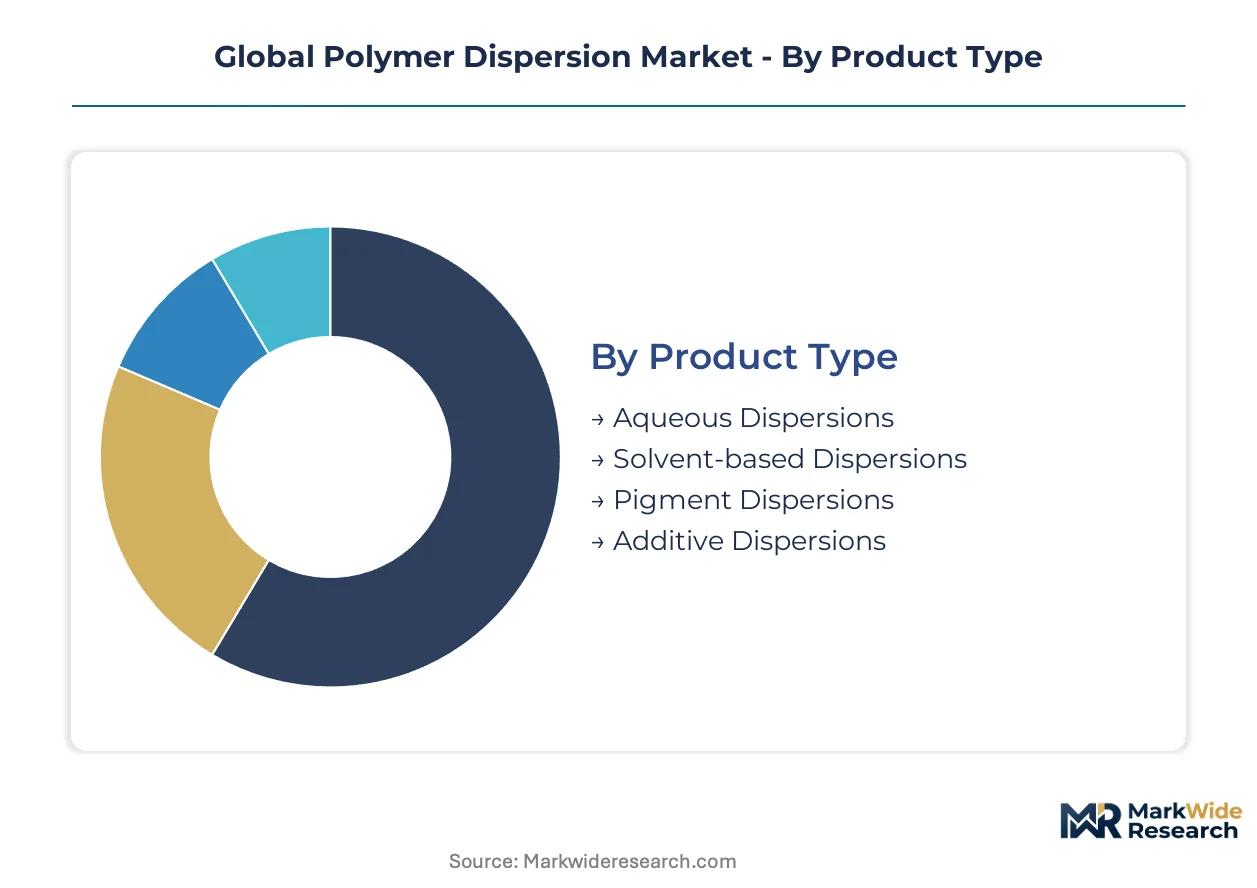
Regulatory pressure on VOC emissions and carbon intensity is fragmenting demand across formulation types, with compliance architecture determining which segments capture procurement budgets in automotive, textile, and packaging supply chains.
Product Type:
REACH authorization timelines and China's MEE enforcement are bifurcating the supplier base into certified aqueous producers and stranded solvent capacity.
- Aqueous Dispersions:Water-based colloidal systems with 40-60% solids content dominate automotive refinishing in Germany and paper coating across China's Yangtze River Delta, driven by KBA type-approval requirements and dual carbon goals tightening emission ceilings. EPA VOC regulations in the United States accelerate conversion from solvent systems in industrial maintenance coatings.
- Solvent-based Dispersions:Hydrocarbon-carried formulations retain niche demand in aerospace primers and specialty metal coatings where film formation kinetics cannot tolerate waterborne drying constraints; procurement concentrates in defense supply chains exempt from commercial emission standards.
- Pigment Dispersions:Colorant concentrates for inkjet textile printing command margin premiums in fashion supply chains around Milan and São Paulo.
- Additive Dispersions:Functional modifiers for rheology control and UV stabilization serve packaging ink formulators in North American folding carton converters.
Aqueous dispersions handle the majority of throughput; pigment dispersions are climbing the fastest on share as digital textile printing scales.
End Use Industry:
Customer procurement patterns stratify by certification burden, with ISO 14001-qualified suppliers capturing coating and adhesive contracts while textile finishers prioritize BIS-compliant formaldehyde-free systems.
- Coatings:Architectural and industrial film-forming applications represent the largest volume sink, with automotive OEMs in Japan and Germany specifying hybrid acrylic-urethane systems for exterior plastic components requiring weathering resistance and flexibility.
- Adhesives:Waterborne pressure-sensitive and structural bonding formulations serve footwear manufacturing clusters around Ho Chi Minh City and furniture assembly operations across Poland and Vietnam.
- Inks:Flexographic and gravure printing for flexible packaging drives demand in India's pharmaceutical blister pack sector and Brazil's processed food labeling industry.
- Textiles:Fabric finishing, printing, and coating applications concentrate in India's Surat and Tiruppur apparel clusters where BIS certification mandates pull acrylic dispersions into formaldehyde-free finish formulations.
Coatings commands the dominant procurement volume; textiles is expanding most quickly as South and Southeast Asian manufacturing scales.
Application:
Performance specifications and regulatory jurisdiction determine which application segments absorb capital deployment in particle engineering and emulsification technology.
- Surface Coating:Protective and decorative films for metal, wood, and plastic substrates serve automotive refinishing networks in Germany under KBA low-VOC mandates and industrial maintenance operations across the United States subject to EPA emission limits.
- Inkjet Printing:High-speed digital textile and graphic arts printing demands sub-100 nanometer pigment dispersion quality; fashion supply chains in Italy and Turkey specify these systems for short-run customization.
- Textile Treatment:Softening agents, water repellents, and flame retardants for apparel and technical fabrics concentrate procurement in China's Zhejiang province and Bangladesh's Dhaka industrial corridor.
- Paper Coating:Barrier and printability enhancement for packaging board serves beverage carton converters in Sweden and personal care packaging producers in France.
Surface coating absorbs the largest formulation volume; inkjet printing shows the steepest expansion trajectory as digital convergence displaces analog textile decoration.
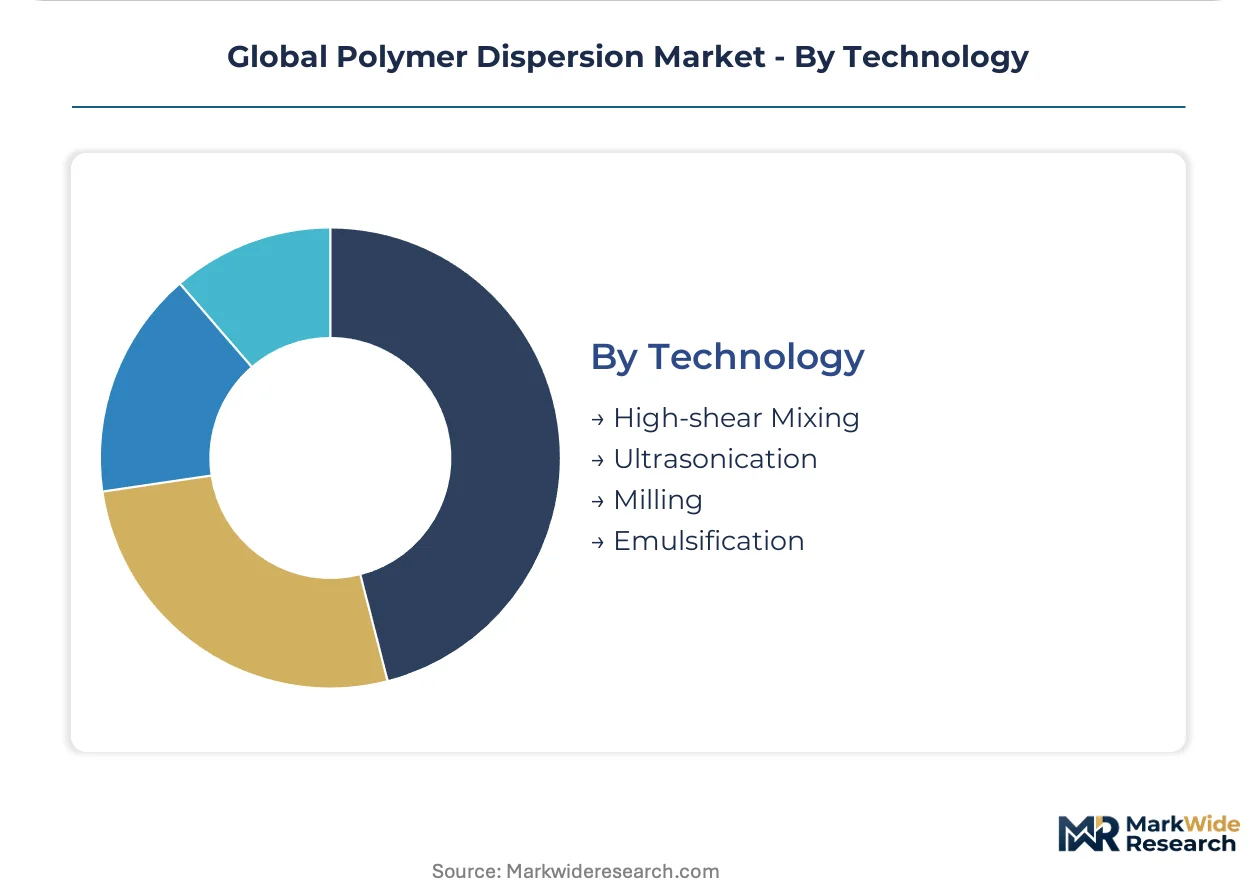
Technology:
Capital allocation to particle size distribution control separates integrated resin producers from commodity blenders, with nanocoating applications demanding sub-100 nanometer precision.
- Emulsification:Controlled shear polymerization of monomers into stable colloidal dispersions enables the finest particle size distributions; German and Japanese automotive suppliers specify these systems for nanocoating electronics protection.
- High-shear Mixing:Rotor-stator systems for pre-emulsion preparation and post-addition compounding serve mid-volume coating formulators in Spain and Mexico balancing capital efficiency with quality requirements.
- Ultrasonication:Acoustic cavitation for nanoparticle dispersion and cell disruption addresses specialty applications in pharmaceutical microencapsulation and cosmetic active delivery.
- Milling:Bead and ball mills for pigment deagglomeration in ink and coating applications retain installed base in legacy production corridors along the Rhine and Great Lakes regions.
Emulsification commands the dominant technology investment; ultrasonication is gaining share fastest in high-value pharmaceutical and electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and textile finishers drive procurement concentration across manufacturing corridors, with regulatory compliance determining supplier qualification in each jurisdiction.
United States
Waterborne coating adoption accelerates among automotive refinishers and industrial maintenance operators. EPA VOC regulations restrict solvent-based formulation sales in architectural and protective coatings. Gulf Coast petrochemical corridors supply acrylic monomer feedstock to dispersion manufacturers clustered around Houston.
Germany
Automotive OEMs specify hybrid acrylic-urethane systems for exterior plastic components requiring weathering resistance. KBA type-approval requirements mandate low-VOC coatings across vehicle repair networks. Rhine River industrial corridors concentrate integrated production by BASF SE and specialty producers serving coating formulators.
China
Paper coating and textile treatment applications absorb aqueous dispersion volume in manufacturing hubs. MEE emission standards and dual carbon goals tighten VOC ceilings and redirect investment toward waterborne systems. Yangtze River Delta industrial clusters scale procurement for packaging board and apparel finishing.
India
Textile finishers pull acrylic dispersions into formaldehyde-free fabric treatments for export apparel. BIS certification mandates eliminate non-compliant suppliers from government procurement lists. Surat and Tiruppur manufacturing clusters concentrate demand for softening agents and water repellents.
Vietnam
Footwear and furniture manufacturing expansion generates unmet demand for water-based adhesives and coatings. Industrial zone incentives attract dispersion suppliers to serve export-oriented assembly operations. Ho Chi Minh City manufacturing corridors anchor procurement for pressure-sensitive bonding formulations.
Global Polymer Dispersion Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive monomer supply and specialty resin producers with molecular architecture capabilities. Market structure concentrates around Rhine River and Gulf Coast production corridors where feedstock integration sustains cost positions. Two strategic archetypes dominate: integrated resin producers controlling emulsion polymerization technology and specialty dispersion blenders serving niche performance specifications. Competitive moves center on backward integration into acrylic monomer production and geographic expansion into Southeast Asian manufacturing zones.
Among German-based integrated producers, BASF SE and Covestro AG exemplify the petrochemical conglomerate archetype with captive feedstock positions. Dow anchors North American supply scale through Gulf Coast manufacturing and deepwater logistics access. Arkema occupies a specialty position focused on acrylic dispersion technology for high-performance coating applications.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| DIC Corporation |
| BASF SE |
| Evonik Industries AG |
| Covestro AG |
| Dow |
| Synthomer |
| Celanese Corporation |
| Arkema |
| Others |
Value Chain & Pricing Dynamics
Acrylic monomer substitution for solvent-based alkyd resins is redrawing procurement geography toward Gulf Coast and Rhine River petrochemical corridors while compressing margin structures for non-integrated formulators. This feedstock pivot simultaneously concentrates volume pricing power among captive producers and exposes merchant buyers to propylene derivative volatility.
Pricing Analysis
Cost-plus contracts indexed to propylene futures dominate acrylic dispersion procurement, with quarterly adjustments passing through monomer swings to automotive OEMs and coating formulators. Price differentiation rests on ISO 14001 certification tier and volume scale, with certified suppliers commanding premiums in European coating supply chains. Pricing pressure stems from merchant buyers lacking backward integration into monomer production. Small automotive refinishers exhibit highest price sensitivity due to legacy equipment replacement burdens, while multinational packaging converters show lowest sensitivity given embedded technical service requirements.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German automotive OEMs and Japanese electronics coaters, while Indian textile finishers maintain strategic stockpiles to buffer monomer price volatility. Supply concentrates in Germany, the United States, and China, with integrated production corridors along the Rhine and Gulf Coast anchoring global capacity. Raw material dependencies center on propylene derivatives, acrylic acid, and specialty surfactants. Single-source vulnerability from BASF SE and Arkema's Rhine River control of specialty grades creates qualification bottlenecks. Distribution runs through approved supplier lists with embedded technical service for large-volume packaging ink accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation support subscriptions are expanding faster than base dispersion volumes, creating recurring-revenue layers that deepen incumbent moats beyond commodity supply relationships.
For Market Incumbents: Shield margin positions by accelerating backward integration into acrylic monomer production and securing ISO 14001 certification ahead of European coating supply chain qualification windows. The threat of merchant feedstock cost volatility demands captive supply control, while certification investment locks out challengers facing 12-18 month audit timelines. For New Entrants and Emerging Players: ISO 14001 fast-track programs through accredited German auditors offer the cleanest entry path into European automotive coating supply chains. White-space targets concentrate in Vietnam's footwear adhesive sector and India's BIS-compliant textile finishing segment, where local formulation support remains underdeveloped. A technical service-led go-to-market approach displaces pure price competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resin producers with captive monomer positions and established certification architecture. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale alone. The acquisition target archetype combines emulsion polymerization technology with Southeast Asian manufacturing footprint. Watch REACH authorization timelines for N-methyl-2-pyrrolidone substitutes as inflection signals for polyurethane dispersion restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer | Captive propylene derivative supply shields margins from petrochemical cycle swings in European production corridors. |
| ISO 14001 Certification Acceleration | Environmental management qualification locks in automotive OEM procurement ahead of 12-18 month competitor exclusion windows. |
| Southeast Asian Manufacturing Expansion | Ho Chi Minh City and Vietnam industrial zones capture footwear and furniture adhesive demand from export-oriented assembly operations. |
| Hybrid Acrylic-Urethane R&D Investment | Molecular architecture control separates integrated producers from commodity blenders in high-performance coating specifications. |
| Direct Mill-Base Supply Contracts | Technical service embedding with North American folding carton converters displaces distributor intermediaries in packaging ink. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with coating formulators, automotive procurement leads, textile technical directors, and distribution channel partners; and secondary validation through customs trade data, SEC 10-K filings, REACH authorization databases, and ACC industry reports. Bottom-up volume triangulation across end-use segments was cross-checked against top-down petrochemical feedstock consumption patterns.
Across the projection horizon, the analytical framework modeled demand by product type, end-use industry, application, and technology, with regional production hub differentiation. CAGRs were derived from segment-level volume build-ups reconciled to macroeconomic drivers. Forecast inputs incorporated KBA type-approval timelines, MEE enforcement intensity, and BIS certification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of VOC limits or accelerated dual carbon goal implementation would require recalibration. Forecasts reflect documented assumptions regarding feedstock cost pass-through mechanisms and qualification timeline stability. Revision becomes warranted when propylene derivative volatility crosses thresholds that disrupt cost-plus contract indexation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycide Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Expanded Polypropylene Market