
 PET Foam Core Market | 2026-2036
PET Foam Core Market Size, Share, and Industry Trends Forecast 2026-2036
PET Foam Core Market Outlook
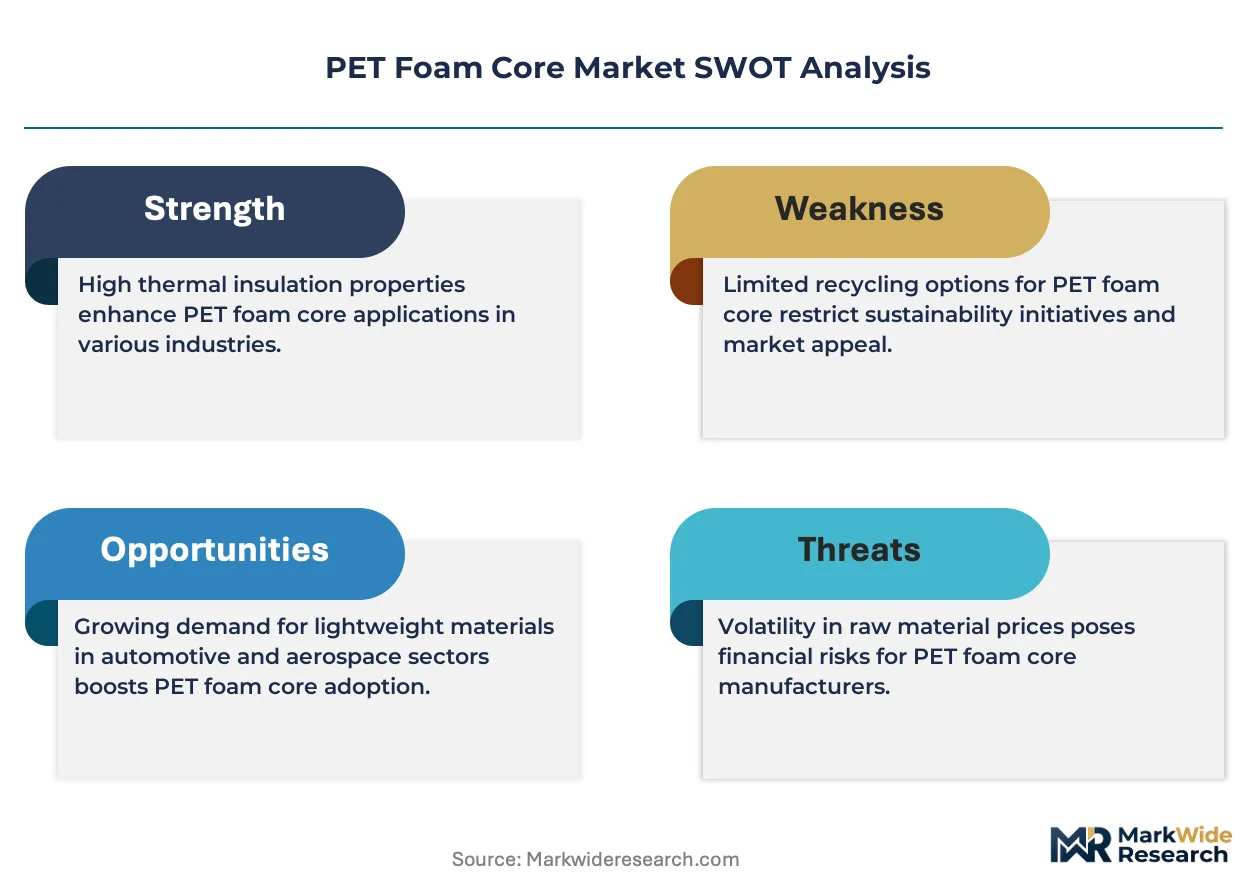
Project finance tied to renewable energy infrastructure is tilting competitive access toward suppliers with balance-sheet capacity to underwrite long-dated offtake contracts. Armacell leverages its integrated PET resin and foam extrusion network to capture margin across the value chain. Gurit Holding AG anchors its position through specialized formulations for vacuum-infused wind blades. DIAB Group competes via geographic proximity to Baltic and North Sea turbine installation hubs.
PET foam core is a closed-cell thermoplastic structural material produced through extrusion or expansion of recycled polyethylene terephthalate, typically achieving densities between 80 and 200 kg/m³ with shear strengths suited to sandwich panel construction. Its primary industrial purpose is to provide rigid, lightweight core layers in fiber-reinforced composite laminates for load-bearing applications. Extruded grades dominate volume in wind energy applications where dimensional stability under resin infusion matters most. Fire-retardant performance grades command premium positioning as building codes tighten across European construction markets. Laminated variants serve a mature niche in transport interiors where existing supply relationships limit new entrant access.
The EU Green Deal and REACH chemical registration requirements shape material formulation decisions, with ECHA evaluations driving substitution timelines for legacy flame retardants in foam core products. Germany's KBA and France's ANSM coordinate with EASA on composite material certification standards for rail and aerospace applications, creating multi-jurisdictional compliance burdens. Stakeholders must monitor how recycled-content mandates evolve under the EU AI Act's supply-chain traceability provisions and whether U.S. IRA domestic content rules redirect investment toward North American foam core fabrication.
Market Dynamics
Wind turbine blade fabricators are consolidating PET foam core procurement around suppliers capable of certifying recycled-content traceability under EU Green Deal carbon-border adjustment mechanisms. This structural force is compressing supplier margins while rewarding integrated resin-to-foam producers with captive recycling streams.
Growth Catalysts
- EU Green Deal carbon-border adjustments:The regulation is compelling blade manufacturers to document embodied carbon in core materials, favoring PET foam with verified post-consumer recycled feedstock over balsa wood and PVC alternatives.
- Offshore wind installation scale-up:North Sea projects are specifying longer blades requiring higher shear-strength core materials, driving specification upgrades toward high-density extruded PET grades.
- REACH flame-retardant substitution timelines:ECHA evaluations of legacy halogenated retardants are accelerating reformulation demand, creating pull for inherently fire-resistant thermoplastic cores in rail and building applications.
Market Restraints
- Recycled PET flake price volatility:Collection infrastructure gaps and competing bottle-to-fiber demand are creating input cost instability for foam extruders without backward-integrated recycling operations.
- Supplier geographic concentration:European extrusion capacity clusters in Germany and Belgium, exposing buyers to single-source risk for certified aerospace and rail grades.
- Resin infusion temperature limitations:PET foam's upper service temperature threshold constrains its displacement of PMI and SAN cores in epoxy systems curing above 120°C.
Strategic Opportunities
- US Inflation Reduction Act domestic content rules:The IRA's tax credit localization requirements are incentivizing North American foam core fabrication investment to serve Great Lakes and Atlantic offshore wind pipelines.
- Building-integrated photovoltaics sandwich panels:Fire-rated PET cores are penetrating BIPV substrate applications as architects specify lightweight, non-combustible insulation layers meeting EN 13501-1 standards.
- Digital twin-enabled resin infusion simulation:Convergence of computational fluid dynamics with core material databases is reducing prototype waste and accelerating qualification cycles for custom density gradients.
Industry Challenges
- Vacuum infusion technician scarcity:Blade fabricators face recruitment gaps for skilled laminators capable of diagnosing core-to-skin bonding defects in large-scale PET sandwich structures.
- Multi-jurisdictional certification timelines:Simultaneous EASA, KBA, and FAA qualification requirements for rail and aerospace grades are extending product launch cycles by 18-24 months.
- Legacy balsa supply contract lock-in:Existing long-term offtake agreements with Ecuadorian balsa plantations are delaying PET foam substitution in some wind OEM blade programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Foam Core Market |
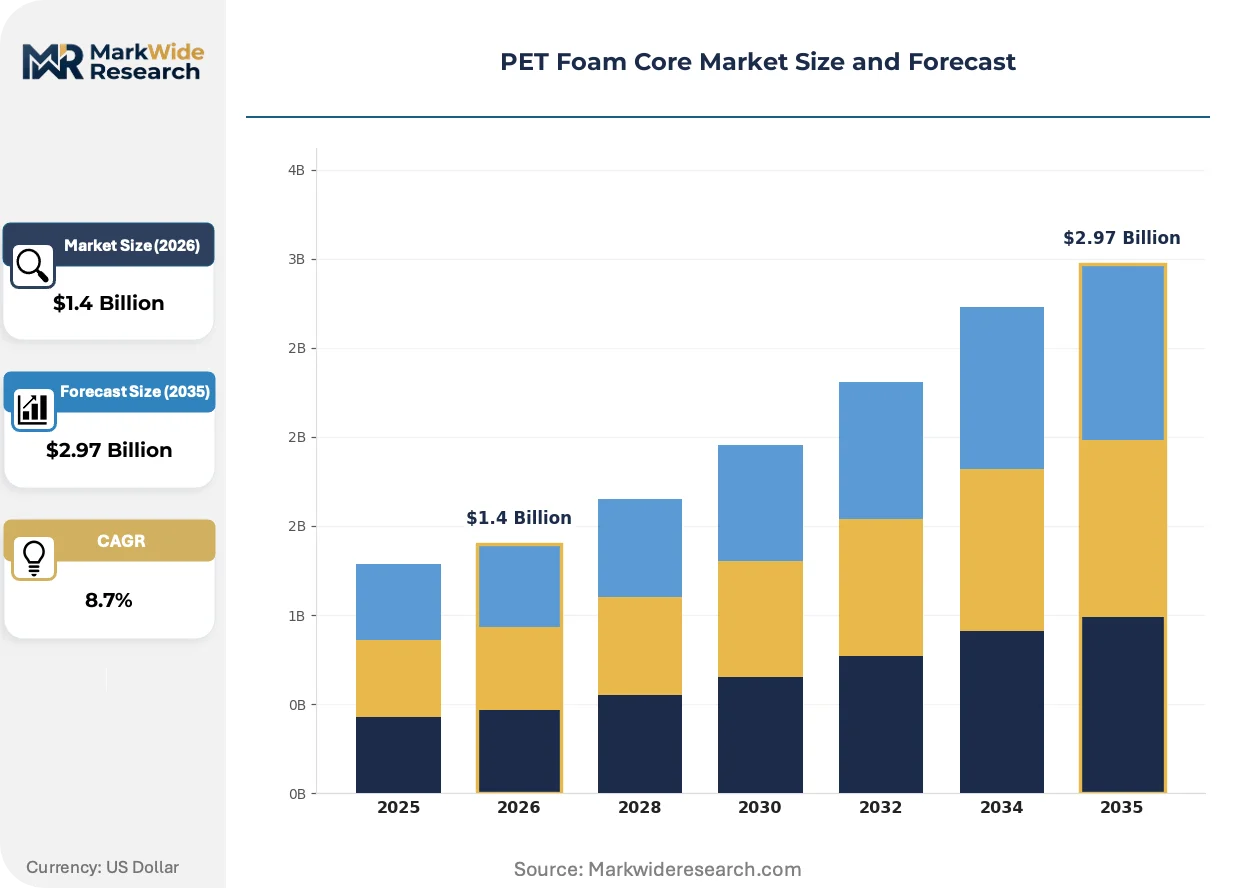
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded, Expanded, Laminated, Coated Application: Packaging, Construction, Automotive, Signage End User: Manufacturers, Retailers, Contractors, Designers Performance Grade: Standard, High-Strength, Fire-Retardant, Lightweight |
| Companies Covered | Armacell, 3A Composites GmbH, DIAB Group, Gurit Holding AG, CoreLite, Carbon-Core Corp, Sicomin Epoxy Systems, SAERTEX GmbH & Co. KG, Changzhou Tiansheng New Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Foam Core Market Strategic Shifts
Material informatics and automated manufacturing are compressing the traditional trial-and-error cycle for core-laminate compatibility testing. Three developments are restructuring how PET foam core is specified, qualified, and deployed across load-bearing composite applications.
Continuous compression molding of variable-density PET profiles is virtualizing the conventional cut-and-scarf core kitting process for wind blades. Vestas and Siemens Gamesa are piloting digitally controlled density gradients that eliminate adhesive bonding lines between core blocks. The technology is virtualizing labor-intensive assembly steps while reducing resin-rich areas that initiate fatigue cracks.
REACH authorization requirements for halogenated flame retardants are forcing reformulation of legacy PET foam grades used in rail interiors. ECHA's 2023 sunset date for decaBDE is compelling suppliers to validate phosphorus-nitrogen synergist systems. German KBA and French ANSM are coordinating transitional certification periods, with ICE 2 and TGV interior refurbishment programs representing the highest-volume near-term demand.
Blade OEMs are consolidating core procurement through direct mill relationships rather than distributor intermediaries. Siemens Gamesa and LM Wind Power have established dedicated supplier development programs with extruders capable of lot-level traceability. This channel compression is most advanced in Denmark and northern Germany, where fabrication clusters can justify dedicated logistics lanes from core production to blade mold staging areas.
PET Foam Core Market Segmentation
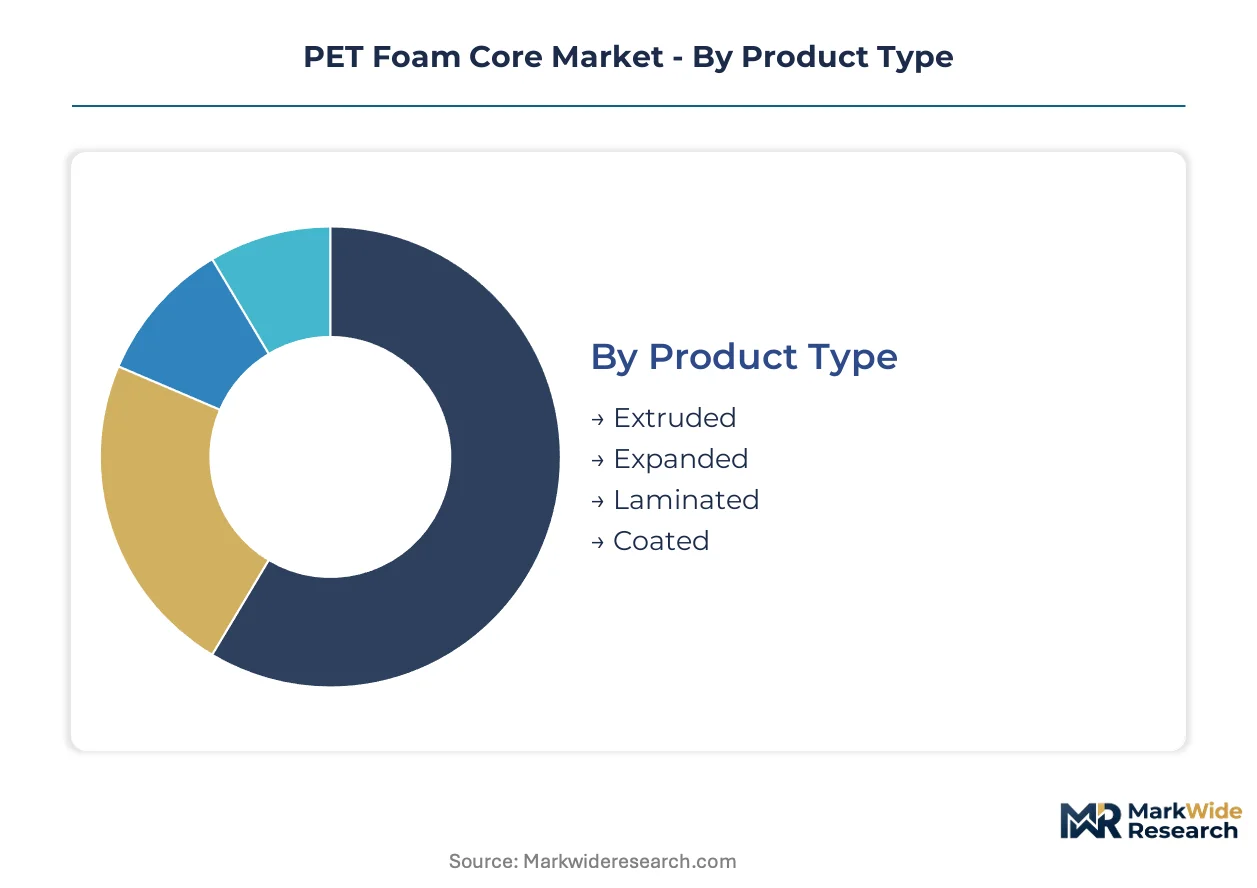
PET foam core specifications diverge sharply across load-bearing versus non-structural applications, with cycle times ranging from multi-year wind blade qualification programs to quarterly packaging material refresh orders. Understanding these velocity differences shapes inventory positioning and R&D resource allocation for extruders serving divergent end-use requirements.
Product Type:
Extruded grades turn over slowest due to wind blade certification timelines, while coated variants refresh fastest as transport interior specifications evolve quarterly.
- Extruded:Continuous profiles achieve densities between 80 and 200 kg/m³ through controlled expansion of recycled PET resin. Siemens Gamesa and Vestas concentrate procurement in Denmark and northern Germany for North Sea offshore blade cores requiring dimensional stability under vacuum infusion. EU Green Deal carbon-border documentation requirements extend qualification cycles to 18-24 months.
- Expanded:Batch-processed bead foams offer lower densities and reduced shear strength compared to extruded alternatives. Building-integrated photovoltaics sandwich panels in Germany and France specify fire-rated expanded grades meeting EN 13501-1 standards as architects prioritize lightweight substrate solutions.
- Laminated:Bonded multi-layer structures serve mature transport interior niches where existing supply relationships limit new entrant access. Rail refurbishment programs for ICE 2 and TGV fleets in Germany and France drive specification updates under ECHA decaBDE sunset timelines.
- Coated:Surface-treated foams enhance resin adhesion and environmental resistance for specialized composite applications. Automotive prototyping studios in Stuttgart and Munich specify rapid-turn coated variants for concept vehicle sandwich panel validation.
Extruded dominates installed base. Coated is where expansion concentrates.
Application:
Cost tier stratification separates premium structural grades from commodity non-load-bearing applications, with certification burden determining margin capture.
- Construction:Fire-retardant PET cores penetrate building-integrated photovoltaics substrates as German and French architects specify EN 13501-1 compliant insulation layers. REACH flame-retardant substitution timelines accelerate reformulation demand for legacy halogenated systems in commercial facade applications.
- Automotive:Lightweight sandwich panels reduce mass in electric vehicle battery enclosures and interior trim modules. BMW and Volkswagen development centers in Munich and Wolfsburg prototype PET core solutions for next-generation platform architectures.
- Packaging:Standard-density expanded grades protect high-value electronics and medical devices during transit. E-commerce fulfillment networks in Belgium and the Netherlands specify recyclable alternatives to expanded polystyrene for last-mile delivery protection.
- Signage:Rigid yet lightweight boards support outdoor advertising displays and exhibition graphics. Print service bureaus in Milan and Barcelona specify UV-stable laminated grades for temporary architectural installations.
Construction commands premium pricing. Packaging generates highest volume throughput.
End User:
Customer type determines technical service intensity, with contractors requiring field support that manufacturers handle through specification engineering.
- Manufacturers:Wind blade fabricators and composite component producers dominate structural grade procurement. LM Wind Power and Siemens Gamesa maintain dedicated supplier development programs with extruders capable of lot-level traceability documentation.
- Contractors:Installation firms specify core materials for retrofit insulation and facade renovation projects. German construction consortiums in the northern industrial corridor coordinate direct mill relationships to bypass distributor markups on large-scale commercial builds.
- Retailers:Point-of-sale display and fixture suppliers source lightweight boards for temporary promotional installations. Scandinavian furniture chains specify recyclable PET alternatives to conventional foam boards for sustainability-aligned visual merchandising.
- Designers:Architectural and industrial design studios prototype conceptual structures using variable-density profiles. Digital fabrication labs in Copenhagen and Eindhoven experiment with custom gradient cores for computational design applications.
Manufacturers anchor structural grade demand. Contractors represent the steepest expansion trajectory for fire-rated building products.
Performance Grade:
Volume concentrates in standard formulations, while margin accrues to certified high-strength and fire-retardant tiers requiring specialized compounding.
- Fire-Retardant:Phosphorus-nitrogen synergist systems replace legacy halogenated retardants under ECHA authorization timelines. Rail interior refurbishment programs for ICE 2 and TGV fleets in Germany and France represent near-term demand concentration.
- High-Strength:Elevated density extruded grades serve offshore wind blades exceeding 100 meters in length. North Sea project specifications drive qualification upgrades as turbine scale increases mechanical loading requirements.
- Standard:General-purpose formulations satisfy non-structural packaging, signage, and temporary protection applications. Price-sensitive buyers in Southern European markets prioritize cost efficiency over performance certification.
- Lightweight:Ultra-low density expanded grades optimize material efficiency in non-load-bearing applications. Aerospace cabin interior prototyping in Toulouse and Hamburg explores weight-minimized cores for seating and partition validation.
Standard grades dominate shipment volume. Fire-retardant formulations capture expanding share in regulated building and transport segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural surplus in PET foam core exports to North Sea wind markets, while the United States and China remain net importers of certified aerospace and rail grades. Trade flows concentrate between extrusion hubs and blade fabrication clusters.
Germany
North Sea offshore wind procurement drives demand for high-density extruded grades serving Vestas and Siemens Gamesa blade programs. KBA coordinates with EASA on composite certification standards for rail applications. The northern industrial corridor between Bremen and Hamburg hosts dedicated logistics lanes connecting core production directly to mold staging areas.
United States
IRA domestic content rules are redirecting investment toward Great Lakes and Atlantic offshore wind fabrication. FAA qualification requirements for aerospace grades extend product launch timelines. Blade manufacturing clusters in Texas and the Great Lakes region are establishing direct mill relationships with extruders capable of lot-level traceability.
China
Dual carbon goals accelerate substitution of PVC and balsa cores in domestic wind turbine manufacturing. MIIT standards for composite materials in rail and construction applications create compliance benchmarks. Yangtze River Delta fabrication hubs serve both domestic blade OEMs and export markets for standard-density grades.
France
ANSM coordinates transitional certification periods for rail interior refurbishment programs on ICE 2 and TGV fleets. ECHA decaBDE sunset timelines compel reformulation of legacy halogenated flame retardants. Paris-region design studios and Toulouse aerospace clusters specify fire-rated grades for cabin interior prototyping.
Denmark
Supplier development programs at LM Wind Power and Vestas compress procurement channels around extruders with verified post-consumer recycled feedstock. EU Green Deal carbon-border documentation requirements favor integrated resin-to-foam producers. Copenhagen digital fabrication labs experiment with variable-density profiles for computational design applications.
PET Foam Core Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream capturing margin through material differentiation. The supplier base concentrates around integrated extruders with captive recycling streams and specialized formulators serving vacuum-infused wind applications. Three archetypes dominate: backward-integrated resin producers, geographic-proximity specialists near installation hubs, and certification-heavy compounders for regulated transport segments. Competitive moves center on M&A to secure flake supply and strategic partnerships for carbon-border traceability systems.
Among European integrated producers, Armacell and Gurit Holding AG exemplify the backward-integrated archetype, while DIAB Group occupies a position anchored to Baltic and North Sea turbine installation geography. These three names represent the core competitive set around which qualification programs and direct mill relationships are consolidating.
| Leading Market Players |
|---|
| Armacell |
| 3A Composites GmbH |
| DIAB Group |
| Gurit Holding AG |
| CoreLite |
| Carbon-Core Corp |
| Sicomin Epoxy Systems |
| SAERTEX GmbH & Co. KG |
| Changzhou Tiansheng New Materials Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Recycled PET flake price volatility compresses margin structures while simultaneously forcing supply chain consolidation around backward-integrated resin producers. This input cost instability widens pricing spreads between certified aerospace grades and commodity packaging formulations.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure. Price differentiation separates fire-retardant rail-certified grades from standard construction formulations. Cost compression in standard-density tiers intensifies because balsa substitution programs are accelerating volume procurement. Packaging buyers exhibit highest price sensitivity, while wind blade fabricators prioritize lot-level traceability over per-unit cost.
Supply Chain Analysis
Extended payment terms from wind OEMs are reshaping supplier working capital requirements across the value chain. Extrusion capacity concentrates in Germany, Belgium, and Denmark. Feedstock draws from post-consumer bottle collection networks and industrial PET scrap streams. Single-source vulnerability for certified aerospace grades creates qualification bottlenecks. Distribution runs through direct mill relationships rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon-border adjustments are disrupting incumbent positioning by mandating verified recycled-content traceability. This regulatory inflection compresses qualification timelines while rewarding integrated producers.
For Market Incumbents: Entrench through captive recycling infrastructure and EASA-KBA coordinated certification investments. Armacell and Gurit Holding AG face margin pressure from PVC core substitutes in sub-100°C applications. Defensive moves center on securing flake supply via M&A and deploying digital twin-enabled resin infusion simulation to accelerate custom density qualification.
For New Entrants and Emerging Players: Establish a beachhead in US IRA-eligible domestic content supply chains for Great Lakes offshore wind. White-space targets include fire-rated building-integrated photovoltaics substrates and automotive battery enclosure prototyping. Go-to-market leverage rests on rapid-turn coated variants for Stuttgart and Munich concept vehicle studios.
For Investors and Strategic Acquirers: ECHA decaBDE sunset timelines reshape the acquisition landscape toward phosphorus-nitrogen synergist compounders. Long-term viability favors extruders with verified post-consumer feedstock and rail-aerospace dual certification. Acquisition target archetype: mid-cap German or Belgian producers with KBA-EASA qualification pipelines. Monitor EU AI Act supply-chain traceability provisions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Recycling | Captive feedstock secures margin against bottle-to-fiber demand competition in EU collection networks. |
| Fire-Retardant Reformulation Investment | Phosphorus-nitrogen systems capture ICE 2 and TGV refurbishment demand under ECHA authorization timelines. |
| Digital Twin-Enabled Qualification | Computational fluid dynamics integration reduces prototype waste for Vestas and Siemens Gamesa density gradient programs. |
| North American Capacity Buildout | IRA domestic content eligibility attracts Great Lakes and Atlantic offshore wind procurement commitments. |
| Rail-Aerospace Dual Certification | Simultaneous KBA and EASA qualification opens multi-jurisdictional revenue streams in regulated transport segments. |
Study Parameters
Initial hypotheses were tested against primary input from wind blade procurement directors, composite R&D engineers, rail interior specification managers, and PET extrusion plant managers and refined through secondary validation. Sources included ECHA substance authorization databases, EU customs trade flows for PET foam core, wind turbine OEM annual disclosures, and REACH compliance filings. Bottom-up segment sizing triangulated against top-down renewable energy infrastructure investment tracking.
Demand-supply balance modeling across the analysis window incorporated density grade tier, end-use application, performance certification level, and regional production hub segmentation. CAGRs derived from installation pipeline tracking and substitution rate assumptions for balsa and PVC cores. Forecast inputs included North Sea offshore wind capacity additions and EU Green Deal carbon-border implementation phasing.
Sensitivities concentrate around recycled PET collection infrastructure development and EASA-KBA certification timeline coordination. Forecasts reflect documented assumptions on flake price volatility and blade length scaling. Macroeconomic contraction, regulatory delay, or thermoset core temperature threshold breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
North America Polymer Emulsion Market