
 Mining Lubricants Market | 2026-2036
Mining Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Lubricants Market Intelligence
The historical distinction between lubricants for surface and underground mining operations is collapsing under pressure for unified, high-performance formulations. Shell plc leverages its extensive global distribution network to serve remote mining sites across multiple continents. Exxon Mobil Corporation competes on advanced synthetic oil technologies designed for extreme temperature and pressure conditions. FUCHS specializes in application-specific greases and fluids for specialized equipment like crushers and conveyors.
Mining lubricants are specialized formulations engineered to protect heavy machinery from wear in abrasive, high-pressure environments. They feature high viscosity indices and specific additive packages to ensure reliability and prevent equipment failure. Hydraulic fluids and gear oils represent core product segments, critical for machinery like excavators and loaders. The metal mining end-user segment is expanding more rapidly than coal extraction due to demand for energy transition minerals.
Environmental regulations from bodies like the US EPA and the European Union's REACH framework govern lubricant composition and disposal. In Australia, state-level environmental protection agencies enforce stringent rules on spills and contamination, influencing product selection at mine sites. Operators must continually balance the technical performance requirements of advanced equipment against evolving sustainability mandates and lubricant lifecycle costs.
Market Dynamics
The central tension shaping the market is the dual pressure from harsh operational environments demanding higher-performance synthetics and regulatory frameworks like the EU's CSRD, which mandate a shift toward biodegradable lubricants.
Growth Catalysts
- Energy Transition Minerals:Demand accelerates in metal mining for battery materials like lithium and cobalt, driven by the global shift to electric vehicles.
- Sustainability Mandates:The EU's CSRD compels operators to adopt biodegradable lubricants to meet new environmental impact disclosure requirements for hydraulic fluids.
- Australian Mining Expansion:Concentrated demand from Australia's vast iron ore and lithium sites provides a significant volume catalyst for specialized greases and oils.
Market Restraints
- Input Cost Volatility:Price fluctuations in synthetic base oils create cost uncertainty for formulators of high-performance lubricants, impacting margins.
- Performance Trade-offs:Biodegradable lubricants can have lower thermal stability than conventional synthetics, limiting use in high-temperature equipment like haul truck engines.
- Regulatory Fragmentation:Divergent chemical rules between the EU's REACH and the US EPA's TSCA complicate global product formulation and market access.
Strategic Opportunities
- Condition Monitoring Integration:Developing "smart lubricants" with embedded sensors for real-time data on fluid health, enabling predictive maintenance strategies.
- African Mining Corridors:Establishing supply hubs along emerging mining corridors in Africa, like the copper belt in Zambia, to serve underpenetrated markets.
- Formulations for Automation:Creating specialized fluids for the unique demands of autonomous mining fleets, including robotic drills and driverless trucks.
Industry Challenges
- Remote Logistics:Maintaining secure supply chains to deliver lubricants to extremely remote mine sites in locations like the Andes remains a core operational hurdle.
- Dual Certification Burden:New formulations face a lengthy process for certification by both equipment OEMs for performance and bodies like the EU Ecolabel for environmental compliance.
- Specialized Talent Scarcity:A shortage of tribologists with expertise in both heavy machinery and sustainable chemistry persists across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Lubricants Market |
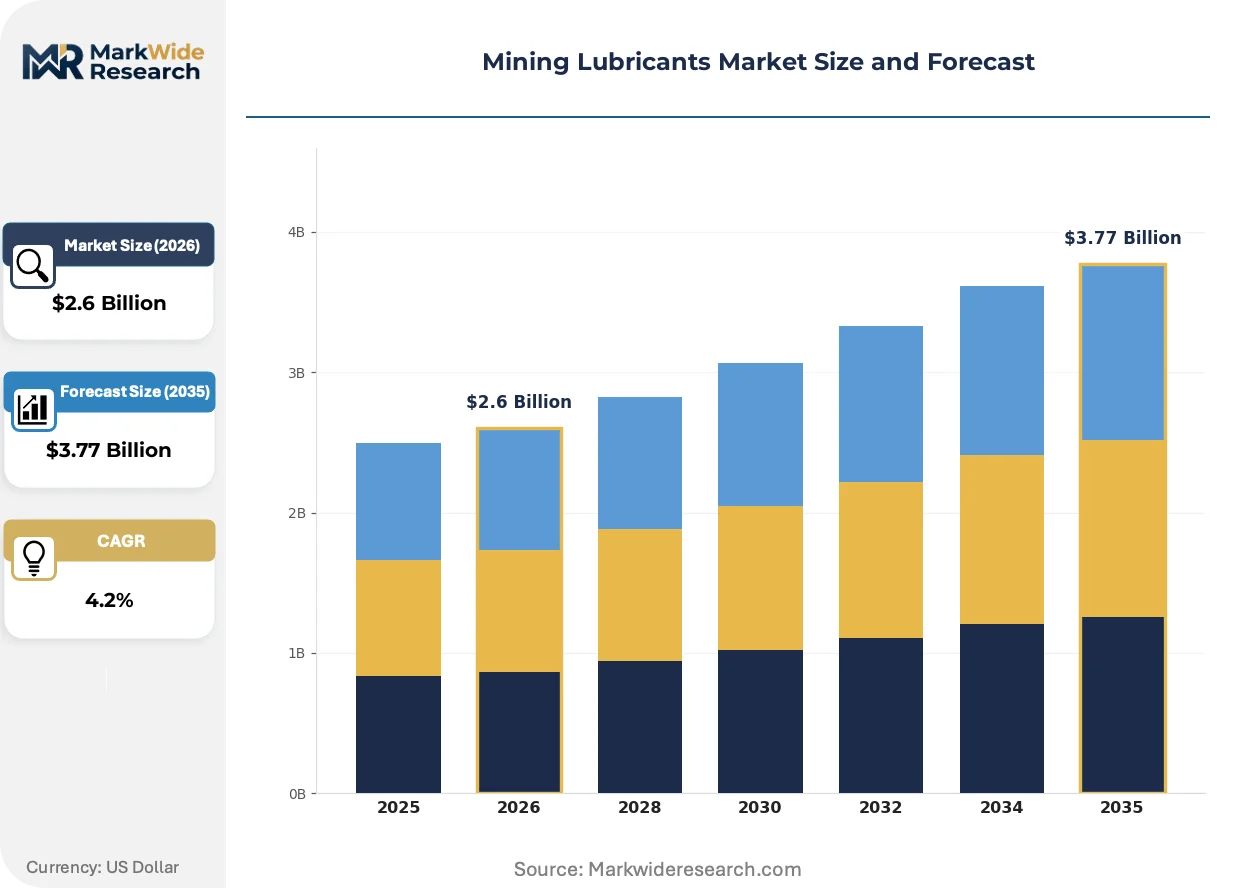
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $3.77 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greases, Hydraulic Fluids, Gear Oils, Compressor Oils, Wire Rope Lubricants, Heat Transfer Fluids Application: Drilling Equipment, Conveyors, Crushers, Excavators, Loaders, Pumps Technology: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Biodegradable Oil, Additive-Enhanced Oil, Base Oil End User: Metal Mining, Coal Extraction, Quarry Operations, Non-Ferrous Mines, Aggregate Producers, Salt Excavation |
| Companies Covered | Exxon Mobil Corporation, TotalEnergies SE, Shell plc, Chevron Corporation, BP p.l.c., FUCHS, Quaker Chemical Corporation, Sinopec Corp., Kluber Lubrication, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Lubricants Market Strategic Shifts & Innovations
The convergence of sustainability mandates and digitalization is altering lubricant selection and lifecycle management within mining. Performance is now evaluated on mechanical protection, environmental footprint, and data-driven operational efficiency.
Synthetic ester-based biodegradable lubricants offer an alternative to mineral oils in environmentally sensitive areas. Mining operators facing strict spill regulations are adopting these for hydraulic systems. The proliferation of these eco-friendly products is fragmenting the traditional market for general-purpose conventional lubricants.
Australia’s state-level environmental agencies enforce strict rules on lubricant spills and soil contamination. This pressure compels operators to prioritize products with high biodegradability, influencing procurement for equipment near sensitive ecosystems. The hydraulic fluid and grease segments in Western Australia's open-pit mines are most affected.
Major mining operators are shifting from transactional purchasing toward total cost of ownership (TCO) evaluation models. This change disrupts traditional distributors, creating an opening for suppliers offering integrated fluid management and on-site analysis. This trend is most prominent in capital-intensive mining operations in Canada and Chile.
Mining Lubricants Market Segmentation
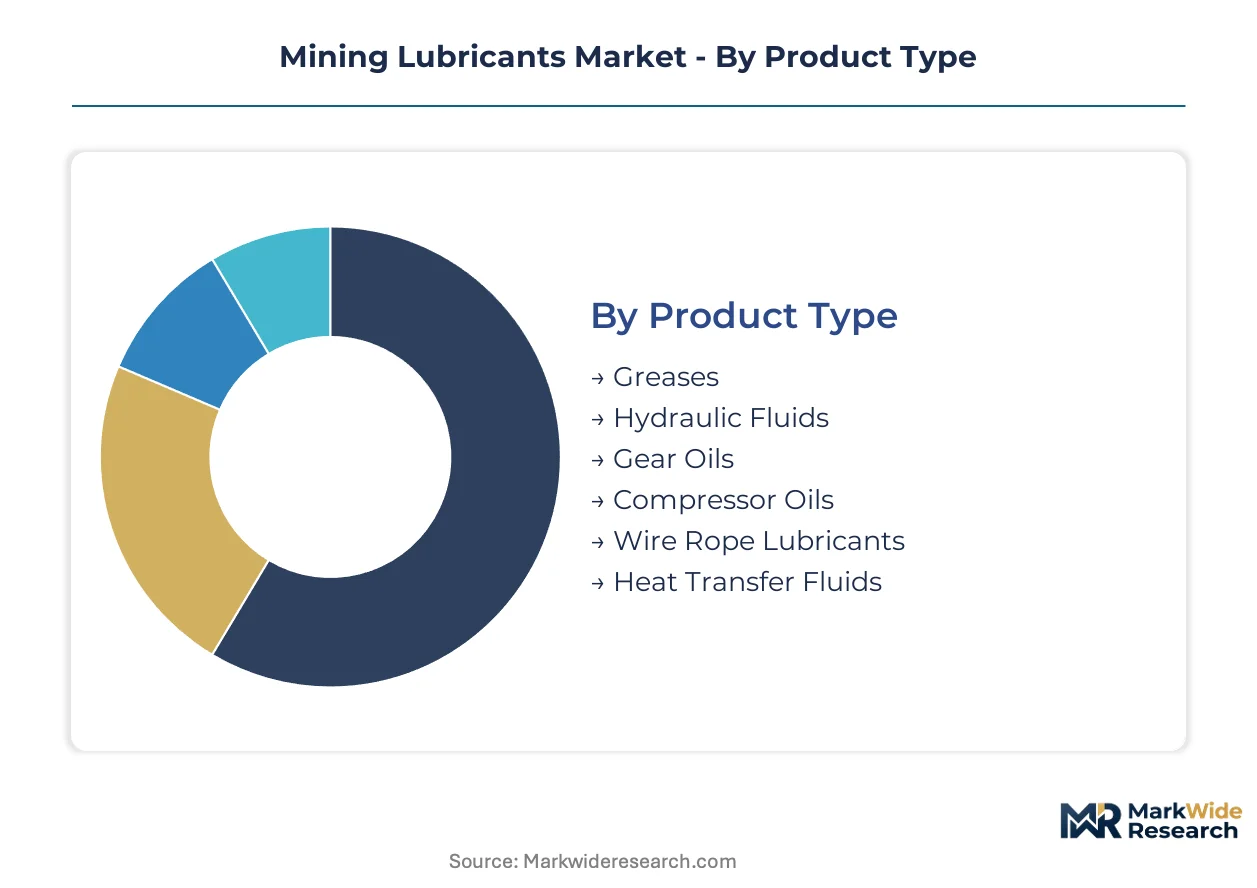
Market segmentation for mining lubricants reveals critical distinctions in product performance, application demands, and technological evolution. Understanding these segments helps suppliers align offerings with specific operational needs and regulatory pressures across the global mining industry.
Product Type:
Margin pools within the product type segment reflect the specialization required for severe mining conditions.
- Hydraulic Fluids:Specialized fluids transmit power and lubricate components within hydraulic systems, ensuring efficient operation of excavators and loaders. Demand is concentrating in Australia's iron ore and lithium sites due to the need for reliable performance in harsh environments.
- Gear Oils:High-viscosity formulations engineered to protect heavy-duty gearboxes from extreme pressure and wear in mining machinery. The expansion of metal mining operations, particularly for battery materials, drives demand for these robust lubricants.
- Greases:Semi-solid lubricants providing long-lasting protection for bearings and joints in crushers and conveyors.
- Compressor Oils:Formulated to maintain efficiency and prevent wear in air compressors used for drilling and pneumatic tools.
- Wire Rope Lubricants:Designed to penetrate and protect steel wire ropes from corrosion and abrasion on hoists and draglines.
- Heat Transfer Fluids:Specialized liquids managing temperature in critical mining equipment, particularly in high-temperature applications.
The dominant share belongs to Hydraulic Fluids, while Gear Oils are closing the gap fastest.
Application:
Volume demand across application segments directly correlates with the scale and mechanization of mining operations.
- Excavators:Heavy-duty earthmoving machines require specialized hydraulic fluids and gear oils for their robust operation. Demand intensifies in large-scale open-pit mines in Australia and Chile.
- Loaders:Equipment used for moving bulk materials, needing high-performance lubricants for their engines, transmissions, and hydraulic systems. Operators in African mining corridors are upgrading fleets, increasing lubricant consumption.
- Drilling Equipment:Requires specific lubricants for rotary and percussion drills operating under high pressure in rock.
- Conveyors:Utilize greases and oils to ensure smooth, continuous material transport in processing plants.
- Crushers:Heavy machinery processing mined ore, demanding lubricants resistant to high impact and dust contamination.
- Pumps:Essential for dewatering and slurry transport, needing robust lubricants for their seals and bearings.
Excavators and Loaders collectively represent the largest consumption points for mining lubricants.
Technology:
Performance requirements dictate technology selection, with advanced formulations addressing extreme operational challenges.
- Synthetic Oil:Engineered for extreme temperature and pressure conditions, offering superior thermal stability and extended drain intervals for heavy machinery. Exxon Mobil Corporation competes on advanced synthetic oil technologies.
- Biodegradable Oil:Environmentally friendly formulations, often ester-based, designed to minimize ecological impact from spills and contamination. The EU's CSRD compels operators to adopt these lubricants for hydraulic fluids.
- Mineral Oil:Traditional petroleum-based lubricants, offering cost-effectiveness but with lower performance in extreme conditions.
- Semi-Synthetic Oil:Blends of mineral and synthetic base stocks, balancing performance and cost for various applications.
- Additive-Enhanced Oil:Base oils fortified with specialized chemicals to improve anti-wear, anti-corrosion, and anti-foaming properties.
- Base Oil:The primary component of lubricants, forming the foundation for all finished product formulations.
The shift towards sustainable operations is rapidly elevating the importance of Biodegradable Oil formulations.
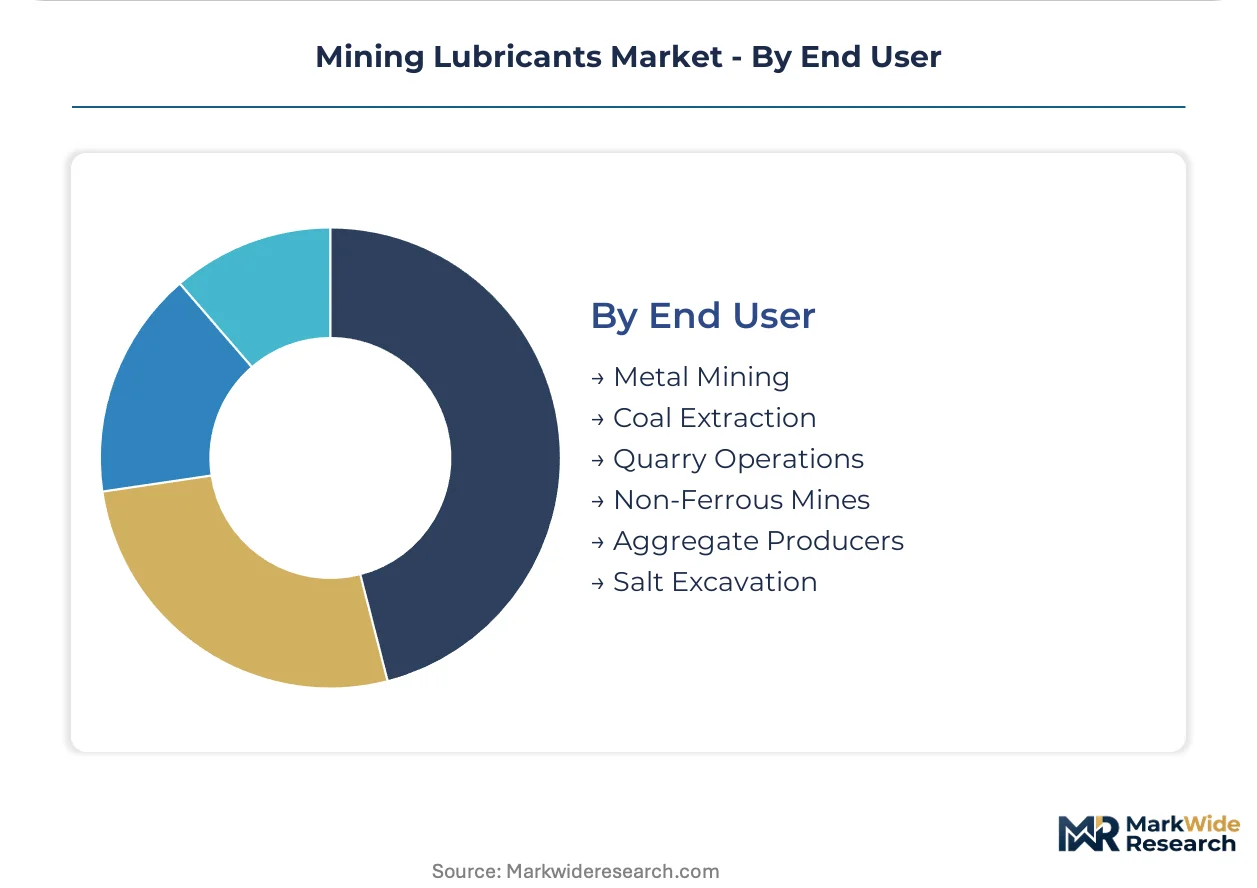
End User:
Demand drivers within the end-user segment reflect global energy transitions and infrastructure development.
- Metal Mining:Encompasses operations extracting battery materials like lithium, cobalt, and iron ore, driving significant demand for high-performance lubricants. This segment is expanding more rapidly due to energy transition minerals.
- Coal Extraction:Involves both surface and underground operations, requiring robust lubricants for longwall shearers and draglines. This segment faces declining demand in many regions due to decarbonization efforts.
- Quarry Operations:Extracting stone, sand, and gravel for construction, using lubricants for crushers, excavators, and haul trucks.
- Non-Ferrous Mines:Focus on metals other than iron, such as copper and nickel, with similar lubricant needs to general metal mining.
- Aggregate Producers:Supply crushed stone, sand, and gravel for infrastructure projects, consuming lubricants for heavy machinery.
- Salt Excavation:Involves specialized equipment for extracting rock salt or brine, requiring lubricants resistant to corrosive environments.
Metal Mining currently represents the most dynamic end-user segment, propelled by global electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global demand for mining lubricants is increasingly shaped by trade flows of critical minerals from extraction hubs to processing centers. Australia's vast iron ore exports to Asian markets, for instance, drive significant lubricant consumption. This global commodity movement underpins regional market dynamics for specialized fluids.
Australia
Australia's extensive iron ore and lithium extraction sites drive substantial demand for high-performance mining lubricants. State-level environmental protection agencies enforce stringent rules on lubricant spills and contamination. Western Australia's Pilbara region concentrates heavy machinery operations, requiring robust hydraulic fluids and gear oils. This region also sees increasing adoption of biodegradable formulations.
Chile
Chilean copper mining operations, particularly in the Atacama Desert, demand specialized lubricants for advanced excavators and haul trucks. National environmental regulations govern mining waste and emissions, influencing lubricant selection. The Antofagasta region, a key copper production hub, prioritizes total cost of ownership models for fluid management. This shift impacts traditional distributor relationships.
China
China's rapid industrialization and metal mining expansion fuel strong demand for robust lubricants across diverse operations. The Ministry of Ecology and Environment (MEE) sets stringent standards for industrial pollution and waste disposal. Inner Mongolia and Xinjiang provinces, with their extensive coal and metal mining activities, represent major consumption points. Local operators seek efficient and compliant fluid solutions.
South Africa
South Africa's deep-level gold and platinum group metals mining operations require highly specialized lubricants for extreme pressure and temperature conditions. The Department of Mineral Resources and Energy oversees environmental compliance, impacting product choices. The Bushveld Complex, a major PGM producing area, sees demand for advanced synthetic oils. Remote logistics present a continuous operational challenge.
Brazil
Brazilian iron ore, bauxite, and nickel extraction operations generate substantial demand for heavy-duty mining lubricants. The National Mining Agency (ANM) enforces environmental and safety standards for mining activities. Minas Gerais state, a primary iron ore producing region, focuses on optimizing equipment uptime through advanced fluid management. This region also sees investments in new mining projects.
Mining Lubricants Market Key Industry Players
Listed leaders compete with private specialists across global distribution and technology development within the mining lubricants market. The market structure exhibits consolidation among major energy companies, while specialized lubricant manufacturers maintain niche positions, often focusing on high-performance formulations. Key strategic archetypes include integrated oil majors leveraging their extensive global networks and pure-play lubricant firms focusing on application-specific solutions. Companies pursue portfolio diversification and strategic partnerships to address evolving sustainability mandates and operational challenges.
Within the integrated oil major archetype, Exxon Mobil Corporation and Shell plc leverage their extensive global infrastructure to serve remote mining sites. Exxon Mobil Corporation emphasizes advanced synthetic oil technologies designed for extreme conditions. Shell plc utilizes its broad distribution network to deliver high-performance formulations across multiple continents. FUCHS, a German-based specialist, exemplifies the pure-play lubricant firm archetype, focusing on application-specific greases and fluids for specialized equipment like crushers and conveyors.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| TotalEnergies SE |
| Shell plc |
| Chevron Corporation |
| BP p.l.c. |
| FUCHS |
| Quaker Chemical Corporation |
| Sinopec Corp. |
| Kluber Lubrication |
| Others |
Cost & Logistics Intelligence
Biodegradable oil formulations replacing traditional mineral oils are reshaping lubricant supply geography and influencing pricing structures across mining operations. This shift introduces new specialized producers and alters cost economics for mine operators.
Pricing Analysis
The pricing gap between advanced synthetic and biodegradable lubricants versus conventional mineral oils reflects a clear technology-generation divide, with value-based pricing dominating for high-performance formulations. Price differentiation stems from performance certification levels and specialized after-sales fluid management services for remote sites. Input cost volatility, particularly for synthetic base oils, creates upward pricing pressure across the market. Metal mining operations focused on critical battery materials are less price-sensitive than coal extraction end-users.
Supply Chain Analysis
Remote logistics to vast mining sites in regions like the Andes and the Australian Outback represent a continuous supply chain chokepoint. Global supply for specialized base oils and advanced additive packages draws from concentrated production hubs in Europe and North America. This reliance on specific raw material sources creates single-source vulnerability for formulators. Downstream distribution often runs through the extensive networks of integrated oil majors or specialized regional distributors catering to niche equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mining lubricants market is experiencing a buyer-power shift as major mining operators consolidate procurement and transition to total cost of ownership evaluation models. This move enhances their leverage over lubricant suppliers.
For Market Incumbents: Compound investments in sustainable lubricant R&D to counter the threat from specialized biodegradable formulations. Integrated oil majors must leverage their existing global distribution networks to offer comprehensive fluid management and on-site analysis, reinforcing channel control. Pursue dual certification for performance and environmental compliance, such as the EU Ecolabel, to meet evolving regulatory demands. This strategy helps defend against niche players and sustainability mandates.
For New Entrants and Emerging Players: Lead with specialized, application-specific fluid solutions targeting underpenetrated markets like African mining corridors. Focus on developing formulations for the unique demands of autonomous mining fleets, including robotic drills. The hydraulic fluid segment in Western Australia's open-pit mines presents a penetrable entry point due to strict spill regulations. Offer integrated fluid management services as a key go-to-market differentiator.
For Investors and Strategic Acquirers: Capital is best deployed toward pure-play lubricant firms specializing in sustainable chemistry or integrated fluid management solutions. These entities offer long-term viability as the mining industry shifts towards energy transition minerals and automation. Seek out targets with strong R&D capabilities in biodegradable formulations and digital integration. The signal to watch is a sustained increase in procurement mandates for "smart lubricants" across major mining operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands production of high-performance synthetic and biodegradable base oils for global demand. |
| Green Manufacturing Transition | Reduces environmental footprint, aligning with EU CSRD and other sustainability mandates. |
| Long-term Supply Agreement | Secures consistent supply of critical raw materials amidst input cost volatility. |
| Product Launch | Introduces new specialized fluids for autonomous mining equipment and extreme conditions. |
| Strategic Partnership | Enhances distribution reach and co-develops advanced lubricant technologies with OEMs. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings of this market analysis. Industry stakeholders, including mine operations managers, tribologists, and lubricant procurement leads, provided critical insights. Secondary research involved environmental agency reports, industry association publications, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Sensitivity analysis informed the quantitative modeling framework used to project market trajectories across the analysis window. Segmentation dimensions included product type, application, technology, end-user, and regional demand patterns. Compound annual growth rates were derived from historical trends, identified market drivers, and expert projections. Key industry-specific inputs included battery material production forecasts and environmental regulatory compliance timelines.
The analysis sits within stated boundaries; outcomes outside significant shifts in geopolitical stability or environmental policy would require recalibration. Forecasts reflect assumptions regarding technological adoption and mineral extraction rates. Practitioners should keep alternative scenarios live as energy transition mineral demand and regulatory landscapes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Japan Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
Contact Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
Firearm Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Germany Automotive Engine Oils Market