
 Global Antioxidant Market | 2026-2036
Global Antioxidant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antioxidant Market Analysis
Buyer concentration among food manufacturers is recalibrating procurement strategies across the value chain. BASF SE leverages its integrated petrochemical feedstock position to sustain cost advantages in synthetic antioxidant production. Kemin Industries anchors its competitive position through specialized botanical extraction capabilities for natural antioxidant lines. Archer Daniels Midland Company competes via vertical grain origination that secures tocopherol supply streams.
Antioxidants are molecules that inhibit oxidation of other compounds by neutralizing free radicals, with specifications including phenolic hydroxyl group density and peroxide value thresholds below 10 meq O₂/kg for food-grade certification; their primary commercial purpose extends shelf life in lipid-rich matrices and protects cellular structures in nutritional applications. Vitamin E derivatives command the deepest margin pools due to pharmaceutical-grade purification requirements, while dietary supplements represent the fastest-expanding application channel as direct-to-consumer wellness brands proliferate. Powder formulations dominate industrial-scale food manufacturing for dosing precision, though liquid emulsions gain traction in beverage fortification.
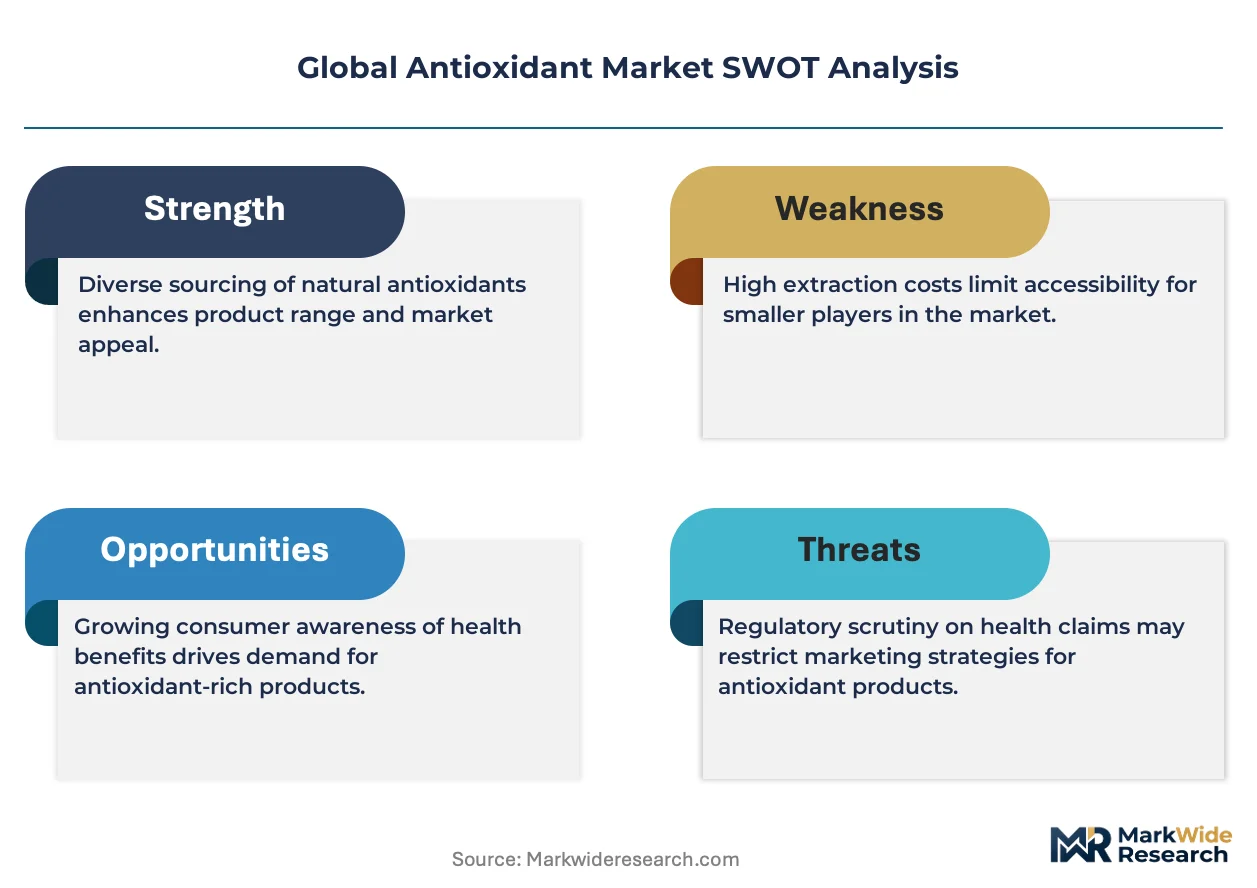
EFSA evaluates novel food antioxidant claims under centralized health claim procedures, while FDA GRAS determinations govern U.S. market entry for new botanical sources. REACH registration requirements constrain European supply of imported synthetic antioxidants, redirecting sourcing toward domestic or REACH-compliant producers. Stakeholders must monitor evolving purity standards across jurisdictions to align certification investments with regional demand trajectories.
Market Dynamics
Clean-label procurement mandates from packaged food manufacturers are compressing synthetic antioxidant volumes while expanding botanical extraction capacity requirements across supplier networks.
Growth Catalysts
- REACH compliance deadlines:ECHA registration timelines for synthetic antioxidants are accelerating domestic European production investments as importers face authorization bottlenecks.
- Pharmaceutical-grade tocopherol demand:Nutraceutical contract manufacturers in the United States are expanding vitamin E derivative orders for direct-to-consumer supplement formulations.
- Dual carbon targets:China's MEE emission standards are redirecting antioxidant production toward lower-carbon botanical extraction methods in Shandong and Jiangsu provinces.
Market Restraints
- Petrochemical feedstock volatility:Synthetic antioxidant producers remain exposed to benzene and phenol price swings tied to crude oil benchmarks.
- Chinese supply concentration:Over half of global BHT and BHA manufacturing capacity sits in East China chemical parks, creating single-point vulnerability.
- Natural extract yield limitations:Rosemary and green tea polyphenol recovery rates cap output scalability regardless of solvent optimization.
Strategic Opportunities
- Brazilian botanical sourcing:Amazonian acerola and camu camu extraction partnerships offer untapped ascorbic acid precursor supplies for North American fortification markets.
- Beverage emulsion systems:Liquid antioxidant dispersions for functional drinks represent a format gap currently underserved by powder-dominant suppliers.
- EU Green Deal bioeconomy incentives:Circular economy funding streams support antioxidant recovery from agricultural sidestreams including grape pomace and olive mill wastewater.
Industry Challenges
- Pharmaceutical-grade GMP certification timelines:New tocopherol purification facilities face 18-24 month FDA validation cycles before commercial supply release.
- Cross-jurisdiction specification alignment:Food-grade peroxide thresholds vary between EFSA, FDA GRAS, and Japan's MHLW standards, forcing redundant testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antioxidant Market |
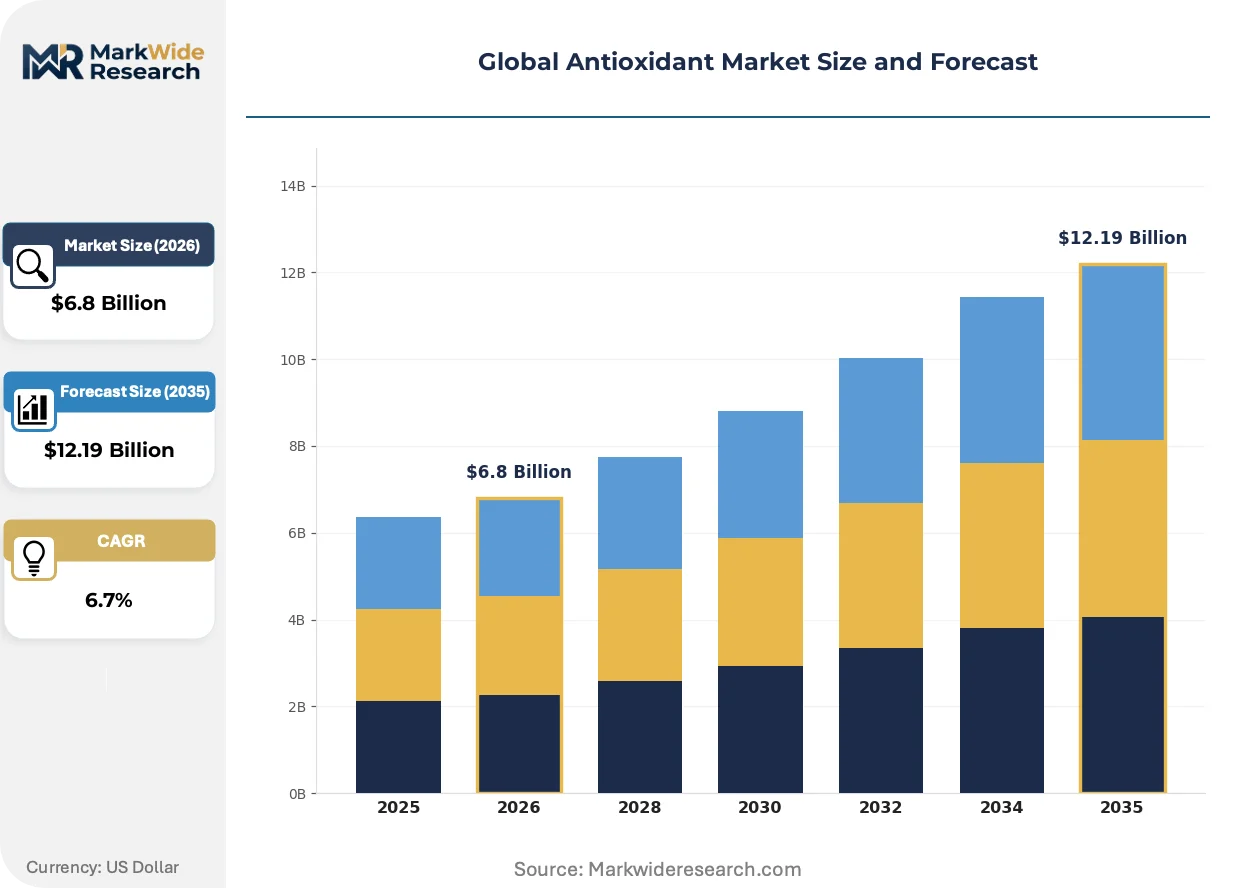
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin C, Vitamin E, Selenium, Alpha-Lipoic Acid Application: Food & Beverage, Cosmetics, Pharmaceuticals, Dietary Supplements Form: Powder, Liquid, Capsule, Granule End User: Food Manufacturers, Cosmetic Companies, Health Organizations, Dietary Supplement Retailers |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Koninklijke DSM N.V., Kemin Industries, Givaudan, Eastman Chemical Company, Kalsec, DuPont de Nemours, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antioxidant Market Emerging Trajectories
Enzymatic extraction protocols and precision fermentation routes are displacing solvent-based recovery methods while regulatory data requirements harden for novel antioxidant sources.
Supercritical CO₂ extraction equipment is modularizing antioxidant production footprints, allowing mid-scale food ingredient processors to install captive rosemary and grape seed processing lines without centralized tolling dependencies. Regional dairy cooperatives in France and Wisconsin are piloting these units for tocopherol retention in fortified milk powders. The technology is modularizing supply chain nodes previously concentrated in dedicated extraction facilities.
EFSA's updated guidance on novel food antioxidant health claims demands human intervention studies for oxidative stress biomarkers, extending authorization timelines for botanical entrants. The regulation compresses venture funding windows for startup ingredient developers. Supplement brands targeting German and Benelux markets are prioritizing EFSA-compliant dossier investments over faster U.S. GRAS pathways.
Direct contracting between antioxidant users and specialty crop growers is displacing spot commodity purchases for natural extracts. Clean-label bakery and snack manufacturers in California and the Netherlands are locking multi-year rosemary and green tea supply agreements with traceability verification. This pattern concentrates procurement functions previously handled by distributors.
Global Antioxidant Market Segmentation
Antioxidant procurement decisions hinge on certification pathways that vary sharply across product categories. Pharmaceutical-grade specifications command distinct regulatory dossiers from food-grade or cosmetic-grade alternatives, fragmenting supplier qualification requirements.
Product Type:
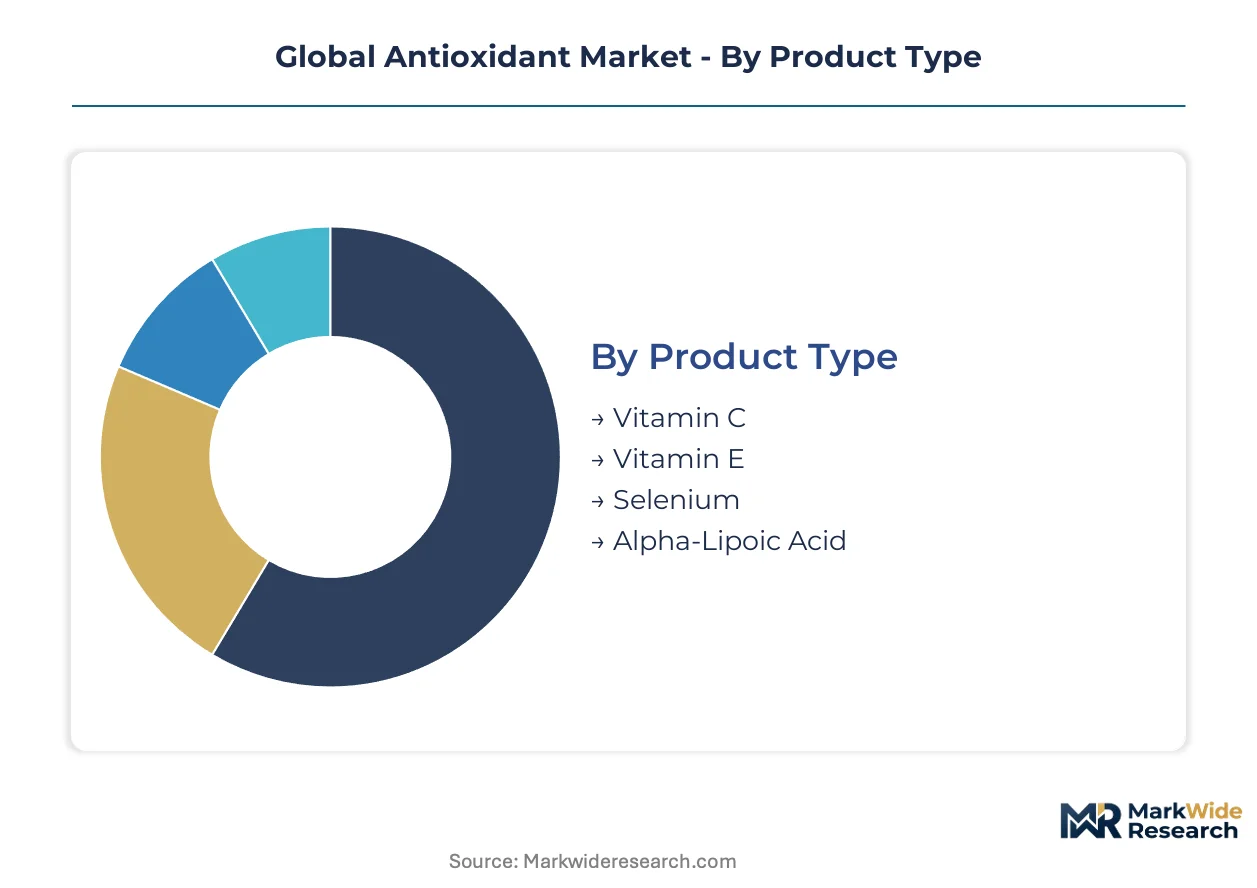
Vitamin E derivatives require FDA pharmaceutical GMP validation for nutraceutical applications, while vitamin C faces simpler FSSAI food-grade registration in India. Selenium compounds trigger EFSA novel food assessments in Europe. Alpha-lipoic acid sits under varying national pharmaceutical regulator oversight depending on intended end-use.
- Vitamin C:Ascorbic acid and its salts deliver water-soluble radical scavenging for beverage fortification and immune-positioned supplements. Demand concentrates in China's Shandong province where domestic pharmaceutical-grade capacity is scaling to serve contract manufacturers. REACH registration costs for synthetic ascorbic acid imports are redirecting European sourcing toward domestic producers.
- Vitamin E:Tocopherol and tocotrienol mixtures provide lipid-soluble protection with the steepest purity premiums for injectable-grade specifications. Nutraceutical contract manufacturers in the United States are expanding orders for direct-to-consumer supplement formulations. Dual carbon targets in China's Jiangsu province are accelerating botanical extraction investments over petrochemical synthesis.
- Selenium:Inorganic selenite and organic selenomethionine serve precision-dosed mineral supplements with narrow therapeutic windows.
- Alpha-Lipoic Acid:Disulfide compound with dual water- and fat-soluble antioxidant activity targets diabetic neuropathy and metabolic health positioning.
Vitamin E sits at the top of the volume ranking, with vitamin C climbing the fastest.
Application:
Cosmetic applications bear the heaviest safety dossier burden under EU MDR and FDA cosmetic ingredient regulations, while food-grade channels face peroxide threshold standardization across EFSA, FDA GRAS, and Japan's MHLW. Pharmaceutical applications lock in 18-24 month GMP validation cycles before commercial release.
- Food & Beverage:Shelf-life extension in lipid-rich matrices drives powder formulation dominance for dosing precision in industrial-scale manufacturing. Clean-label procurement mandates from packaged food manufacturers are compressing synthetic antioxidant volumes. EFSA purity standards for synthetic imports are tightening across European ports.
- Pharmaceuticals:Injectable-grade tocopherol and parenteral ascorbic acid command the deepest margin pools due to purification requirements. New tocopherol purification facilities face extended FDA validation timelines. Cross-jurisdiction specification alignment forces redundant testing protocols across export markets.
- Cosmetics:Topical antioxidant claims require stability testing and dermal safety documentation under varying national cosmetic regulations.
- Dietary Supplements:Direct-to-consumer wellness brands proliferate, expanding the fastest-expanding application channel for encapsulated and tableted formats.
Food and Beverage holds the largest volume position, with Dietary Supplements gaining share fastest.
Form:
Powder formulations dominate capital expenditure profiles for industrial-scale dosing equipment, while liquid emulsions require specialized homogenization investments. Capsule and granule formats carry distinct excipient registration requirements that vary by target market.
- Powder:Free-flowing crystalline or spray-dried formats enable precise batch dosing in bakery, snack, and dairy matrix integration. Powder formulations dominate industrial-scale food manufacturing for dosing precision.
- Liquid:Oil-based dispersions and aqueous solutions serve beverage fortification and cosmetic serum applications. Liquid emulsions gain traction in beverage fortification as functional drinks expand.
- Capsule:Hard gelatin and vegetarian shell formats target supplement retail with consumer-controlled dosing convenience.
- Granule:Agglomerated particles improve flow properties for direct-compression tablet manufacturing and sachet packaging.
Powder leads by volume, with Liquid expanding most quickly.
End User:
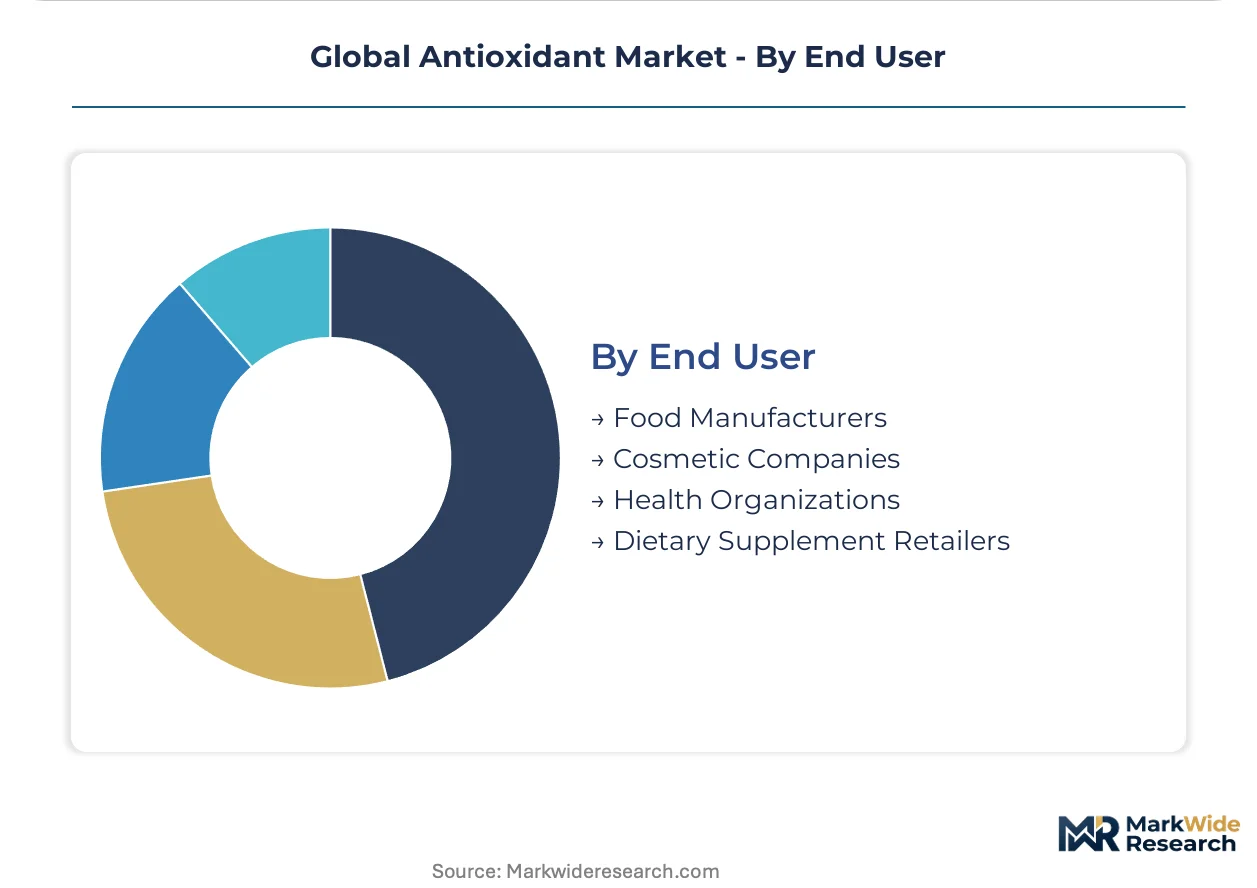
Food manufacturers consolidate procurement through direct grower contracting for traceability, while cosmetic companies demand batch-specific CoA documentation. Health organizations and dietary supplement retailers split between branded ingredient specifications and generic pharmacopeial grades.
- Food Manufacturers:Clean-label bakery and snack producers lock multi-year rosemary and green tea supply agreements with traceability verification. This pattern concentrates procurement functions previously handled by distributors.
- Dietary Supplement Retailers:Direct-to-consumer wellness brands prioritize EFSA-compliant dossier investments over faster U.S. GRAS pathways for German and Benelux market access.
- Cosmetic Companies:Formulators require oxidative stability data and compatibility testing for emulsion and anhydrous systems.
- Health Organizations:Hospital and clinical nutrition services source pharmaceutical-grade antioxidants under tender-based procurement with stringent purity guarantees.
Food Manufacturers occupy the top volume tier, with Dietary Supplement Retailers climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters in Germany's Ruhr Valley and China's Shandong province anchor antioxidant innovation pipelines. Process chemists and extraction specialists concentrate in industrial zones where petrochemical and botanical processing capabilities overlap.
China
Pharmaceutical-grade tocopherol contract manufacturers in Jiangsu province scale capacity to serve North American nutraceutical brands. MEE emission standards under dual carbon targets redirect production toward lower-carbon botanical extraction methods. Shandong chemical parks host over half of global BHT and BHA synthetic capacity, creating concentrated supply vulnerability.
United States
Nutraceutical contract manufacturers expand vitamin E derivative orders for direct-to-consumer supplement formulations. FDA GRAS determinations govern market entry timelines for novel botanical antioxidant sources. Wisconsin dairy cooperatives pilot supercritical CO₂ extraction units for tocopherol retention in fortified milk powders.
Germany
REACH registration requirements constrain imported synthetic antioxidant supply, accelerating domestic production investments. ECHA authorization bottlenecks redirect sourcing toward REACH-compliant producers. Bavarian extraction specialists serve clean-label bakery manufacturers across the Benelux corridor.
France
Regional dairy cooperatives deploy modular supercritical CO₂ equipment for captive rosemary and grape seed processing. EU Green Deal bioeconomy funding supports antioxidant recovery from agricultural sidestreams including grape pomace. ANSM oversight of cosmetic-grade specifications adds regulatory layers for topical applications.
Brazil
Amazonian acerola and camu camu extraction partnerships supply ascorbic acid precursors for North American fortification markets. ANVISA pharmaceutical-grade certification requirements parallel FDA validation complexity for export-bound production. São Paulo-state processors develop traceability verification systems for clean-label procurement contracts.
Global Antioxidant Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the antioxidant value chain. The market structure tiers between integrated petrochemical producers and specialized botanical extraction houses. Three archetypes dominate: feedstock-integrated synthetics producers, crop-origination-secured natural extractors, and pharmaceutical-grade purification specialists. Capacity expansion and direct grower contracting represent the dominant competitive moves reshaping supply relationships.
Among European-based diversified chemical producers, BASF SE and Koninklijke DSM N.V. occupy positions reflecting integrated feedstock and nutritional ingredient portfolios respectively. Kemin Industries exemplifies the specialized botanical extraction archetype, while Archer Daniels Midland Company anchors the agricultural origination-secured model through vertical grain control. These three company structures represent the strategic fault lines dividing synthetic from natural antioxidant supply.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Kemin Industries |
| Givaudan |
| Eastman Chemical Company |
| Kalsec |
| DuPont de Nemours |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap botanical extraction specialists anchor supply discipline across European and North American procurement networks, translating crop origination control into pricing power that resists commodity volatility. Their long-term grower contracts insulate margin structures from spot market swings while synthetic antioxidant producers absorb benzene and phenol feedstock pressure.
Pricing Analysis
Bundled certification-and-delivery contracts dominate pharmaceutical-grade tocopherol procurement, while unbundled spot transactions persist for food-grade synthetic antioxidants. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade certification levels separates margin pools by purity threshold. Cost compression in synthetic BHT and BHA runs through crude oil benchmark volatility. Dietary supplement retailers exhibit highest price sensitivity due to direct-to-consumer margin pressure, while injectable-grade pharmaceutical buyers accept steep premiums for GMP-validated supply security.
Supply Chain Analysis
Direct-to-food-manufacturer channels handle clean-label procurement volumes previously routed through distributors, with Shandong province chemical parks and Jiangsu botanical extraction facilities anchoring Chinese supply dominance. Feedstock flows draw from petrochemical benzene streams, rosemary and green tea agricultural harvests, and Amazonian acerola orchards. Single-source vulnerability concentrates in East China synthetic capacity clusters. Distribution runs through long-term offtake agreements with traceability verification replacing spot commodity purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-constrained European sourcing costs and expanding Chinese pharmaceutical-grade production capacity, with regulatory compliance differentials creating procurement cost spreads.
For Market Incumbents: Extend backward integration into specialty crop origination to defend against direct grower contracting by clean-label food manufacturers. Lock multi-year rosemary and green tea supply agreements with traceability verification before regional extraction capacity saturates. Prioritize EFSA-compliant dossier investments over faster U.S. GRAS pathways for German and Benelux market access. For New Entrants and Emerging Players: Beverage emulsion system manufacturers represent an underserved buyer archetype currently forced to adapt powder-dominant supplier formats. Target liquid antioxidant dispersion gaps in functional drink fortification with specialized homogenization capabilities. Enter through direct contracting partnerships with regional dairy cooperatives piloting supercritical CO₂ extraction units. For Investors and Strategic Acquirers: Nutraceutical contract manufacturers are the most active acquirer in this space, consolidating pharmaceutical-grade purification specialists to secure injectable-grade tocopherol supply security. Position for five-to-ten year viability by targeting botanical extraction houses with captive Amazonian or Mediterranean crop origination. Monitor EFSA novel food authorization timelines as inflection indicator for venture funding compression in startup ingredient developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Crop Origination | Direct grower contracting locks rosemary and green tea supply streams away from distributor intermediaries. |
| Pharmaceutical-Grade GMP Certification Investment | FDA validation cycles secure 18-24 month competitive moats in injectable-grade tocopherol supply. |
| Liquid Emulsion Format Development | Homogenization capabilities capture beverage fortification demand underserved by powder-dominant competitors. |
| REACH-Compliant Domestic Production Expansion | ECHA authorization bottlenecks redirect European sourcing toward compliant producers with registration dossiers. |
| Supercritical CO₂ Extraction Modularization | Mid-scale equipment deployment enables captive processing without centralized tolling dependencies. |
Methodological Framework
Multiple input streams — regulatory filing databases, customs trade records, and crop origination contracts — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant managers at extraction facilities, procurement leads at nutraceutical contract manufacturers, and technical R&D directors at food ingredient formulators informed capacity and pricing intelligence. Secondary validation drew from EFSA novel food registers, FDA GRAS notifications, REACH registration databases, and SEC 10-K disclosures from diversified chemical producers.
Cross-referencing historical volume trajectories against panel input from industry stakeholders anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application channel, form factor, and end-user archetype alongside regional regulatory cluster differentiation. CAGRs were derived from elasticity-adjusted demand curves incorporating pharmaceutical-grade purity premiums and clean-label substitution rates.
Inputs from EFSA authorization timelines and Chinese MEE emission standard enforcement were available through the study window; gaps in private grower contract pricing introduce uncertainty bands around natural extract cost forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Tongkat Ali Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market