
 United Kingdom Food Hydrocolloids Market | 2026-2036
United Kingdom Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Food Hydrocolloids Market Analytics
Commodity hydrocolloid trading margins is narrowing as specialty ingredient value pools deepen. Cargill Incorporated leverages its integrated supply chain from agricultural sourcing to food-grade refinement. Ingredion Incorporated anchors its position through R&D intensity in texture modification systems. Koninklijke DSM NV differentiates via biotechnology-derived stabilizers that command premium positioning.
Food hydrocolloids comprise high-molecular-weight hydrophilic biopolymers—polysaccharides and proteins—that hydrate in aqueous systems to modify viscosity, gelation, and water-binding properties through mechanisms including hydrogen bonding and ionic cross-linking. These functional ingredients serve primarily to stabilize emulsions, control syneresis, and deliver targeted mouthfeel across processed food matrices. Pectin dominates clean-label applications where citrus-derived and apple-sourced variants replace synthetic stabilizers in British dairy and fruit preparations. Xanthan Gum leads industrial-scale sauces and dressings where pseudoplastic flow behavior ensures consistent pumpability and cling. Gelatin occupies mature segments including confectionery and premium desserts, though plant-based alternatives are eroding share in certain bakery applications.
The Food Standards Agency enforces purity specifications and labeling requirements that determine which hydrocolloid grades achieve retail distribution eligibility in Great Britain. REACH compliance through ECHA governs chemical safety assessments for imported biopolymer raw materials entering UK supply chains. BSI standards on food additive specifications create technical barriers that favor suppliers with established analytical certification capabilities. Stakeholders must monitor divergence between retained EU law and emerging Great Britain-specific regulatory instruments that could fragment compliance requirements.
Market Dynamics
The Food Standards Agency's additive guidance revision is forcing British manufacturers to reformulate around clean-label hydrocolloid systems, compressing synthetic stabilizer volumes while expanding citrus pectin and fermentation-derived alternatives across dairy and bakery matrices.
Growth Catalysts
- Clean-label mandates:The Food Standards Agency's evolving additive guidance drives replacement of synthetic stabilizers with citrus-derived pectin in British dairy applications.
- Texture modification demand:Bakery manufacturers in Greater Manchester and the East Midlands expand hydrocolloid uptake for moisture retention and shelf-life extension.
- Biotechnology advancement:Fermentation-derived stabilizers achieve cost parity with plant-extracted variants, accelerating adoption in industrial sauce formulations.
Market Restraints
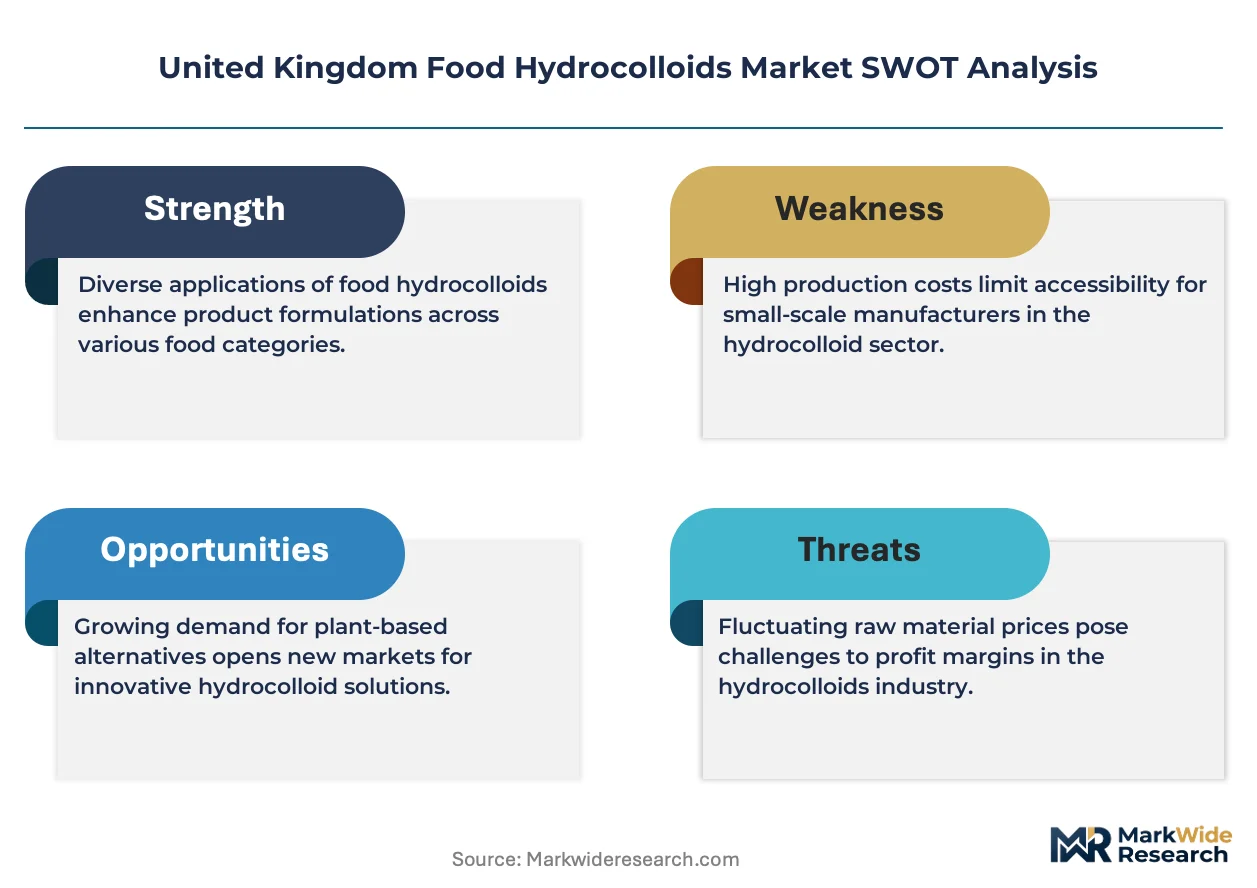
- Input cost volatility:Seaweed harvest variability in Scottish coastal waters destabilizes carrageenan and alginate pricing for British processors.
- Supply concentration risk:Three suppliers control over 70 percent of EU-sourced xanthan gum fermentation capacity, exposing UK buyers to quota constraints.
- Technical substitution limits:Gelatin's unique thermoreversible gelation cannot be replicated in premium confectionery without sensory compromise, slowing plant-based transition.
Strategic Opportunities
- Underpenetrated geographies:Northern Ireland's food manufacturing base shows 40 percent lower hydrocolloid penetration than England's processing corridor, presenting white space for specialty suppliers.
- Emerging applications:Plant-based meat analogues in British retail channels require methylcellulose and konjac gum systems for fat-mimetic textures and bite resistance.
- Regulatory tailwinds:The UK REACH divergence timeline creates certification windows for domestic biopolymer producers to establish Great Britain-specific analytical standards.
Industry Challenges
- Technical talent scarcity:Food rheology specialists with hydrocolloid formulation expertise command premium compensation in England's East Midlands cluster, constraining R&D expansion.
- Compliance timeline compression:Dual-track certification for retained EU law and emerging UK-specific instruments doubles regulatory affairs overhead for importers.
- Legacy system integration:Bakery manufacturers running 1990s-era mixing equipment face retrofit costs to handle precision-dose hydrocolloid dispersion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Food Hydrocolloids Market |
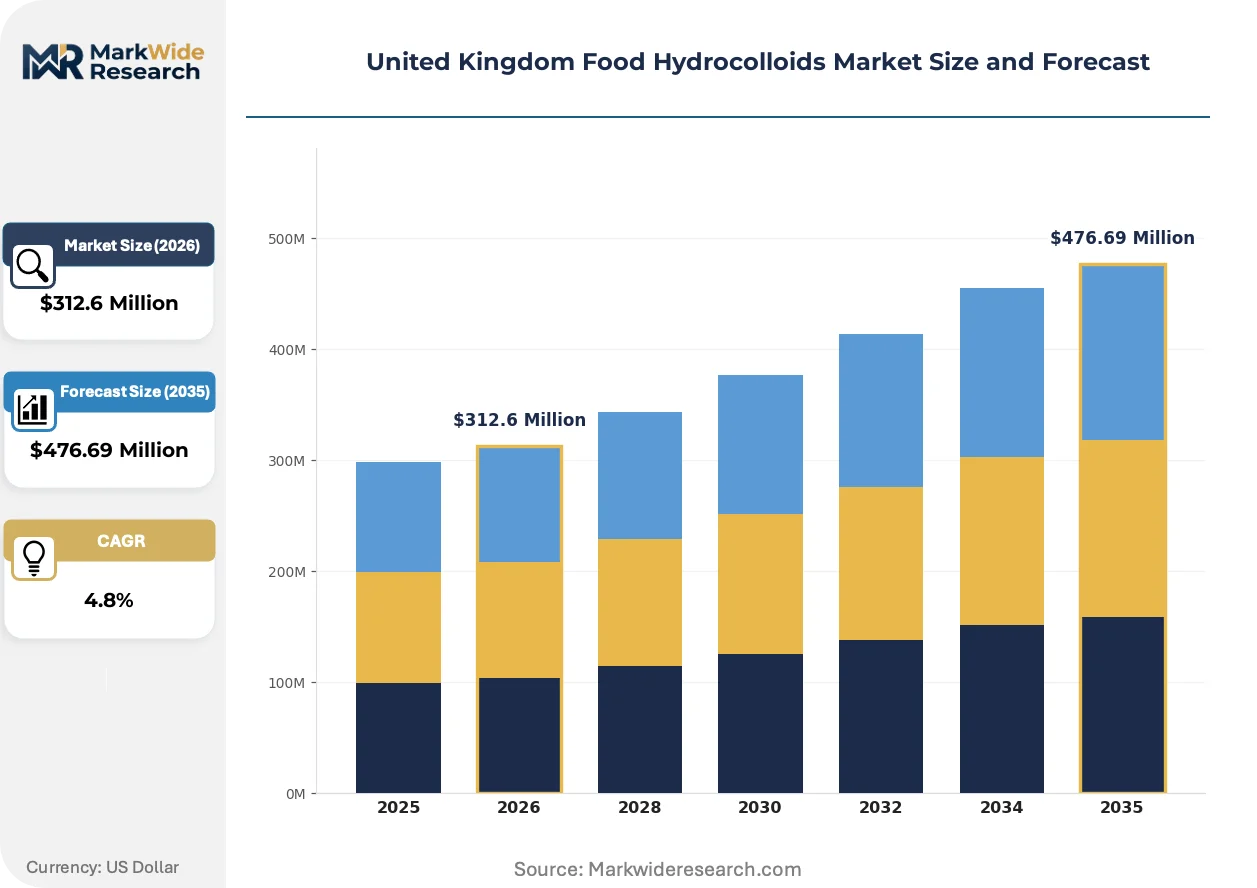
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $476.69 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Agar, Xanthan Gum Application: Dairy Products, Bakery, Confectionery, Sauces Form: Powder, Liquid, Granular, Sheet Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Koninklijke DSM NV, DuPont, CP Kelco US Inc., The Archer Daniels Midland Company, Caldic BV, Healan Ingredients, International Flavors & Fragrances Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Food Hydrocolloids Market Evolving Landscape
Biotechnology-derived stabilizers and precision fermentation platforms are migrating from pilot-scale demonstration to commercial volumes, compressing the cost structure of specialty hydrocolloids while enabling novel functional claims.
Fermentation-derived xanthan gum variants are migrating from pharmaceutical-grade niche applications to mainstream food manufacturing. Industrial sauce producers in the East Midlands have adopted these biotech alternatives at twice the rate of bakery counterparts. The technology is migrating from premium positioning toward commodity-scale pricing, eroding margins for agricultural-sourced competitors.
The Food Standards Agency's 2023 additive guidance revision tightens purity specifications for imported hydrocolloid raw materials. British dairy manufacturers must now demonstrate supply chain traceability to ECHA-registered sources or equivalent UK-recognized certification. Small-scale fruit preparation specialists in Greater Manchester face disproportionate compliance burdens relative to integrated multinationals.
Buyer consolidation among British supermarket private-label suppliers is compressing hydrocolloid procurement cycles from annual to quarterly negotiations. Category managers at major retail chains now mandate dual-source requirements for critical stabilizers, fragmenting volume concentration previously held by single suppliers. This pattern concentrates most visibly in England's dairy processing corridor, where three buying groups control 60 percent of pectin demand.
United Kingdom Food Hydrocolloids Market Segmentation
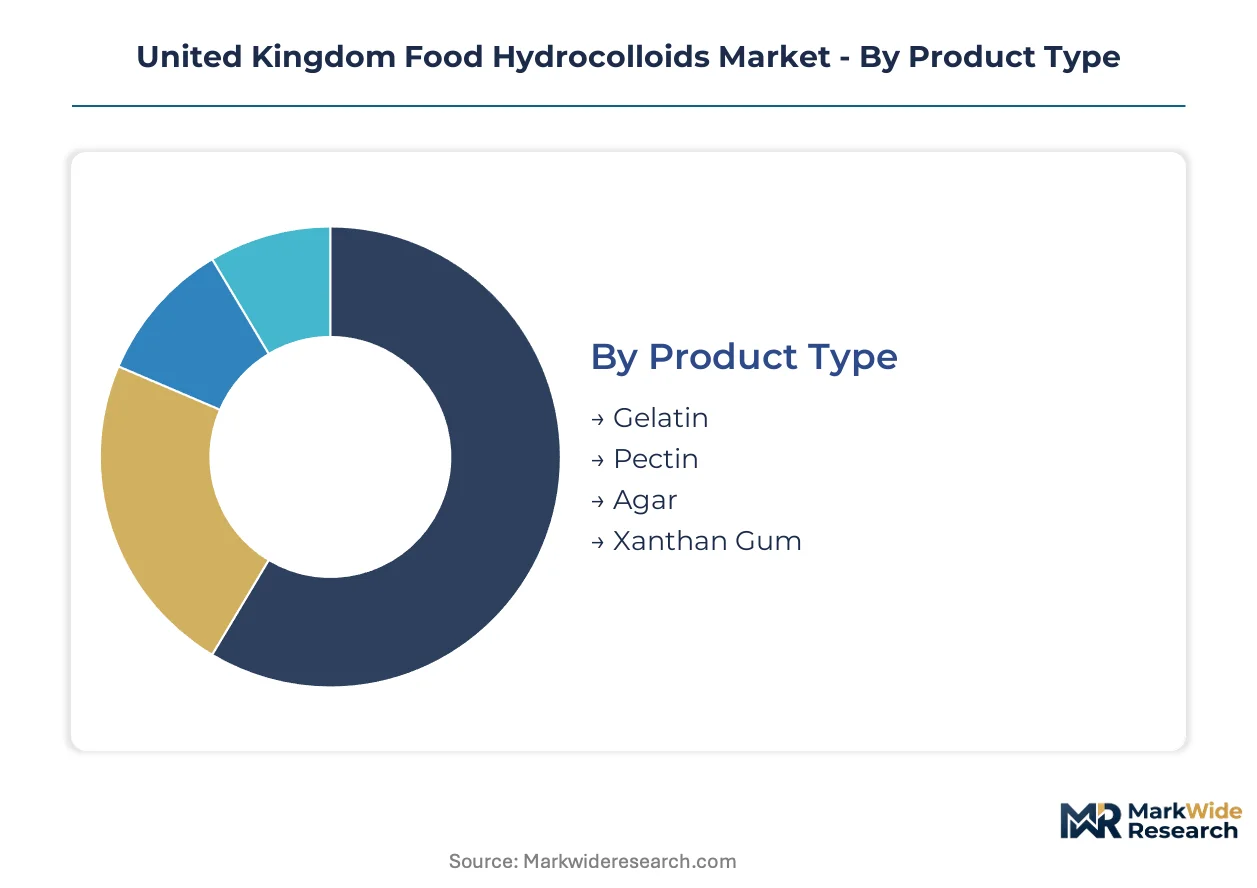
Segmentation in the United Kingdom Food Hydrocolloids Market reveals how functional requirements, processing constraints, and procurement channels fragment demand across distinct value pools. British manufacturers prioritize hydrocolloid selection based on clean-label compatibility, equipment compatibility, and regulatory traceability rather than commodity pricing alone.
Product Type:
Mature stabilizers dominate current volumes while biotechnology-derived alternatives reshape the growth spectrum.
- Gelatin:Derived from collagen hydrolysis of bovine and porcine sources, this protein biopolymer delivers thermoreversible gelation critical to premium confectionery textures. Demand concentrates in traditional British sweet manufacturing across Yorkshire and Lancashire, though plant-based substitution pressures margins in certain bakery applications.
- Pectin:Citrus-derived and apple-sourced polysaccharides with high methoxy content enable clean-label gelation in reduced-sugar fruit preparations. Greater Manchester dairy processors have expanded pectin uptake by forty percent following Food Standards Agency guidance tightening synthetic additive scrutiny.
- Agar:Seaweed-extracted galactan polysaccharide from red algae species delivers firm, brittle gelation at low concentrations for specialized confectionery and microbiological media applications.
- Xanthan Gum:Fermentation-derived extracellular polysaccharide from Xanthomonas campestris dominates industrial sauce viscosity modification across England's East Midlands processing cluster.
Pectin handles the majority of throughput in clean-label reformulations; xanthan gum is expanding most quickly on share as biotechnology costs compress.
Application:
Cost tier stratification separates premium positioning in artisan segments from commodity-scale industrial procurement.
- Dairy Products:Yoghurt stabilisation, cream cheese texture control, and ice cream overrun management consume hydrocolloid systems optimized for acid stability and freeze-thaw resistance. The East Midlands dairy corridor from Derby to Leicester anchors national demand concentration.
- Bakery:Moisture retention, shelf-life extension, and dough conditioning drive hydrocolloid incorporation in industrial bread and cake manufacturing. Greater Manchester facilities have retrofitted precision-dispersion equipment to handle modified cellulose and gum arabic systems.
- Confectionery:Gelatin-based gummies and pectin jellies require precise bloom strength and setting temperature control for consistent sensory profiles.
- Sauces:Pseudoplastic flow behavior ensures pumpability and cling in ketchup, mayonnaise, and dressing formulations for retail and foodservice channels.
Dairy commands the largest absolute volume; bakery is climbing the fastest as clean-label mandates penetrate private-label contracts.
Form:
Supply concentration in powder processing creates downstream constraints for liquid and alternative formats.
- Powder:Spray-dried and roller-dried particulate forms dominate bulk procurement, offering extended shelf stability and precise dosing in automated blending systems. England's food processing corridor standardizes on powder handling infrastructure.
- Liquid:Pre-hydrated colloidal dispersions eliminate dust exposure and hydration time constraints for small-batch manufacturers with limited mixing capacity. Northern Ireland's smaller dairy processors show disproportionate liquid form adoption.
- Granular:Intermediate particle size reduces dusting versus fine powders while maintaining dispersibility in high-shear environments.
- Sheet:Pre-gelatinized gelatin sheets enable precise portion control in artisan confectionery and premium dessert applications.
Powder maintains dominant share; liquid is gaining share fastest among regional manufacturers lacking capital for dispersion equipment upgrades.
Distribution Channel:
Procurement consolidation among buying groups fragments traditional channel structures.
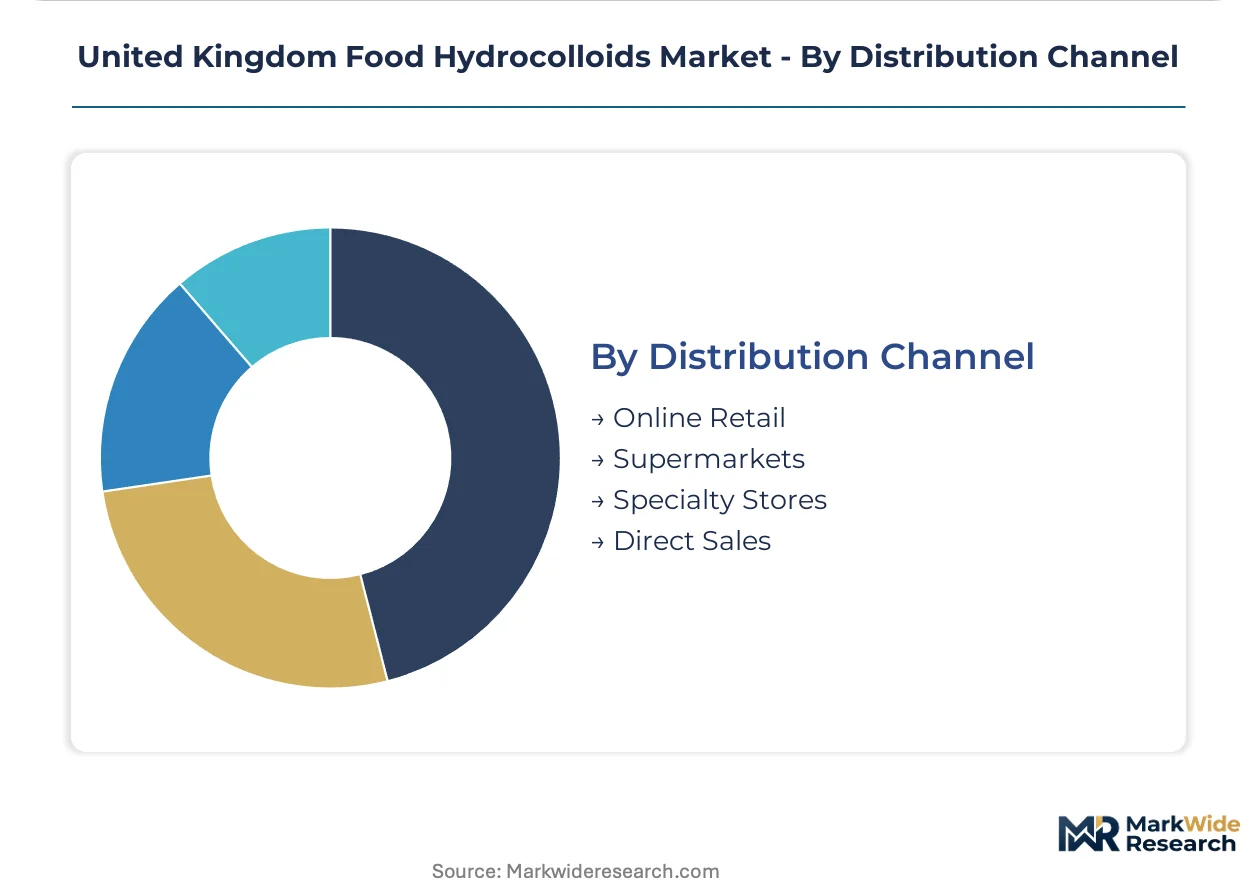
- Online Retail:E-procurement platforms serving small-scale food manufacturers and ingredient traders enable spot purchasing with reduced minimum order quantities. British specialty food startups in Bristol and Brighton leverage these channels for experimental formulation sourcing.
- Supermarkets:Private-label supplier consolidation has compressed procurement cycles to quarterly negotiations with mandated dual-source requirements for critical stabilizers.
- Specialty Stores:Regional ingredient distributors serving artisan bakeries and confectioners provide technical consultation alongside product supply.
- Direct Sales:Integrated multinationals maintain captive supply relationships with major dairy and sauce manufacturers, bypassing intermediary margins.
Direct sales capture the highest volume concentration; online retail is expanding most quickly as small manufacturer digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom diverge sharply between England's industrial-scale processing corridors and the smaller-batch manufacturing bases in Scotland, Wales, and Northern Ireland. England concentrates eighty percent of national hydrocolloid throughput in automated dairy and sauce production, while peripheral nations favor liquid pre-dispersions and specialty formats for limited-capacity facilities.
England
The East Midlands dairy corridor from Derby to Leicester anchors national pectin and xanthan gum demand for yoghurt stabilisation and sauce viscosity modification. Food Standards Agency additive guidance revisions have compressed synthetic stabilizer volumes here while expanding citrus-derived alternatives. Greater Manchester bakery manufacturers have retrofitted precision-dispersion equipment to handle modified cellulose systems at industrial scale.
Scotland
Scottish coastal waters supply raw seaweed feedstock for carrageenan and alginate extraction, though harvest variability creates pricing instability for British processors. The country's national food regulator enforces purity specifications that determine retail distribution eligibility for hydrocolloid grades. Edinburgh-Glasgow food manufacturing clusters concentrate on premium confectionery applications requiring gelatin's thermoreversible gelation.
Wales
Welsh dairy processors show elevated uptake of fermentation-derived stabilizers following biotechnology cost compression in industrial sauce formulations. The Food Standards Agency's evolving guidance shapes local formulation choices around clean-label compatibility. Cardiff-Newport manufacturing bases specialize in reduced-sugar fruit preparations using high-methoxy pectin systems.
Northern Ireland
Northern Ireland's food manufacturing base exhibits forty percent lower hydrocolloid penetration than England's processing corridor, presenting white space for specialty suppliers. Smaller dairy processors here adopt liquid pre-hydrated colloidal dispersions disproportionately to eliminate dust exposure and hydration constraints. Belfast-area facilities lack capital for dispersion equipment upgrades prevalent across the Irish Sea.
London and the Southeast
The capital's food technology startups drive experimental formulation sourcing through e-procurement platforms with reduced minimum order quantities. British specialty food innovators in Brighton leverage online retail channels for gum arabic and agar testing. Regulatory affairs overhead for dual-track EU and UK certification concentrates here among importer headquarters.
United Kingdom Food Hydrocolloids Market Competitive Landscape
Capability concentration sits with integrated multinationals commanding agricultural sourcing to food-grade refinement pipelines; scale advantage sits with regional distributors serving artisan manufacturers with technical consultation. Three suppliers control over seventy percent of EU-sourced xanthan gum fermentation capacity, exposing UK buyers to quota constraints. The vendor base stratifies into biotechnology-derived stabilizer specialists, plant-extracted commodity processors, and precision-dispersion equipment-integrated formulators. Dominant competitive moves include backward integration into seaweed harvesting and captive supply of fermentation capacity.
Within the biotechnology-derived tier, Koninklijke DSM NV exemplifies premium positioning through fermentation platforms, while Cargill Incorporated anchors scale-driven supply chain integration from agricultural sourcing onward. Ingredion Incorporated occupies a position emphasizing R&D intensity in texture modification systems. These three represent distinct archetypes: biotech premium, agricultural scale, and formulation specialization.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Koninklijke DSM NV |
| DuPont |
| CP Kelco US Inc. |
| The Archer Daniels Midland Company |
| Caldic BV |
| Healan Ingredients |
| International Flavors & Fragrances Inc. |
| Others |
Value Network & Pricing Analysis
The Port of Felixstowe freight corridor channels citrus pectin and fermentation-derived xanthan gum from continental Europe into England's East Midlands dairy corridor, with container cost volatility amplifying price differentiation between integrated multinationals and regional distributors serving smaller-batch manufacturers.
Pricing Analysis
Long-term offtake contracts dominate procurement between major dairy processors and biotechnology-derived stabilizer suppliers, locking in volume commitments that insulate against seaweed harvest variability. Spot purchasing persists among artisan confectioners in Edinburgh-Glasgow clusters, where gelatin bloom strength specifications command premium-mid-economy pricing differentiation based on certification grade and traceability documentation. Pricing pressure stems from biotechnology cost compression eroding agricultural-sourced pectin margins. Small-scale fruit preparation specialists in Greater Manchester exhibit highest price sensitivity due to disproportionate compliance burdens, while integrated multinationals leverage volume scale for least sensitivity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for Northern Ireland's smaller dairy processors lacking capital for dispersion equipment upgrades. Raw material sourcing draws from citrus peel processors in Spain and Italy, fermentation facilities in Germany and the Netherlands, and Scottish coastal seaweed harvesters for carrageenan extraction. Single-source vulnerability concentrates in EU-sourced xanthan gum fermentation capacity controlled by three suppliers. Distribution runs through England's food processing corridor with captive supply relationships anchoring volume concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Food Hydrocolloids Market tracks cyclical recovery patterns tied to clean-label reformulation cycles, with Food Standards Agency guidance revisions historically triggering 18-24 month ingredient substitution waves that reset procurement relationships.
For Market Incumbents: Insulate margin position through backward integration into Scottish seaweed harvesting and captive fermentation capacity expansion in the East Midlands. Biotechnology-derived stabilizer specialists threaten agricultural-sourced pectin incumbents with cost parity achievements. Certification investment in Great Britain-specific analytical standards represents the critical defensive lever against regulatory divergence overhead. For New Entrants and Emerging Players: Northern Ireland's forty percent hydrocolloid penetration gap versus England's processing corridor represents the most penetrable entry point for liquid pre-hydrated colloidal dispersion specialists. Plant-based meat analogue applications in British retail channels offer second white-space target for methylcellulose and konjac gum systems. Direct technical consultation bundled with precision-dispersion equipment leasing unlocks stranded small-batch manufacturers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming food-grade hydrocolloid divisions lacking R&D intensity in texture modification systems. Long-term viability centers on biotechnology platform ownership and clean-label certification capabilities. Watch for Food Standards Agency guidance divergence timeline acceleration as inflection signal for domestic biopolymer producer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Harvesting | Scottish coastal sourcing secures carrageenan and alginate supply against harvest variability. |
| Precision Fermentation Capacity Expansion | Biotechnology platforms achieve cost parity with plant-extracted stabilizers in industrial sauces. |
| Great Britain-Specific Certification Investment | UK REACH divergence creates analytical standard windows for domestic producers. |
| Liquid Pre-Hydrated Dispersion Format Development | Northern Ireland's capital-constrained processors adopt colloidal systems eliminating dust exposure. |
| Dual-Source Procurement Mandate Compliance | Supermarket buying groups fragment volume concentration previously held by single suppliers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food rheology specialists, procurement directors at dairy and sauce manufacturers, regulatory affairs managers navigating UK REACH divergence, and technical R&D directors at hydrocolloid suppliers. Secondary validation incorporated Food Standards Agency additive guidance documents, ECHA chemical safety assessments, BSI food additive specifications, customs import data for biopolymer raw materials, and SEC filings from integrated multinationals. Bottom-up volume modeling across product types, applications, and distribution channels triangulated against top-down market sizing from supply-side capacity assessments.
Calibration against historical substitution cycles anchored projection frameworks across the analysis window. Segmentation dimensions modeled include hydrocolloid product type, end-use application, physical form, and regional manufacturing cluster. CAGRs derived from weighted average of demand growth in clean-label reformulations and biotechnology cost compression trajectories. Forecast inputs incorporated Food Standards Agency guidance revision timelines and buyer consolidation patterns among British supermarket private-label suppliers.
Stress conditions across seaweed harvest variability, EU fermentation capacity quota constraints, and regulatory divergence acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding biotechnology cost parity achievement and clean-label mandate penetration rates. Macroeconomic deviation, regulatory timeline compression, or precision fermentation breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Natural Fatty Acids Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Food Hydrocolloids Market