
 Polymer Seals Market | 2026-2036
Polymer Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Seals Market Analytics
Maintenance and refurbishment service contracts are expanding as a revenue layer alongside original equipment sales, shifting vendor economics toward lifetime-value models. SKF Group leverages its bearing-seal bundling infrastructure to capture recurring aftermarket spend across European wind turbine fleets. Freudenberg Sealing Technologies anchors its position through captive material science capabilities in fluoroelastomer compounding. Trelleborg AB competes via marine and offshore specialization where salt-degradation resistance commands premium positioning.
Polymer seals are precision-engineered elastomeric components, typically molded from silicone, fluoroelastomer, or polyurethane compounds with Shore A hardness ratings between 40 and 90, designed to prevent fluid or gas leakage between mating surfaces under pressure, temperature, and chemical exposure. Their primary purpose is ensuring system integrity in dynamic and static applications across fluid power, transportation, and energy infrastructure. O-rings and gaskets dominate volume throughput due to universal interchangeability and low unit cost, while seal kits for hydraulic systems capture disproportionate margin pools through application-specific engineering and certification requirements. Fluoroelastomer formulations lead material value contribution where chemical resistance and thermal stability justify material cost premiums over standard ethylene propylene grades.
REACH compliance in Europe, EPA emissions standards in the United States, and China's GB standards for mechanical sealing products collectively elevate barrier-to-entry for uncertified suppliers while steering formulation chemistry toward lower-toxicity curatives and fillers. These frameworks directly shape material substitution timelines and factory qualification protocols for aerospace and automotive tier-one supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border distribution networks.
Market Dynamics
The EU F-Gas Regulation is compressing permissible leakage thresholds for high-global-warming-potential elastomers, forcing aerospace and automotive tier-one suppliers into accelerated material qualification cycles and captive fluoroelastomer compounding investments.
Growth Catalysts
- REACH compliance mandates:European chemical registration requirements elevate barriers for uncertified suppliers, steering formulation chemistry toward lower-toxicity curatives and consolidating qualified vendor pools.
- Next-generation engine platforms:Aerospace manufacturers in Germany and France are expanding fluorocarbon seal procurement for hydraulic flight control systems serving Toulouse and Hamburg industrial clusters.
- Precision-machined seal kits:Application-specific engineering and certification requirements for hydraulic systems capture disproportionate margin pools through captive technical specifications.
Market Restraints
- Raw material concentration:Fluoroelastomer polymer supply concentrates among a limited set of specialty chemical producers, creating input cost volatility and qualification timeline risk.
- Technical performance ceilings:Standard ethylene propylene grades face substitution pressure in high-temperature aerospace applications where thermal stability requirements exceed material limits.
- Regulatory friction:Divergence between EPA emissions standards in the United States and EU F-Gas Regulation creates stranded inventory risk in cross-border distribution networks.
Strategic Opportunities
- Wind turbine aftermarket:Recurring maintenance and refurbishment service contracts for bearing-seal bundles offer lifetime-value revenue models across European offshore installations.
- Marine specialization premium:Salt-degradation resistance capabilities command pricing power in offshore oil and gas platforms and deep-sea vessel applications.
- GB standards alignment:China's mechanical sealing product regulations create qualification pathways for suppliers meeting dual certification requirements for export markets.
Industry Challenges
- Compounding expertise scarcity:Fluoroelastomer formulation chemistry requires specialized polymer science talent that concentrates among legacy material science departments.
- Factory qualification timelines:Aerospace tier-one supply chain onboarding protocols extend 18-36 months, compressing competitive response windows to specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Seals Market |
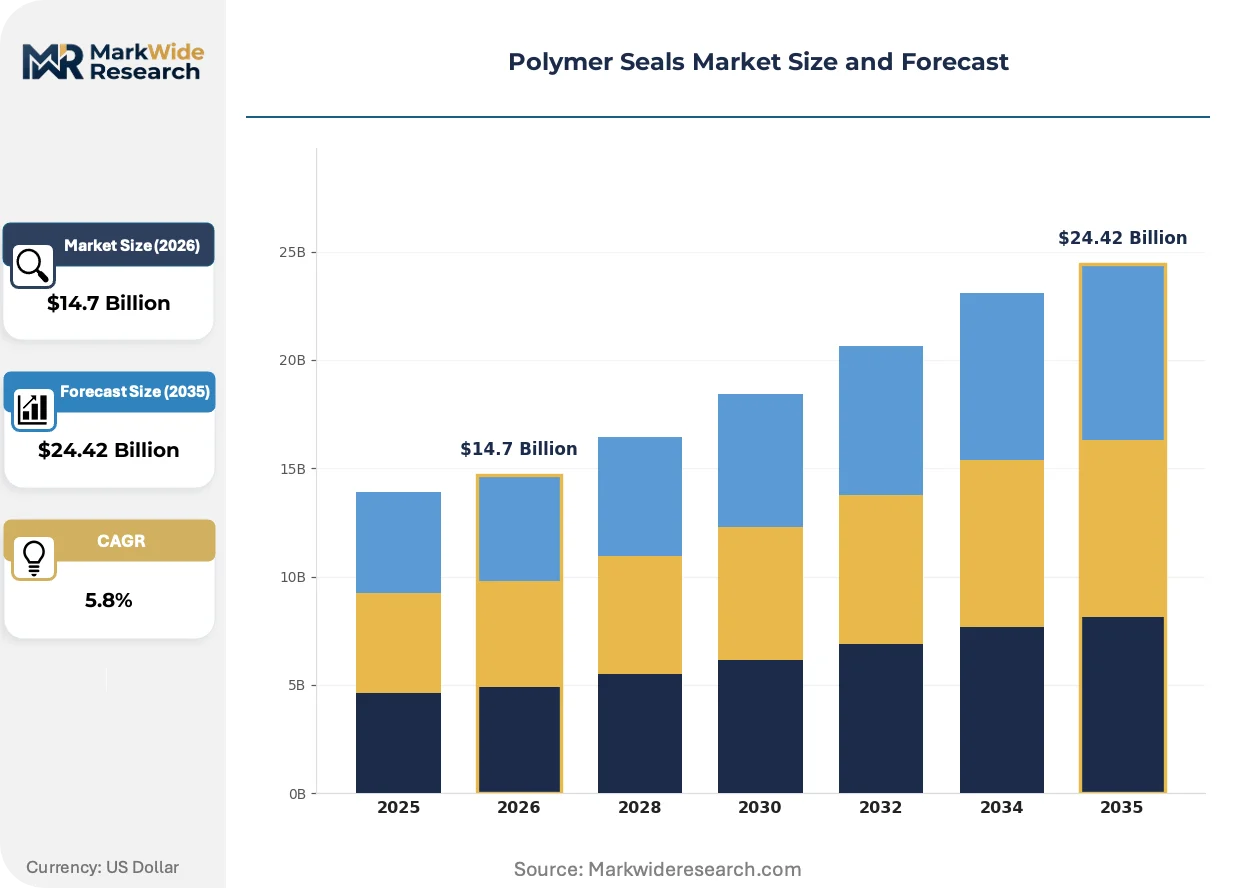
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Seal Kits, Diaphragms Material: Silicone, Fluoroelastomer, Polyurethane, Ethylene Propylene End User: Aerospace, Automotive, Oil & Gas, Food Processing Application: Hydraulic Systems, Pneumatic Seals, Electrical Connections, Water Management |
| Companies Covered | SKF Group, Saint-Gobain S.A., Trelleborg AB, DuPont de Nemours Inc., Eaton Corporation Plc, Freudenberg Sealing Technologies, James Walker Group Ltd., Hutchinson S.A., Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Seals Market Evolving Landscape
Additive manufacturing of seal geometries is reshaping prototyping velocity and low-volume production economics, compressing traditional mold-based lead times and enabling application-specific design iteration without capital-intensive tooling investments.
Perfluoroelastomer formulations with enhanced plasma resistance are decentralizing cleanroom semiconductor manufacturing equipment supply chains, as fabs in South Korea and Taiwan adopt modular seal replacement protocols that reduce downtime-driven revenue loss. Equipment vendors are bundling predictive wear monitoring with seal kits, converting component sales into recurring service relationships.
The EU F-Gas Regulation's tightening leakage thresholds are forcing material substitution toward lower-global-warming-potential elastomers, with aerospace hydraulic system suppliers in France and Germany accelerating qualification of hydrofluoroolefin-based compounds. Tier-one vendors are vertically integrating into captive compounding to protect formulation intellectual property and secure supply continuity.
Aftermarket service unbundling is fragmenting traditional distribution channels, as wind farm operators in Denmark and Germany establish direct technical relationships with seal manufacturers for bearing replacement programs. Procurement teams are negotiating lifetime-value contracts that bundle installation labor with material supply, displacing spot purchasing through industrial distributors.
Polymer Seals Market Segmentation
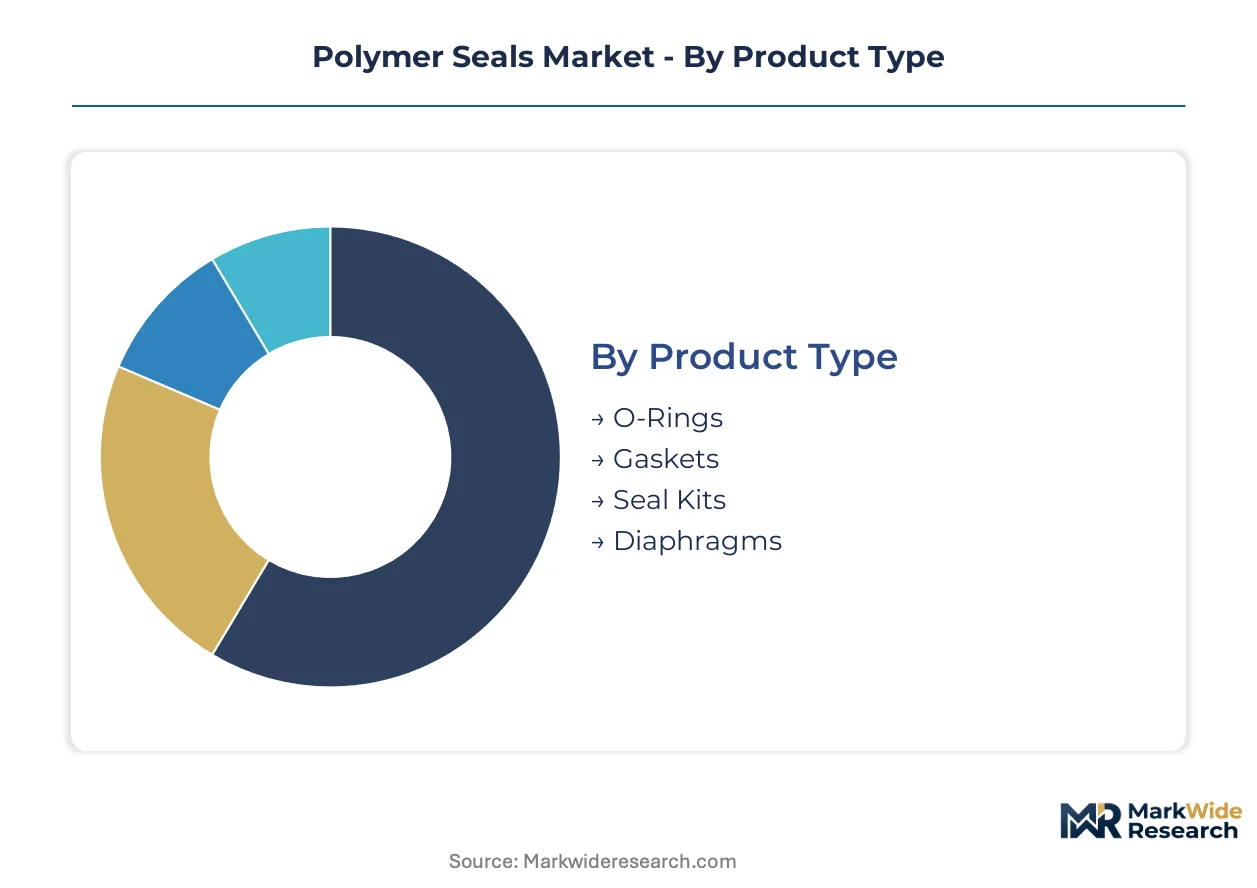
Polymer seal procurement divides sharply between commodity interchangeability and captive specification engineering. Certification burdens cluster in aerospace and semiconductor-adjacent segments where material traceability and factory qualification timelines create vendor stickiness. Understanding where margin pools concentrate versus where volume throughput dominates shapes portfolio allocation decisions.
Product Type:
REACH registration and aerospace tier-one factory qualification requirements concentrate in precision-machined categories, while commodity interchangeability dominates high-volume molded products.
- O-Rings:Circular cross-section elastomeric rings molded from nitrile, silicone, or fluoroelastomer compounds with standardized AS568 dimensional specifications. Demand concentrates in general industrial maintenance across German automotive supplier parks where interchangeability and distributor availability outweigh specification engineering.
- Seal Kits:Application-specific assemblies bundling multiple seal geometries with installation hardware and predictive wear monitoring sensors. Toulouse and Hamburg aerospace clusters drive procurement for hydraulic flight control systems where captive technical specifications and 18-36 month factory qualification timelines protect incumbent positions.
- Gaskets:Flat sealing elements compressed between flange surfaces, typically fabricated from sheet stock or molded for high-volume applications. Food processing equipment manufacturers in France specify platinum-cured silicone grades meeting EU 1935/2004 migration limits.
- Diaphragms:Flexible membranes transmitting pressure or motion while maintaining separation between fluid chambers. Pneumatic control valve manufacturers in Italy specify fabric-reinforced elastomer constructions for process instrumentation.
O-Rings sit at the top of the volume ranking, with Seal Kits climbing the fastest.
Material:
Raw material cost tiers separate commodity elastomers from specialty compounds requiring captive compounding infrastructure and polymer science expertise.
- Fluoroelastomer:High-fluorine-content polymers delivering thermal stability above 200°C and resistance to aggressive hydrocarbon fluids. EU F-Gas Regulation leakage thresholds are accelerating hydrofluoroolefin-based compound qualification in French and German aerospace hydraulic systems.
- Silicone:Polysiloxane elastomers with temperature range flexibility from -60°C to 230°C and low compression set characteristics. Platinum-cured grades command premium positioning in dairy processing equipment serving Danish and Dutch food safety inspection regimes.
- Polyurethane:Cast or injection-molded thermoset elastomers combining abrasion resistance with load-bearing capacity. Mining equipment rebuilders in Western Australia specify castable formulations for hydraulic cylinder rod seals.
- Ethylene Propylene:Saturated polymer chains delivering ozone and weathering resistance at material cost below fluoroelastomer alternatives. Water management infrastructure in Spain and Portugal specifies EPDM for municipal pipeline gasket applications where aromatic hydrocarbon exposure is absent.
Ethylene Propylene dominates unit volume through water management and automotive coolant applications, though Fluoroelastomer captures disproportionate value contribution per kilogram.
End User:
End-use concentration determines whether procurement flows through industrial distributors or direct manufacturer relationships with embedded technical service.
- Aerospace:Hydraulic flight control, fuel system, and landing gear actuation applications requiring FAA/EASA dual certification. Factory qualification protocols in Toulouse and Hamburg industrial clusters extend 18-36 months, compressing competitive response windows.
- Automotive:Powertrain sealing, HVAC compressor, and brake system applications with IATF 16949 quality system mandates. German OEM supplier parks concentrate demand for high-volume molded seals with PPAP submission requirements.
- Oil & Gas:Wellhead, subsea production, and pipeline compression applications where NORSOK M-710 sour gas resistance certification gates supplier participation. North Sea operators in Norway specify perfluoroelastomer grades for high-pressure high-temperature completions.
- Food Processing:Clean-in-place equipment, filling valves, and pasteurization system sealing with EU 1935/2004 and FDA 21 CFR 177.2600 dual compliance. Dairy cooperatives in Denmark negotiate lifetime-value contracts bundling installation labor with material supply.
Automotive sits at the top of the volume ranking, with Aerospace climbing the fastest.
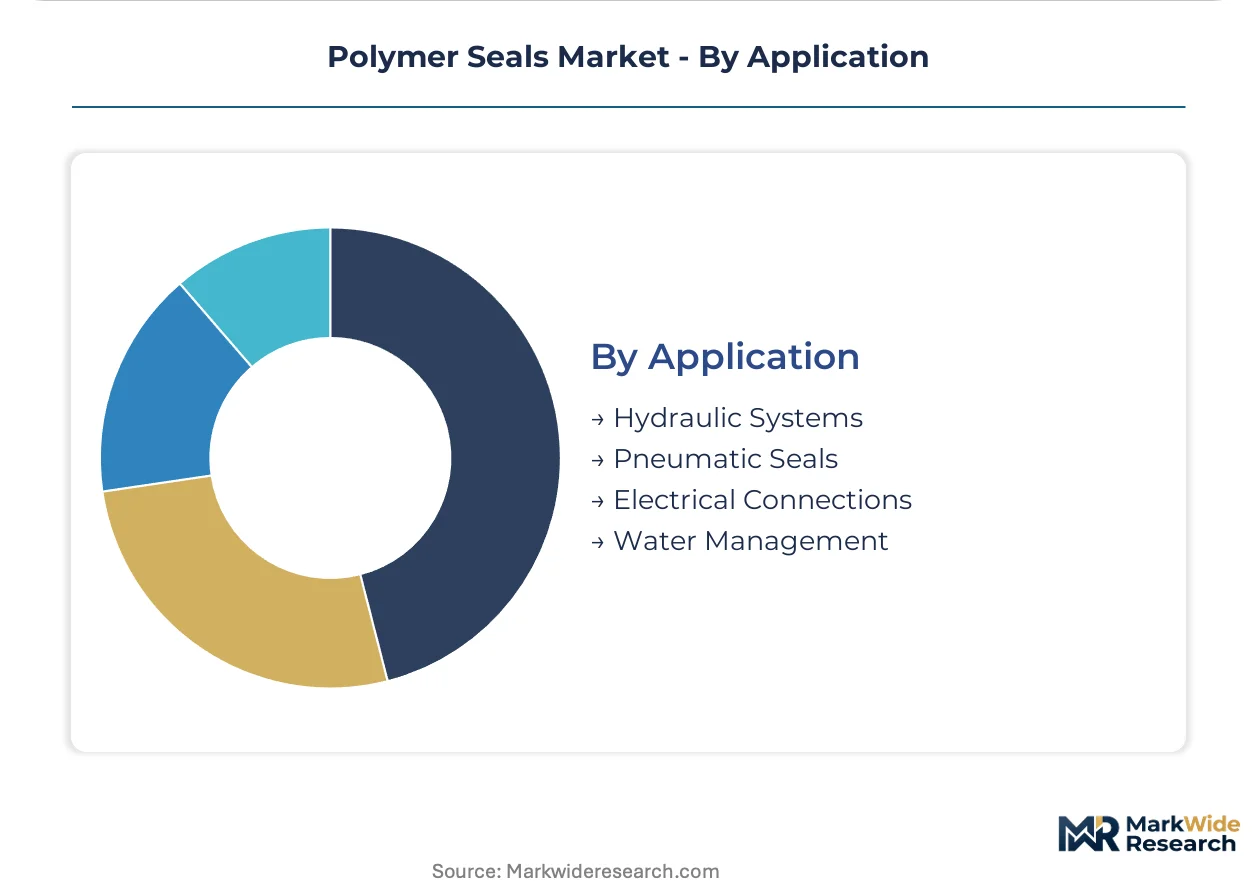
Application:
Dynamic versus static sealing duty cycles determine material selection, hardware integration complexity, and aftermarket service attach rates.
- Hydraulic Systems:Reciprocating rod and piston seals operating under cyclic pressure loading with fluid film lubrication requirements. Precision-machined seal kits for flight control systems serving Toulouse and Hamburg clusters capture disproportionate margin pools through captive specifications.
- Pneumatic Seals:Low-friction dynamic sealing in compressed air systems with minimal lubrication availability. Italian packaging machinery manufacturers specify PTFE-impregnated polyurethane for high-speed cylinder applications.
- Electrical Connections:Environmental sealing of connectors and cable penetrations against moisture and particulate ingress. Offshore wind turbine OEMs in Denmark specify silicone cable glands with 30-year service life ratings.
- Water Management:Static gasket and O-ring applications in municipal distribution and wastewater infrastructure. Spanish water utilities specify EPDM flange gaskets with WRAS approval for potable water contact.
Hydraulic Systems sit at the top of the value ranking, with Electrical Connections climbing the fastest as offshore wind installation scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France outpace other European markets in aerospace-grade seal procurement, while the United States and China anchor divergent demand profiles across energy infrastructure and semiconductor manufacturing equipment.
Germany
Hamburg and Munich aerospace clusters drive fluorocarbon seal procurement for next-generation hydraulic flight control systems. The EU F-Gas Regulation compresses permissible leakage thresholds, forcing accelerated material qualification cycles. Stuttgart automotive supplier parks concentrate demand for high-volume molded seals with IATF 16949 submission requirements.
France
Toulouse aerospace manufacturers expand fluorocarbon seal procurement for engine platforms and landing gear actuation systems. REACH compliance mandates steer formulation chemistry toward lower-toxicity curatives. Lyon and Grenoble industrial zones specialize in food processing equipment seals meeting EU 1935/2004 migration limits.
United States
Houston oilfield service contractors specify perfluoroelastomer grades for high-pressure completions in Permian Basin operations. EPA emissions standards create qualification divergence from European protocols. California semiconductor equipment vendors adopt modular seal replacement protocols for cleanroom manufacturing.
China
Shanghai and Shenzhen semiconductor fabs drive demand for plasma-resistant perfluoroelastomer formulations in etching equipment. GB standards for mechanical sealing products create dual certification pathways for export-oriented suppliers. Western mining equipment rebuilders specify castable polyurethane formulations for hydraulic cylinder applications.
Japan
Nagoya automotive suppliers concentrate procurement for powertrain and brake system sealing applications. METI industrial standards govern material traceability requirements for tier-one supply chain participation. Osaka-based process instrumentation manufacturers specify fabric-reinforced elastomer diaphragms for pneumatic control valves.
Polymer Seals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace and semiconductor-adjacent categories favoring qualified incumbents while automotive maintenance channels tolerate distributor-branded interchangeability. The vendor base concentrates among three strategic archetypes: captive compounders protecting formulation intellectual property, bearing-seal bundlers capturing aftermarket lifetime-value, and marine specialists commanding salt-degradation premiums. Dominant competitive moves include backward integration into fluoroelastomer polymer supply and predictive wear monitoring bundling that converts component sales into recurring service relationships.
Among European material science anchors, SKF Group and Trelleborg AB occupy positions spanning bearing-seal bundling and marine specialization respectively, while Freudenberg Sealing Technologies exemplifies the captive compounding archetype through in-house fluoroelastomer formulation capabilities. These three represent distinct strategic vectors: bundling infrastructure, offshore application focus, and vertical control over polymer chemistry.
| Leading Market Players |
|---|
| SKF Group |
| Saint-Gobain S.A. |
| Trelleborg AB |
| DuPont de Nemours Inc. |
| Eaton Corporation Plc |
| Freudenberg Sealing Technologies |
| James Walker Group Ltd. |
| Hutchinson S.A. |
| Parker Hannifin Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between aerospace-qualified fluoroelastomer seals and commodity O-rings manifests in divergent pricing architectures and procurement channel structures across European and North American supply networks. Premium tiers command five-to-ten-fold unit price multiples over standard grades, with factory qualification timelines and REACH registration costs embedding structural margin protection for incumbent compounders while distributor-branded interchangeability dominates high-volume aftermarket replenishment.
Pricing Analysis
Capacity additions in Chinese polyurethane casting facilities are reshaping price floors for mining and construction equipment seals, compressing margins for European and North American molders serving mid-tier industrial applications. Three-tier pricing structure across aerospace-certified, automotive-qualified, and general industrial grades reflects divergence in material traceability and testing documentation burdens. Cost compression in standard ethylene propylene gasket tiers intensifies because of raw material volatility and distributor consolidation. Wind farm operators exhibit lowest price sensitivity due to lifetime-value contracting models, while general industrial maintenance buyers prioritize distributor availability over specification compliance.
Supply Chain Analysis
Direct-to-OEM channels handle aerospace and semiconductor equipment manufacturer demand through captive technical specifications and 18-36 month factory qualification protocols, while industrial distributors serve spot-replacement procurement for automotive supplier parks and general manufacturing. Fluoroelastomer polymer supply concentrates in Germany, Japan, and the United States among specialty chemical producers with captive compounding infrastructure. Raw material sourcing draws from fluorocarbon feedstock streams, platinum-cured silicone precursors, and castable polyurethane resin systems. Single-source vulnerability in aerospace-grade fluoroelastomer polymer supply creates qualification timeline risk for tier-one suppliers. Distribution runs through authorized distributor networks for commodity grades and direct manufacturer relationships for specification-engineered seal kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in fluoroelastomer compounding capacity, where EU F-Gas Regulation compliance investments in France and Germany create cost differentials against Chinese and Indian suppliers serving less regulated export markets.
For Market Incumbents: To counter raw material concentration risk among specialty fluoropolymer producers, secure captive supply agreements with German and Japanese polymer suppliers while accelerating backward integration into hydrofluoroolefin-based compound development. Factory qualification timeline compression through pre-emptive REACH registration investments protects incumbent positioning against emerging compounders. For New Entrants and Emerging Players: Aftermarket service unbundling in European offshore wind installations represents the most penetrable white-space target, with Danish and German operators seeking direct technical relationships outside traditional distributor channels. Marine and offshore specialization in salt-degradation-resistant formulations offers defensible positioning against bearing-seal bundlers. Go-to-market execution should emphasize predictive wear monitoring integration and installation labor bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where fluoroelastomer formulation expertise concentrates among legacy material science departments with limited succession planning. Long-term viability favors compounders with dual REACH and GB standards certification enabling cross-border supply flexibility. Acquisition target archetypes include mid-cap marine seal specialists with NORSOK M-710 certification and captive silicone compounding capabilities. Watch for EU F-Gas Regulation enforcement acceleration as inflection indicator for material substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoroelastomer Compounding | Protects formulation IP and secures supply continuity against raw material concentration. |
| REACH and GB Standards Dual Certification | Opens cross-border qualification pathways for aerospace and semiconductor export markets. |
| Predictive Wear Monitoring Bundling | Converts component sales into recurring service relationships with wind farm operators. |
| Marine Specialization Capacity Expansion | Captures salt-degradation premium pricing in North Sea and offshore Brazil developments. |
| Long-term Supply Agreement with Polymer Producers | Mitigates single-source vulnerability and stabilizes input cost volatility for tier-one contracts. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with aerospace procurement directors, automotive tier-one supplier quality managers, wind farm maintenance heads, and fluoroelastomer compounding technical directors were validated against secondary sources including ECHA REACH registration databases, EU F-Gas Regulation implementation reports, SEC filings from seal and bearing manufacturers, and customs trade data for fluoropolymer feedstock flows. Triangulation across these sources ensures demand segmentation integrity and supply concentration accuracy.
Historical trendline analysis across material substitution cycles, factory qualification timeline distributions, and aftermarket service contract penetration rates informed the projection framework. Segmentation dimensions modeled include product type precision level, material chemistry tier, end-use certification burden, application duty cycle, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements across the projection horizon. Industry-specific forecast inputs incorporate EU F-Gas Regulation phase-down schedules and semiconductor fab equipment capital expenditure patterns.
Underlying measurement precision varies by segment; aerospace and semiconductor-adjacent categories carry tighter precision than commodity industrial maintenance due to factory qualification documentation availability. Forecasts reflect base-case assumptions regarding regulatory enforcement continuity and raw material supply stability. Periodic stress-testing of base assumptions is recommended against potential acceleration of hydrofluoroolefin-based compound adoption or disruption in specialty fluoropolymer polymer supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
PEKK Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market