
 Thermoplastic Polyamide Elastomer (TPE) Market | 2026-2036
Thermoplastic Polyamide Elastomer (TPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyamide Elastomer (TPE) Market Intelligence
Aftermarket service revenue in polymer compounding is fragmenting as original equipment manufacturers internalize formulation expertise and captive blending operations. BASF SE leverages its Ludwigshafen integrated site to sustain backward integration into polyamide 12 precursors. Arkema S.A anchors its position through specialty Pebax grades that dominate medical catheter applications. Evonik Industries AG competes via high-performance Vestamid E compounds engineered for extreme temperature cycling in powertrain seals.
Thermoplastic polyamide elastomers combine rigid polyamide hard segments with flexible polyether or polyester soft segments through block copolymerization, yielding Shore hardness values from 25D to 70D and continuous service temperatures reaching 150°C for dynamic sealing and flexible tubing applications. TPA grades lead volume consumption in automotive wire jacketing where oil resistance and flex fatigue life are critical specifications. Medical Devices applications represent the fastest-expanding demand pool as US FDA and EU MDR biocompatibility requirements elevate performance barriers against commodity TPU alternatives. Injection Molding technology dominates processing economics for thin-wall components, though 3D Printing adoption is accelerating in patient-specific orthopedic tooling prototypes.
US EPA fuel permeation standards and EU F-Gas Regulation on mobile air conditioning systems are tightening material specifications for under-hood elastomeric components, directly shaping R&D priorities across compounders. REACH substance restrictions and California Proposition 65 litigation risk are forcing substitution of conventional plasticizers with bio-based polyol feedstocks in consumer-facing applications. Stakeholders must monitor evolving automotive electrification thermal management requirements and assess whether existing TPE melt-processing capabilities can adapt to battery pack sealing geometries without capital-intensive retooling.
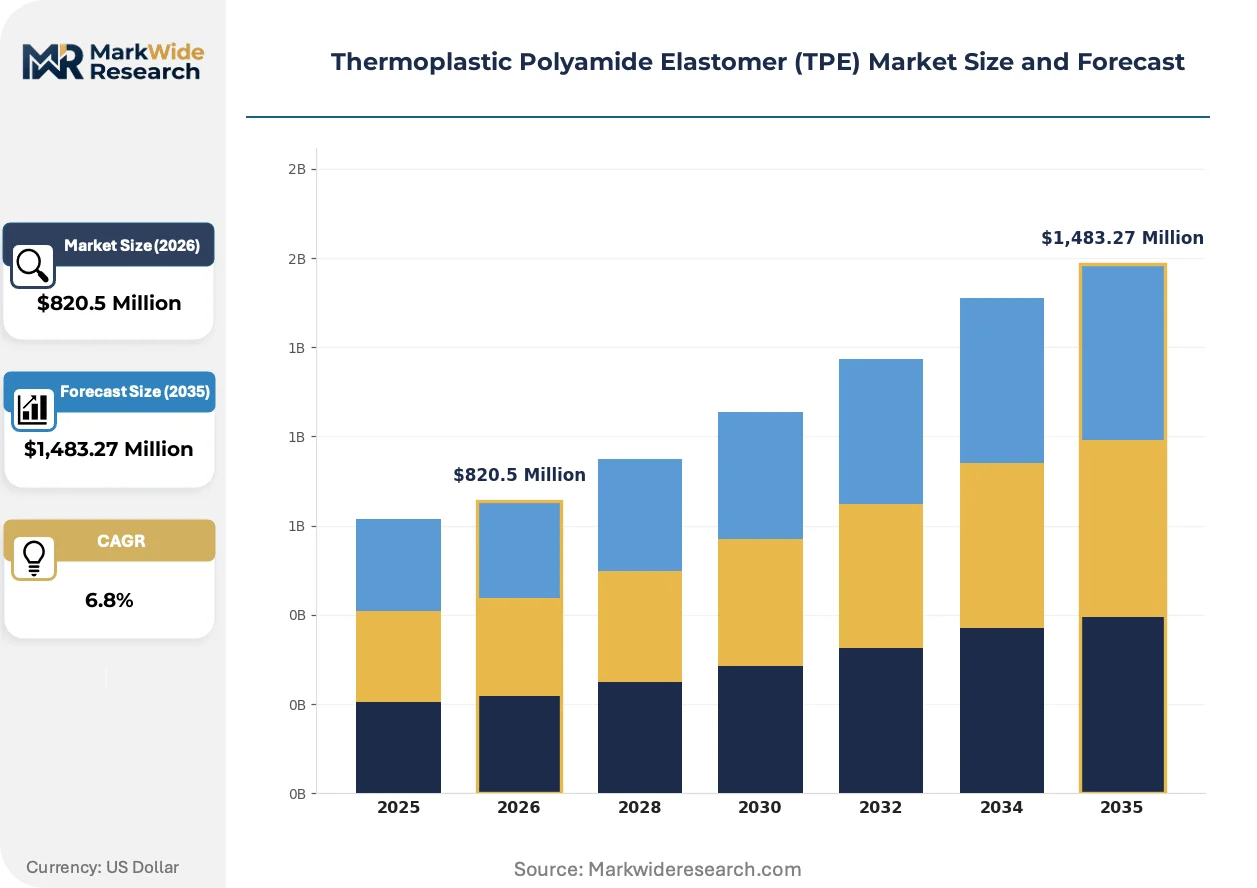
Market Dynamics
Automotive electrification is compressing thermal management specifications for elastomeric sealing systems, forcing compounders to reformulate Shore hardness ranges and continuous service temperature ceilings without retooling existing injection molding assets.
Growth Catalysts
- EU F-Gas Regulation:Mobile air conditioning mandates are elevating specifications for under-hood elastomeric components, pulling higher-performance grades into volume production.
- Medical catheter demand:US FDA and EU MDR biocompatibility requirements are erecting performance barriers that specialty polyamide elastomers clear more reliably than commodity alternatives.
- Stuttgart-Munich corridor concentration:Germany's automotive supplier density creates localized pull for oil-resistant wire jacketing compounds with extended flex fatigue life.
Market Restraints
- Polyamide 12 precursor concentration:Backward integration into lauryl lactam feedstocks limits supplier base to integrated petrochemical majors with caprolactam assets.
- REACH phthalate restrictions:ECHA substance evaluations are forcing emergency reformulation of plasticized compounds, elevating R&D burn rates without immediate volume recovery.
- Commodity TPU substitution:Lower-specification applications in consumer goods face displacement by cost-optimized thermoplastic polyurethane grades with adequate performance envelopes.
Strategic Opportunities
- Battery pack sealing geometries:Electric vehicle thermal management architectures require new gasket profiles that existing TPE melt-processing capabilities can address with die modifications rather than greenfield extrusion lines.
- Bio-based polyol feedstocks:California Proposition 65 litigation risk and REACH restrictions are creating first-mover advantage for compounders with certified renewable soft-segment supply chains.
- Patient-specific orthopedic tooling:3D printing adoption in surgical guide production opens channel for small-batch Pebax-grade powder formulations outside traditional injection molding economics.
Industry Challenges
- Formulation chemistry expertise scarcity:Original equipment manufacturers internalizing compounding capabilities are poaching experienced polyamide-polyether block copolymer specialists from independent compounders.
- EU MDR certification timelines:Extended notified body review periods for medical device material qualifications are freezing inventory commitments and compressing working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyamide Elastomer (TPE) Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TPU, TPA, TPEE, TPI Application: Automotive Components, Medical Devices, Consumer Goods, Industrial Equipment End User: Automotive Manufacturers, Healthcare Providers, Electronics Industry, Consumer Product Companies Technology: Injection Molding, Blow Molding, Extrusion, 3D Printing |
| Companies Covered | EMS-CHEMIE HOLDING AG, LG Chem Ltd, Arkema S.A, Avient Corporation, SABIC, Evonik Industries AG, UBE Industries Ltd, RTP Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyamide Elastomer (TPE) Market Strategic Shifts & Innovations
Material scientists are fusing rigid polyamide hard segments with bio-derived soft segments to satisfy simultaneous thermal performance and sustainability mandates. This convergence is rewriting supplier qualification protocols across automotive and medical procurement organizations.
Polyamide-polyether block copolymer chemistry is hybridizing with renewable feedstock sourcing to create grades that maintain 150°C service ceilings while satisfying corporate Scope 3 reduction targets. Tier 1 automotive suppliers in Germany are qualifying these formulations for under-hood air conditioning seals ahead of 2025 model year refreshes. The technology is hybridizing traditional petrochemical supply chains with agricultural commodity derivatives, compressing the addressable market for conventional fossil-based elastomers.
REACH substance restrictions on phthalate plasticizers are forcing compounders to validate bio-based polyol alternatives through ECHA's substitution assessment framework. The industrial consequence is extended formulation lock periods as suppliers await read-across approvals for novel soft-segment chemistries. Medical device manufacturers face the tightest compliance timelines, with EU MDR technical documentation requiring updated biocompatibility testing for any altered plasticizer package.
Aftermarket service revenue in polymer compounding is fragmenting as OEMs bring formulation expertise in-house through captive blending operations. The traditional distribution channel of independent compounders selling standardized grades is yielding to direct specification relationships between automotive suppliers and integrated petrochemical sites. This pattern concentrates most visibly in Germany's automotive supplier corridor, where Stuttgart-based OEMs now maintain resident chemists at major precursor production facilities.
Thermoplastic Polyamide Elastomer (TPE) Market Segmentation
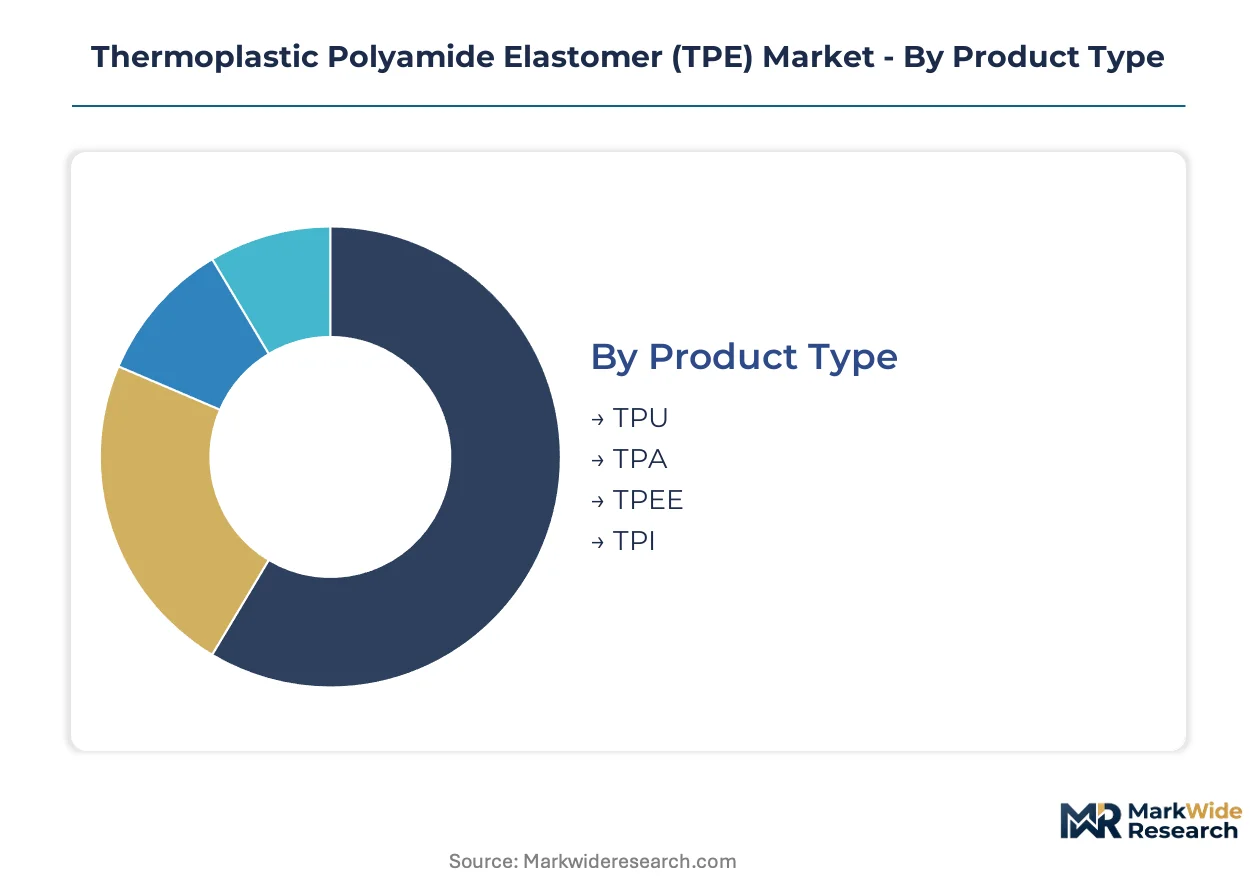
Thermoplastic polyamide elastomers serve divergent performance requirements across automotive sealing, medical tubing, and industrial flex components. Segmentation reveals how Shore hardness ranges, biocompatibility certifications, and melt-processing economics partition addressable demand.
Product Type:
Use-case spectrum spans oil-resistant wire jacketing, catheter-grade flexibility, and high-temperature dynamic seals.
- TPA:Polyamide-polyether block copolymers deliver Shore 25D–70D hardness with 150°C continuous service ceilings. Stuttgart-based automotive suppliers specify TPA grades for under-hood wire jacketing where flex fatigue life determines warranty exposure.
- TPEE:Polyester soft-segment variants trade some low-temperature flexibility for superior chemical resistance and mechanical strength. Industrial equipment manufacturers favor TPEE for hydraulic hose covers and power transmission belting in chemical processing environments.
- TPU:Urethane-based elastomers compete on cost in consumer goods applications with less demanding thermal profiles.
- TPI:Imide-modified grades address niche aerospace and semiconductor fabrication equipment requiring extreme thermal cycling tolerance.
Established volume favors TPA; emerging adoption favors TPEE.
Application:
Cost tier stratification separates specification-grade medical and automotive applications from price-sensitive consumer segments.
- Automotive Components:Under-hood seals, airbag systems, and wire jacketing consume the largest volume share. EU F-Gas Regulation compliance is elevating material specifications for mobile air conditioning elastomeric components.
- Medical Devices:Catheters, surgical tubing, and drug delivery components represent the steepest expansion trajectory. US FDA and EU MDR biocompatibility requirements erect performance barriers that specialty polyamide elastomers clear more reliably than commodity alternatives.
- Consumer Goods:Sporting equipment grips and personal care packaging face displacement pressure from cost-optimized TPU grades.
- Industrial Equipment:Seals, gaskets, and flexible couplings in chemical processing and food handling equipment demand FDA-compliant grades with extractables documentation.
Specification intensity peaks in Medical Devices; volume scale concentrates in Automotive Components.
End User:
Customer type determines procurement modality, with integrated automotive OEMs internalizing formulation expertise while healthcare providers rely on compounder partnerships.
- Automotive Manufacturers:Stuttgart-Munich corridor OEMs maintain resident chemists at precursor production facilities, compressing traditional independent compounder channels.
- Healthcare Providers:Extended EU MDR notified body review periods freeze inventory commitments and compress working capital cycles for material suppliers.
- Electronics Industry:Cable jacketing and connector seals for data centers and telecommunications infrastructure require flame-retardant formulations.
- Consumer Product Companies:REACH phthalate restrictions and California Proposition 65 litigation risk force emergency reformulation of plasticized compounds.
Direct procurement relationships favor Automotive Manufacturers; qualification complexity favors Healthcare Providers.
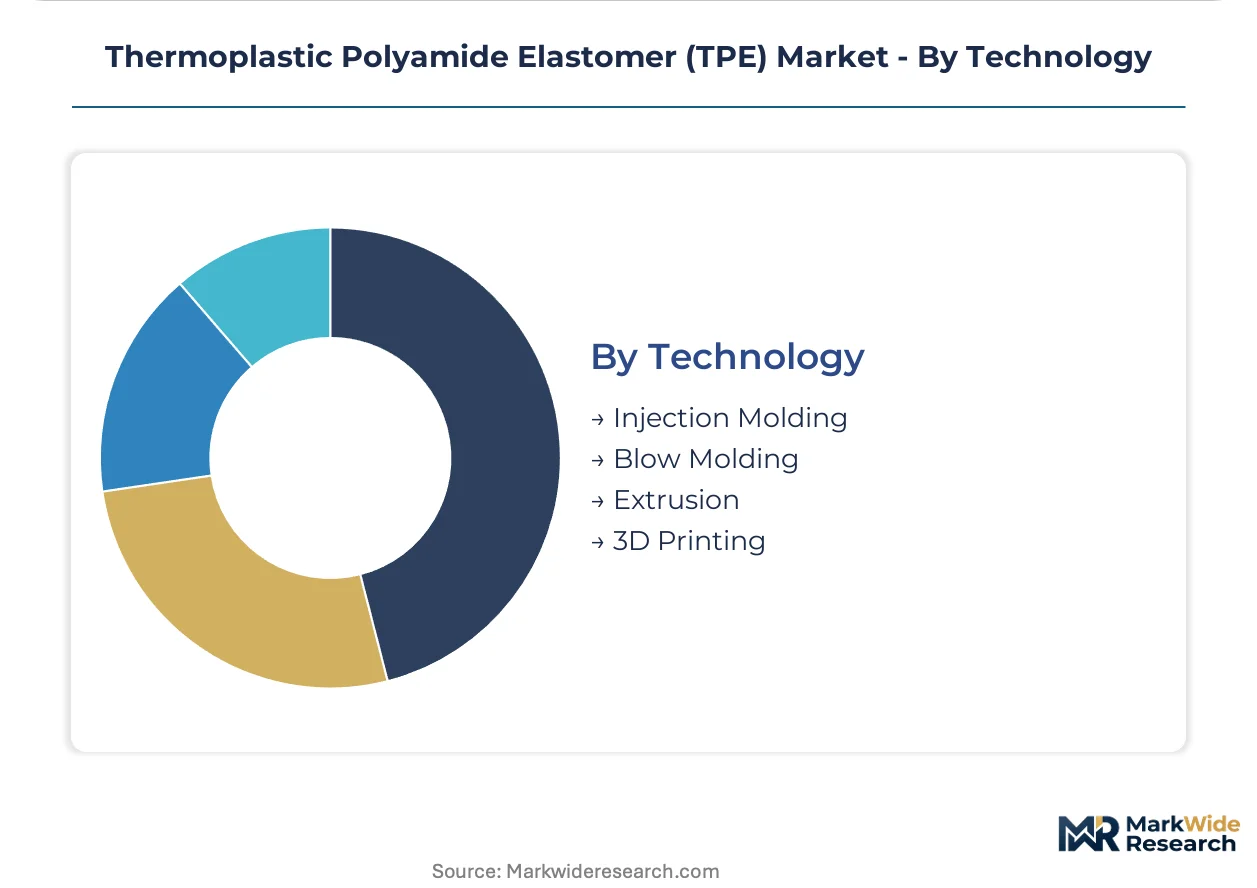
Technology:
Maturity gradient separates high-volume injection molding from emerging additive manufacturing geometries.
- Injection Molding:Dominates thin-wall component economics with cycle times optimized for automotive wire jacketing and medical device housings. Existing assets accommodate battery pack sealing geometries with die modifications rather than greenfield investment.
- Extrusion:Continuous profile production for tubing, sheet, and film applications serving industrial fluid handling systems.
- Blow Molding:Hollow part fabrication for reservoirs, ducts, and expandable bellows in automotive thermal management.
- 3D Printing:Patient-specific orthopedic tooling prototypes open channels for small-batch Pebax-grade powder formulations outside traditional injection molding economics.
Process scale favors Injection Molding; geometric flexibility favors 3D Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification and medical device regulation are creating divergent consumption patterns across major economies. Germany concentrates specification-grade demand through captive OEM-supplier relationships, while the United States channels growth through FDA-cleared medical applications. Asian manufacturing hubs prioritize cost-optimized grades for industrial and consumer segments.
Germany
Stuttgart-based OEMs and Munich-area suppliers drive premium-grade consumption for under-hood sealing and wire jacketing. EU F-Gas Regulation compliance mandates are elevating material specifications for mobile air conditioning components ahead of model year transitions. The automotive supplier corridor maintains resident chemists at precursor production facilities, compressing traditional independent compounder channels.
United States
Medical catheter manufacturers and automotive thermal management suppliers anchor demand growth. US FDA biocompatibility requirements and EPA fuel permeation standards are tightening qualification protocols for elastomeric components. Southeast Michigan automotive engineering centers and Minnesota medical device clusters concentrate specification development activity.
China
Domestic EV battery pack sealing and industrial fluid handling equipment consume volume-grade formulations. MIIT new energy vehicle mandates and GB standards for automotive materials are accelerating localization of supply chains. Yangtze River Delta chemical parks and Pearl River Delta manufacturing zones host compounding operations serving regional automotive OEMs.
Japan
Precision medical tubing and semiconductor fabrication equipment demand ultra-pure grades with extractables documentation. METI carbon neutrality roadmaps and PMDA medical device quality requirements are shaping procurement specifications. Osaka-Kobe industrial corridor and Nagoya automotive supplier networks concentrate technical qualification activity.
South Korea
Battery thermal management systems and electronics cable jacketing absorb growing compound volumes. MFDS medical device regulations and corporate Scope 3 reduction targets are filtering supplier selection criteria. Seoul Capital Area and Busan-Ulsan manufacturing belts integrate TPE sourcing into captive automotive and electronics supply chains.
Thermoplastic Polyamide Elastomer (TPE) Market Key Industry Players
Capability concentration sits with integrated petrochemical majors possessing backward integration into polyamide precursors; scale advantage sits with diversified materials conglomerates serving multiple elastomer chemistries. The market structure splits between three archetypes: precursor-integrated European majors, Asian diversified chemical groups, and North American specialty compounders. Dominant competitive moves include geographic co-location with automotive OEM engineering centers and certification pre-positioning ahead of EU MDR and EPA regulatory deadlines.
Within the precursor-integrated tier, BASF SE and Evonik Industries AG exemplify European majors leveraging caprolactam assets to control feedstock economics. Arkema S.A occupies a specialty position through Pebax-grade formulations serving medical catheter applications. Among Asian diversified producers, LG Chem Ltd and UBE Industries Ltd represent scale-driven competitors with broad elastomer portfolios spanning multiple chemistries and price tiers.
| Leading Market Players |
|---|
| EMS-CHEMIE HOLDING AG |
| LG Chem Ltd |
| Arkema S.A |
| Avient Corporation |
| SABIC |
| Evonik Industries AG |
| UBE Industries Ltd |
| RTP Company |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Undercapacity in European polyamide 12 precursor facilities is tightening supplier leverage and compressing compounder margins, while Stuttgart-based OEMs exploit their resident-chemist relationships to lock in preferential offtake terms ahead of model year transitions. This utilization squeeze concentrates pricing power with integrated majors possessing captive lauryl lactam assets.
Pricing Analysis
Long-term offtake contracts dominate premium-grade TPA supply to automotive OEMs, insulating BASF and Evonik from spot volatility while independent compounders absorb raw material swings on quarterly resets. Price differentiation rests on FDA/MDR biocompatibility certification tiers and volume scale commitments, with medical catheter grades commanding substantial premiums over industrial formulations. Cost compression in consumer-facing TPU-substitutable tiers is intensifying because REACH phthalate reformulation expenses cannot be passed to price-sensitive buyers. Healthcare providers exhibit lowest price sensitivity due to qualification lock-in, while consumer product companies face acute displacement risk from commodity alternatives.
Supply Chain Analysis
Contract manufacturing concentration sits with EMS-CHEMIE and RTP Company holding specialized compounding capacity for thin-wall medical components and automotive wire jacketing. Geographic supply concentration centers on Germany, China, and the United States, with Ludwigshafen and Stuttgart anchoring European precursor-to-compound integration. Raw material dependencies draw from caprolactam feedstocks, bio-based polyol alternatives, and specialty additive packages. Single-source vulnerability around lauryl lactam intermediates creates exposure to petrochemical major production decisions. Distribution runs through direct OEM-supplier relationships in automotive, bypassing traditional independent compounder channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as battery pack sealing geometries standardize around interoperable thermal management architectures, creating winner-take-most dynamics for compounders with pre-qualified melt-processing capabilities.
For Market Incumbents: Entrench backward integration into polyamide 12 precursors through Ludwigshafen-style integrated sites, locking in feedstock economics against commodity TPU substitution threats. Prioritize EU MDR certification pre-positioning ahead of notified body queue congestion, converting regulatory delay into competitive moat. Channel control through resident-chemist programs at Stuttgart OEM engineering centers compresses independent compounder access.
For New Entrants and Emerging Players: Build out bio-based polyol formulation capabilities to exploit California Proposition 65 litigation risk and REACH substitution mandates, capturing first-mover advantage in renewable soft-segment supply chains. Patient-specific orthopedic tooling via 3D-printed Pebax-grade powders offers the most penetrable white-space, operating outside injection molding scale economics. Go-to-market should target Minnesota medical device clusters with powder-bed fusion partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty-materials consolidation play because automotive electrification and medical regulation are simultaneously elevating performance barriers and compressing the viable supplier base. Acquisition targets should display captive precursor relationships or FDA/MDR pre-certification assets. The signal to watch is EU MDR notified body approval velocity—accelerating clearances would unlock inventory commitment cycles and working capital recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide 12 Precursors | Ludwigshafen-style integrated sites control lauryl lactam feedstock economics against supply disruption. |
| EU MDR Certification Pre-Positioning | Extended notified body timelines freeze competitor inventory commitments and compress working capital cycles. |
| Bio-Based Polyol Supply Chain Development | REACH substitution assessments and California Proposition 65 litigation create first-mover certification advantage. |
| 3D Printing Powder Formulation Launch | Patient-specific orthopedic tooling opens channels outside traditional injection molding scale economics. |
| Resident Chemist Programs at OEM Engineering Centers | Stuttgart-based automotive suppliers internalize formulation expertise and bypass independent compounder channels. |
Research Approach
Cross-validation between primary interviews with polyamide elastomer plant managers, automotive Tier 1 procurement leads, medical device regulatory affairs directors, and distribution channel partners anchors the qualitative findings against secondary validation. Secondary sources include ECHA substance restriction databases, FDA 510(k) filings, EU MDR technical documentation, customs/trade data for polyamide precursor flows, and SEC 10-K disclosures from integrated petrochemical majors. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Calibration against historical volume trajectories in automotive wire jacketing and medical catheter applications informs the analytical framework. Segmentation dimensions span hardness grade tier, end-use industry, certification level, processing technology, and regional production cluster. CAGRs derive from elasticity-adjusted demand modeling incorporating automotive electrification thermal management specifications and EU F-Gas Regulation compliance timelines. Industry-specific inputs include battery pack sealing geometry adoption curves and 3D printing powder formulation commercialization rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian diversified chemical groups or accelerated FDA/MDR approval pathways would shift outcomes beyond modeled ranges. Quarterly review of EU MDR notified body queue lengths, REACH substitution assessment read-across decisions, and automotive OEM thermal management architecture standardization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Global UV Curable Resins Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
EVA Foam Market