
 Polymer Processing Aid (PPA) Market | 2026-2036
Polymer Processing Aid (PPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Processing Aid (PPA) Market Outlook
Aftermarket technical service revenue is tilting toward formulation customization and on-site extrusion troubleshooting rather than commodity product sales. Arkema S.A. leverages its fluoropolymer heritage to anchor high-performance PPA supply for demanding multilayer film applications. Solvay S.A. sustains competitive position through backward integration into fluorinated raw materials and captive monomer supply. 3M Company differentiates via proprietary dispersion technologies that reduce dosage rates in polyolefin processing.
Polymer Processing Aid denotes a class of additives, typically fluorinated elastomers or silicone-based compounds at 0.01–0.1% loading levels, that migrate to metal die surfaces during extrusion to eliminate sharkskin melt fracture and reduce pressure buildup in blown film lines. The primary industrial purpose centers on enabling higher throughput rates, improved surface aesthetics, and reduced energy consumption in polyethylene and polypropylene conversion. Powder formulations dominate current volume shipments due to ease of dry blending with resin pellets, while liquid concentrates represent the fastest-expanding form category as compounders seek automated dosing systems and reduced dust exposure. Among end-use industries, packaging applications command the largest absolute consumption, though automotive interior film specifications are emerging as a concentrated margin pool where OEM scratch-resistance standards elevate technical barriers.
EPA oversight of per- and polyfluoroalkyl substances under TSCA Section 5 premanufacture notification rules is constraining fluorinated PPA introductions in the United States, while REACH authorization requirements in Europe are accelerating substitution research toward polymerized wax and glycerol ester alternatives. FDA food-contact clearance under 21 CFR 177.1520 remains the decisive market-access gate for suppliers targeting polyethylene film for direct food packaging applications. Stakeholders must monitor regulatory divergence between jurisdictions and align R&D portfolios with emerging fluorine-free performance benchmarks before compliance deadlines harden into procurement requirements.
Market Dynamics
Fluorinated PPA phase-out mandates across major jurisdictions are forcing formulation chemists to rebuild performance benchmarks from molecular foundations rather than incremental adjustments.
Growth Catalysts
- Blown film throughput pressure:Packaging converters in Germany's Rhine corridor demand higher line speeds to amortize capital-intensive extrusion equipment, pulling fluorine-free PPA adoption ahead of compliance deadlines.
- EU F-Gas Regulation:The 2024 tightening of fluorinated greenhouse gas controls accelerates substitution research toward polymerized wax and glycerol ester chemistries for polyethylene film applications.
- Automotive interior specifications:OEM scratch-resistance standards for polypropylene dashboard films create concentrated demand for high-performance processing aids with optical clarity retention.
Market Restraints
- Fluorinated raw material concentration:Captive supply of tetrafluoroethylene monomer sits with integrated chemical majors, constraining independent PPA producers from matching performance-tier pricing.
- REACH authorization timelines:ECHA's substance evaluation procedures for novel fluorine-free candidates extend commercialization cycles by 18-36 months versus legacy fluoropolymer registrations.
- Silicone-based substitution limits:Polydimethylsiloxane alternatives exhibit plate-out accumulation in long production runs, restricting their viability in continuous blown film operations.
Strategic Opportunities
- India packaging expansion:FSSAI food-contact clearance pathways for polyethylene film additives remain underexploited by Western suppliers despite accelerating domestic blown film capacity installation.
- Liquid concentrate automation:Automated dosing systems in compounder operations favor liquid PPA formats over powder, creating margin expansion through value-added formulation services.
- Japan automotive film:METI carbon-neutral material mandates for vehicle interiors elevate technical specifications where premium PPA performance commands price premiums.
Industry Challenges
- Formulation chemist scarcity:Expertise in fluoropolymer-to-hydrocarbon transition chemistry concentrates among retiring specialists at major additive houses, constraining R&D velocity.
- FDA 21 CFR 177.1520 clearance duration:Food-contact notification reviews for novel PPA chemistries extend 14-22 months, compressing commercialization windows against regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Processing Aid (PPA) Market |
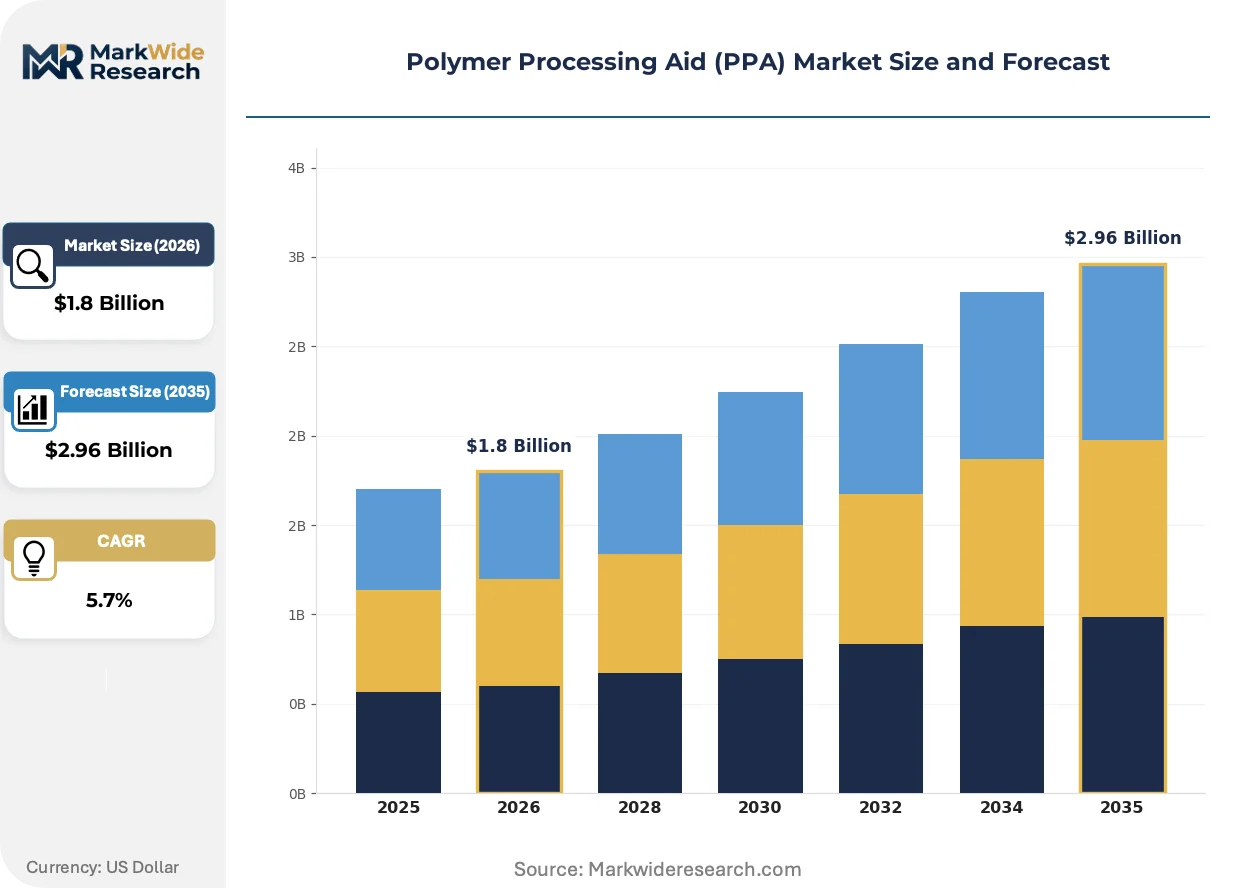
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amides, Esters, Glycerol, Fatty Acids End Use Industry: Automotive, Packaging, Construction, Consumer Goods Form: Powder, Granules, Liquid, Concentrate Application: Extrusion, Injection Molding, Blow Molding, Coating |
| Companies Covered | Arkema S.A., Solvay S.A., 3M Company, LyondellBasell Industries N.V., Clariant AG, BASF SE, Mitsubishi Chemical Corporation, Avient Corporation, The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Processing Aid (PPA) Market Strategic Shifts
Formulation chemistry is pivoting from incremental fluoropolymer optimization toward molecular architecture redesign, with dispersion technology and bio-derived backbones emerging as parallel innovation vectors.
Polymerized wax processing aids with controlled molecular weight distribution are rendering obsolete conventional low-density polyethylene waxes in high-clarity film applications. Korean and Taiwanese packaging converters adopted these materials aggressively through 2023-2024. The shift compresses dosage rate requirements by 40-60% versus legacy chemistries, restructuring supplier value capture toward formulation expertise over commodity volume.
EPA TSCA Section 5 premanufacture notification rules for per- and polyfluoroalkyl substances now require 90-day review periods for fluorinated PPA introductions in the United States. The industrial consequence is a hard bifurcation between grandfathered fluoropolymer formulations and novel substance development pipelines. Food packaging film producers are responding by dual-sourcing fluorinated and fluorine-free grades to hedge against authorization denial risks.
Converters increasingly unbundle technical service contracts from product supply, paying separately for on-site extrusion troubleshooting and die design optimization. This procurement model change disrupts traditional distributor relationships that bundled advisory support with volume rebates. The pattern is most visible in Germany's automotive supply chain, where OEM audit requirements demand documented process validation support that commodity distributors cannot provide.
Polymer Processing Aid (PPA) Market Segmentation
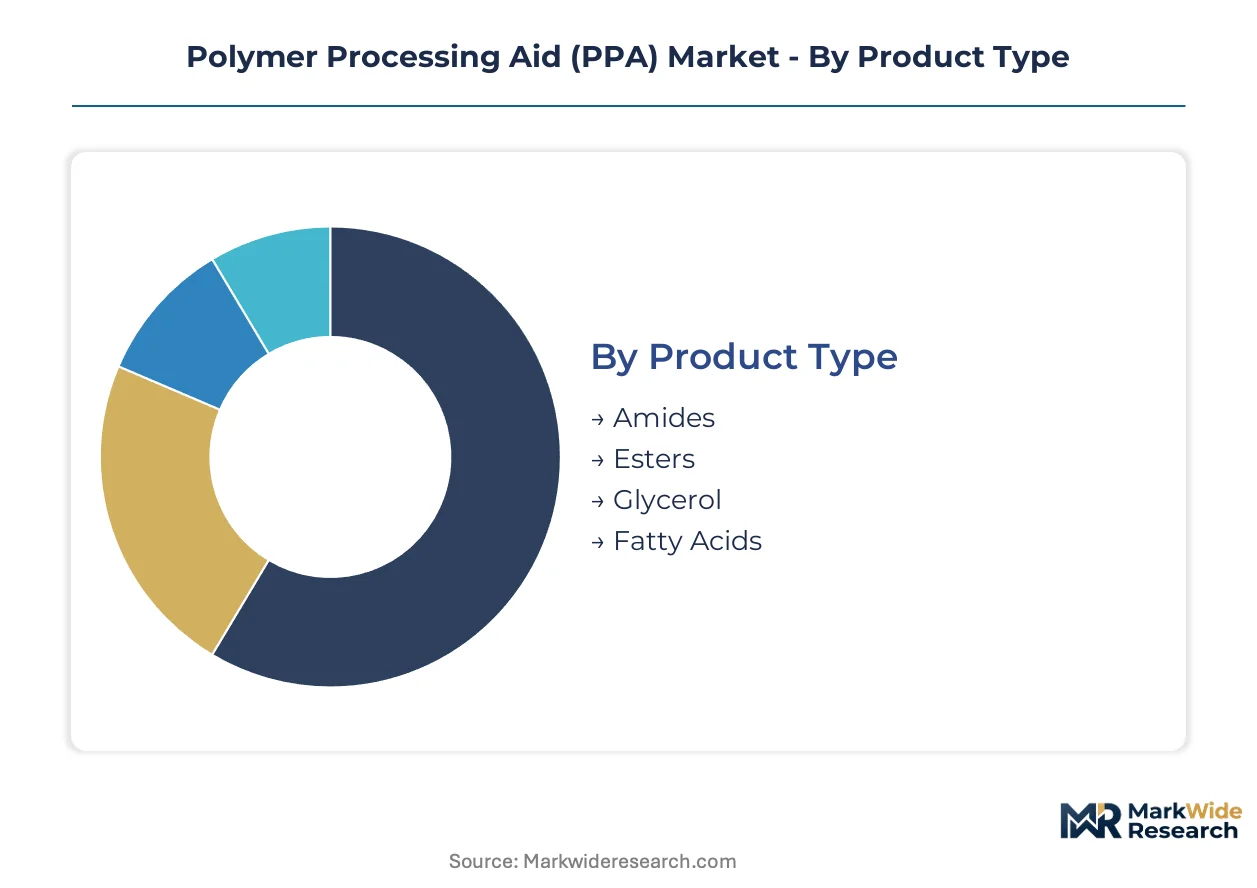
PPA segmentation reveals how formulation chemistry, physical form, and conversion process requirements intersect to determine supplier value capture. Understanding these dimensions clarifies why fluorine-free transitions concentrate in specific product categories while legacy technologies retain position in others.
Product Type:
Cost tier differentiation separates commodity fatty acid derivatives from performance-engineered amide structures in converter procurement decisions.
- Amides:Primary amide and secondary amide chemistries dominate high-throughput blown film lines through controlled surface migration rates. Demand clusters in Germany's Rhine corridor packaging clusters where EU F-Gas Regulation compliance deadlines accelerate substitution from fluorinated alternatives.
- Esters:Glycerol ester and polyol ester formulations deliver optical clarity retention in multilayer polyethylene films for food packaging. Korean and Taiwanese converters adopted these materials aggressively as dosage-efficient replacements for conventional wax-based systems.
- Glycerol:Bio-derived glycerol backbones serve sustainability-mandated automotive interior specifications where METI carbon-neutral material requirements elevate technical barriers.
- Fatty Acids:Saturated fatty acid derivatives function as cost-optimized processing aids in commodity polypropylene extrusion with limited performance demands.
Amides hold installed capacity. Esters is rotating up the share rankings.
End Use Industry:
Application-driven performance specifications create divergent margin pools across converter segments with distinct regulatory exposure profiles.
- Automotive:Polypropylene dashboard and interior film applications demand scratch-resistance retention under OEM validation protocols. Japan's METI carbon-neutral mandates and German OEM audit requirements concentrate premium PPA procurement in these supply chains.
- Packaging:Blown film and cast film extrusion for food-contact polyethylene represents the largest absolute volume consumption. FDA 21 CFR 177.1520 clearance requirements and FSSAI pathways in India structure supplier access decisions.
- Construction:Pipe extrusion and geomembrane applications utilize processing aids for surface finish optimization in high-density polyethylene systems with less stringent optical specifications.
- Consumer Goods:Injection-molded polypropylene articles for household applications deploy commodity-grade additives where cost minimization dominates formulation selection.
Packaging commands volume concentration. Automotive is climbing the fastest as a margin pool.
Form:
Physical delivery format determines dosing automation compatibility and workplace exposure compliance in compounder operations.
- Powder:Dry-blend compatible powder formulations dominate current shipment volumes through established handling infrastructure and cost efficiency in manual batch operations.
- Granules:Dust-free pelletized forms serve automated compounding lines in large-scale polyethylene resin production with integrated additive dosing systems.
- Liquid:Pump-dispersed liquid systems enable precise metering in continuous extrusion with reduced airborne particulate exposure. Automated dosing system adoption in compounder operations favors this format's expansion trajectory.
- Concentrate:High-loading masterbatch concentrates minimize transport costs and inventory footprint for remote converter locations with limited on-site formulation capability.
Powder holds installed capacity. Liquid is gaining share fastest through automation adoption.
Application:
Conversion process mechanics dictate shear stress profiles and residence time requirements that filter compatible PPA chemistries.
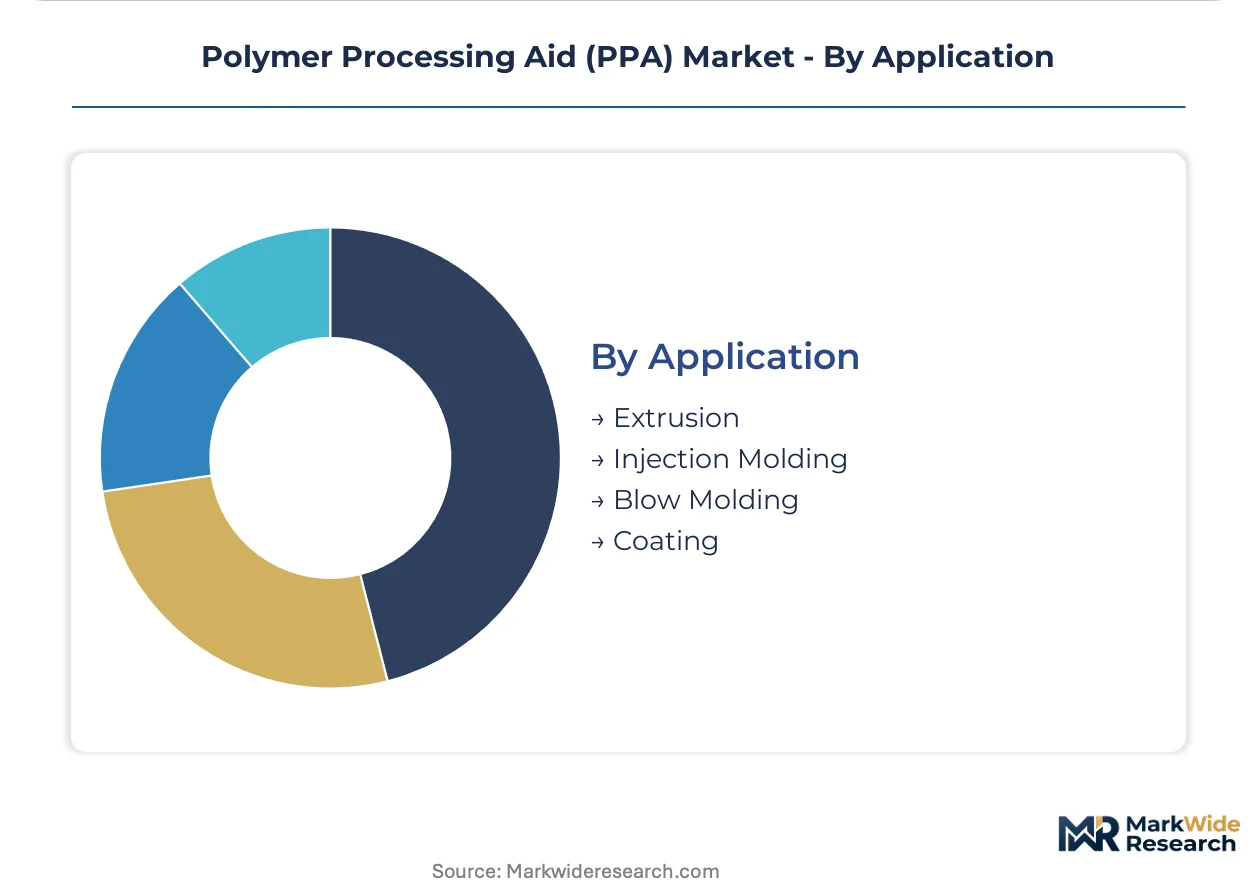
- Extrusion:Blown film and sheet extrusion lines generate the primary demand pull for sharkskin suppression and die pressure reduction. Germany's automotive and food packaging supply chains anchor this segment's technical specification intensity.
- Injection Molding:High-shear filling phases in thin-wall polypropylene molding utilize processing aids for flow enhancement and mold release optimization with cycle time reduction objectives.
- Blow Molding:Parison stability and surface aesthetics in polyethylene bottle production drive moderate PPA loading with emphasis on lot-to-lot consistency.
- Coating:Extrusion coating of paper and foil substrates employs specialized low-volatility formulations to prevent plate-out on chill roll surfaces during continuous operations.
Extrusion holds installed capacity. Injection molding is rotating up the share rankings through thin-wall packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes PPA formulations with heavier fluorine-free loading than other major markets, while India and the United States maintain bifurcated procurement portfolios hedging against regulatory divergence.
Germany
Blown film extruders along the Rhine corridor demand amide-based PPA systems to meet EU F-Gas Regulation phase-out deadlines ahead of schedule. ECHA authorization timelines for novel chemistries extend commercialization cycles, forcing converters to validate polymerized wax alternatives early. Automotive OEM clusters in Stuttgart and Munich drive premium-grade consumption for polypropylene dashboard specifications.
United States
Food packaging film producers in the Gulf Coast petrochemical belt dual-source fluorinated and fluorine-free grades to manage EPA TSCA Section 5 review risks. FDA 21 CFR 177.1520 clearance requirements structure supplier access decisions for direct food-contact applications. Houston-area compounders are automating liquid concentrate dosing systems to reduce workplace dust exposure.
China
Packaging converters in the Yangtze River Delta region deploy PPA additives to sustain throughput rates on capital-intensive blown film lines serving export markets. SAMR food-contact regulations and evolving GB standards for plastic additives shape formulation selection criteria. Shanghai-based resin compounders are expanding liquid masterbatch capacity to serve automated dosing adoption.
India
Domestic blown film capacity installation in Maharashtra and Gujarat is accelerating ahead of FSSAI food-contact clearance pathway maturation. BIS certification requirements for polyethylene film additives create technical barriers for unvalidated imports. Mumbai-Pune industrial corridor converters are trialing glycerol ester formulations for sustainability-mandated export contracts.
Japan
Automotive interior film specifications from Toyota and Honda suppliers elevate technical barriers for PPA performance under METI carbon-neutral material mandates. JIS standards for vehicle interior emissions compatibility filter supplier qualification. Nagoya-area polypropylene processors command price premiums for scratch-resistance retention in dashboard applications.
Polymer Processing Aid (PPA) Market Competitive Environment
Capability concentration sits with integrated fluoropolymer heritage players; scale advantage sits with diversified chemical majors with captive resin supply. The vendor base stratifies across three tiers: heritage fluoropolymer specialists with backward integration into tetrafluoroethylene monomer, diversified additive houses with formulation service bundling, and regional compounders competing on logistics proximity. Dominant competitive moves include portfolio diversification toward fluorine-free chemistries and geographic expansion through technical service center establishment in high-growth packaging corridors.
Among heritage-integrated specialists, Arkema S.A. and Solvay S.A. occupy positions anchored by fluoropolymer manufacturing legacies, while 3M Company exemplifies the dispersion technology differentiation archetype. These three represent distinct competitive vectors: captive raw material control, formulation customization depth, and proprietary delivery system engineering respectively.
| Leading Market Players |
|---|
| Arkema S.A. |
| Solvay S.A. |
| 3M Company |
| LyondellBasell Industries N.V. |
| Clariant AG |
| BASF SE |
| Mitsubishi Chemical Corporation |
| Avient Corporation |
| The Chemours Company |
| Others |
Value Chain & Pricing Dynamics
Captive tetrafluoroethylene monomer supply concentrated among integrated chemical majors in Belgium and France anchors margin pools downstream in fluoropolymer-grade PPA formulations, while independent additive houses compete on formulation service bundling rather than raw material cost parity.
Pricing Analysis
Long-term offtake agreements dominate procurement between major resin compounders and heritage fluoropolymer suppliers, insulating premium-tier pricing from spot volatility while spot transactions concentrate in commodity fatty acid derivatives. Price differentiation separates FDA-cleared food-contact grades from industrial specifications, with EU F-Gas Regulation compliance premiums widening spreads between fluorinated legacy stocks and validated fluorine-free alternatives. Cost compression in standard-grade amides is intensifying as Korean and Taiwanese converters consolidate purchasing volumes. Automotive OEM supply chains exhibit lowest price sensitivity due to scratch-resistance validation requirements, while commodity packaging converters in India drive hardest bargain terms.
Supply Chain Analysis
Export-control regimes limiting fluoropolymer technology transfer constrain raw material flows from integrated European producers to independent Asian compounders, fragmenting supply security across tiers. Manufacturing concentrates in Germany, Belgium, and the United States for high-performance grades, while China and India expand domestic polymerized wax capacity. Supply chains draw from tetrafluoroethylene monomer, glycerol feedstocks, and specialized amide precursors. Single-source vulnerability sits with legacy fluoropolymer registrations facing REACH authorization sunset. Distribution runs through technical service centers co-located with automotive and packaging clusters rather than commodity distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts unbundled from product supply represent the fastest-expanding revenue layer, with on-site extrusion troubleshooting and die design optimization commanding premium attach rates above commodity PPA volumes.
For Market Incumbents: Build formulation customization moats through captive regulatory affairs capabilities spanning FDA 21 CFR 177.1520, EU REACH authorization, and FSSAI clearance pathways. Expand technical service center footprint in Germany's Rhine corridor and India's Maharashtra-Gujarat belt to capture automotive OEM audit requirements and emerging food packaging demand. Backward integration into fluorine-free raw material streams hedges against ECHA substance evaluation delays. For New Entrants and Emerging Players: Pursue liquid concentrate automation partnerships with resin compounders seeking dust-free dosing systems, a white-space segment where heritage players retain powder infrastructure lock-in. Target India's FSSAI clearance gap before pathway maturation hardens import barriers. Enter through glycerol ester formulations for sustainability-mandated export contracts serving European automotive supply chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional compounders in Asia-Pacific lacking backward integration but holding formulated-product customer relationships. Five-to-ten year viability hinges on successful fluorine-free transition execution rather than legacy fluoropolymer cash harvest. Monitor ECHA authorization denial rates for novel chemistries as inflection signal for competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorine-Free Raw Materials | Captive glycerol ester supply secures margin capture ahead of REACH authorization deadlines. |
| Technical Service Center Expansion | Co-located extrusion troubleshooting meets German OEM audit documentation requirements. |
| Liquid Concentrate Capacity Buildout | Automated dosing compatibility captures compounder automation adoption in Houston and Shanghai. |
| Regulatory Clearance Portfolio Diversification | Simultaneous FDA, ECHA, and FSSAI pathways hedge against jurisdiction-specific authorization delays. |
| Joint Venture with Regional Resin Producers | Integrated formulation supply locks in polyethylene compounder volume commitments in India. |
Study Parameters
Cross-validation between primary interviews with extrusion plant managers, procurement leads at blown film converters, technical R&D directors at additive houses, and distribution channel partners anchors the qualitative findings against secondary validation from customs trade data, SEC 10-K filings, Cefic additive reports, and FDA food-contact notification databases. Bottom-up volume estimates from end-use consumption patterns triangulate with top-down supplier capacity assessments.
Calibration against historical price realization data and disclosed capacity expansion timelines structures the analytical framework across the analysis window. Segmentation dimensions span product chemistry tier, physical delivery format, conversion process type, end-use industry vertical, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections incorporating blown film line speed requirements and automotive specification evolution. Forecast inputs include ECHA authorization timeline probabilities and FSSAI clearance pathway maturation curves.
Sensitivities concentrate around ECHA substance evaluation outcomes, EPA TSCA Section 5 review durations, and fluorine-free formulation performance validation success rates. Forecasts reflect documented assumptions on regulatory deadline adherence and converter substitution velocity. Material shifts in EU F-Gas Regulation enforcement timing or breakthrough silicone-based alternatives without plate-out accumulation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
ePTFE Filter Film Market
Chemicals & Materials
North America Refining Catalysts Market
Chemicals & Materials
Nitrogen Trifluoride (NF3) Market
Chemicals & Materials
Steel Wire Rope and Plastic Rope Market
Chemicals & Materials
Mexico Flat Glass Market
Chemicals & Materials
Ethane Market
Chemicals & Materials
Oridonin Market
Chemicals & Materials
Gas Sampling Line Market
Chemicals & Materials
Europe Membrane Bioreactor (MBR) Market
Chemicals & Materials
Global Recycled PET (R-PET) Bottles Market
Chemicals & Materials
Global Amorphous Alloy Band Market
Chemicals & Materials
Potassium Schoenite Market
Chemicals & Materials
Isodecyl Pelargonate Market
Chemicals & Materials
Enzymatically Interesterified Oils Market
Chemicals & Materials
Europe Epoxy Resins Market
Chemicals & Materials
Liquid Applied Membranes Market