
 Global Metal Anodizing Market | 2026-2036
Global Metal Anodizing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Anodizing Market Foresight
Electrolytic process automation and closed-loop chemistry recovery is tilting capital allocation toward pulse current and plasma electrolytic oxidation lines. Lorin Industries sustains broad coil-anodizing capacity for architectural aluminum across North American building markets. Pioneer Metal Finishing operates a distributed shop network that competes on turnaround speed for aerospace and defense tier suppliers. Advanced Plating Technologies differentiates through specialized masking capabilities for selective anodizing on complex machined geometries.
Metal anodizing is an electrochemical surface conversion process that grows a controlled oxide layer, typically 5–25 microns for sulfuric acid variants and up to 100 microns for hard anodizing, to enhance corrosion resistance, dielectric properties, or wear performance on aluminum, titanium, and magnesium substrates. Sulfuric acid anodizing dominates volume due to its cost efficiency and versatility across electronics enclosures and consumer goods, while hard anodizing commands premium positioning in aerospace landing gear and hydraulic cylinder applications where extreme wear resistance is mandatory. Pulse current anodizing is gaining share in precision electronics for its ability to produce denser, more uniform oxide films with reduced thermal stress on thin-walled components.
EPA effluent guidelines in the United States restrict hexavalent chromium discharge from chromic acid anodizing baths, pushing shops toward trivalent alternatives or sulfuric-phosphoric blends. REACH authorization requirements in the European Union similarly constrain carcinogenic process chemistry, elevating compliance costs for legacy installations. ECHA's ongoing substance evaluation of boric acid derivatives further tightens formulation options for European operators. Stakeholders must monitor regulatory divergence between jurisdictions when siting new capacity or reformulating process chemistry, as compliance asymmetry is reshaping competitive access across major demand centers.
Market Dynamics
Pulse current anodizing and plasma electrolytic oxidation lines are capturing capital allocation as shops automate electrolytic processes and implement closed-loop chemistry recovery systems to meet tightening discharge limits.
Growth Catalysts
- Aerospace OEM expansion:North American and European airframe manufacturers are scaling anodized component sourcing for landing gear and structural applications, pulling capacity toward certified suppliers.
- REACH authorization pressure:The European Union's restrictions on hexavalent chromium processes are accelerating conversion to trivalent and organic acid alternatives, creating replacement demand for compliant equipment.
- Electronics cluster concentration:Industrial demand is concentrating in China's Guangdong and Zhejiang provinces where electronics and architectural metal finishing capacity has scaled significantly.
Market Restraints
- Input chemistry volatility:Sulfuric acid and chromic acid supply fluctuations create margin pressure for job shops running continuous batch operations.
- European regulatory friction:ECHA's ongoing substance evaluation of boric acid derivatives is tightening formulation options and elevating compliance costs for legacy installations.
- Hard anodizing substitution ceiling:Physical vapor deposition and thermal spray coatings are capturing select aerospace wear applications where oxide thickness requirements exceed 75 microns.
Strategic Opportunities
- India industrialization gap:Domestic aerospace and defense manufacturing expansion under the PLI scheme is creating first-mover potential for hard anodizing capacity near Bengaluru and Hyderabad clusters.
- CE marking convergence:The EU Green Deal's emphasis on circular economy principles is elevating preference for anodized aluminum in building facades over less recyclable alternatives.
- Digital thread integration:Convergence of pulse current power supplies with real-time impedance monitoring is digitizing quality assurance and compressing certification timelines for precision electronics.
Industry Challenges
- Electrochemist talent scarcity:Qualified bath chemistry specialists and pulse current technicians are in short supply as legacy operators retire without formal apprenticeship pipelines.
- EPA effluent compliance timelines:US shops face capital-intensive upgrades to meet discharge guidelines for hexavalent chromium, with permit renewals requiring documented treatment system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Anodizing Market |
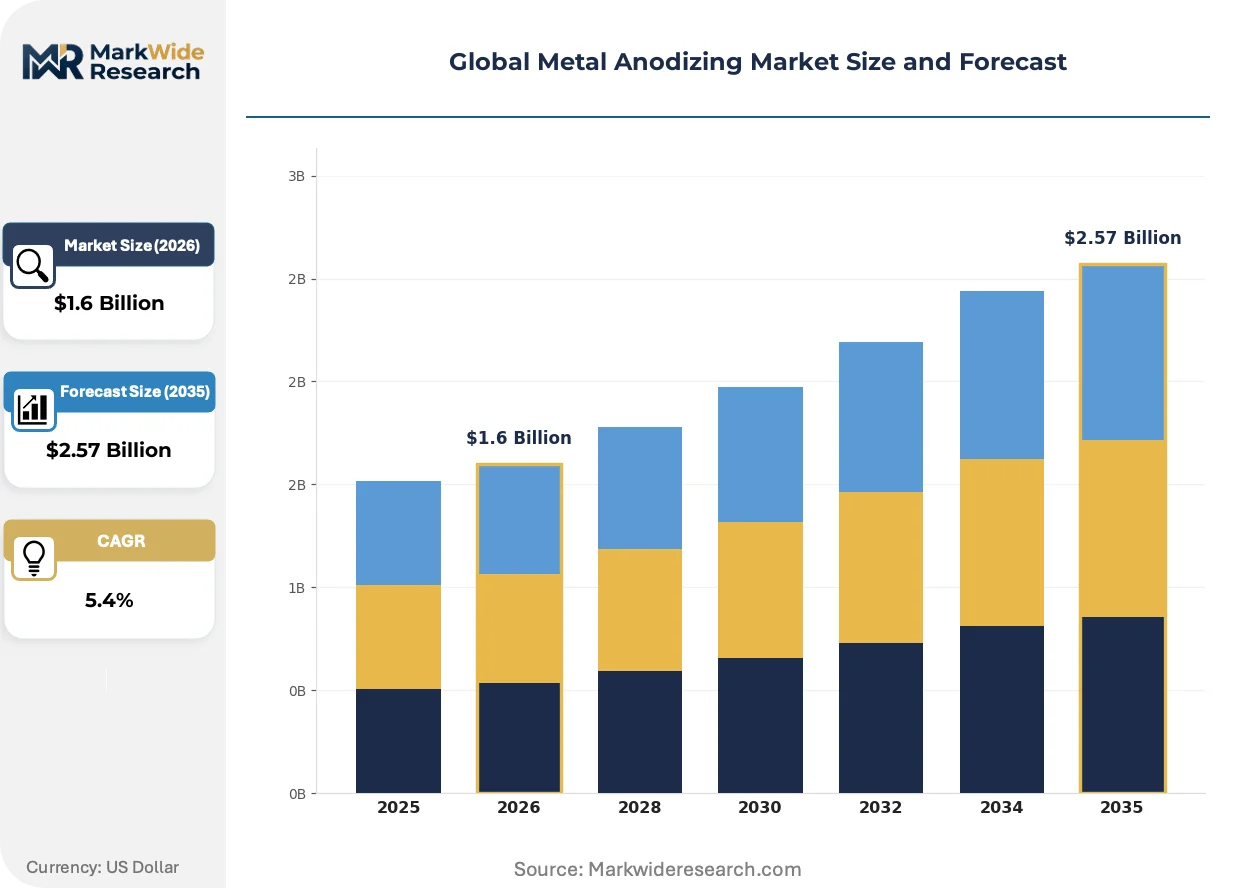
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfuric Acid Anodizing, Chromic Acid Anodizing, Hard Anodizing, Organic Acid Anodizing, Phosphoric Acid Anodizing Technology: DC Anodizing, Pulse Current Anodizing, AC Anodizing, Micro-Arc Oxidation, Plasma Electrolytic Oxidation End Use Industry: Aerospace, Electronics, Marine Equipment, Architecture, Consumer Goods Application: Corrosion Protection, Electrical Insulation, Surface Decoration, Wear Resistance, Heat Dissipation |
| Companies Covered | Advanced Plating Technologies, Lorin Industries, Huber Engineered Materials, Hillock Anodizing, Alucol, Pioneer Metal Finishing, Anoplate Corporation, PFI, K & L Anodizing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Anodizing Market Shifts & Advancements
Process digitization and chemistry reformulation are restructuring competitive advantage across anodizing operations, with automation and environmental compliance emerging as the primary axes of differentiation.
Plasma electrolytic oxidation is digitizing quality control through integrated impedance spectroscopy and machine learning-driven bath management. Medical device manufacturers in Switzerland and Germany are adopting these systems for magnesium implant surface modification. The technology is digitizing process documentation for FDA and Swissmedic submissions, compressing regulatory approval cycles.
REACH authorization requirements are constraining carcinogenic process chemistry across European coating operations. Shops are reformulating toward sulfuric-phosphoric blends and trivalent chromium alternatives, elevating capital intensity for compliant installations. Aerospace tier suppliers in France and Germany are prioritizing ECHA-registered formulations to defend OEM qualification status.
Specification-driven procurement is consolidating vendor relationships around certified job shops with documented process control. Electronics OEMs in Japan and South Korea are reducing supplier counts and extending quality agreements to capture volume discounts. This concentration is most visible in precision electronics for semiconductor capital equipment, where pulse current capability has become a gating criterion.
Global Metal Anodizing Market Segmentation
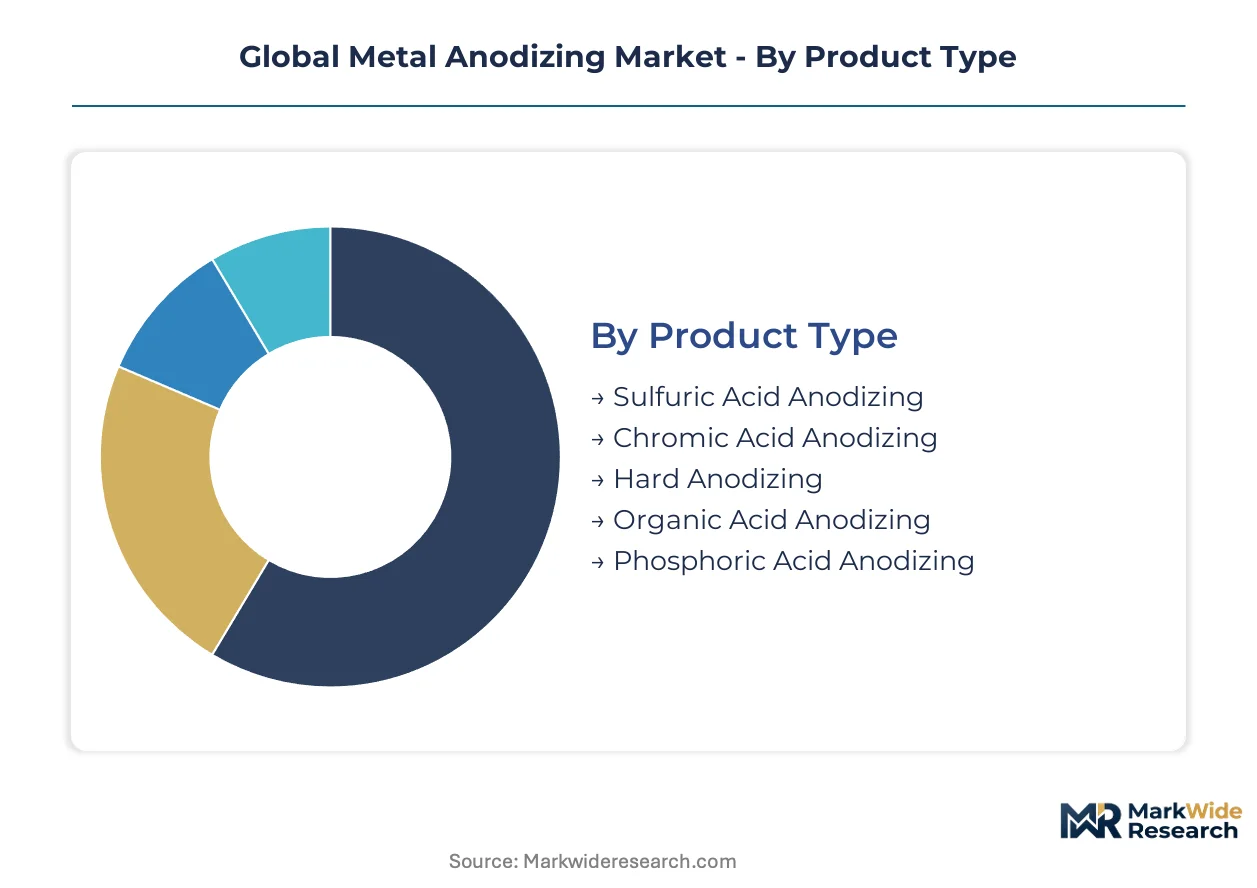
Segmentation in metal anodizing reveals how process chemistry, power delivery, and end-use specifications create distinct competitive arenas with divergent capital requirements and certification barriers. Understanding these boundaries helps suppliers align capacity investments with the most defensible customer relationships.
Product Type:
Sulfuric acid and hard anodizing turn over production slots fastest due to standardized bath chemistry and established aerospace qualification pathways, while organic acid variants cycle slower as formulation adjustments extend setup times.
- Sulfuric Acid Anodizing:The workhorse process employs 15-20% acid concentration to produce 5-25 micron oxide layers with excellent dye absorption for consumer electronics enclosures. Demand concentrates in China's Guangdong province where smartphone and laptop manufacturers operate just-in-time finishing contracts with 48-hour turnaround requirements.
- Hard Anodizing:Low-temperature electrolyte formulations near 0°C generate dense aluminum oxide up to 100 microns thick for landing gear and hydraulic actuators. Boeing and Airbus tier suppliers in France and Germany maintain dedicated lines with Nadcap accreditation to serve airframe OEM qualification requirements.
- Chromic Acid Anodizing:Thin-film variants for precision aerospace fasteners face EPA discharge restrictions in the United States and REACH authorization limits across the European Union.
- Organic Acid Anodizing:Oxalic and malonic acid blends serve architectural applications seeking warmer tone finishes without hexavalent chromium exposure risks.
- Phosphoric Acid Anodizing:Specialized pretreatment for adhesive bonding in aircraft structural assemblies, particularly prevalent in Japanese and South Korean aerospace subcontracting networks.
Sulfuric acid anodizing dominates installed base. Hard anodizing is where expansion concentrates.
Technology:
DC equipment represents the lowest cost tier with mature supplier ecosystems, while pulse current and plasma electrolytic systems command premium positioning through precision control capabilities.
- DC Anodizing:Conventional rectifier technology serves high-volume architectural and consumer goods with proven reliability and minimal maintenance requirements.
- Pulse Current Anodizing:Modulated power delivery produces denser oxide films with reduced thermal stress on thin-walled semiconductor equipment components. Swiss and German medical device manufacturers specify these systems for magnesium implant surface modification to meet Swissmedic documentation requirements.
- AC Anodizing:Alternating current variants for specialized coloring effects in decorative architectural applications.
- Micro-Arc Oxidation:High-voltage spark discharge processes for magnesium and titanium alloys in lightweight automotive prototyping.
- Plasma Electrolytic Oxidation:Integrated impedance spectroscopy and machine learning-driven bath management digitize quality control for FDA submission documentation. The technology is gaining traction in German orthopedic implant manufacturing where process traceability compresses regulatory approval cycles.
DC systems anchor volume production. Pulse current capability is climbing the fastest as electronics OEMs reduce supplier counts around certified precision shops.
End Use Industry:
Consumer goods and electronics drive highest batch frequency with shortest lead times, while aerospace runs longest production cycles tied to OEM qualification protocols.
- Aerospace:Landing gear, airframe structures, and hydraulic systems require Nadcap-accredited hard anodizing with documented process control. French and German tier suppliers prioritize ECHA-registered formulations to defend Boeing and Airbus qualification status.
- Electronics:Enclosures, heat sinks, and semiconductor capital equipment components demand sulfuric acid and pulse current precision. Japanese and South Korean OEMs are consolidating vendor relationships around shops with real-time impedance monitoring capabilities.
- Marine Equipment:Corrosion-resistant finishes for hardware and structural components in saltwater environments.
- Architecture:Building facades and interior metalwork favor anodized aluminum under EU Green Deal circular economy principles elevating recyclable material preference.
- Consumer Goods:Appliances, sporting equipment, and premium packaging accessories.
Electronics commands the steepest expansion trajectory. Aerospace maintains the highest margin retention through certification barriers.
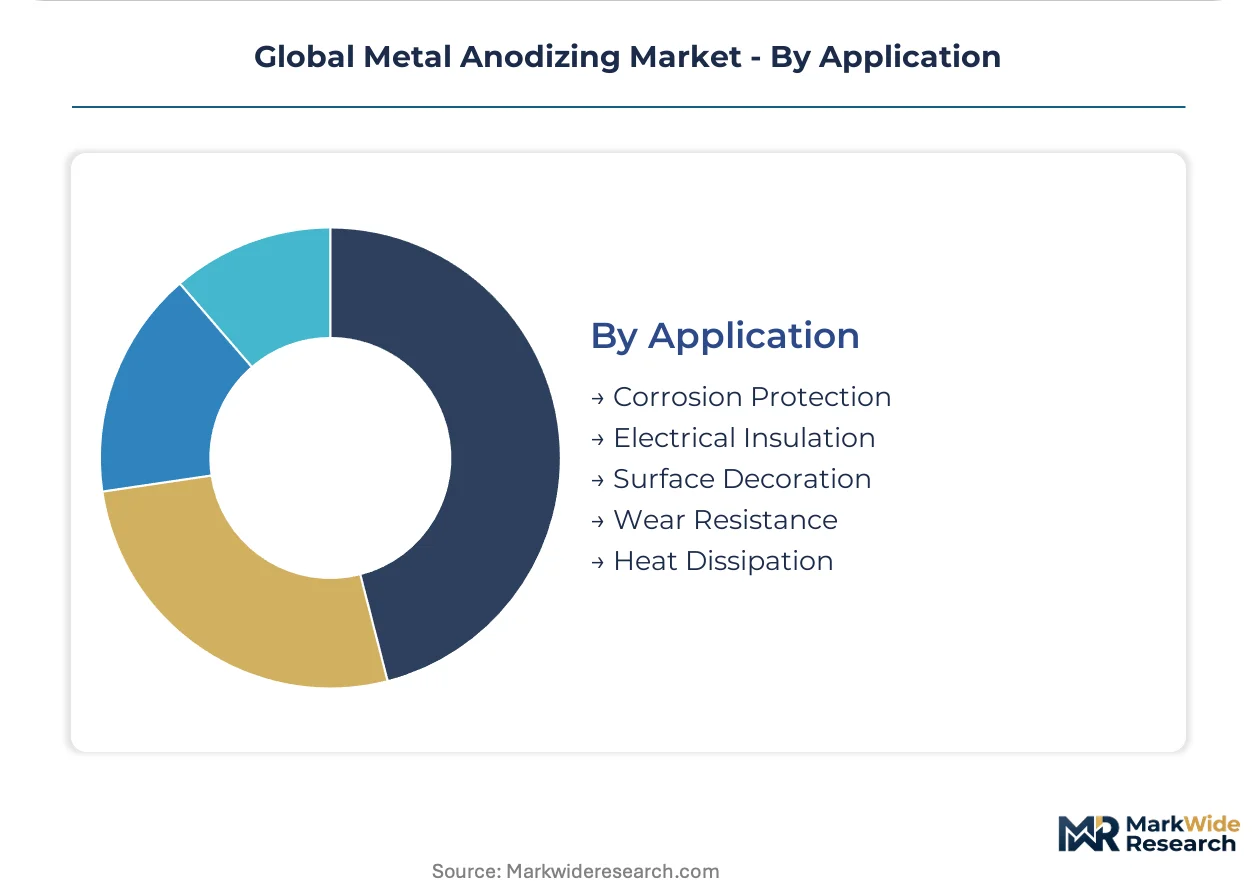
Application:
Corrosion protection and wear resistance applications run continuously with predictable chemistry consumption, while electrical insulation and surface decoration require more frequent bath adjustment cycles.
- Corrosion Protection:Barrier oxide layers for marine, industrial, and outdoor architectural exposure. India's PLI scheme for domestic aerospace manufacturing is creating first-mover opportunity for hard anodizing capacity near Bengaluru defense clusters.
- Wear Resistance:Hard anodizing for sliding surfaces in hydraulic cylinders and landing gear struts. Physical vapor deposition competes for applications exceeding 75 micron thickness requirements.
- Electrical Insulation:Dielectric oxide films for electronic housings and thermal management substrates.
- Surface Decoration:Dyed and sealed finishes for consumer products and architectural accents.
- Heat Dissipation:Structured oxide surfaces enhancing thermal transfer in LED and power electronics.
Corrosion protection holds the largest installed footprint. Wear resistance is gaining share fastest as aerospace OEMs expand sourced component programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese anodizing capacity serves electronics OEMs across Japan, South Korea, and Taiwan with 48-hour turnaround contracts. German and French tier suppliers export hard-anodized aerospace components to Boeing and Airbus final assembly lines in the United States.
United States
Aerospace OEMs in Washington and California states scale sourced anodized landing gear programs. EPA effluent guidelines restrict hexavalent chromium discharge from chromic acid baths, pushing shops toward trivalent alternatives. Job shops in Southern California and Arizona clusters face capital-intensive treatment system upgrades to meet permit renewal requirements.
Germany
Airbus tier suppliers in Bavaria and Baden-Württemberg maintain Nadcap-accredited hard anodizing lines for airframe qualification. ECHA REACH authorization requirements constrain carcinogenic process chemistry, elevating compliance costs for legacy installations. Aerospace subcontractors around Hamburg and Munich prioritize ECHA-registered formulations to defend Boeing and Airbus supplier status.
China
Electronics enclosure demand concentrates in Guangdong and Zhejiang provinces where smartphone and laptop manufacturers operate just-in-time finishing contracts. MIIT industrial standards govern surface treatment emissions in the Yangtze and Pearl River Delta clusters. Shenzhen and Dongguan job shops have scaled sulfuric acid capacity to serve Apple and Huawei supplier networks with sub-48-hour turnaround.
France
Aerospace structural component demand pulls capacity toward Toulouse and Bordeaux aerospace clusters serving Airbus final assembly. REACH restrictions on hexavalent chromium accelerate conversion to trivalent and organic acid alternatives. Job shops in the Occitanie region invest in pulse current automation to meet OEM documentation requirements for landing gear and hydraulic systems.
India
Domestic aerospace and defense manufacturing expansion under the PLI scheme creates first-mover potential for hard anodizing capacity. BIS certification requirements govern surface treatment standards for defense procurement. Industrial clusters near Bengaluru and Hyderabad are attracting investment from tier suppliers seeking to localize anodized component sourcing for HAL and DRDO programs.
Global Metal Anodizing Market Competitive Landscape
On the supply side, the industry is fragmented across independent job shops, captive in-house operations, and specialized coil processors. The vendor base spans three strategic tiers: high-volume architectural processors, precision aerospace-certified shops, and electronics-focused rapid-turnaround specialists. Competitive moves center on Nadcap accreditation acquisition and geographic proximity to OEM final assembly lines.
Within the precision-certified tier, Advanced Plating Technologies and Pioneer Metal Finishing exemplify shops competing on documented process control and turnaround speed. Lorin Industries occupies a distinct position as a coil-anodizing specialist serving architectural aluminum markets across North American building sectors. These three companies represent the archetypal specialization vectors—selective masking capability, distributed shop networks, and continuous coil processing—that define competitive positioning in the current market structure.
| Leading Market Players |
|---|
| Advanced Plating Technologies |
| Lorin Industries |
| Huber Engineered Materials |
| Hillock Anodizing |
| Alucol |
| Pioneer Metal Finishing |
| Anoplate Corporation |
| PFI |
| K & L Anodizing Corporation |
| Others |
Supply & Pricing Matrix
Shenzhen's sulfuric acid anodizing cluster commands pricing leverage over electronics OEMs through sub-48-hour turnaround guarantees, while Guangdong's capacity concentration forces margin compression on architectural job shops competing for commodity coating contracts.
Pricing Analysis
DC rectifier systems anchor economy-tier pricing for high-volume architectural contracts, pulse current equipment commands mid-tier premiums from precision electronics OEMs, and plasma electrolytic oxidation lines capture premium positioning in medical device applications. Price differentiation hinges on Nadcap certification status and real-time process monitoring capabilities. Cost compression in sulfuric acid anodizing intensifies as Chinese job shops scale automated batch processing. Consumer electronics enclosure buyers exhibit highest price sensitivity; aerospace tier suppliers show lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for anodized electronics components. Manufacturing concentrates in China, Germany, and the United States. Sulfuric acid, chromic acid, and proprietary organic acid formulations constitute critical input dependencies. Distribution runs through certified job shop networks with documented process control for aerospace qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal anodizing is approaching a platform-economics inflection as pulse current power supplies converge with machine learning-driven bath management, creating interoperability standards that will consolidate vendor relationships around digitally certified suppliers.
For Market Incumbents: Harden Nadcap-accredited capacity positions in France and Germany against physical vapor deposition substitution threats in aerospace wear applications exceeding 75 microns. Deepen backward integration into proprietary organic acid formulations to deflect REACH authorization pressure on hexavalent chromium alternatives. Prioritize real-time impedance monitoring R&D to meet Japanese and South Korean electronics OEM documentation requirements. For New Entrants and Emerging Players: Pursue hard anodizing capacity deployment near Bengaluru and Hyderabad defense clusters under India's PLI scheme, where domestic aerospace manufacturing expansion has outpaced certified finishing infrastructure. Target phosphoric acid anodizing for adhesive bonding pretreatment in Japanese aerospace subcontracting networks. Lead with ECHA-registered formulation compliance to accelerate OEM qualification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage consolidation play because jurisdictional divergence in EPA effluent guidelines and REACH authorization requirements is reshaping competitive access across major demand centers. Acquisition targets should emphasize shops with documented pulse current capability and existing aerospace tier supplier relationships. Monitor ECHA substance evaluation outcomes for boric acid derivatives as inflection signals for European formulation reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Hard anodizing lines near Bengaluru serve HAL and DRDO localization requirements under India's PLI scheme. |
| Backward Integration | In-house organic acid formulation development defends margin positions against REACH-driven chemistry substitution costs. |
| Green Manufacturing Transition | Trivalent chromium conversion aligns with EU Green Deal circular economy principles for building facade applications. |
| Long-term Supply Agreement | Quality agreements with Japanese electronics OEMs lock in volume commitments around pulse current capability. |
| Joint Venture | Technology partnerships with Swiss and German medical device manufacturers accelerate FDA submission documentation cycles. |
Research Methodology
The analysis maps sulfuric acid, hard, chromic, organic, and phosphoric acid anodizing sub-sectors, each validated through plant managers at job shops, procurement leads at aerospace tier suppliers, technical R&D directors at chemical suppliers, and distribution channel partners. Primary interview insights triangulate against secondary sources including EPA effluent guideline filings, ECHA REACH authorization databases, MIIT industrial standard disclosures, and SEC 10-K filings from publicly traded coating equipment manufacturers. Bottom-up capacity estimates and top-down demand projections reconcile through iterative stakeholder validation.
Assumptions held fixed include regulatory enforcement timelines for hexavalent chromium restrictions, pulse current equipment adoption curves in precision electronics, and aerospace OEM sourced component expansion rates. Variables tested include boric acid derivative evaluation outcomes, physical vapor deposition substitution thresholds, and Indian PLI scheme implementation pace. The analytical framework models product type, technology generation, end-use industry, application function, and regional regulatory cluster across the projection horizon. CAGRs derive from segmented volume trajectories weighted by pricing tier concentration. Industry-specific inputs encompass Nadcap accreditation counts, ECHA-registered formulation inventories, and electronics cluster capacity utilization surveys.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed industrial clusters or accelerated physical vapor deposition technology maturation would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Extruders Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Argon Knife Market
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Plain Bearing Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Plastic Molds Market