
 Hybrid Polymer Market | 2026-2036
Hybrid Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Polymer Market Analysis
Software-defined formulation tuning is decoupling product performance from fixed resin chemistry, allowing manufacturers to sell adaptive polymer systems rather than static compounds. Henkel AG & Co. KGaA leverages its adhesives heritage to anchor hybrid polyurethane lines in automotive assembly applications. Sika AG dominates construction-grade sealant distribution through direct contractor channels across Europe and Asia. BASF SE extends its raw material position into formulated hybrid systems, competing on captive monomer supply.
Hybrid polymers are macromolecular systems combining two or more distinct polymer chemistries—typically silane-terminated polyurethanes or epoxy-acrylic hybrids—cured through moisture or thermal activation to achieve combined elasticity, adhesion, and environmental resistance. These materials serve primarily as structural bonding and protective layers where single-resin performance proves inadequate. Polyurethanes lead volume consumption in adhesive applications owing to their flexibility and substrate compatibility, while epoxy resins command premium positioning in aerospace composites where thermal and mechanical thresholds are most severe. Silicones sustain growth in electronics coatings as miniaturization demands thinner, thermally stable protection layers.
REACH in Europe and EPA regulations in the United States restrict volatile organic compound content in formulated products, forcing reformulation toward low-emission hybrid systems. China's GB standards and MEE oversight similarly tighten environmental compliance for domestic production and import qualification. BIS certification requirements in India add another layer of market access conditioning for foreign suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
Market Dynamics
REACH compliance deadlines in Europe are forcing accelerated reformulation cycles across sealant and adhesive portfolios, compressing product development timelines while elevating R&D spend as a competitive differentiator.
Growth Catalysts
- Construction sector specification shifts:German contractors now mandate hybrid systems for structural glazing in commercial facades, displacing conventional silicone sealants in high-rise applications.
- REACH Article 33 disclosure requirements:ECHA enforcement is accelerating substitution of isocyanate-heavy formulations toward silane-terminated polyurethanes with lower SVHC footprints.
- Epoxy-acrylic hybrid curing advances:Dual-cure chemistry enabling room-temperature processing is unlocking aerospace composite repairs previously restricted to autoclave-dependent systems.
Market Restraints
- Silane monomer supply concentration:German and Chinese chemical clusters control over three-quarters of organofunctional silane precursor capacity, creating geographic vulnerability for formulators elsewhere.
- Epoxy resin price volatility:Bisphenol A feedstock fluctuations and benzene derivative sourcing constraints transmit directly to hybrid system cost structures.
- Moisture-cure limitations in humid climates:Southeast Asian applicators face extended tack-free times and surface defect risks that thermal-cure alternatives avoid.
Strategic Opportunities
- Indian infrastructure buildout:BIS certification pathways for hybrid sealants in metro rail and airport construction remain underpenetrated by European formulators despite PLI scheme incentives for domestic manufacturing.
- Wind turbine blade bonding:Epoxy-urethane hybrids with tailored elongation profiles are displacing conventional adhesive systems in rotor assembly as blade lengths exceed 100 meters.
- EU Green Deal procurement mandates:Public construction tenders above threshold values now require Environmental Product Declarations, favoring low-VOC hybrid formulations with verified lifecycle data.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in silane-terminated polyurethane reaction kinetics and moisture stability is concentrated among retiring specialists in German and Japanese industrial centers.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of REACH registration, EPA TSCA compliance, and China MEE environmental assessment extends product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Polymer Market |
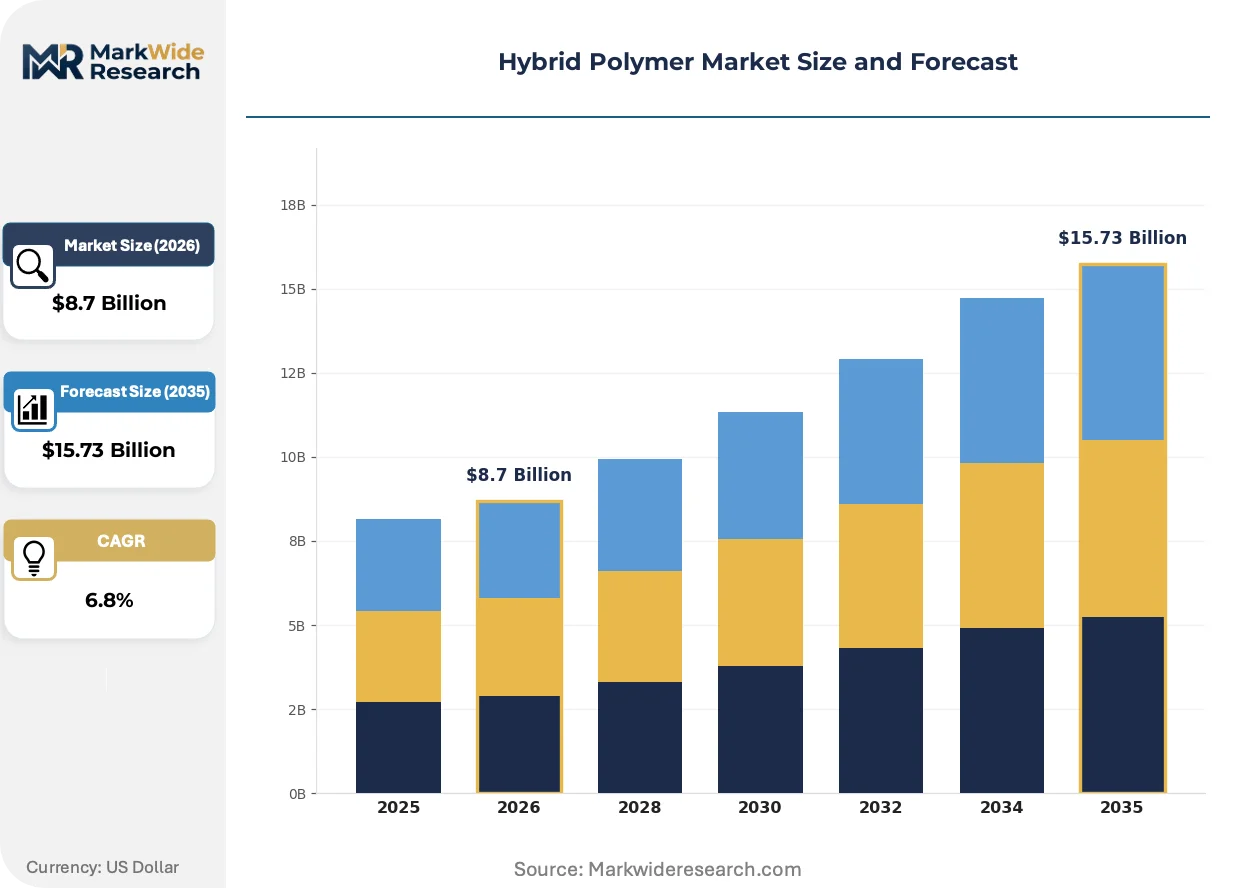
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylics, Polyurethanes, Epoxy Resins, Silicones Application: Adhesives, Coatings, Sealants, Composites End User: Automotive, Electronics, Aerospace, Construction Form: Liquid, Powder, Granules, Films |
| Companies Covered | Bostik, 3M Company, Sika AG, Henkel AG & Co. KGaA, Wacker Chemie AG, Arkema Group, Dow Chemical Company, Evonik Industries AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Polymer Market Emerging Trajectories
Software-defined formulation platforms are decoupling performance attributes from fixed resin architectures, enabling real-time polymer system adaptation to application-specific requirements without batch-scale reformulation.
Silane-terminated polyurethane synthesis is modularizing around plug-and-play organofunctional silane building blocks that permit independent tuning of cure speed, modulus, and adhesion profile. Automotive assembly plants in Stuttgart and Detroit are adopting these adaptive systems for mixed-substrate bonding lines. The technology is modularizing supplier-customer relationships from compound sales toward performance-parameter subscriptions.
EPA VOC emission standards under 40 CFR Part 59 are tightening permissible limits for architectural coatings and adhesives, compelling reformulation toward exempt solvent hybrid systems. Manufacturers serving US construction markets are accelerating waterborne and 100%-solid hybrid development to maintain shelf presence. California Air Resources Board (CARB) Suggested Control Measures are transmitting pressure to neighboring state jurisdictions, expanding geographic scope of compliance investment.
Specification authority is migrating from general contractors to asset owners and their engineering consultants, who now demand certified performance data and extended warranty terms as procurement gatekeepers. Direct channel relationships between hybrid polymer formulators and infrastructure fund managers are displacing traditional distributor networks in European renewable energy projects. This pattern is most pronounced in German offshore wind and Spanish solar installation procurement, where lifecycle cost modeling dominates adhesive selection criteria.
Hybrid Polymer Market Segmentation
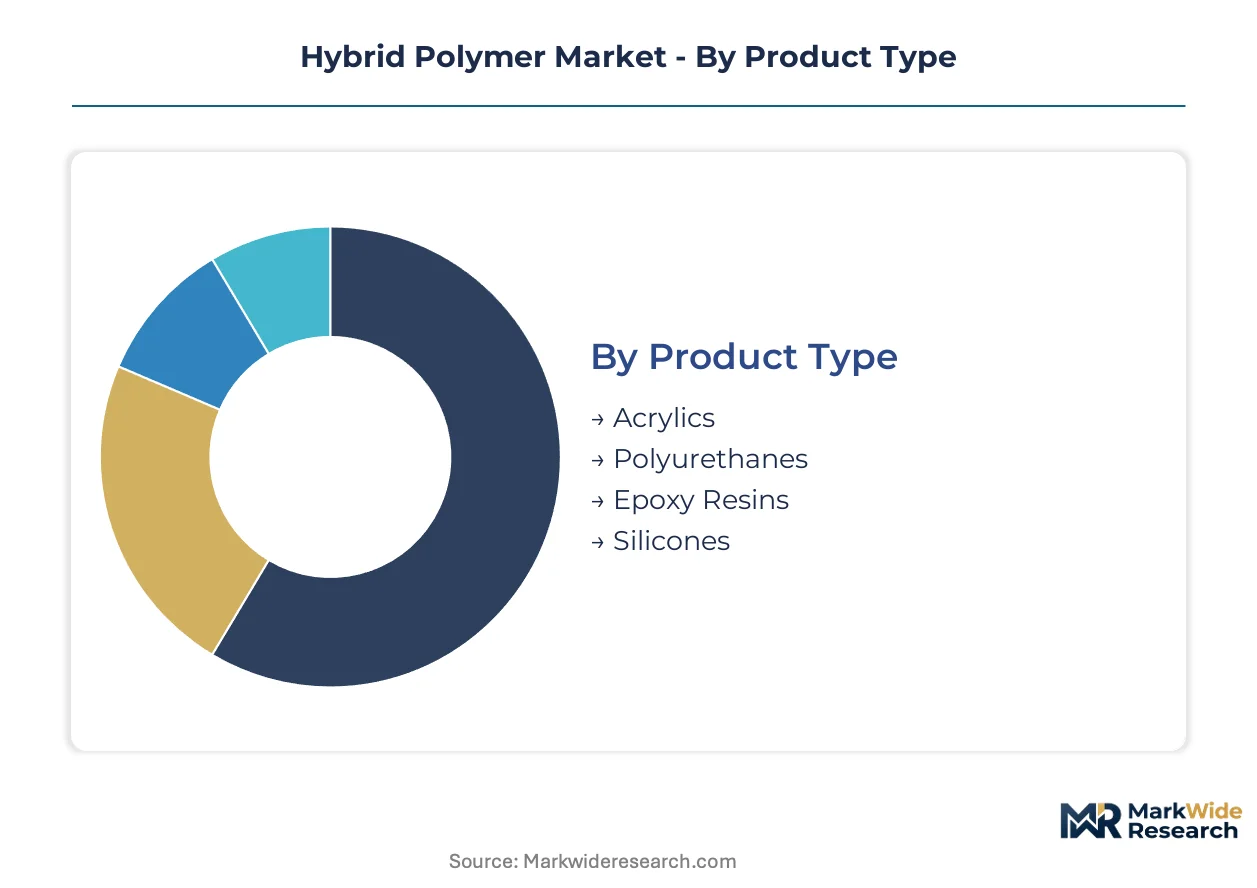
Hybrid polymer manufacturers compete across chemically distinct product architectures, each commanding different specification authority in end-use markets. Segmentation reveals where formulation expertise concentrates versus where application engineering determines supplier selection.
Product Type:
Polyurethanes dominate volume consumption while epoxy resins extract premium positioning through performance thresholds.
- Polyurethanes:Silane-terminated and moisture-cure systems combine elasticity with substrate adhesion across construction and automotive bonding. German automotive assembly plants specify these for mixed-metal and composite joining lines. REACH Article 33 disclosure requirements are accelerating substitution from isocyanate-heavy precursors toward lower-SVHC silane variants.
- Epoxy Resins:Bisphenol A-derived systems cure through thermal or amine activation to deliver compressive strength and chemical resistance. Aerospace composite repairs in Stuttgart and Toulouse facilities specify epoxy-acrylic hybrids for room-temperature processing previously requiring autoclave cycles. Benzene derivative feedstock volatility transmits directly to hybrid system cost structures.
- Silicones:Electronics miniaturization in Shenzhen and Seoul drives demand for thermally stable thin-film protection layers.
- Acrylics:UV-cure and waterborne formulations serve architectural coatings markets facing EPA VOC emission limits.
Mature deployment sits with polyurethanes. Newer deployment is concentrated in epoxy-acrylic hybrid systems gaining specification in aerospace repair protocols.
Application:
Specification authority migrates toward asset owners demanding certified lifecycle data rather than distributor-recommended products.
- Sealants:Structural glazing applications in German commercial facades now mandate hybrid systems displacing conventional silicone in high-rise construction. Direct contractor channel relationships dominate procurement.
- Adhesives:Wind turbine blade bonding exceeding 100-meter lengths specifies epoxy-urethane hybrids with tailored elongation profiles. Indian metro rail and airport construction under BIS certification pathways remain underpenetrated by European formulators.
- Coatings:Public construction tenders above EU Green Deal threshold values require Environmental Product Declarations favoring low-VOC formulations.
- Composites:Dual-cure chemistry enables aerospace component fabrication without autoclave dependency.
Sealants capture the steepest specification upgrade trajectory. Composites represent the most technically constrained expansion pathway due to certification timelines.
End User:
Construction and automotive concentrate volume procurement while electronics and aerospace command formulation premiums.
- Construction:German contractors specify hybrid sealants for structural glazing. EU Green Deal procurement mandates now require Environmental Product Declarations for public tenders above threshold values.
- Automotive:Stuttgart and Detroit assembly plants adopt adaptive polymer systems for mixed-substrate bonding lines. Software-defined formulation tuning enables real-time parameter adjustment without batch-scale reformulation.
- Electronics:Miniaturization demands thinner thermally stable protection layers in Shenzhen and Seoul manufacturing clusters.
- Aerospace:Room-temperature curing epoxy-acrylic hybrids unlock composite repairs previously restricted to autoclave-dependent systems.
Construction anchors volume demand. Electronics and aerospace concentrate the fastest margin expansion.
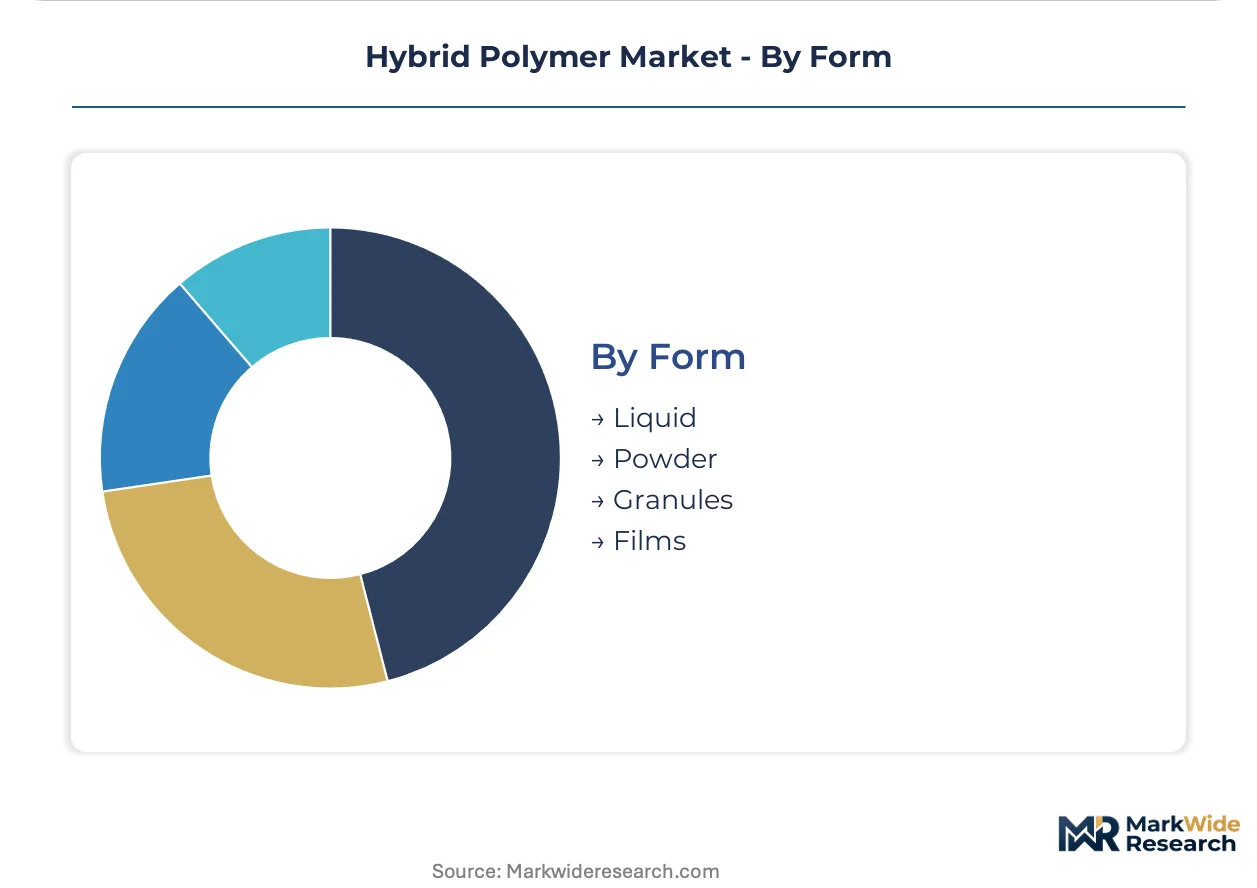
Form:
Physical state determines application equipment compatibility and supply chain configuration.
- Liquid:Pumpable systems dominate sealant and adhesive dispensing in automated automotive and construction assembly lines.
- Powder:100%-solid formulations serve markets facing stringent VOC emission regulations under EPA 40 CFR Part 59.
- Granules:Intermediate processing form for compounders blending custom hybrid systems.
- Films:Pre-cured sheet formats enable electronics lamination and aerospace surface protection applications.
Liquid forms retain specification dominance. Powder formats gain share fastest in jurisdictions tightening solvent emission limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical clusters supply silane monomer precursors to formulators worldwide, while Chinese manufacturing hubs absorb disproportionate hybrid polymer volumes for domestic construction and electronics assembly. Indian infrastructure expansion and US automotive retooling create competing demand centers that strain existing supply allocations.
Germany
Stuttgart automotive plants specify adaptive hybrid systems for mixed-metal bonding lines, consuming specialized silane-terminated polyurethanes. ECHA enforces REACH Article 33 disclosure requirements that accelerate substitution away from isocyanate-heavy formulations. The Rhine-Ruhr chemical corridor concentrates organofunctional silane precursor capacity, supplying three-quarters of European formulator demand.
China
Shenzhen electronics miniaturization drives thermally stable silicone hybrid coatings for semiconductor protection layers. MEE oversight and GB standards tighten environmental compliance for domestic production and import qualification. The Yangtze River Delta industrial cluster houses moisture-cure adhesive formulators serving wind turbine blade assembly for domestic renewable energy projects.
United States
Detroit automotive assembly plants adopt software-defined formulation tuning for real-time parameter adjustment across mixed-substrate bonding lines. EPA 40 CFR Part 59 VOC emission standards compel reformulation toward exempt solvent hybrid systems. California Air Resources Board Suggested Control Measures transmit regulatory pressure to neighboring state jurisdictions, expanding compliance investment scope.
India
Metro rail and airport construction under BIS certification pathways creates specification demand for structural sealants in commercial infrastructure. PLI scheme incentives attract domestic manufacturing investment from European formulators seeking market access. The Delhi-Mumbai Industrial Corridor concentrates captive consumption for hybrid adhesive systems in transportation infrastructure projects.
Japan
Tokyo-Osaka electronics manufacturing clusters demand thinner protection layers as device miniaturization advances. METI oversees industrial chemical standards that align with REACH-equivalent disclosure frameworks for hybrid polymer imports. Chubu region formulators specialize in silane-terminated polyurethane reaction kinetics expertise that global competitors struggle to replicate.
Hybrid Polymer Market Vendor Landscape
Top-tier vendors anchor formulated product distribution, while mid-scale compounders compete on captive monomer supply and regional certification speed. The market structure concentrates specification authority among adhesives specialists with direct contractor channel relationships. Three archetypes dominate: diversified chemical conglomerates with backward monomer integration, construction-focused sealant formulators with specification engineering capabilities, and automotive assembly specialists with adaptive polymer system platforms. Competitive moves center on M&A to secure silane precursor supply and strategic partnerships to compress multi-jurisdiction certification timelines.
Among European-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the backward-integrated archetype, leveraging captive feedstock positions to compete on raw material cost structures. Sika AG and Henkel AG & Co. KGaA occupy positions within the specification-driven tier, anchoring construction-grade and automotive assembly applications respectively through direct channel relationships rather than distributor networks. These four represent distinct competitive vectors: monomer supply security versus formulation expertise versus application engineering depth.
| Leading Market Players |
|---|
| Bostik |
| 3M Company |
| Sika AG |
| Henkel AG & Co. KGaA |
| Wacker Chemie AG |
| Arkema Group |
| Dow Chemical Company |
| Evonik Industries AG |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Software-defined formulation tuning is decoupling product performance from fixed resin chemistry, simultaneously compressing batch-scale production costs and concentrating specification authority among adaptive system providers with direct automotive and construction channel relationships. This production-method transition rewards German and Chinese chemical clusters with captive silane monomer capacity while elevating R&D spend as a competitive barrier for formulators lacking backward integration.
Pricing Analysis
Margin tightening in standard-grade formulations reflects benzene derivative feedstock volatility and bisphenol A price swings that transmit directly to epoxy-urethane hybrid cost structures. Three-tier pricing structure across premium, standard, and economy levels differentiates on REACH compliance tier and certified Environmental Product Declaration status. Pricing pressure intensifies in construction-grade sealants as German contractors consolidate procurement through direct specification engineering relationships. Asset owners and engineering consultants exhibit lowest price sensitivity due to lifecycle cost modeling dominance, while small-scale applicators in Southeast Asian humid climates face highest sensitivity to moisture-cure system performance failures.
Supply Chain Analysis
Specialized formulation chemist scarcity in German and Japanese industrial centers constrains production scaling for silane-terminated polyurethane reaction kinetics expertise. Geographic supply concentration centers on Germany, China, and the United States for organofunctional silane precursors, epoxy resin feedstocks, and automotive assembly consumption respectively. Raw material dependencies rest on bisphenol A derivatives, benzene-based intermediates, and moisture-sensitive silane monomers. Single-source vulnerability from German and Chinese chemical cluster control over three-quarters of precursor capacity creates geographic concentration risk. Distribution runs through direct contractor channels in European construction and specification engineering relationships in German automotive assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH Article 33 disclosure requirements and ECHA enforcement create a barrier-to-entry moat for formulators with established substitution pathways away from isocyanate-heavy precursors.
For Market Incumbents: Hedge silane monomer supply exposure through long-term offtake agreements with Rhine-Ruhr chemical corridor producers or strategic partnerships with Chinese precursor manufacturers. Accelerate software-defined formulation platform deployment to defend margin position against adaptive polymer system competitors. Prioritize certification investment in BIS pathways for Indian infrastructure access before PLI scheme incentives attract domestic manufacturing entrants. For New Entrants and Emerging Players: Direct contractor channel relationships in German offshore wind and Spanish solar installation procurement represent the most penetrable white-space target, as specification authority migration from distributors to asset owners disrupts incumbent lock-in. Indian metro rail and airport construction under BIS certification pathways remain underpenetrated by European formulators despite infrastructure buildout acceleration. Pursue joint development agreements with engineering consultants as the primary go-to-market angle, offering certified lifecycle data and extended warranty terms that match procurement gatekeeper requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in construction-focused sealant formulators with specification engineering capabilities and captive silane precursor supply positions. Long-term viability over the projection horizon favors backward-integrated compounders with REACH-registered portfolios and direct channel control in German automotive or renewable energy procurement. Acquisition target archetype: mid-scale formulators with modular silane-terminated polyurethane synthesis expertise and pending multi-jurisdiction certification timelines. Monitor ECHA enforcement intensity and REACH compliance deadline acceleration as the signal to watch for market consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursor Supply | Rhine-Ruhr chemical corridor capacity secures formulation cost structures against benzene derivative volatility. |
| Software-Defined Formulation Platform Launch | Real-time parameter adjustment enables Stuttgart and Detroit automotive plants to reduce mixed-substrate bonding line changeover times. |
| BIS Certification Pathway Investment | Delhi-Mumbai Industrial Corridor infrastructure projects create specification demand for compliant structural sealants. |
| Direct Contractor Channel Expansion | EU Green Deal procurement mandates favor formulators with asset owner relationships over distributor networks. |
| Joint Venture with Chinese Precursor Manufacturer | Yangtze River Delta industrial cluster access mitigates geographic supply concentration vulnerability. |
Methodological Framework
Document review covered ECHA regulatory filings, customs and trade data, SEC 10-K disclosures from chemical conglomerates, and industry association reports from ACC and Cefic, complemented by interviews with plant managers at hybrid polymer formulators, procurement leads at German automotive OEMs, distribution channel partners in European construction, and technical R&D directors specializing in silane-terminated polyurethane synthesis. Bottom-up demand modeling across end-use applications triangulated with top-down supply-side capacity assessments.
Segmentation outputs reflect disaggregation by resin chemistry type, application function, end-user industry concentration, and physical form factor across the analysis window. CAGRs derived from regression analysis against construction spending indices, automotive production volumes, and electronics manufacturing activity. Forecast inputs incorporated REACH compliance timeline acceleration, EPA 40 CFR Part 59 enforcement patterns, and MEE oversight intensity in Chinese manufacturing hubs.
Several conditions sit outside the modeled scope, including abrupt feedstock price dislocations from benzene derivative supply disruptions, unilateral regulatory divergence between REACH and EPA TSCA frameworks, and technological substitution from purely bio-based adhesive systems. Forecasts reflect documented assumptions regarding certification timeline compression and channel relationship stability. Material deviation in ECHA enforcement intensity, silane monomer supply allocation disruptions, or BIS certification pathway acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Global Amino Resin Market