
 Global Polyethylene Glycol Market | 2026-2036
Global Polyethylene Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyethylene Glycol Market Foresight
Specialized polymer chemist availability is redrawing competitive boundaries across the polyethylene glycol value chain. Dow Inc. leverages backward integration into ethylene oxide feedstock to secure cost advantages in high-molecular-weight grades. BASF SE anchors European supply through Ludwigshafen-based alkoxylation capacity that serves pharmaceutical and personal care formulators. SABIC competes via petrochemical integration at Jubail Industrial City, redirecting glycol streams toward differentiated PEG derivatives.
Polyethylene glycol comprises ethylene oxide oligomers with molecular weights spanning 200 to over 8,000 g/mol, synthesized via base-catalyzed ring-opening polymerization and valued for tunable hydrophilicity, low toxicity, and FDA-approved status across multiple pharmacopeias. PEG 3350 and PEG 6000 dominate pharmaceutical applications where laxative and protein conjugation demand command premium pricing over industrial grades. Cosmetic and personal care applications represent the fastest-expanding consumption pool as Korean and Japanese formulators adopt PEGylated emollients in waterless beauty products.
REACH registration requirements and USP-NF monograph standards govern impurity profiles for pharmaceutical-grade material, while FDA's process validation guidelines for excipients shape supplier qualification timelines for drug manufacturers. China's NMPA has aligned pharmacopeial standards with ICH Q3D elemental impurity limits, raising compliance costs for non-domestic producers serving Chinese pharmaceutical manufacturers. Stakeholders must monitor evolving pharmacopeial convergence between USP, EP, and ChP standards to anticipate specification-driven procurement shifts.
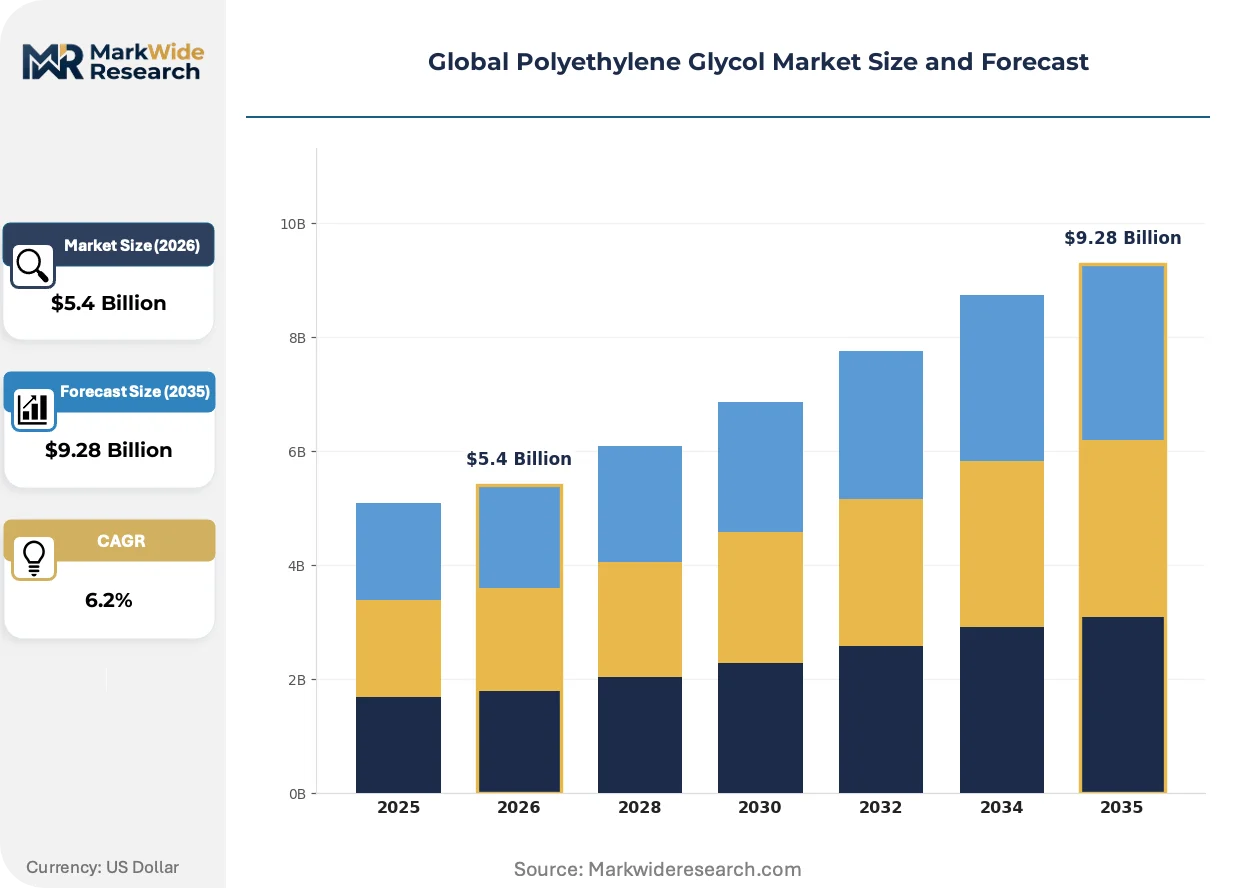
Market Dynamics
Pharmaceutical PEGylation programs are concentrating demand among qualified excipient suppliers capable of meeting tightening pharmacopeial purity specifications across multiple jurisdictions simultaneously.
Growth Catalysts
- Biologics Delivery Expansion:Protein conjugation applications for monoclonal antibodies and peptide therapeutics are pulling high-molecular-weight pharmaceutical grades into chronic disease treatment protocols.
- REACH Registration Tiering:ECHA's differentiated registration requirements for polymer intermediates are streamlining market access for compliant European alkoxylation specialists serving personal care formulators.
- Waterless Beauty Formulation:Korean and Japanese cosmetic manufacturers are integrating PEGylated emollients into solid shampoo and anhydrous skincare products.
Market Restraints
- Ethylene Oxide Feedstock Volatility:Petrochemical cracking economics and regional ethylene supply disruptions transmit directly into PEG production cost structures.
- Alkoxylation Capacity Concentration:Ludwigshafen and Jubail Industrial City host disproportionate shares of pharmaceutical-grade production, creating geographic supply vulnerability.
- Elemental Impurity Compliance Burden:ICH Q3D alignment across USP-NF, EP, and ChP monographs is extending supplier qualification timelines for non-domestic producers.
Strategic Opportunities
- Indian API Producer Integration:CDSCO's harmonization with ICH guidelines is enabling domestic excipient substitution for import-dependent pharmaceutical manufacturers.
- Continuous Processing Technology:Loop reactor alkoxylation systems are reducing batch-to-batch variability and shortening lead times for just-in-time pharmaceutical supply chains.
- Green Chemistry Procurement Mandates:EU Green Deal circular economy requirements are creating preference premiums for bio-based ethylene oxide feedstock pathways.
Industry Challenges
- Specialized Polymer Chemist Scarcity:Ring-opening polymerization expertise and pharmacopeial quality systems knowledge rarely coexist in individual technical personnel.
- Multi-Pharmacopeial Validation Complexity:Simultaneous USP, EP, and ChP certification requirements demand redundant analytical method development and stability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyethylene Glycol Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEG 400, PEG 6000, PEG 1000, PEG 2000, PEG 3350 Application: Pharmaceuticals, Cosmetics, Food Processing, Personal Care, Detergents End User: Pharmaceutical Manufacturers, Cosmetic Producers, Food & Beverage Companies, Industrial Cleaners, Biotechnology Firms Packaging Type: Drums, Bags, Bulk Containers, Totes |
| Companies Covered | Lotte Chemical Corporation, INEOS Holdings AG, Dow Inc., SABIC, Sanyo Chemical Industries Group, BASF SE, Croda International Plc, Merck KGaA, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyethylene Glycol Market Shifts & Advancements
Process intensification and regulatory convergence are compressing supplier qualification timelines while fragmenting procurement authority between quality and sourcing functions.
Continuous loop reactor technology is supplanting traditional batch alkoxylation for pharmaceutical-grade production. European and North American excipient manufacturers are retrofitting existing assets or greenfielding continuous systems to reduce solvent carryover and tighten molecular weight distribution. The technology is supplanting incumbent batch processes by enabling real-time process analytical technology integration that satisfies FDA process validation guidelines with reduced documentation burden.
REACH authorization list expansion for ethylene oxide derivatives is tightening occupational exposure documentation requirements across European manufacturing sites. ECHA's 2023-2024 substance evaluation wave has targeted residual ethylene oxide and 1,4-dioxane impurity thresholds in cosmetic and pharmaceutical applications. German and French alkoxylation facilities are investing in closed-loop handling systems and advanced purification trains to preempt downstream customer audit failures.
Dual-track qualification strategies are separating pharmaceutical and industrial grade supply relationships. Large molecule drug developers are consolidating excipient procurement around suppliers with dedicated pharmaceutical production lines and segregated quality systems. This bifurcation is most pronounced in China where NMPA's 2025 pharmacopeial revision timeline is accelerating domestic API producer migration to qualified local PEG sources.
Global Polyethylene Glycol Market Segmentation
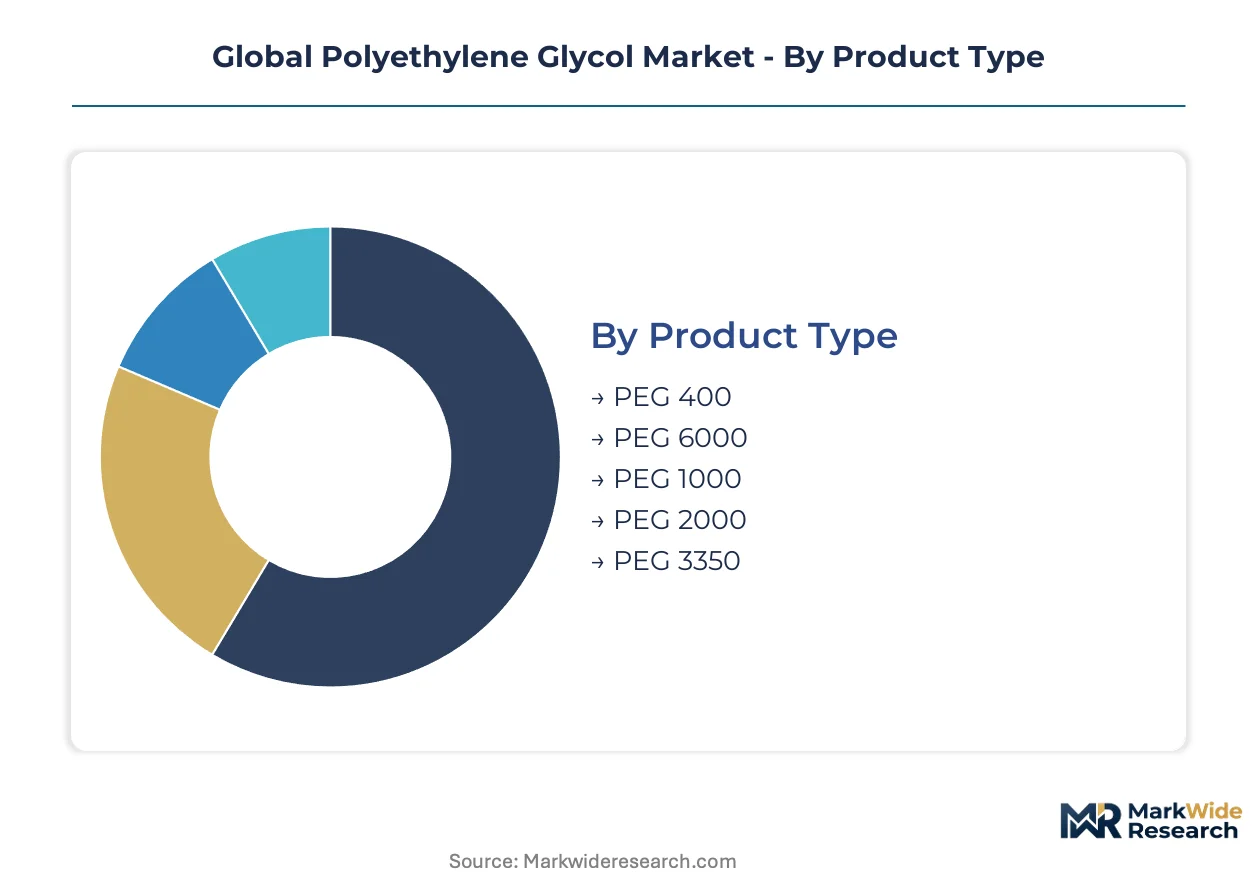
Molecular weight distribution and pharmacopeial grade specifications fragment procurement channels across the polyethylene glycol value chain. Pharmaceutical formulators, cosmetic manufacturers, and industrial processors each demand distinct purity tiers, packaging formats, and documentation packages that reshape supplier-customer relationships.
Product Type:
Channel mix varies sharply by molecular weight, with pharmaceutical distributors capturing high-value grades and industrial chemical houses moving commodity volumes.
- PEG 3350:This mid-range molecular weight grade serves as the backbone of prescription laxative formulations and protein PEGylation protocols for monoclonal antibody delivery. Demand concentrates among FDA-qualified excipient suppliers serving US and European biologics manufacturers facing tightening USP-NF and EP monograph compliance timelines.
- PEG 6000:Higher molecular weight specifications command premium positioning in sustained-release tablet matrices and ophthalmic ointment bases. Korean and Japanese cosmetic formulators are pulling volumes into waterless beauty applications, diverting traditional pharmaceutical allocations.
- PEG 400:Low-viscosity liquid grades flow through industrial chemical distributors into lubricant and surfactant applications.
- PEG 1000:Intermediate viscosity positioning serves cosmetic emulsifier demand across Southeast Asian personal care manufacturing.
- PEG 2000:Specialized pharmaceutical and biotechnology applications require dedicated pharmacopeial documentation packages.
PEG 3350 dominates installed base. PEG 6000 is where expansion concentrates.
Application:
Cost tier stratification separates premium pharmacopeial grades from industrial commodity pricing, with certification burden driving customer switching costs.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications demand simultaneous USP-NF, EP, and ChP certification, extending supplier qualification timelines. Protein conjugation for biologics delivery is concentrating procurement among alkoxylation specialists with dedicated pharmaceutical production lines in Germany, the United States, and China.
- Cosmetics:Korean formulators are integrating PEGylated emollients into solid shampoo and anhydrous skincare products, creating specification divergence from pharmaceutical grades. REACH registration requirements and residual impurity thresholds are reshaping European supply relationships.
- Personal Care:Mass-market formulations tolerate broader molecular weight distributions, opening procurement to industrial-grade suppliers.
- Food Processing:FDA food additive regulations and FSSAI standards in India govern antifoaming and coating applications.
- Detergents:Industrial cleaning formulations prioritize cost efficiency over pharmacopeial documentation.
Pharmaceutical applications anchor value capture. Cosmetics is climbing the fastest.
End User:
Customer type determines contract structure, with biotechnology firms demanding just-in-time flexibility and industrial cleaners accepting volume commitments.
- Pharmaceutical Manufacturers:Large molecule drug developers are consolidating excipient procurement around suppliers with segregated quality systems and continuous processing capabilities. NMPA's pharmacopeial alignment with ICH Q3D is accelerating Chinese API producer migration to qualified domestic PEG sources.
- Biotechnology Firms:Emerging protein therapeutic developers require smaller batch sizes and accelerated stability testing protocols.
- Cosmetic Producers:Korean and Japanese manufacturers are qualifying alternative suppliers to reduce dependence on European alkoxylation capacity.
- Food & Beverage Companies:Antifoaming applications in processing equipment cleaning tolerate broader specification ranges.
- Industrial Cleaners:Detergent and degreaser formulations prioritize feedstock cost over molecular weight precision.
Pharmaceutical manufacturers command supplier attention. Biotechnology firms are gaining procurement leverage.
Packaging Type:
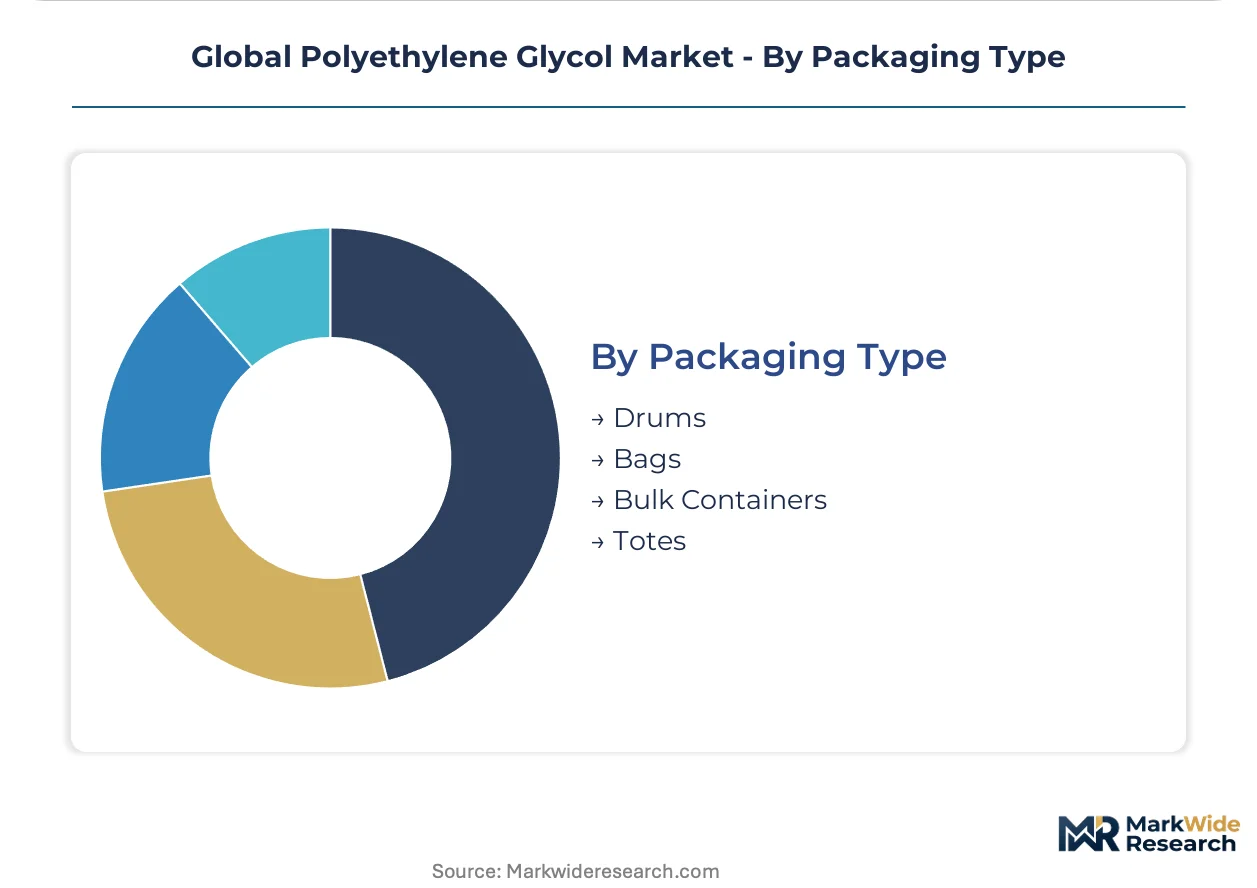
Supply concentration in Ludwigshafen and Jubail Industrial City dictates bulk logistics economics, with drum and tote formats serving dispersed formulators.
- Bulk Containers:Pharmaceutical-grade production at concentrated alkoxylation hubs ships via dedicated bulk logistics to large-scale formulators. German and Saudi Arabian facilities are investing in closed-loop handling systems to satisfy ECHA occupational exposure documentation requirements.
- Drums:Mid-scale cosmetic and personal care manufacturers require drum formats with full pharmacopeial certification packages.
- Totes:Intermediate volume flexibility serves contract manufacturing organizations with variable batch sizes.
- Bags:Food processing and industrial cleaning applications utilize bagged powder grades with reduced documentation burden.
Bulk containers dominate volume throughput. Totes are where format diversification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA pharmacopeial revisions are concentrating pharmaceutical-grade polyethylene glycol demand among qualified domestic suppliers in China, while FDA process validation guidelines shape procurement patterns across North American biologics manufacturers.
China
Domestic API producers are accelerating excipient integration as NMPA aligns pharmacopeial standards with ICH Q3D elemental impurity limits. Yangtze River Delta alkoxylation clusters are expanding pharmaceutical-dedicated production lines to capture substitution demand from import-dependent manufacturers. Shanghai and Jiangsu province facilities are investing in continuous processing capabilities to shorten qualification timelines for local drug developers.
United States
FDA process validation guidelines for excipients are extending supplier qualification timelines for large molecule drug developers. Texas Gulf Coast petrochemical infrastructure feeds backward-integrated PEG production serving biologics manufacturers. Houston-area alkoxylation capacity is retrofitting continuous loop reactor systems to satisfy real-time process analytical technology requirements.
Germany
ECHA REACH authorization list expansion is tightening occupational exposure documentation for residual ethylene oxide and 1,4-dioxane impurities. Ludwigshafen-based alkoxylation capacity anchors European pharmaceutical-grade supply through dedicated production lines with segregated quality systems. BASF SE's Ludwigshafen complex is investing in closed-loop handling systems to preempt downstream customer audit failures.
Japan
PMDA pharmacopeial standards govern excipient purity specifications for protein conjugation applications in monoclonal antibody development. Kansai region cosmetic formulators are pulling PEG 6000 volumes into waterless beauty product lines. Osaka-based manufacturers are qualifying alternative suppliers to reduce dependence on European alkoxylation capacity.
Saudi Arabia
SABIC's petrochemical integration at Jubail Industrial City redirects glycol streams toward differentiated PEG derivatives serving pharmaceutical and personal care markets. SFDA pharmaceutical regulations are aligning with ICH guidelines, creating export qualification pathways for Gulf-produced excipient grades. Jubail facilities are expanding pharmaceutical-dedicated production to capture Middle East and North Africa biologics demand.
Global Polyethylene Glycol Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the polyethylene glycol value chain. Petrochemical-integrated multinationals dominate high-volume industrial grades through captive ethylene oxide feedstock, while specialized alkoxylation specialists capture pharmaceutical premiums through pharmacopeial certification depth. Three archetypes define competitive positioning: backward-integrated petrochemical majors, dedicated pharmaceutical excipient specialists, and regional alkoxylation contractors serving personal care formulators. Capacity expansion and continuous processing technology licensing represent the dominant competitive moves as suppliers race to reduce batch-to-batch variability.
Among petrochemical-integrated majors, Dow Inc., SABIC, and BASF SE exemplify the cost-leadership archetype through upstream control over ethylene oxide feedstock. Dow Inc. leverages North American shale gas economics to secure cost advantages in high-molecular-weight grades. SABIC occupies a position anchoring Middle East supply through Jubail Industrial City integration. BASF SE represents the European technology-leadership vector through Ludwigshafen-based alkoxylation capacity serving multi-pharmacopeial compliance requirements. These three companies sit within the tier that shapes industrial-grade pricing while selectively penetrating pharmaceutical applications through dedicated production line investments.
| Leading Market Players |
|---|
| Lotte Chemical Corporation |
| INEOS Holdings AG |
| Dow Inc. |
| SABIC |
| Sanyo Chemical Industries Group |
| BASF SE |
| Croda International Plc |
| Merck KGaA |
| Clariant AG |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with pharmaceutical manufacturers lock in supply access for high-molecular-weight grades while anchoring price visibility against ethylene oxide feedstock volatility. These contracts tie pricing adjustments to Ludwigshafen and Jubail ethylene oxide benchmarks, insulating qualified suppliers from spot market swings while committing buyers to minimum volume thresholds.
Pricing Analysis
Geographic price spreads between German pharmaceutical-grade production and Chinese industrial-grade output exceed certification-cost differentials alone. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects pharmacopeial documentation burden and molecular weight precision. Pricing pressure stems from REACH registration cost recovery and continuous processing technology investments. Industrial cleaners exhibit highest price sensitivity, while biologics manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for non-integrated formulators sourcing from Ludwigshafen and Jubail Industrial City. Supply concentrates in Germany, Saudi Arabia, and China, with ethylene oxide, ethylene glycol, and alkoxylation catalysts feeding production. Single-source vulnerability runs through concentrated alkoxylation hubs. Distribution runs through pharmaceutical distributors for high-value grades and industrial chemical houses for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and pharmacopeial certification support represent the fastest-expanding revenue layer, outpacing base polymer sales as drug developers outsource supplier qualification documentation.
For Market Incumbents: Fortify multi-pharmacopeial certification depth against emerging Chinese alkoxylation specialists capturing NMPA-aligned demand. Invest in continuous loop reactor retrofits at Texas Gulf Coast and Ludwigshafen facilities to compress batch-to-batch variability. Deepen backward integration into bio-based ethylene oxide feedstock to preempt EU Green Deal procurement mandates. For New Entrants and Emerging Players: Differentiate on accelerated stability testing protocols for biotechnology firms requiring smaller batch sizes. Target Indian API producers migrating from import-dependent excipient supply under CDSCO-ICH harmonization. Deploy just-in-time logistics partnerships with Yangtze River Delta contract manufacturers. For Investors and Strategic Acquirers: Capital is best deployed toward specialized alkoxylation specialists with existing USP-NF and EP certification depth rather than petrochemical-integrated commodity producers. Five-to-ten year viability hinges on pharmacopeial convergence completion and continuous processing technology adoption rates. Monitor NMPA pharmacopeial revision implementation as inflection signal for Chinese domestic substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Retrofit | Loop reactor installation at Houston and Ludwigshafen sites satisfies FDA process analytical technology requirements. |
| Multi-Pharmacopeial Certification | Simultaneous USP-NF, EP, and ChP qualification opens procurement channels for global biologics manufacturers. |
| Backward Integration into Bio-Based Feedstock | Captive bio-ethylene oxide supply secures preference premiums under EU Green Deal circular economy mandates. |
| Pharmaceutical-Dedicated Production Line Segregation | Segregated quality systems bifurcate supply relationships and protect premium grade pricing power. |
| Technical Service Contract Expansion | Supplier qualification documentation outsourcing captures recurring revenue from emerging biotechnology firms. |
Research Methodology
The analysis maps pharmaceutical-grade, cosmetic-grade, and industrial-grade polyethylene glycol production, each validated through excipient procurement managers, alkoxylation plant engineers, and regulatory affairs specialists at drug manufacturers. Primary interviews with FDA-qualified supplier quality directors and CDSCO compliance officers combined with secondary validation against ECHA REACH registration databases, USP-NF monograph revisions, and NMPA pharmacopeial alignment notices. Bottom-up capacity modeling and top-down demand estimation triangulated market sizing.
Consistency checks against ethylene oxide derivative trade flows and pharmaceutical excipient import statistics validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include molecular weight tier, pharmacopeial certification level, end-use industry, and regional production hub. CAGRs derived from ethylene oxide feedstock cost trajectory analysis and biologics PEGylation program expansion rates. Forecast inputs incorporated continuous processing technology adoption curves and multi-pharmacopeial convergence timelines.
Material uncertainties — ethylene oxide supply disruptions, ICH Q3D implementation delays, or REACH authorization list expansion — sit outside the modeled envelope. Forecasts reflect assumptions about pharmacopeial standard convergence and continuous processing technology diffusion. Recalibration cycles align with material shifts in NMPA regulatory implementation and EU Green Deal procurement mandate enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Plastisols Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Resin Cement for Luting Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Nylon 66 Market