
 Anti-Block Additives Market | 2026-2036
Anti-Block Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Block Additives Market Analysis
Specialty chemical distribution channels serving film converters is reconfiguring as regional compounders bypass traditional distributors to secure direct additive supply agreements. Evonik Industries AG leverages its silica technology portfolio to sustain premium positioning among European packaging film producers. BASF SE anchors its competitive stance through backward integration into polymer-grade additive synthesis. Croda International PLC differentiates via bio-based anti-block formulations targeting brand-owner sustainability mandates.
Anti-block additives are surface-modifying agents, typically inorganic silica or organic amide compounds, incorporated at 500–5000 ppm loading levels to reduce coefficient of friction between adjacent polymer film layers and prevent blocking during roll storage and unwinding. Polyethylene-grade anti-block additives dominate volume consumption due to the resin's ubiquity in flexible food and industrial packaging films. Powder and granule forms command the largest share of current demand, though liquid concentrates are gaining traction in high-speed cast film lines where dosing precision and dust reduction matter. Films application segment leads value capture, with multilayer barrier structures driving specification intensity for migration-compliant additive systems.
REACH registration requirements and EU Packaging and Packaging Waste Regulation migration limits shape product development priorities for additive suppliers seeking European market access. FDA food contact notifications and ISO 10993 biocompatibility pathways govern qualification for pharmaceutical and medical film applications in the United States. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and brand-owner circularity pledges, as these will increasingly dictate acceptable additive chemistries and recyclability certification requirements.
Market Dynamics
Blown film capacity expansion across Asia-Pacific is compressing additive specification cycles, forcing suppliers to reconcile migration-compliant formulations with cost-down pressures from high-volume converters.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening migration limits for plastic additives compel film producers to upgrade anti-block systems, creating specification intensity for compliant masterbatches.
- Silica-based masterbatch technology:Advanced surface-treated precipitated silica grades enable lower loading levels without sacrificing anti-block performance, reducing total additive cost per ton of film.
- China:Domestic blown film capacity expansion drives concentrated additive consumption as local converters scale multilayer barrier film production for food packaging.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene resin price swings compress converter margins, reducing willingness to pay premium additive prices even for performance benefits.
- Specialty silica supply concentration:High-purity precipitated silica production clusters in limited manufacturing locations, exposing film compounders to logistics bottlenecks and extended lead times.
- Organic amide thermal stability ceiling:Erucamide and oleamide anti-blocks face performance degradation above standard polyethylene processing temperatures, constraining their use in high-speed cast film lines.
Strategic Opportunities
- India:Underpenetrated flexible packaging conversion capacity presents white space for anti-block masterbatch localization as BIS standards harmonize with global migration protocols.
- Pharmaceutical blister films:ISO 10993 biocompatibility pathways for medical-grade anti-blocks remain sparsely contested, offering premium positioning for qualified suppliers.
- Direct supply agreements:Regional compounders bypassing traditional distributors to secure captive additive supply create channel restructuring opportunities for technology-integrated suppliers.
Industry Challenges
- Migration testing protocol complexity:Multi-jurisdiction food contact compliance requires parallel qualification studies for REACH, FDA, and emerging state-level extended producer responsibility frameworks.
- Recyclability certification alignment:Brand-owner circularity pledges demand additive chemistries compatible with mechanical recycling streams, yet standardized test methods remain under development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Block Additives Market |
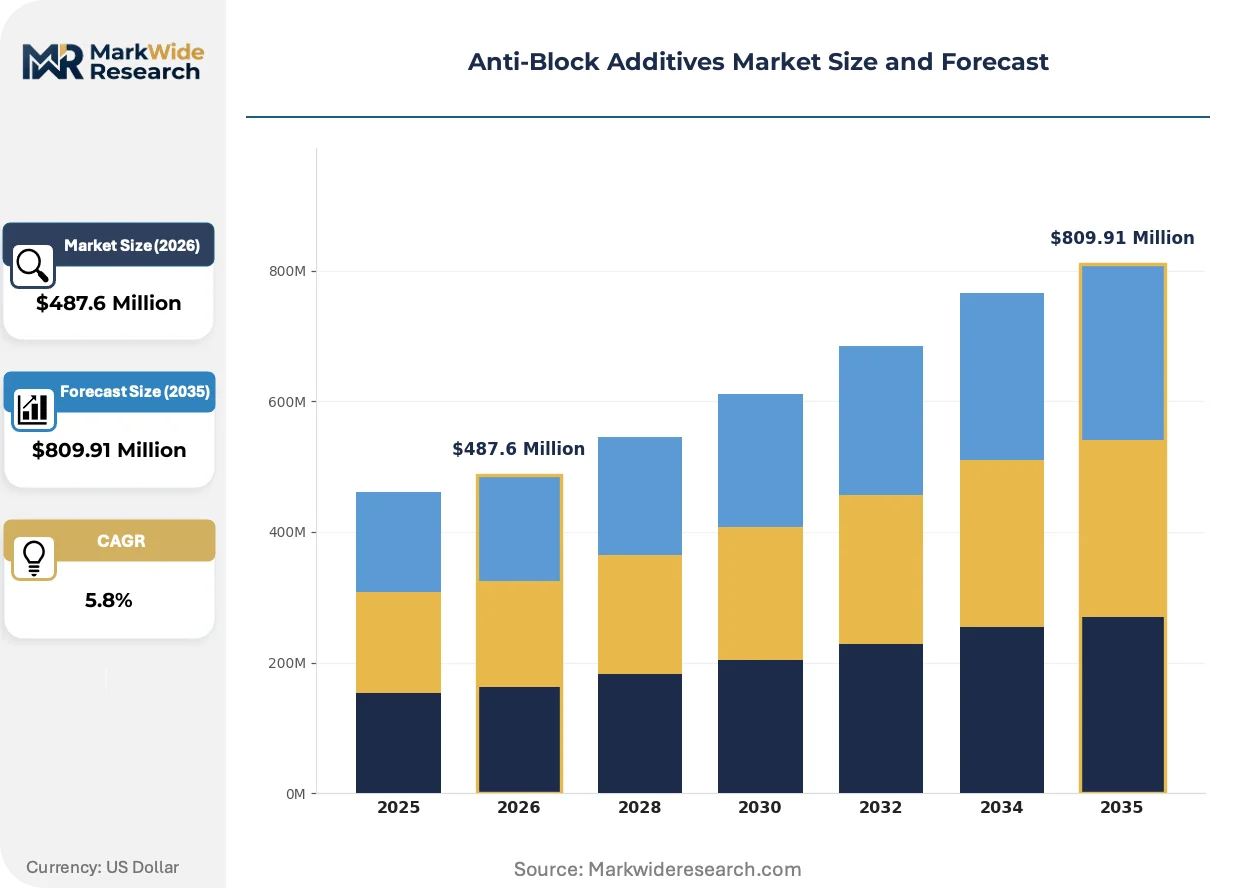
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Others End Use Industry: Packaging, Textiles, Consumer Goods, Automotive Form: Liquid, Powder, Granules, Concentrates Application: Films, Coatings, Sheets, Compounds |
| Companies Covered | Ampacet Corporation, Evonik Industries AG, BASF SE, Honeywell International Inc., Imerys, LyondellBasell Industries Holdings B.V., Croda International PLC, Clariant AG, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Block Additives Market Emerging Trajectories
Active reformulation of anti-block systems is compressing traditional technology boundaries, as migration compliance, processing efficiency, and circular economy compatibility converge in specification requirements.
Surface-modified silica-organic hybrid anti-block systems are hybridizing conventional inorganic and amide chemistries into single-masterbatch solutions. High-speed cast film producers in Germany and Italy are adopting these grades at accelerated specification cycles. This convergence is hybridizing the previously distinct premium silica and economy amide market tiers into intermediate performance categories.
REACH registration dossier updates for existing anti-block substances are tightening toxicological data requirements for sub-1000 ppm migration thresholds. European compounders face reformulation costs for legacy erucamide-based systems that marginally exceed revised specific migration limits. Pharmaceutical and medical film segments are most affected, with converters accelerating ISO 10993 biocompatibility studies to preempt regulatory disqualification.
Film converters are consolidating additive procurement through direct technical partnerships with regional masterbatch compounders, displacing traditional distributor intermediaries. This channel restructuring concentrates in China's Yangtze River Delta and Pearl River Delta manufacturing clusters. Food packaging multinationals with captive film operations are driving this behavioral shift, prioritizing formulation co-development over spot purchasing.
Anti-Block Additives Market Segmentation
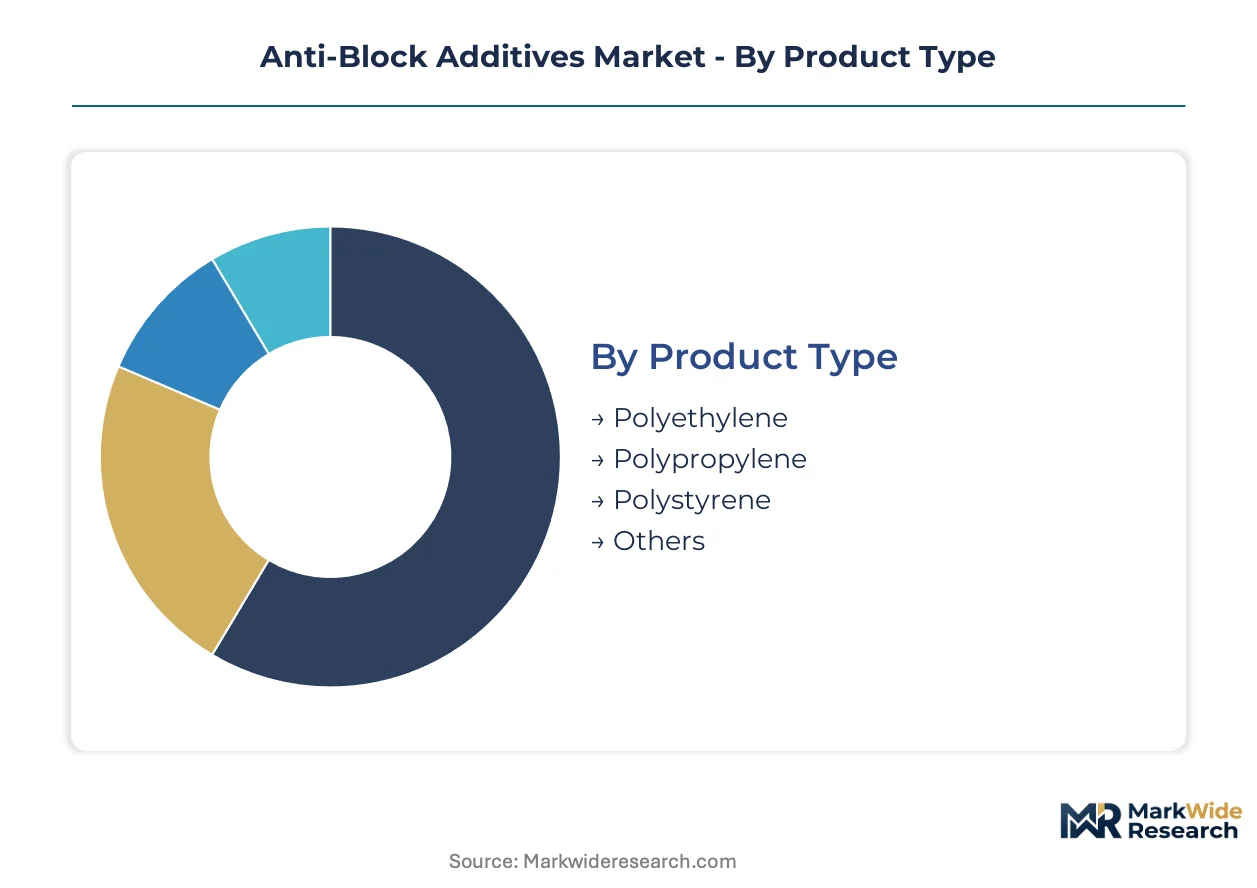
Anti-block additive specifications diverge sharply across polymer chemistries, processing methods, and end-use compliance requirements. Film converters select additive systems based on migration limits, thermal stability thresholds, and recyclability mandates rather than commodity pricing alone.
Product Type:
Polyolefin compatibility requirements span blown film, cast film, and extrusion coating operations with distinct thermal and optical specifications.
- Polyethylene:Linear low-density and high-density grades absorb the majority of silica-based and organic amide anti-block loadings. Food packaging multilayers in China's Yangtze River Delta drive concentrated specification intensity for migration-compliant masterbatches.
- Polypropylene:Biaxially oriented film applications demand higher thermal stability than polyethylene, favoring surface-modified precipitated silica over erucamide derivatives. Cast PP lines in Italy and Germany specify hybrid organic-inorganic systems for clarity retention.
- Polystyrene:Crystal and impact grades use lower anti-block loadings due to inherent brittleness and limited film applications.
- Others:Engineering thermoplastics and biopolymers require specialized additive compatibility testing.
The dominant share belongs to Polyethylene, while Polypropylene is closing the gap fastest.
End Use Industry:
Customer procurement patterns separate compliance-driven premium specifications from cost-optimized commodity purchasing.
- Packaging:Flexible food and industrial films constitute the core demand pool, with multilayer barrier structures requiring REACH and FDA dual-registered additive systems. Extended producer responsibility frameworks in Germany and France are forcing reformulation of legacy erucamide-based masterbatches.
- Textiles:Nonwoven and fiber applications use anti-blocks at lower loadings for processing lubricity rather than film unwinding performance.
- Consumer Goods:Personal care and household product films prioritize optical clarity and low odor specifications.
- Automotive:Interior trim films and surface protection applications specify UV-stable anti-block grades with low volatility.
Packaging commands the largest volume position, though Automotive specifications are expanding most quickly.
Form:
Physical delivery formats align with converter dosing equipment, dust exposure limits, and precision requirements.
- Powder:Untreated and surface-coated silica powders remain the lowest-cost option for compounders with dust collection systems. Pearl River Delta masterbatch producers specify powder grades for captive blending operations.
- Granules:Dust-free handling and consistent feeding characteristics position granules as the default for automated high-speed lines. German blown film converters specify granule masterbatches for migration-critical food contact applications.
- Liquid:Pumpable concentrates enable precise dosing in cast film lines where temperature sensitivity limits solid additive use.
- Concentrates:High-loading masterbatches reduce transport costs and warehouse footprint for large-volume converters.
Granules hold the leading position, while Liquid formats are gaining share fastest in cast film segments.
Application:
Surface area-to-mass ratios and contact compliance requirements differentiate additive specification intensity across finished goods.
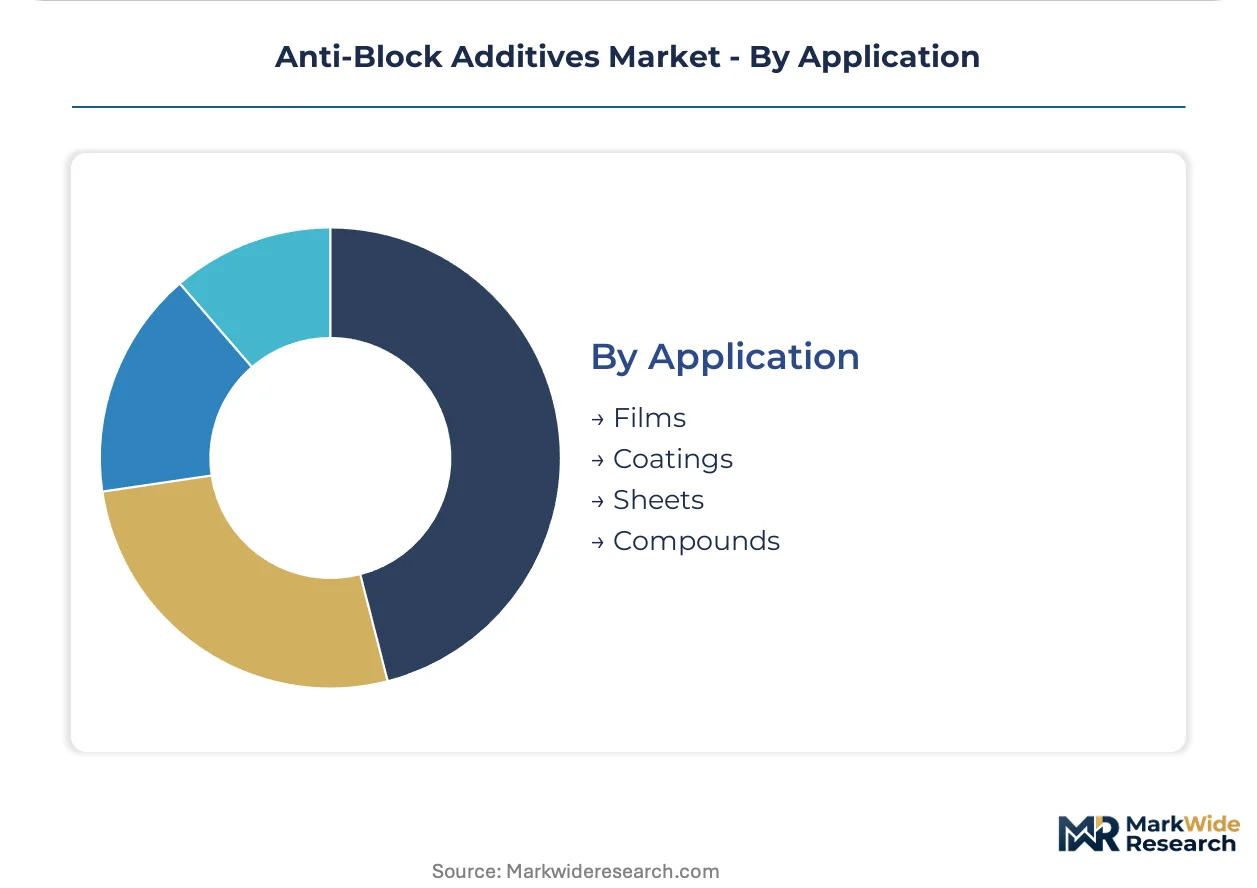
- Films:Multilayer flexible packaging, shrink films, and stretch films represent the specification apex, with food contact layers demanding sub-1000 ppm migration thresholds under REACH updates. Yangtze River Delta converters are consolidating procurement through direct compounder partnerships.
- Coatings:Extrusion and lamination coatings use anti-blocks at reduced loadings for slip control rather than blocking prevention.
- Sheets:Thermoforming and printing substrates require balanced anti-block and anti-static performance.
- Compounds:Pre-colored and pre-modified resin systems incorporate anti-blocks during compounding rather than film extrusion.
Films dominate value capture, with Coatings trailing but climbing fastest in medical packaging applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration requirements anchor European demand for migration-compliant anti-block systems, while China's blown film capacity expansion concentrates volume consumption. Regional regulations and industrial clustering reshape procurement patterns across major manufacturing centers.
China
Domestic blown film capacity expansion in the Yangtze River Delta and Pearl River Delta drives concentrated additive consumption. GB standards for food contact materials tighten migration testing protocols, forcing reformulation of legacy masterbatches. Suzhou and Dongguan masterbatch producers are consolidating procurement through direct technical partnerships with silica suppliers.
Germany
Multilayer barrier film producers in Bavaria and North Rhine-Westphalia specify REACH-registered hybrid organic-inorganic systems. The EU Packaging and Packaging Waste Regulation compels converters to replace erucamide-based additives nearing revised migration limits. KBA oversight of automotive interior trim films extends anti-block qualification to UV-stable, low-volatility grades.
United States
Flexible food packaging converters in the Midwest and Southeast balance FDA food contact notifications with state-level extended producer responsibility frameworks. High-speed cast film lines in Ohio and Georgia adopt liquid concentrate dosing systems for precision and dust reduction. Pharmaceutical blister film manufacturers in New Jersey and North Carolina accelerate ISO 10993 biocompatibility studies.
India
Underpenetrated flexible packaging conversion capacity in Maharashtra and Gujarat presents localization opportunities for anti-block masterbatch producers. BIS standards harmonization with global migration protocols reduces technical barriers for imported formulation technology. Mumbai and Ahmedabad film converters are scaling multilayer production for domestic food brands.
Italy
Cast polypropylene film specialists in Lombardy and Emilia-Romagna specify surface-modified precipitated silica for clarity retention in biaxially oriented applications. ECHA dossier updates for existing substances tighten toxicological data requirements for sub-1000 ppm thresholds. Milan and Bologna converters are adopting hybrid anti-block systems at compressed specification cycles.
Anti-Block Additives Market Vendor Landscape
Integrated chemical conglomerates and specialty additive specialists split the market along technology ownership and application focus lines. The vendor base concentrates around silica technology control, polymer-grade synthesis capability, and bio-based formulation expertise. Three archetypes dominate: backward-integrated resin producers with captive additive supply, precipitated silica technology owners with surface modification IP, and sustainability-focused formulators with bio-based portfolios. Capacity expansion in Asia-Pacific and direct supply agreement restructuring constitute the dominant competitive moves.
Among European chemical conglomerates, Evonik Industries AG and BASF SE exemplify contrasting strategic positions. Evonik leverages its silica technology portfolio to sustain premium positioning among packaging film producers requiring migration-compliant systems. BASF anchors its stance through in-house production of polymer-grade additive synthesis, securing feedstock control for high-volume masterbatch operations. Croda International PLC represents the sustainability-focused archetype, differentiating via bio-based formulations targeting brand-owner circularity mandates. Specialty distributors serving regional compounders face displacement as direct supply agreements reconfigure channel economics.
| Leading Market Players |
|---|
| Ampacet Corporation |
| Evonik Industries AG |
| BASF SE |
| Honeywell International Inc. |
| Imerys |
| LyondellBasell Industries Holdings B.V. |
| Croda International PLC |
| Clariant AG |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on high-purity precipitated silica from select European and Chinese manufacturing clusters determines both pricing tier spreads and supply chain shape, as converters face simultaneous pressure to secure migration-compliant grades while managing total additive cost per ton of film. This structural concentration compresses margin flexibility for compounders caught between resin price volatility and specification intensity from food packaging multinationals.
Pricing Analysis
Configured-to-order pricing for REACH-registered hybrid organic-inorganic systems commands substantial premiums over standard erucamide-based masterbatches, with price differentiation driven by certification grade and customization level. Three-tier pricing structure across premium, standard, and economy levels stratifies according to migration compliance thresholds and thermal stability specifications. Pricing pressure stems from polyethylene resin margin compression in Asia-Pacific, forcing converters to resist additive premiums even for performance benefits. High-volume blown film producers in China's Yangtze River Delta exhibit greatest price sensitivity, while pharmaceutical blister film manufacturers in New Jersey and North Carolina demonstrate lowest sensitivity due to ISO 10993 biocompatibility requirements.
Supply Chain Analysis
Upstream feedstock control over polymer-grade additive synthesis concentrates among integrated chemical conglomerates in Germany, China, and the United States, with high-purity precipitated silica production anchored in select European and Asian manufacturing locations. Raw material dependencies span petrochemical-derived oleamide precursors, sodium silicate for silica precipitation, and surface modification chemistries for hybrid systems. Supply chain risk centers on logistics bottlenecks from specialty silica supply concentration, exposing compounders to extended lead times during regional disruptions. Distribution runs through direct technical partnerships between regional masterbatch compounders and silica technology owners, displacing traditional distributor intermediaries in China's manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anti-block additive demand tracks cyclical recovery in flexible packaging capital expenditure, with blown film capacity expansion in Asia-Pacific providing the named cyclical driver justifying medium-term volume growth assumptions.
For Market Incumbents: Harden silica technology IP positions through surface modification patent filings and captive precipitated silica supply agreements, defending against specialty chemical distributors attempting direct supply restructuring. Prioritize backward integration into sodium silicate feedstocks to secure margin control against petrochemical volatility eroding converter willingness to pay premium prices. For New Entrants and Emerging Players: Pharmaceutical blister film applications in North Carolina and New Jersey represent the most penetrable entry point given sparse ISO 10993 biocompetition and premium pricing tolerance. India's underpenetrated flexible packaging conversion capacity in Maharashtra and Gujarat offers secondary white-space as BIS standards harmonize with global migration protocols. A technical partnership model with regional compounders bypasses distributor channel capture and accelerates specification cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precipitated silica technology owners with surface modification IP and established REACH registration dossiers. Long-term viability over the next decade hinges on recyclability certification alignment as brand-owner circularity pledges harden into mechanical recycling compatibility requirements. Watch for ECHA dossier updates tightening sub-1000 ppm migration thresholds as the inflection signal triggering accelerated reformulation demand and premium capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate Feedstocks | Captive raw material supply secures margin control against petrochemical price volatility affecting converter economics. |
| REACH Registration Dossier Updates | Proactive toxicological data submission preempts regulatory disqualification under tightened migration thresholds. |
| Direct Technical Partnerships with Regional Compounders | Channel restructuring in China's Yangtze River Delta manufacturing clusters displaces traditional distributor intermediaries. |
| ISO 10993 Biocompatibility Qualification | Medical-grade certification opens premium positioning in pharmaceutical blister film segments with sparse competition. |
| Surface-Modified Silica-Organic Hybrid Development | Hybrid systems compress specification cycles for high-speed cast film producers in Germany and Italy demanding clarity retention. |
Methodological Framework
A standing panel of masterbatch plant managers, flexible packaging procurement leads at food multinationals, distribution channel partners, and technical R&D directors at silica suppliers provided ongoing calibration across the study period. Primary interview findings triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and REACH registration dossier updates. Bottom-up additive consumption estimates from film converter capacity data reconciled with top-down market sizing from supplier revenue disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning polymer chemistry, end-use compliance tier, physical delivery format, and regional production hub. CAGRs derived from fitted growth curves incorporating blown film capacity expansion schedules, regulatory implementation timelines, and brand-owner circularity pledge acceleration. Industry-specific forecast inputs included multilayer barrier film specification intensity indices and masterbatch localization investment pipelines.
Practitioners should monitor ECHA migration limit revisions, state-level extended producer responsibility framework implementations, and polyethylene resin margin compression for early signals requiring forecast adjustment. Cross-checking against customs trade data for anti-block additive import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Feed Additives Market
Additives
Liquid Thickeners Market
Additives
Tragacanth Market
Additives
Chitosan Powder Market
Additives
Global Isosorbide Market
Additives
South Africa Acidulants Market
Additives
Global Performance Additives Market
Additives
Global Ester Gum Market
Additives
Disodium Inosinate Market
Additives
Indonesia Feed Additives Market
Additives
Adjustive Agents Market
Additives
Global PVC Stabilizer Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Polyols and Sorbitols Products Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Automotive Coolant Additives Market