
 Hydrophobic Interaction Chromatography Resins Market | 2026-2036
Hydrophobic Interaction Chromatography Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrophobic Interaction Chromatography Resins Market Foresight
Omnichannel distribution for chromatography resins is tilting toward direct manufacturer partnerships with large biopharma accounts. Bio-Rad Laboratories leverages its regional distribution centers to secure proximity supply contracts with North American biotech clusters. Thermo Fisher Scientific anchors global fulfillment through its integrated life sciences logistics network. Sartorius AG specializes in application-specific resin consultation bundled with hardware platforms, differentiating its channel approach from catalog-centric competitors.
Hydrophobic interaction chromatography resins are porous or non-porous media functionalized with aliphatic or aromatic ligands that bind proteins via reversible hydrophobic associations at high ionic strength, then release targets upon salt gradient elution. Their primary commercial purpose lies in polishing steps during monoclonal antibody purification, where they remove aggregates and host cell proteins with orthogonal selectivity to ion exchange methods. Polymer-based resins lead the product type landscape due to superior pressure stability and broader pH tolerance, while agarose variants occupy premium niches demanding lowest nonspecific binding. Preparative grade dominates value capture given batch manufacturing scale, though analytical grade sustains method development pull-through revenue.
FDA biologics licensing requirements and EMA good manufacturing practice frameworks govern resin extractables, leachables documentation, and lot-to-lot consistency. ISO 9001 quality management and USP <661> plastic packaging standards further constrain supplier qualification pathways. REACH registration obligations in Europe add compliance overhead for resin chemistries imported from non-EU manufacturing sites. Stakeholders must monitor evolving regulatory harmonization between FDA process validation guidance and EMA ICH Q5A viral safety expectations, as divergence would fragment resin qualification protocols across manufacturing geographies.
Market Dynamics
Monoclonal antibody purification complexity is intensifying resin performance demands as biologics pipelines shift toward bispecific and fusion protein formats requiring orthogonal polishing steps.
Growth Catalysts
- FDA Process Validation Guidance:Biologics manufacturers must demonstrate consistent impurity clearance profiles, forcing upgrades to high-resolution HIC resins with documented lot-to-lot consistency.
- Continuous Bioprocessing Adoption:Perfusion cell culture systems generate higher titers and aggregate loads, expanding HIC resin volumes for intermediate and final polishing operations.
- China Biologics Manufacturing Expansion:NMPA domestic innovation incentives and CDMO cluster development in Suzhou and Shanghai are accelerating resin procurement from international and local suppliers.
Market Restraints
- Protein A Capture Dominance:Affinity chromatography's established position in mAb platforms limits HIC resin penetration to downstream polishing rather than primary capture steps.
- Raw Material Concentration:Agarose base matrix supply concentrates in Scandinavian and Japanese seaweed processing facilities, creating geographic vulnerability for natural polymer resin production.
- REACH Registration Burden:ECHA compliance costs for novel ligand chemistries imported from non-EU manufacturing sites deter resin innovation and delay product launches.
Strategic Opportunities
- India Biosimilar Manufacturing:CDSCO accelerated approval pathways and PLI scheme incentives for biologics production create resin demand from emerging domestic manufacturers.
- Single-Use Chromatography Integration:Pre-packed HIC columns converging with disposable downstream processing eliminate cleaning validation requirements and reduce batch turnaround times.
- Gene Therapy Vector Purification:AAV and lentiviral vector manufacturing requires aggregate removal methods compatible with large biomolecular targets, opening adjacent application space.
Industry Challenges
- Resin Lifetime Validation:FDA and EMA require extensive cycling studies to establish resin reuse limits, extending qualification timelines and consuming development resources.
- Extractables Documentation:USP <661> and <1661> standards mandate comprehensive leachables profiles for each resin-solvent combination, fragmenting supplier qualification protocols.
- Method Transfer Complexity:Scale-up from analytical to preparative HIC demands reoptimization of salt gradients and linear velocities, creating technical bottlenecks for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrophobic Interaction Chromatography Resins Market |
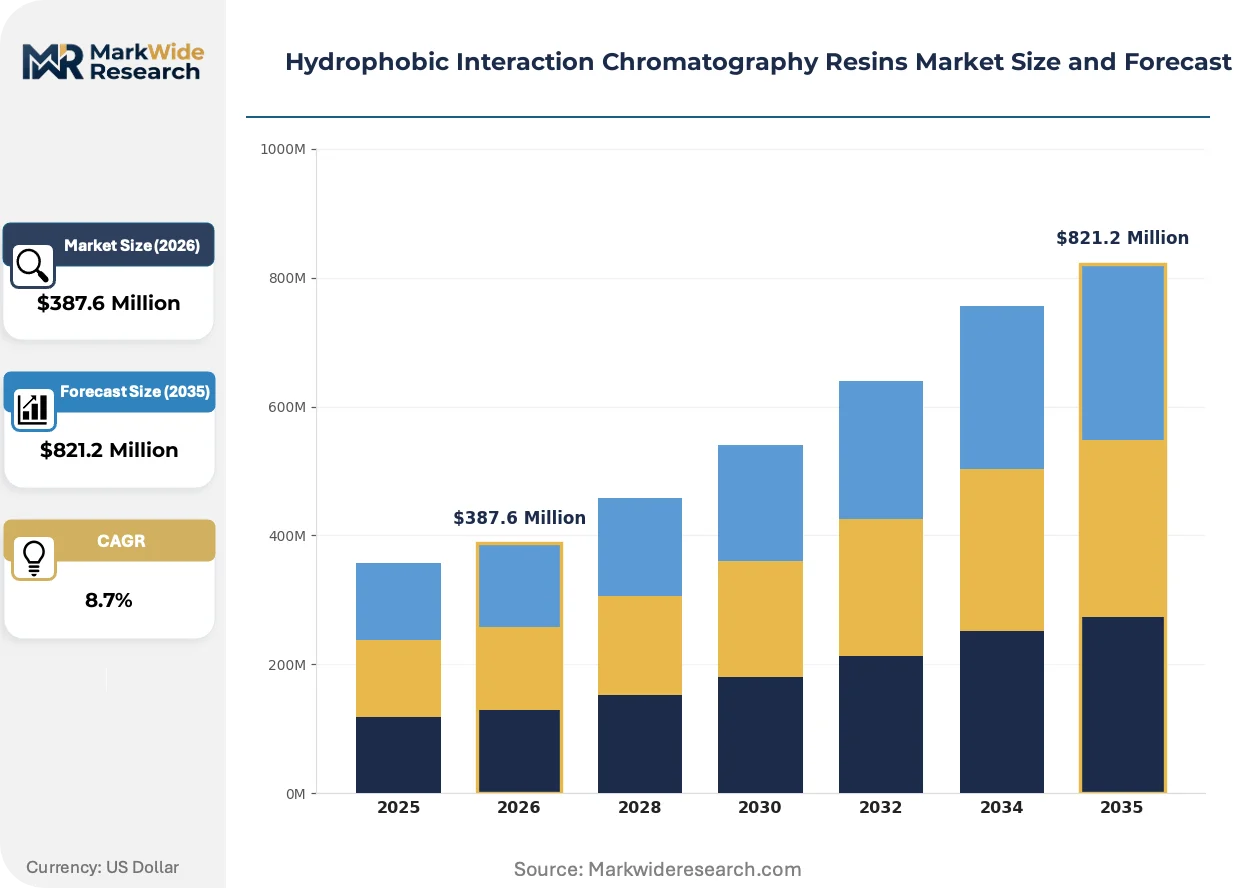
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica, Polymer-based, Agarose, Mixed-mode Grade: Analytical, Preparative, Pilot Scale, Research End User: Pharmaceutical, Biotech, Research Institutions, Chemical Application: Protein Purification, Antibody Production, Downstream Processing, Vaccine Development |
| Companies Covered | Bio-Rad Laboratories, Thermo Fisher Scientific, Sartorius AG, Tosoh Bioscience, Merck KGaA, Cytiva, Danaher Corporation, Agilent Technologies, Purolite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrophobic Interaction Chromatography Resins Market Shifts & Advancements
Resin chemistry and manufacturing formats are evolving to address pressure stability, throughput demands, and regulatory documentation burdens that constrain current purification workflows.
Multimodal HIC resins combining hydrophobic and ionic ligands are migrating from niche aggregate removal applications toward standard polishing protocols. Contract manufacturers in Germany and Switzerland are adopting these hybrid media to reduce column count and buffer consumption. The technology is migrating from specialty biologins toward mainstream mAb platforms as suppliers demonstrate equivalent purity with simplified process trains.
EMA ICH Q5A viral safety expectations are tightening documentation requirements for resin sanitization validation. Manufacturers must now demonstrate clearance of model viruses across multiple reuse cycles with statistical rigor. Small-scale biotech companies in the Netherlands and Denmark are outsourcing these studies to specialized testing laboratories, creating service-layer revenue adjacent to resin sales.
Direct manufacturer partnerships are displacing traditional distributor relationships for large-volume accounts. Biopharma procurement teams in Massachusetts and California are negotiating multi-year resin supply agreements with technical consultation bundled. This consolidation concentrates purchasing power among top-tier manufacturers while fragmenting mid-tier account access.
Hydrophobic Interaction Chromatography Resins Market Segmentation
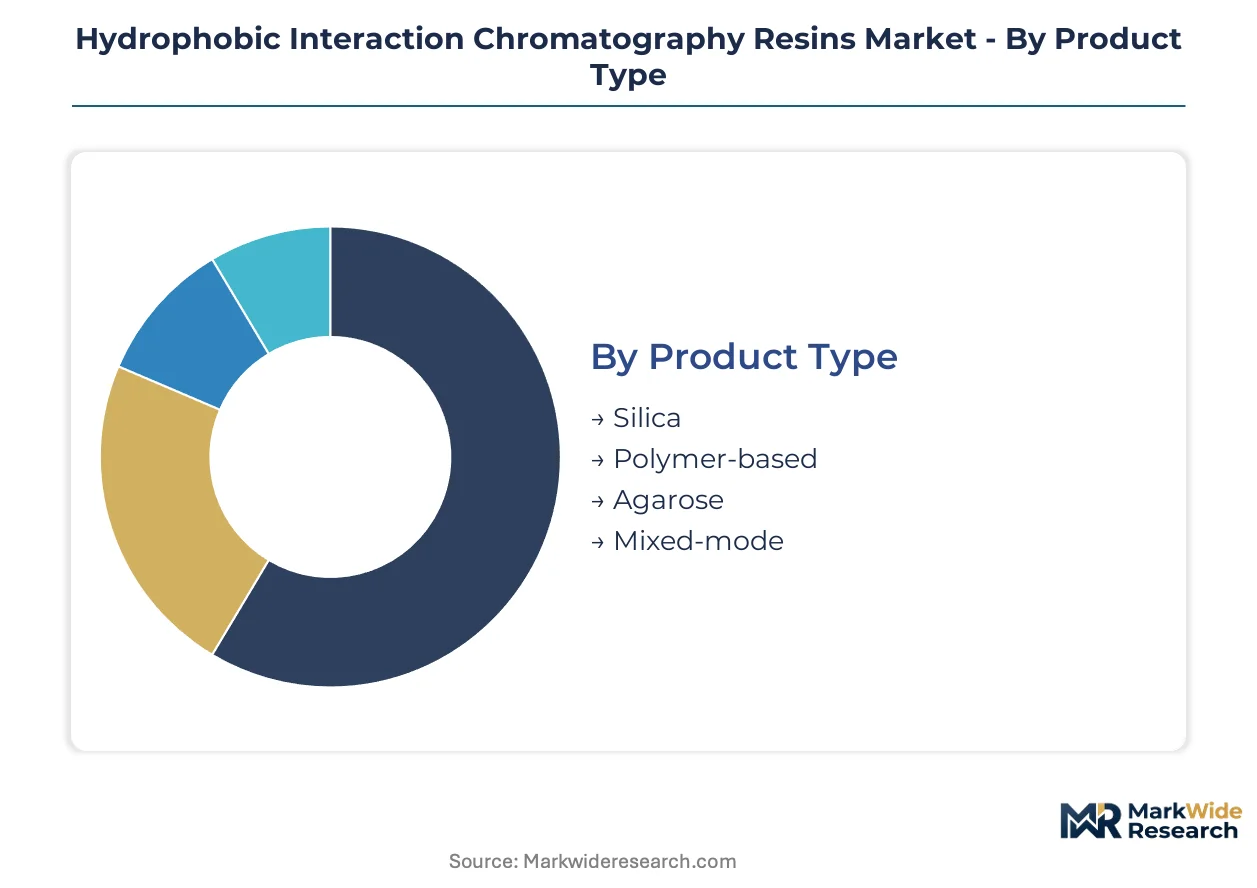
Hydrophobic interaction chromatography resins segment across matrix chemistry, operational scale, end-user sophistication, and therapeutic application. Each dimension carries distinct technical specifications, regulatory documentation requirements, and procurement patterns that shape supplier positioning.
Product Type:
Polymer-based variants occupy the mature center of the technology spectrum while silica and mixed-mode formats represent emerging alternatives with pressure tolerance advantages.
- Polymer-based:Synthetic copolymers deliver superior mechanical stability under high linear velocities demanded by continuous bioprocessing systems. Demand concentrates in Massachusetts and California biotech clusters where FDA process validation guidance mandates documented lot-to-lot consistency for commercial mAb manufacturing.
- Agarose:Natural polysaccharide matrices from Scandinavian seaweed processing offer lowest nonspecific protein binding for sensitive therapeutic targets. Procurement in Germany and Switzerland favors agarose for premium biologins where aggregate removal efficiency outweighs pressure limitations.
- Silica:Inorganic backbone supports higher pressure ratings for rapid cycling applications in analytical method development.
- Mixed-mode:Hybrid ligand chemistries combining hydrophobic and ionic interactions reduce column count in contract manufacturing workflows.
Polymer-based resins handle the majority of throughput; mixed-mode is gaining share fastest as CDMOs consolidate polishing steps.
Grade:
Scale of operation determines validation burden, documentation depth, and pricing tier across the customer base.
- Preparative:Manufacturing-grade resins undergo extensive extractables testing per USP 661 and EMA viral safety protocols. Batch sizes in Suzhou and Shanghai CDMO facilities drive volume procurement with multi-year supply agreements.
- Analytical:Small-scale columns support method development and regulatory submission activities in research institutions. North American biotech clusters source analytical grade for early-stage candidate screening where resin lot traceability precedes scale-up requirements.
- Pilot Scale:Intermediate volumes bridge process development and commercial manufacturing with abbreviated qualification packages.
- Research:Non-GMP grade serves academic laboratories with minimal documentation overhead and fastest delivery cycles.
Preparative grade commands the dominant revenue position; analytical grade shows the steepest expansion trajectory as preclinical pipelines thicken.
End User:
Customer type dictates technical service intensity, contract structure, and regulatory engagement depth.
- Pharmaceutical:Large molecule manufacturers in the United States and Germany negotiate direct partnerships with resin suppliers for integrated hardware-software platforms. FDA biologics licensing requirements force rigorous resin reuse validation studies that consume supplier technical resources.
- Biotech:Emerging developers in the Netherlands and Denmark outsource viral clearance documentation to specialized testing laboratories. Venture-backed companies prioritize pre-packed column formats that eliminate cleaning validation and accelerate IND timelines.
- Research Institutions:Academic centers in China leverage NMPA domestic innovation incentives to build internal purification capabilities.
- Chemical:Industrial enzyme manufacturers apply HIC resins for non-therapeutic protein separations with reduced regulatory scrutiny.
Pharmaceutical accounts anchor procurement volume; biotech represents the most rapid customer segment expansion.
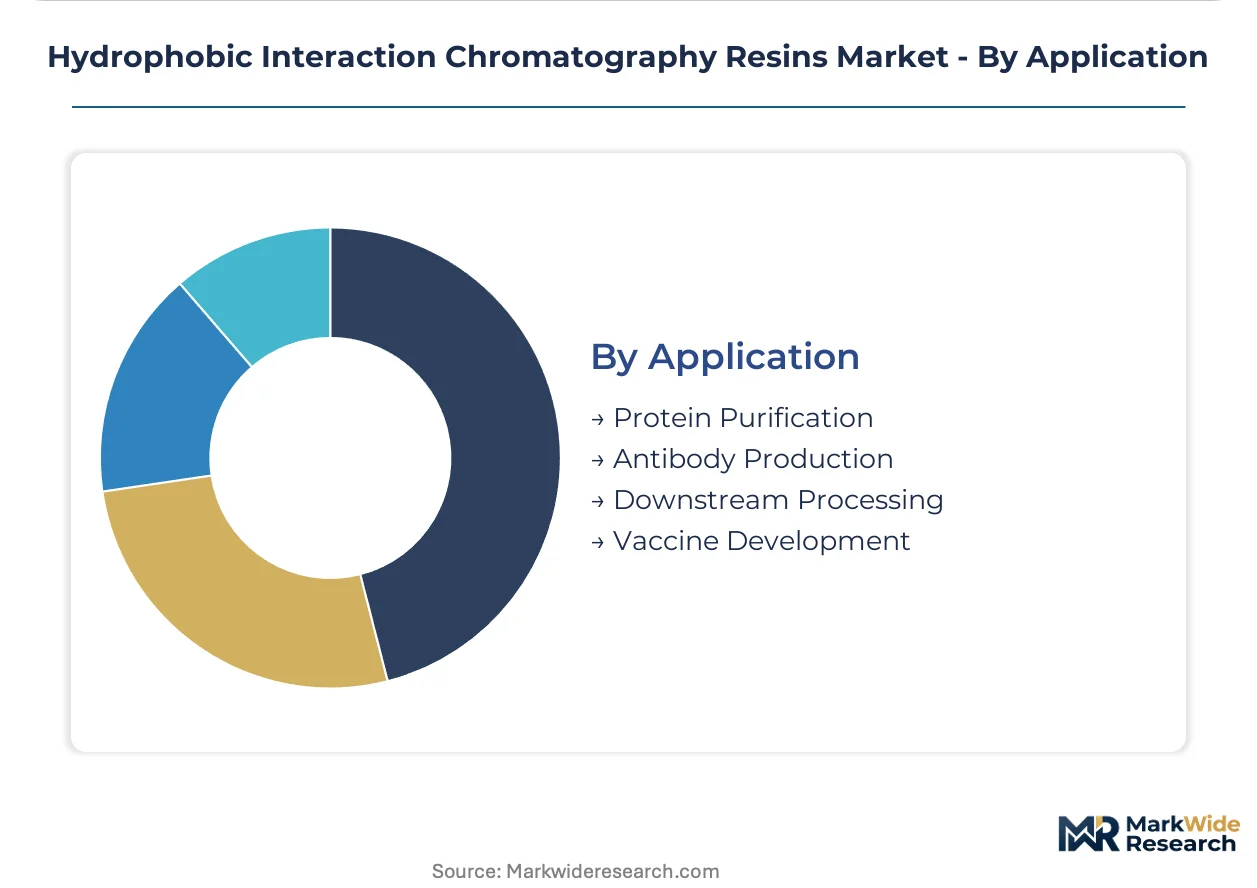
Application:
Therapeutic category determines impurity profile complexity, aggregate load tolerance, and orthogonal step requirements.
- Antibody Production:Monoclonal and bispecific antibody polishing in Massachusetts facilities demands high-resolution aggregate removal orthogonal to Protein A capture. EMA ICH Q5A viral safety expectations tighten documentation for resin sanitization validation across reuse cycles.
- Downstream Processing:Integrated purification trains in German CDMOs combine HIC with ion exchange and mixed-mode steps to reduce buffer consumption. Continuous bioprocessing adoption expands resin volumes as perfusion systems generate higher titer harvests.
- Protein Purification:Recombinant enzyme and cytokine manufacturing in Chinese facilities applies HIC for host cell protein clearance.
- Vaccine Development:Subunit and conjugate vaccine antigen purification employs HIC for endotoxin reduction and aggregate control.
Antibody production consumes the largest resin volumes; downstream processing applications are climbing the fastest on share expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA domestic innovation incentives and CDSCO production-linked incentives are redirecting biologics manufacturing capacity toward Asia-Pacific while FDA process validation guidance and EMA ICH Q5A standards sustain North American and European demand.
United States
FDA biologics licensing requirements force Massachusetts and California biotech clusters to document lot-to-lot resin consistency for commercial mAb manufacturing. Continuous bioprocessing adoption in Greater Boston expands HIC resin volumes as perfusion systems generate higher titer harvests. Procurement teams in Cambridge negotiate multi-year supply agreements with technical consultation bundled.
Germany
EMA good manufacturing practice frameworks govern resin extractables documentation across Baden-Württemberg and Bavaria CDMO facilities. REACH registration obligations constrain novel ligand chemistries imported from non-EU manufacturing sites. Contract manufacturers in Heidelberg specialize in multimodal HIC resins to reduce column count and buffer consumption.
China
NMPA domestic innovation incentives accelerate resin procurement from international and local suppliers across Suzhou and Shanghai biologics clusters. CDMO development in the Yangtze River Delta generates preparative-grade demand with multi-year supply agreements. Local manufacturers leverage government funding to build internal purification capabilities.
India
CDSCO accelerated approval pathways and PLI scheme incentives for biologics production create resin demand from emerging domestic manufacturers in Maharashtra and Gujarat. Biosimilar manufacturing expansion in Hyderabad and Bangalore favors pre-packed column formats that eliminate cleaning validation. Venture-backed companies prioritize analytical-grade resins for early-stage candidate screening.
Switzerland
Swissmedic purity guidelines for biologics tighten resin performance thresholds across Basel and Zurich pharmaceutical manufacturing. Premium biologics producers favor agarose matrices for lowest nonspecific protein binding despite pressure limitations. Contract manufacturers adopt application-specific resin consultation bundled with hardware platforms.
Hydrophobic Interaction Chromatography Resins Market Competitive Landscape
On the supply side, the industry is consolidating around integrated life sciences conglomerates with captive logistics networks and specialized resin consultancies with hardware-software bundling capabilities. Three archetypes dominate: diversified laboratory supply conglomerates with global fulfillment infrastructure, precision separation specialists with application-specific technical services, and regional distribution-anchored proximity suppliers. Competitive moves concentrate on strategic partnerships for continuous bioprocessing integration and portfolio diversification into gene therapy vector purification.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific exemplifies the integrated logistics archetype through its global life sciences fulfillment network. Danaher Corporation and Cytiva occupy positions within the precision separation tier, anchoring application-specific consultation models. Bio-Rad Laboratories represents the regional proximity supplier archetype, securing supply contracts through distribution center density in North American biotech clusters.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Sartorius AG |
| Tosoh Bioscience |
| Merck KGaA |
| Cytiva |
| Danaher Corporation |
| Agilent Technologies |
| Purolite |
| Others |
Supply & Pricing Matrix
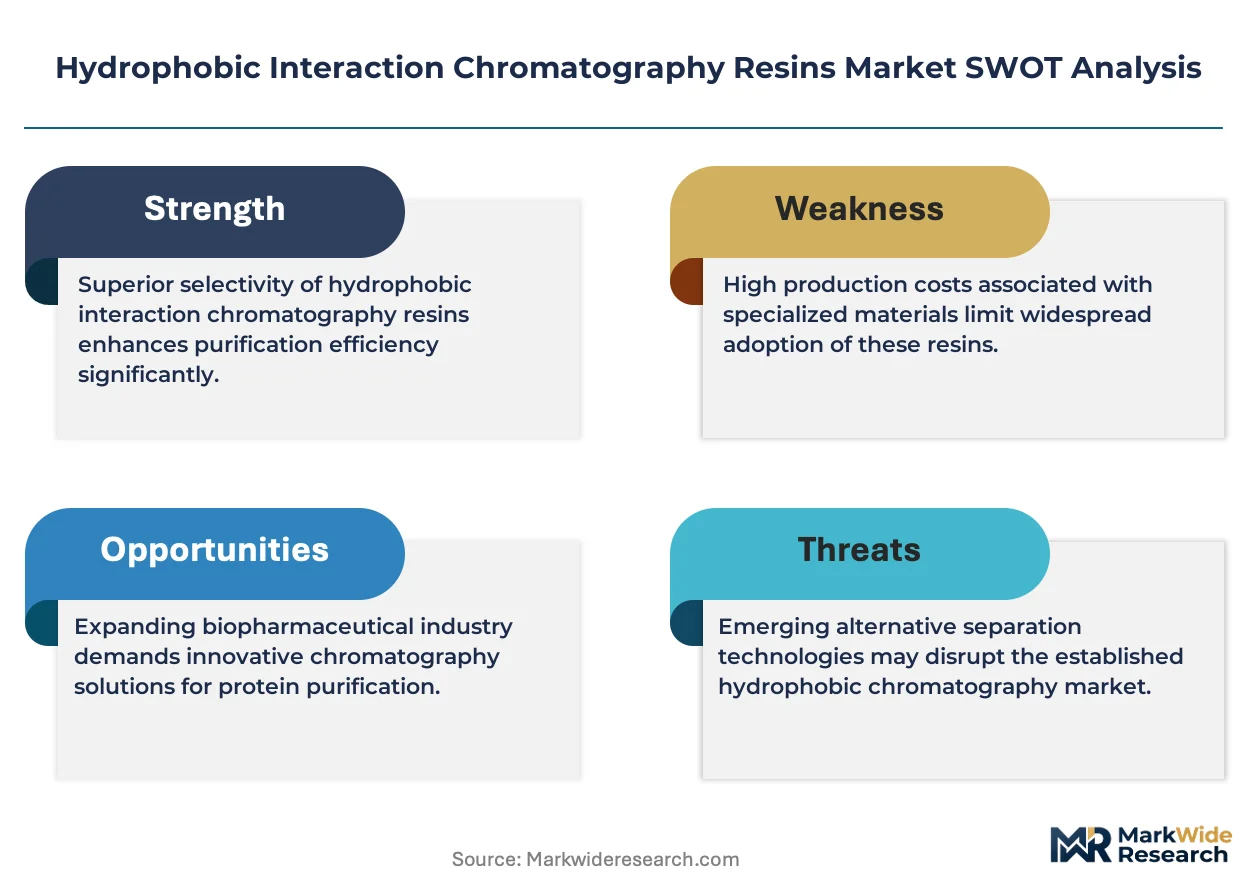
Scandinavian seaweed processing facilities anchor agarose base matrix supply, concentrating pricing power among natural polymer resin producers serving German and Swiss premium biologics manufacturers. This geographic concentration creates asymmetric leverage where downstream biopharma procurement teams absorb cost volatility or switch to synthetic polymer alternatives.
Pricing Analysis
Certification level (FDA-grade, EMA GMP-compliant, ISO 9001) creates the primary spread between resin tiers, with preparative-grade lots commanding substantial premiums over analytical-grade equivalents. Contract-based long-term offtake agreements dominate large-volume pharmaceutical procurement, while research institutions transact on per-unit spot terms. Cost compression in analytical-grade segments is intensifying because CDMO consolidation concentrates purchasing power among fewer accounts. Biotech startups exhibit highest price sensitivity, prioritizing pre-packed column formats that eliminate capital equipment outlays; large molecule manufacturers show lowest sensitivity, absorbing premium pricing for documented lot-to-lot consistency.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for international resin suppliers serving both markets. Manufacturing concentrates in Germany, the United States, and Japan, with agarose raw materials drawing from Scandinavian and Japanese seaweed processing. Ligand chemistries and synthetic polymer backbones rest on petrochemical feedstocks and specialized functionalization reagents. Single-source vulnerability in natural polysaccharide matrices creates geographic concentration risk. Distribution runs through direct manufacturer partnerships for large biopharma accounts, supplemented by regional distribution centers serving mid-tier biotech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopharma procurement consolidation into multi-year supply agreements has shifted bargaining power toward large molecule manufacturers, fragmenting access for mid-tier resin suppliers.
For Market Incumbents: Build regulatory documentation moats by expanding viral clearance validation services and extractables profiling capabilities. Incumbents should deepen captive supply of agarose base matrices to offset Scandinavian supply concentration, while investing in continuous bioprocessing-compatible resin formats to preempt substitution by mixed-mode alternatives. FDA process validation guidance tightening creates barrier reinforcement opportunities. For New Entrants and Emerging Players: India biosimilar manufacturing clusters offer the most penetrable geography, where CDSCO accelerated approval pathways and PLI scheme incentives outpace established supplier coverage. New entrants should target pre-packed analytical-grade column formats for venture-backed biotech companies prioritizing speed-to-IND over customization. Application-specific resin consultation bundled with hardware platforms provides differentiation against catalog-centric competitors. For Investors and Strategic Acquirers: Long-term, this sits as a bioprocessing infrastructure play because downstream purification complexity intensifies across antibody, gene therapy, and cell therapy modalities regardless of therapeutic target. Acquisition candidates include specialized resin consultancies with integrated hardware-software platforms and regional proximity suppliers with dense North American distribution networks. Watch for NMPA domestic innovation incentives accelerating local Chinese manufacturing capacity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Services Expansion | Viral clearance validation outsourcing captures service-layer revenue adjacent to resin sales. |
| Continuous Bioprocessing Format Development | Pressure-stable polymer resins align with perfusion system throughput demands in Massachusetts facilities. |
| Pre-Packed Column Portfolio Launch | Single-use formats eliminate cleaning validation and accelerate batch turnaround for CDMOs. |
| Backward Integration into Base Matrix Supply | Captive agarose production mitigates Scandinavian seaweed processing geographic vulnerability. |
| Gene Therapy Vector Application Development | AAV aggregate removal protocols open adjacent purification market beyond antibody platforms. |
Research Methodology
Cross-validation between primary interviews with downstream processing executives, resin procurement managers, regulatory affairs leads, and CDMO technical directors anchors the qualitative findings. Secondary validation draws from FDA biologics licensing filings, EMA GMP inspection reports, USP documentation standards, and NMPA domestic innovation incentive disclosures. Bottom-up resin volume estimates from biopharma manufacturing capacity data triangulate against top-down market sizing from supplier revenue disclosures.
Calibration against historical capacity expansion announcements and regulatory approval timelines informs the projection framework. The analytical model segments across matrix chemistry, operational grade, end-user sophistication, and therapeutic application, with CAGRs derived from elasticity modeling against biologics pipeline growth. Continuous bioprocessing adoption rates and gene therapy manufacturing capacity buildouts serve as industry-specific demand drivers throughout the forecast period.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic resin manufacturers or disruptive multimodal technology entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Flame Retardant Polyester Resins Market