
 Nylon Resins Market | 2026-2036
Nylon Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon Resins Market Analytics
Modular compounding and regional toll-manufacturing arrangements are recalibrating how buyers source nylon resins across tiers. BASF SE leverages its integrated Ludwigshafen Verbund site to sustain captive caprolactam supply for Nylon 6 grades. DuPont de Nemours Inc anchors its position through specialized Zytel formulations for automotive thermal management. Ascend Performance Materials dominates the North American merchant market with backward integration into adiponitrile and hexamethylenediamine.
Nylon resins comprise thermoplastic polyamides synthesized primarily via ring-opening polymerization of caprolactam or polycondensation of diamine-diacid salts, yielding semi-crystalline materials with melting points between 180°C and 265°C and tensile strengths exceeding 80 MPa in glass-filled grades. These polymers serve as metal replacements in load-bearing automotive, electrical, and industrial components where fatigue resistance and dimensional stability matter. Injection molding applications command the largest volume share, though 3D printing filament formulations represent the fastest-expanding application channel as powder-bed fusion and material extrusion platforms adopt PA11 and PA12 variants for production parts. Nylon 66 maintains premium positioning in under-hood automotive and electrical connector markets due to its higher melting point and lower moisture uptake versus Nylon 6.
EPA fuel-economy standards and NHTSA vehicle safety rules in the United States compel automakers to substitute aluminum and magnesium with glass-reinforced nylon in structural brackets and cooling modules. REACH authorization requirements and the EU Green Deal's circular economy action plan restrict certain additive chemistries and mandate recycled-content thresholds in consumer goods and electronics applications. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in Germany and France, where packaging and automotive end-of-life regulations will determine which nylon grades qualify for closed-loop recycling streams and preferential procurement status.
Market Dynamics
Automotive lightweighting mandates and circular economy regulations are forcing a feedstock transition from virgin petrochemicals toward bio-based and recycled-content nylon grades, compressing traditional polymer economics while opening new supply chain architectures.
Growth Catalysts
- EPA Fuel-Economy Standards:NHTSA vehicle safety rules compel automakers to substitute metal with glass-reinforced nylon in structural brackets and cooling modules across US passenger vehicle platforms.
- 3D Printing Adoption:Powder-bed fusion and material extrusion platforms are consolidating PA11 and PA12 variants for production parts in aerospace tooling and medical device prototyping.
- Yangtze River Delta Concentration:Integrated adipic acid-caprolactam-nylon polymer complexes in East China operate at scale, pulling global demand toward this manufacturing cluster.
Market Restraints
- Adiponitrile Supply Concentration:Merchant market dependence on a handful of hexamethylenediamine producers creates vulnerability in Nylon 66 feedstock security.
- REACH Authorization Friction:ECHA restrictions on certain plasticizers and flame retardants force costly reformulation cycles before products can re-enter EU consumer goods markets.
- Polypropylene Substitution:Lower-cost commodity thermoplastics capture non-structural automotive interior applications where temperature resistance requirements have relaxed.
Strategic Opportunities
- EU Green Deal Mandates:Circular economy action plan recycled-content thresholds create preferential procurement status for post-industrial and post-consumer nylon grades in electronics housings.
- India PLI Scheme:Production-linked incentives for advanced materials manufacturing attract integrated polymer investments serving domestic automotive and electrical component demand.
- Closed-Loop Recycling Infrastructure:Extended Producer Responsibility frameworks in Germany and France determine qualification for automotive end-of-life material recovery streams.
Industry Challenges
- Compounding Technician Scarcity:Specialized skills in reactive extrusion and long-fiber reinforcement processing lag behind capacity expansion timelines in emerging manufacturing regions.
- Multi-Site Certification Complexity:ISO 14001 and IATF 16949 audits across toll-manufacturing networks delay qualification for automotive OEM approved vendor lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon Resins Market |
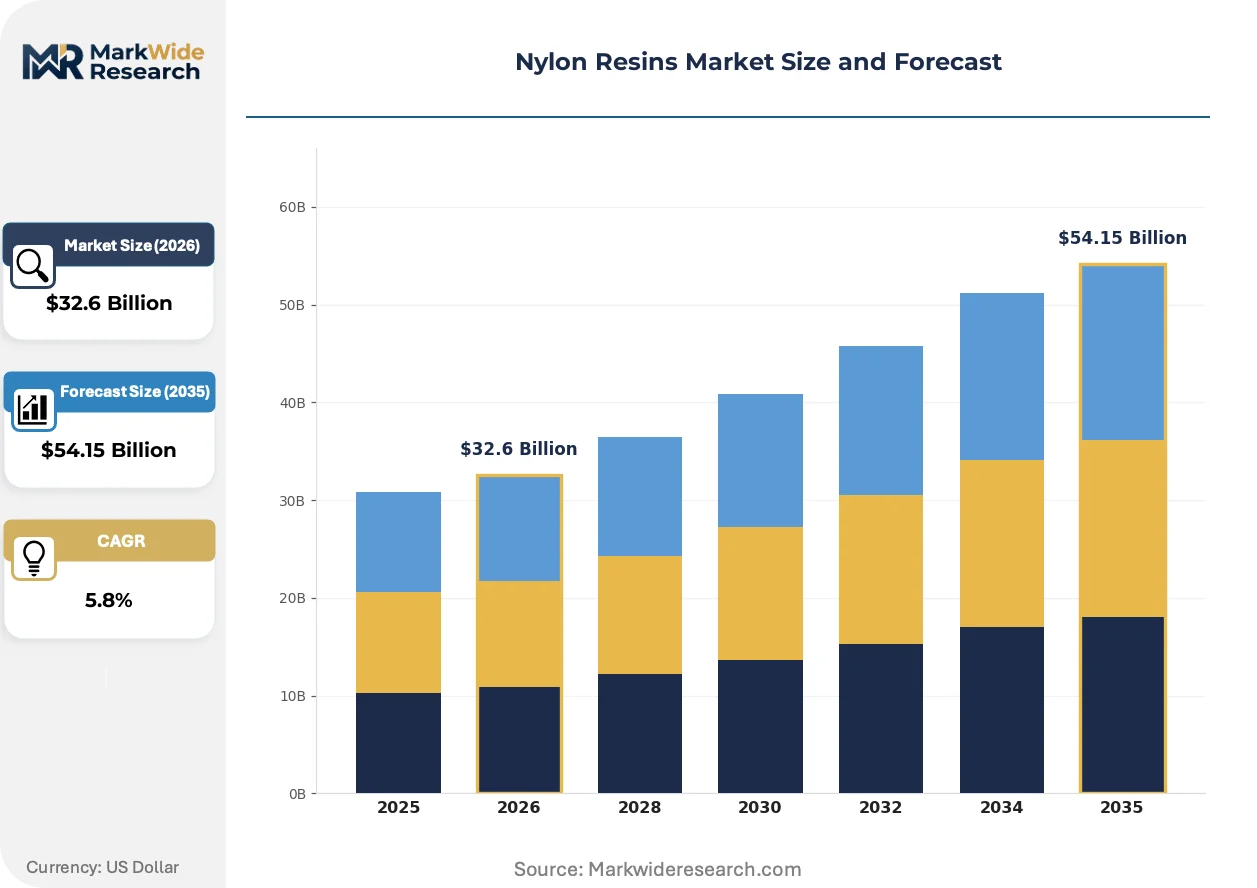
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $54.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon 6, Nylon 66, Nylon 610, Nylon 11 End User: Automotive, Consumer Goods, Electronics, Textiles Application: Injection Molding, Extrusion, Blow Molding, 3D Printing Form: Granules, Powders, Sheets, Films |
| Companies Covered | BASF SE, DuPont de Nemours Inc, DSM, Asahi Kasei Corporation, Kuraray Co Ltd, Lanxess AG, Ascend Performance Materials, Invista, Toray Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon Resins Market Evolving Landscape
Material science advances and regulatory compliance requirements are compressing development cycles while fragmenting supply relationships across the value chain.
Continuous fiber-reinforced thermoplastic tapes are consolidating metal replacement opportunities in automotive structural components. Tier-1 suppliers in Germany and China are qualifying these unidirectional tapes for seat frames and front-end modules. The technology is consolidating previously separate stamping and injection molding supply chains into single-step forming operations.
REACH authorization requirements and the EU Green Deal's circular economy action plan restrict certain additive chemistries and mandate recycled-content thresholds in consumer goods and electronics applications. ECHA substance evaluations force reformulation of flame-retardant nylon grades used in electrical connectors. Appliance manufacturers are responding by qualifying halogen-free alternatives ahead of sunset dates for legacy chemistries.
Modular compounding arrangements are displacing integrated polymer production for mid-volume specialty grades. Regional toll-manufacturing partnerships allow compounders to source base polymer locally while adding proprietary additive packages near end-use customers. This pattern concentrates most visibly in the US Southeast, where automotive assembly plants source customized glass-filled grades from distributed compounding nodes rather than captive resin operations.
Nylon Resins Market Segmentation
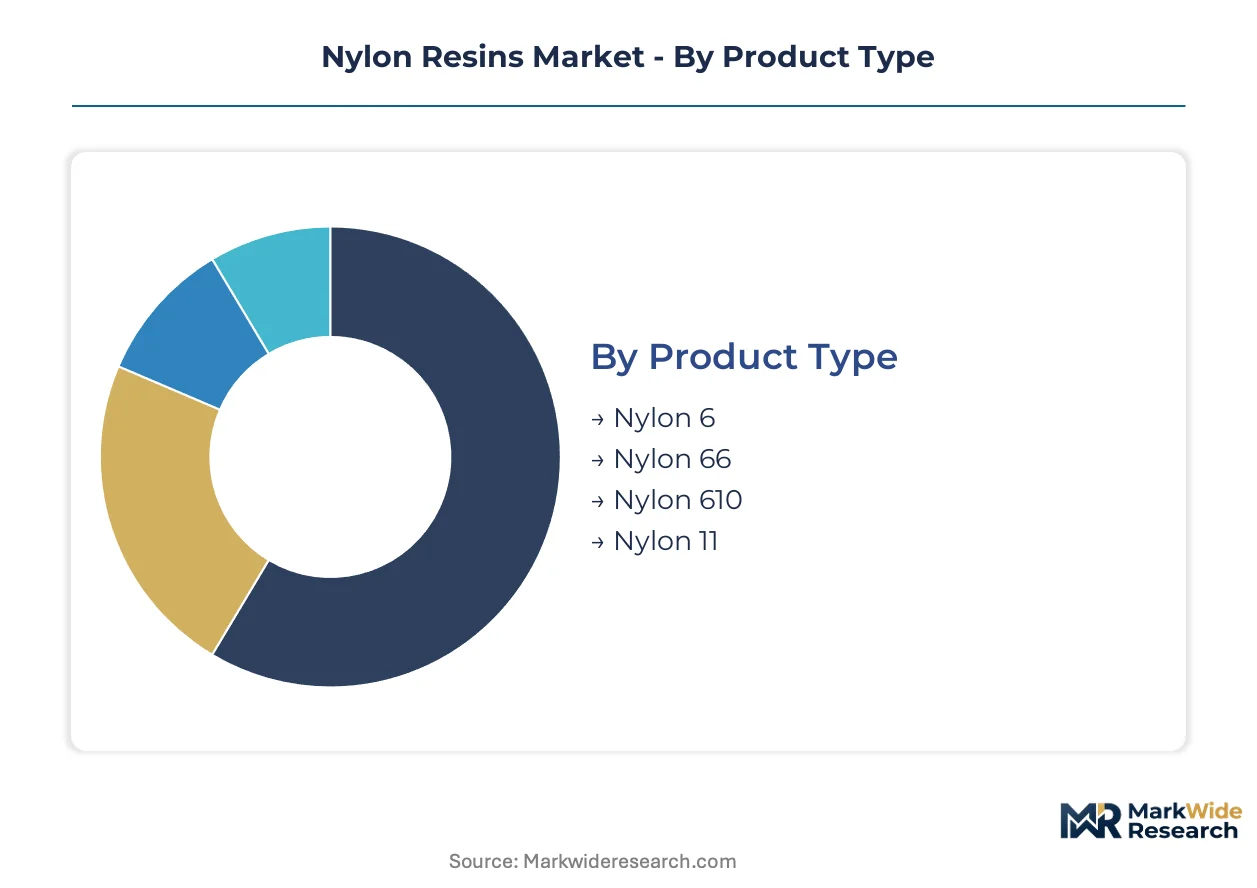
Nylon resin segments diverge sharply in capital requirements and margin profiles. Polymerization technology choices, compounding infrastructure, and end-use certification demands create distinct investment thresholds across categories.
Product Type:
Caprolactam-based Nylon 6 demands integrated adipic acid complexes with the heaviest upfront capital burden, while specialty bio-polyamides require fermentation-capable feedstock assets.
- Nylon 6:Ring-opening polymerization of caprolactam yields semi-crystalline resin with melting points near 220°C. German and Chinese automotive programs pull glass-filled grades into engine covers and intake manifolds where cost-performance balance matters.
- Nylon 66:Polycondensation of adipic acid and hexamethylenediamine produces higher melting point material with superior dimensional stability. Under-hood applications in US and European vehicles favor this grade for thermal management modules and electrical connectors.
- Nylon 610:Sebacic acid-based polymer offers lower moisture absorption for precision gears and bearing cages.
- Nylon 11:Castor oil-derived bio-polyamide serves oil and gas flexible tubing and sports equipment where renewable content carries procurement weight.
Nylon 6 absorbs the bulk of installed capacity; Nylon 11 is expanding most quickly.
End User:
Automotive qualification timelines stretch 18-36 months, creating the steepest barrier to entry, while consumer goods permit faster formulation turnover.
- Automotive:Structural brackets, cooling modules, and powertrain components substitute metal under EPA fuel-economy and NHTSA safety mandates. Glass-reinforced grades dominate where fatigue resistance and dimensional stability under cyclic loading prove critical.
- Electronics:Flame-retardant formulations for connectors and housings face REACH-driven reformulation cycles. ECHA substance evaluations accelerate halogen-free grade adoption ahead of legacy chemistry sunset dates.
- Consumer Goods:Appliance housings and power tool casings prioritize surface finish and colorability over mechanical extremes.
- Textiles:Industrial yarn and carpet fiber applications consume high-volume unfilled resin with stringent molecular weight specifications.
Automotive commands the longest qualification pipelines; electronics is climbing the fastest as regulatory deadlines compress procurement timelines.
Application:
Processing method determines equipment specialization and batch economics, with continuous extrusion lines representing the largest fixed-asset commitment.
- Injection Molding:High-pressure molding of glass-filled compounds produces complex geometries for automotive structural brackets. Tooling investments and cycle time optimization dominate total cost structures.
- 3D Printing:Powder-bed fusion and material extrusion platforms adopt PA11 and PA12 variants for production parts in aerospace tooling and medical device prototyping.
- Extrusion:Continuous profile and sheet production serves film and monofilament applications with dedicated line configurations.
- Blow Molding:Hollow part formation for fuel tanks and fluid reservoirs requires specialized parison control and wall-thickness management.
Injection Molding retains the largest volume footprint; 3D Printing shows the steepest expansion trajectory.
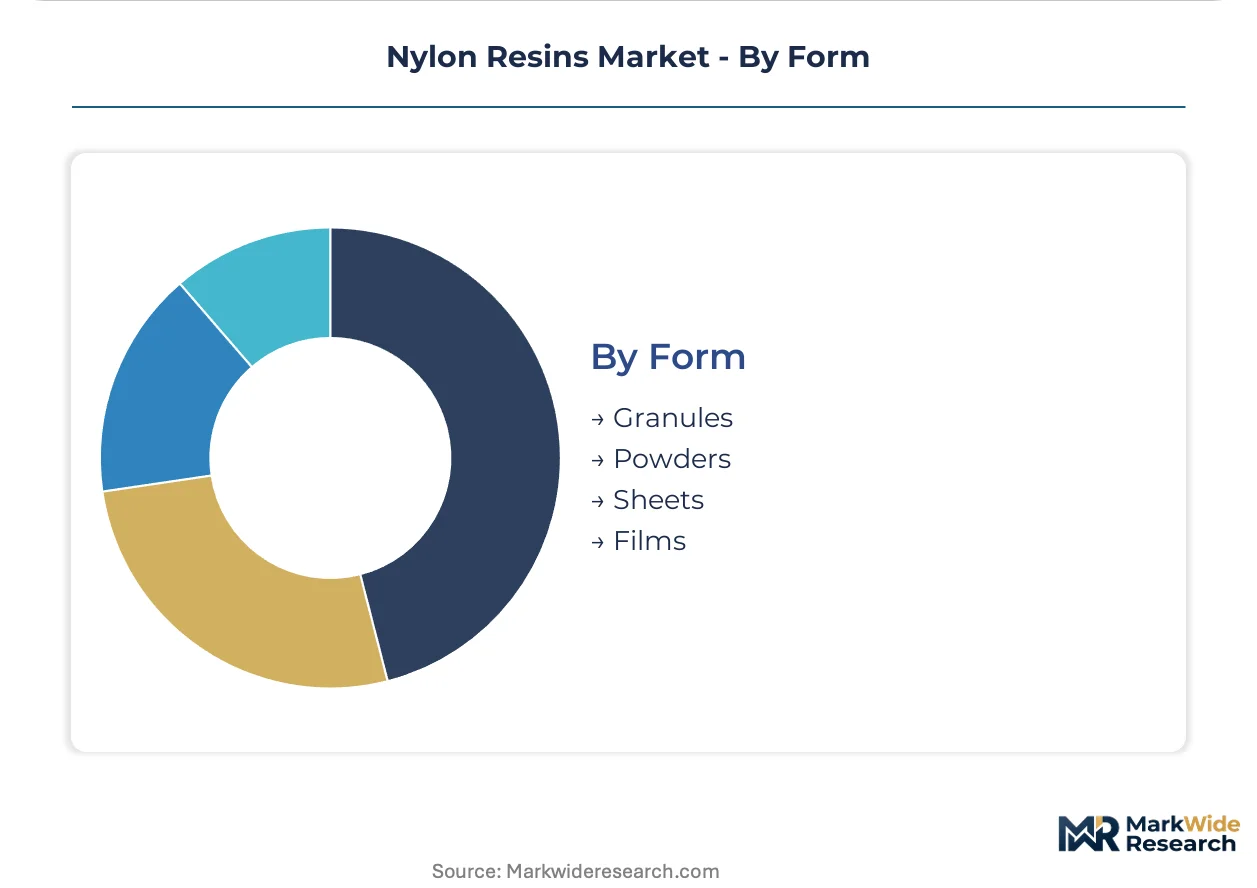
Form:
Physical form dictates logistics infrastructure and downstream handling equipment, with powder systems requiring the most specialized containment and conveyance.
- Granules:Standard pellet form for injection molding and extrusion with established bulk handling protocols across all major manufacturing regions.
- Powders:Fine particle grades for rotational molding and coating applications where melt flow and sintering behavior prove critical.
- Sheets:Compression-molded or extruded plate stock for thermoformed housings and machined structural components.
- Films:Biaxially oriented or cast film for flexible packaging and industrial lamination with tight thickness tolerance requirements.
Granules move the highest tonnage; powders are gaining share fastest in additive manufacturing feedstocks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of caprolactam and adipic acid feedstock yet Germany and the United States consume disproportionate volumes of engineered grades for automotive and industrial applications. This production-consumption asymmetry shapes trade flows and investment patterns across the value chain.
China
Automakers in Shanghai and Jiangsu province specify glass-filled Nylon 6 for electric vehicle battery housings and thermal management modules. MIIT dual carbon goals and GB standards for vehicle energy consumption accelerate metal substitution programs. The Yangtze River Delta chemical cluster hosts integrated adipic acid-caprolactam-nylon polymer complexes that supply domestic compounders and export base resin to Southeast Asian processors.
Germany
BMW and Volkswagen procurement teams qualify continuous fiber-reinforced thermoplastic tapes for seat frames and front-end modules under KBA safety protocols. REACH authorization requirements and EU Green Deal circular economy mandates restrict legacy flame retardants and mandate recycled-content thresholds. The Ludwigshafen chemical complex maintains captive caprolactam supply chains serving tier-1 automotive suppliers across Baden-Württemberg and Bavaria.
United States
EPA fuel-economy standards and NHTSA vehicle safety rules compel Detroit automakers to substitute aluminum with glass-reinforced nylon in structural brackets and cooling modules. Extended Producer Responsibility frameworks in California and pending federal circular economy legislation shape end-of-life recycling qualifications. The US Southeast automotive corridor sources customized compounds from distributed toll-manufacturing nodes rather than integrated resin operations.
India
Maruti Suzuki and Tata Motors procurement teams specify Nylon 66 for under-hood connectors and powertrain components as domestic vehicle production scales. PLI scheme incentives for advanced materials manufacturing attract integrated polymer investments serving automotive and electrical component demand. The Gujarat chemical belt and Maharashtra industrial corridors concentrate compounding capacity for domestic appliance and power tool manufacturers.
Japan
Toyota and Honda engineering teams prioritize Nylon 66 for thermal management modules and electrical connectors requiring higher melting points and lower moisture uptake. METI carbon neutrality roadmaps and JIS standards for automotive materials accelerate bio-based polyamide qualification programs. The Nagoya industrial zone and Kanto manufacturing belt concentrate precision molding operations for camera housings and electronic device structural components.
Nylon Resins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capital-intensity tiers. The market structure concentrates polymerization capacity among integrated chemical majors while mid-scale compounders occupy specialty formulation niches. Three archetypes dominate: backward-integrated feedstock owners, regional toll-compounding networks, and bio-based material innovators. Capacity expansion and strategic toll-manufacturing partnerships constitute the dominant competitive moves as stakeholders recalibrate geographic coverage.
Among European-based integrated producers, BASF SE and Lanxess AG occupy positions anchored by Verbund site economics and specialized engineering resin portfolios. DuPont de Nemours Inc represents the diversified materials conglomerate archetype with historical strength in automotive thermal management formulations. Ascend Performance Materials exemplifies the North American pure-play model with upstream control over adiponitrile and hexamethylenediamine feedstocks. These three anchors demonstrate how divergent capital structures—captive petrochemical integration versus merchant market positioning—shape competitive options across pricing cycles.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours Inc |
| DSM |
| Asahi Kasei Corporation |
| Kuraray Co Ltd |
| Lanxess AG |
| Ascend Performance Materials |
| Invista |
| Toray Industries Inc |
| Others |
Value Network & Pricing Analysis
Detroit automaker procurement teams negotiate long-term offtake contracts that compress compounder margins while rewarding volume scale and IATF 16949 certification tiers. This buyer concentration forces pricing stratification across premium glass-filled grades, standard unfilled resins, and economy recycled-content tiers.
Pricing Analysis
Cost-down pressure on merchant compounders accelerates because Yangtze River Delta integrated producers flood base resin supply. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified grades from industrial commodity tiers. REACH-driven reformulation cycles raise premium tier costs while polypropylene substitution erodes standard tier pricing. Electronics procurement teams exhibit highest price sensitivity; aerospace tooling buyers accept premium positioning for PA11 and PA12 variants.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore consolidate bulk resin flows before last-mile compounding operations. Feedstock security draws from China, Germany, and the United States where adipic acid-caprolactam complexes anchor upstream supply. Merchant compounders rest on hexamethylenediamine from a handful of adiponitrile producers. Single-source vulnerability in Nylon 66 precursor supply creates disruption risk. Distribution runs through toll-manufacturing nodes in the US Southeast and East China automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based polyamide fermentation technology is displacing petrochemical caprolactam routes, forcing incumbents to recalibrate feedstock investments and opening white-space for specialized producers.
For Market Incumbents: Anticipate REACH authorization deadlines by accelerating halogen-free flame-retardant R&D ahead of legacy chemistry sunset dates. Lock in adiponitrile supply through long-term offtake with hexamethylenediamine producers or captive backward integration into feedstock. Defend automotive qualification pipelines against polypropylene substitution in non-structural applications. For New Entrants and Emerging Players: EU Green Deal circular economy mandates in Germany and France open a window for post-industrial and post-consumer nylon grades in electronics housings. White-space concentrates in India PLI scheme zones where domestic automotive production scales fastest. Target toll-compounding partnerships near Gujarat and Maharashtra industrial corridors to bypass integrated polymer capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor bio-polyamide specialists with castor oil feedstock agreements in Brazil and India. Five-to-ten-year viability hinges on fermentation-capable asset bases qualifying for EU recycled-content thresholds. Watch ECHA substance evaluation timelines as inflection signals for flame-retardant grade reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Captive hexamethylenediamine supply insulates Ascend Performance Materials from merchant market volatility. |
| Green Manufacturing Transition | Bio-based PA11 fermentation at Arkema and Evonik aligns with EU Green Deal procurement mandates. |
| Long-term Supply Agreement | BASF SE's Ludwigshafen Verbund site locks caprolactam flows for German automotive tier-1 suppliers. |
| Joint Venture | Regional toll-compounding partnerships in the US Southeast reduce logistics costs for Detroit OEM programs. |
| Capacity Expansion | Yangtze River Delta integrated complexes capture East China electric vehicle battery housing demand. |
Research Methodology
Multi-period observation of caprolactam spot pricing, automotive production schedules, and REACH authorization timelines anchored the trend analysis, supplemented by interviews with polymerization plant managers, Tier 1 supplier procurement leads, compounding technical directors, and distribution channel partners. Secondary validation drew from customs trade data, Cefic polymer reports, SEC 10-K chemical segment disclosures, and IHS Markit vehicle production databases. Bottom-up resin demand modeling triangulated against top-down automotive content-per-vehicle estimates.
Input-output matrices mapped adipic acid and caprolactam feedstock flows through polymerization, compounding, and end-use conversion stages across the analysis window. Segmentation dimensions included grade tier, end-use industry, processing method, and regional production hub. CAGRs derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs incorporated EPA fuel-economy compliance timelines and MIIT dual carbon policy implementation rates.
The model assumes a particular technology adoption path; alternative pathways for bio-based polyamide fermentation would alter the outlook if castor oil feedstock costs diverge from petrochemical benchmarks. Forecasts reflect documented assumptions around REACH sunset dates and PLI scheme disbursement schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market