
 Polyolefin (PO) Market | 2026-2036
Polyolefin (PO) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin (PO) Market Analytics
Metallocene-grade specifications are redrawing competitive boundaries across the polyolefin value chain. SABIC leverages its feedstock integration across Saudi Arabia's industrial cities to sustain cost leadership in high-density polyethylene. LyondellBasell Industries Holdings B.V. anchors its position through proprietary multireactor technology that differentiates molecular weight distribution control. Dow competes aggressively in North American linear low-density polyethylene through advantaged ethane cracking economics.
Polyolefins constitute a family of thermoplastic polymers synthesized primarily from olefin monomers, with polyethylene and polypropylene representing the dominant commercial categories characterized by density ranges from 0.910 to 0.970 g/cm³ and melt flow indices spanning 0.1 to 1500 g/10 min. These materials serve as foundational inputs for flexible packaging films, rigid containers, automotive components, and textile fibers owing to their tunable crystallinity, chemical inertness, and processability across extrusion and injection molding platforms. Polyethylene occupies the largest volume share across product types, while polypropylene captures expanding automotive interior applications driven by weight reduction mandates. Films and sheets represent the fastest-growing form segment as downstream converters prioritize downgauging for sustainability compliance.
EPA regulations governing volatile organic compound emissions from resin production shape facility permitting and technology selection across the United States. REACH substance restrictions and the EU Green Deal's plastics circularity targets compel European producers to certify recycled content thresholds and reduce hazardous additive loadings. China's GB standards and dual carbon goals from MEE enforce energy intensity caps on steam crackers and catalytic polymerization units. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between mechanical recycling investments versus advanced chemical recycling partnerships before regulatory deadlines crystallize.
Market Dynamics
Metallocene catalysis is compressing molecular weight distribution tolerances, forcing commodity producers to either license single-site technology or retreat to volume-driven bulk grades where ethane cost economics still defend margins.
Growth Catalysts
- EU REACH additive restrictions:Reformulation mandates are accelerating demand for cleaner masterbatch compounds as converters seek pre-certified resin systems that bypass downstream compliance testing.
- Automotive lightweighting:Tier-1 suppliers are specifying mineral-filled polypropylene for instrument panels and door modules to meet OEM fleet efficiency targets without metal substitution penalties.
- China integrated petrochemical expansion:Gas-phase polypropylene capacity additions in Ningbo and Dalian are absorbing domestic propylene supply and displacing seaborne imports from Middle East producers.
Market Restraints
- Naphtha feedstock volatility:European steam crackers remain exposed to crude-linked naphtha pricing, compressing spreads versus North American ethane-based polyethylene operations.
- Specialty catalyst supply concentration:Metallocene and Ziegler-Natta catalyst manufacturing concentrates among three technology licensors, creating royalty bottlenecks for new market entrants.
- Mechanical recycling contamination limits:Multi-layer flexible packaging films containing incompatible adhesive tie-layers cannot enter existing mechanical recycling streams without costly delamination.
Strategic Opportunities
- India packaging conversion:Domestic film extrusion capacity is undersized relative to food and FMCG growth, creating import substitution potential for biaxially oriented polypropylene suppliers.
- Chemical recycling partnerships:Pyrolysis oil offtake agreements with refining complexes offer circular content certification pathways that mechanical recycling cannot match for complex multilayer structures.
- Medical device migration:US FDA device master file registrations for pharmaceutical-grade polypropylene are opening barrier film applications previously captured by cyclic olefin copolymers.
Industry Challenges
- Polymer characterization expertise shortage:Metallocene product development requires specialized rheology and crystallization kinetic modeling capabilities that legacy commodity resin teams lack.
- Recycled content certification timelines:EU ECHA SCIP database registrations and third-party mass balance audits impose 12-18 month lead times before circular claims can enter commercial specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin (PO) Market |
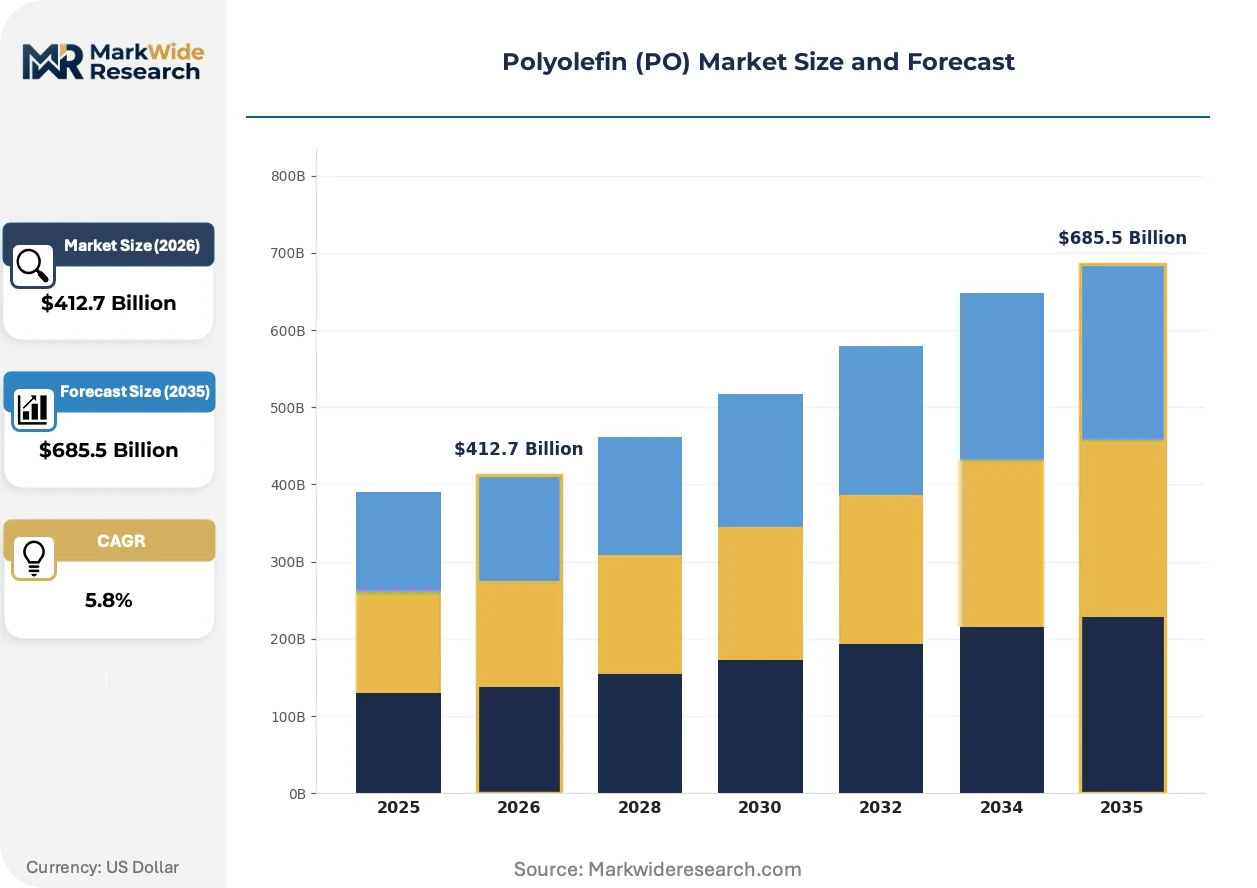
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $685.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polybutene, Polymers End Use Industry: Packaging, Automotive, Construction, Textiles Form: Granules, Films, Sheets, Fibers Technology: Catalytic Polymerization, Gas Phase Polymerization, Bulk Polymerization, Solution Polymerization |
| Companies Covered | SABIC, China Petrochemical Corporation, LyondellBasell Industries Holdings B.V., Dow, ExxonMobil Corporation, Borealis AG, China National Petroleum Corporation, Braskem S.A., TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin (PO) Market Evolving Landscape
Polyolefin value chains are bifurcating between precision-grade specifications serving automotive and medical verticals versus undifferentiated commodity grades competing purely on feedstock arbitrage and logistics optimization.
Single-site metallocene polyethylene is supplanting conventional Ziegler-Natta resins in premium stretch film applications. Brand owners in fresh produce packaging are specifying octene-based linear low-density grades that enable 15-20% downgauging without puncture resistance loss. This substitution is compressing margins for commodity high-pressure low-density polyethylene producers in Asia-Pacific export markets.
REACH substance restrictions under Annex XVII are prohibiting certain phthalate plasticizers and heavy metal pigments in consumer-contact applications. Compounders must reformulate color concentrates and slip agents using alternative chemistries that meet both migration limits and processing window requirements. Automotive interior suppliers serving EU OEMs are accelerating migration to halogen-free flame retardant polypropylene grades ahead of 2026 enforcement deadlines.
Brand sustainability commitments are restructuring procurement specifications around mass balance-certified circular content. Major food retailers in Germany and France are mandating minimum recycled thresholds in flexible packaging that mechanical recycling cannot currently supply. This specification gap is forcing converters to qualify chemical recycling feedstocks and absorb price premiums that commodity film markets historically rejected.
Polyolefin (PO) Market Segmentation
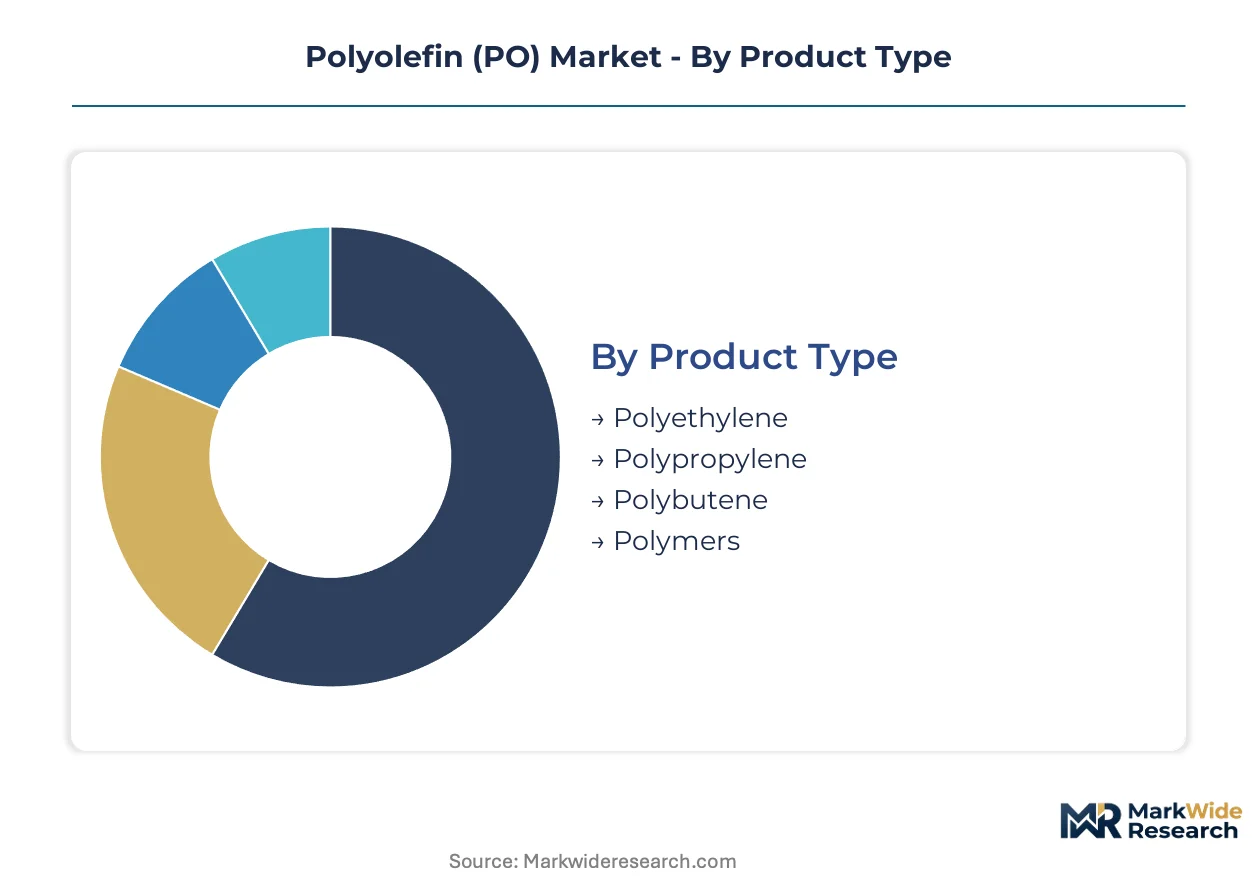
Polyolefin market segmentation reveals distinct supply-demand mismatches across product grades and conversion technologies. Producers must align capacity investments with end-use specifications rather than treating polyethylene and polypropylene as interchangeable commodity streams.
Product Type:
Polyethylene dominates export-oriented supply chains from US Gulf Coast ethane crackers, while polypropylene clusters around integrated refinery-petrochemical complexes serving regional automotive molding demand.
- Polyethylene:Density-graded resins span LDPE through HDPE specifications with melt flow indices calibrated for film extrusion versus injection molding. Food packaging converters in Germany and France are specifying metallocene LLDPE for downgauged stretch films that meet EU Green Deal circularity targets without mechanical recycling contamination risks.
- Polypropylene:Isotactic homopolymer and impact copolymer grades offer tunable stiffness-toughness balances through Ziegler-Natta or metallocene catalyst selection. Tier-1 automotive suppliers in Stuttgart and Wolfsburg are qualifying mineral-filled grades for instrument panels to satisfy fleet efficiency mandates under KBA type approval frameworks.
- Polybutene:Specialty pipe-grade resin serving European potable water infrastructure with creep resistance superior to polyethylene.
- Polymers:Ethylene-vinyl acetate and ethylene-butene copolymers filling adhesive and sealant layer applications in multilayer flexible packaging.
Polyethylene commands the established base. The steepest expansion runs through polypropylene as automotive lightweighting accelerates specification upgrades.
End Use Industry:
Cost tier stratification separates specification-grade automotive and medical applications from undifferentiated commodity packaging volumes competing on feedstock arbitrage alone.
- Packaging:Flexible films, rigid containers, and closure systems absorb the majority of polyethylene resin output. Major German retailers are mandating mass balance-certified circular content thresholds that mechanical recycling cannot satisfy, forcing converters toward pyrolysis oil offtake agreements with refining partners.
- Automotive:Interior trim, bumper fascias, and HVAC ducting specify talc-filled polypropylene with low volatile organic compound emissions to meet ECHA REACH substance restrictions. OEMs in Wolfsburg and Munich are consolidating supplier bases around compounders with in-house rheology modeling capabilities.
- Construction:Geomembranes, pipe systems, and vapor barriers requiring UV-stabilized HDPE with 50-year service life predictions.
- Textiles:Bicomponent fibers and nonwoven spunbond materials for hygiene applications with hydrophilic surface treatment specifications.
Packaging absorbs the volume base. Automotive applications are gaining share fastest as metal substitution penalties tighten under fleet efficiency regulations.
Form:
Volume concentration favors pelletized granules for compounder flexibility, while film and sheet converters absorb resin directly from polymerization units to capture logistics savings.
- Granules:Standard pellet form enabling long-haul shipment to dispersed compounding and conversion facilities. Masterbatch producers in Ningbo and Shanghai are qualifying pre-certified additive packages that bypass downstream EU REACH compliance testing for export-bound film customers.
- Films:Cast and blown film extrusion serving fresh produce and industrial stretch wrap applications with downgauging specifications. Biaxially oriented polypropylene film demand is climbing fastest in India as domestic food processing capacity expands ahead of local extrusion infrastructure.
- Sheets:Thermoforming feedstock for rigid containers and automotive interior panels requiring consistent gauge tolerance.
- Fibers:Staple and filament grades for carpet backing and geotextile applications with tenacity specifications above 5.5 g/denier.
Granules dominate shipment volumes. Films are expanding most quickly as sustainability mandates accelerate packaging redesign cycles.
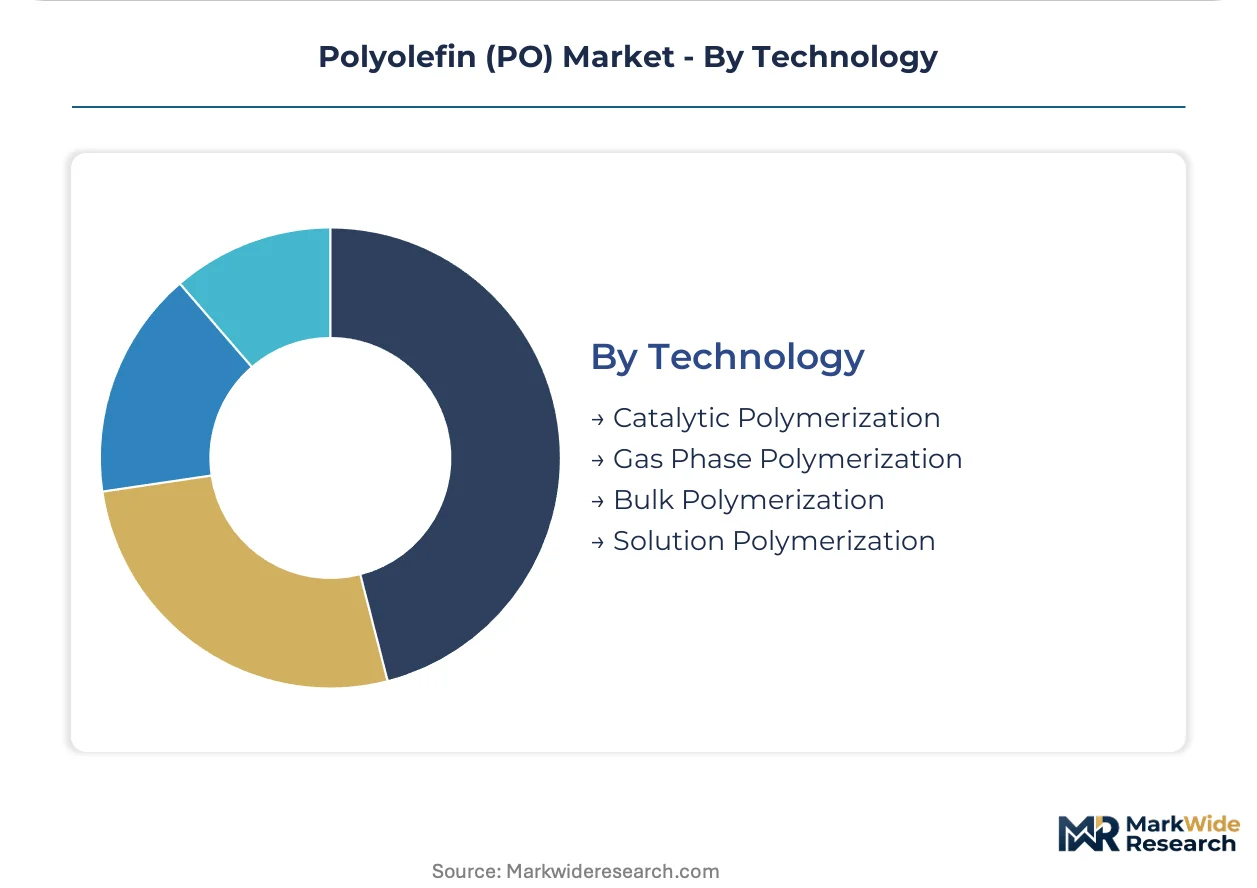
Technology:
Margin structure separates proprietary single-site metallocene licensing from commodity Ziegler-Natta bulk polymerization where ethane cost economics defend returns.
- Catalytic Polymerization:Ziegler-Natta and metallocene catalyst systems enabling molecular weight distribution control. Technology licensors in Europe and North America are extracting royalty premiums from Asian producers seeking specification-grade resin capabilities.
- Gas Phase Polymerization:Fluidized bed reactors producing polypropylene with high isotacticity and low xylene solubles. Chinese integrated complexes in Ningbo and Dalian are scaling gas-phase capacity to displace Middle East seaborne imports.
- Bulk Polymerization:Liquid propylene monomer process eliminating hydrocarbon diluent recovery costs.
- Solution Polymerization:Homogeneous catalysis for specialty ethylene-octene copolymers with narrow composition distribution.
Catalytic polymerization retains the installed base. Gas-phase technology is climbing the fastest as Chinese capacity additions absorb domestic propylene supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes cluster in coastal industrial zones where feedstock access and export logistics converge. Capacity expansion is concentrating in jurisdictions with advantaged ethane or naphtha economics.
United States
Shale-derived ethane supplies Gulf Coast steam crackers with cost-advantaged feedstock for linear low-density polyethylene export. EPA regulations on volatile organic compound emissions shape facility permitting timelines. Houston and Corpus Christi host expanding polyethylene pellet capacity serving Latin American film converters.
China
Domestic automotive molding and consumer goods fabrication absorb rising gas-phase polypropylene output from Ningbo and Dalian complexes. GB standards and MEE dual carbon goals enforce energy intensity caps on catalytic polymerization units. Yangtze River Delta integrated refineries are displacing Middle East seaborne imports through captive propylene supply.
Germany
Automotive tier-1 suppliers in Stuttgart and Wolfsburg specify mineral-filled polypropylene for instrument panels under KBA type approval frameworks. EU REACH Annex XVII restrictions on phthalate plasticizers compel masterbatch reformulation. Rhine-Ruhr chemical clusters are certifying mass balance circular content for flexible packaging export to French retailers.
Saudi Arabia
SABIC leverages feedstock integration across Jubail and Yanbu industrial cities to supply high-density polyethylene to Asian pipe and film markets. SAMR standards alignment with EU technical regulations facilitates export certification. Eastern Province petrochemical complexes are expanding gas-phase polypropylene capacity for Indian automotive molding demand.
India
Domestic biaxially oriented polypropylene film extrusion capacity lags behind food processing and FMCG packaging growth. BIS quality certification requirements create compliance barriers for imported resin grades. Gujarat and Maharashtra polymerization facilities are scaling to capture import substitution opportunities in flexible packaging conversion.
Polyolefin (PO) Market Competitive Landscape
Concentration sits with integrated petrochemical majors possessing captive feedstock and proprietary catalyst licensing. The competitive structure divides between technology licensors extracting royalty premiums and volume operators defending margins through feedstock arbitrage. Two archetypes dominate: Gulf-based ethane-integrated producers and European technology specialists with multireactor process control. Capacity expansion and strategic catalyst licensing represent the primary competitive vectors.
Among Gulf-based integrated producers, SABIC anchors the feedstock-advantaged tier with operations across Saudi industrial cities. Dow and ExxonMobil Corporation occupy positions within North American ethane-cracking economics, supplying export-oriented polyethylene grades. LyondellBasell Industries Holdings B.V. exemplifies the technology-licensing archetype through proprietary multireactor systems. These three entities represent distinct competitive positioning: feedstock integration, regional cost structure, and catalytic process control.
| Leading Market Players |
|---|
| SABIC |
| China Petrochemical Corporation |
| LyondellBasell Industries Holdings B.V. |
| Dow |
| ExxonMobil Corporation |
| Borealis AG |
| China National Petroleum Corporation |
| Braskem S.A. |
| TotalEnergies |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day order-to-delivery windows for metallocene-grade polyethylene concentrate pricing power with technology licensors possessing single-site catalyst expertise, while commodity bulk grades trade on spot ethane-naphtha spreads that compress margins for non-integrated European steam crackers.
Pricing Analysis
EU REACH Annex XVII substance restrictions dictate the pricing tier structure across polyolefin value chains, separating pre-certified masterbatch compounds from downstream-reformulated alternatives. Three-tier pricing structure across premium metallocene specifications, standard Ziegler-Natta grades, and economy bulk resins reflects catalyst royalty burdens and migration testing costs. Cost compression in European naphtha-based polyethylene is intensifying because Middle East ethane-integrated exports undercut regional spot pricing. Brand owners in German retail packaging demonstrate highest price sensitivity, while automotive tier-1 suppliers in Stuttgart accept premiums for KBA-compliant low-VOC emission grades.
Supply Chain Analysis
Saudi Arabia and the United States anchor high-density polyethylene pellet production for Asian pipe and Latin American film export markets. China and South Korea concentrate gas-phase polypropylene capacity serving domestic automotive molding and Indian biaxially oriented film demand. Feedstock draws from shale-derived ethane, crude-linked naphtha, and refinery-sourced propylene monomer. Single-source vulnerability concentrates in metallocene catalyst manufacturing among three technology licensors. Distribution runs through integrated petrochemical complexes with captive port terminals, bypassing third-party logistics for pelletized granule export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized rheology modeling capabilities and crystallization kinetic expertise remain scarce across legacy commodity resin teams, creating competitive moats for producers with in-house polymer characterization laboratories.
For Market Incumbents: Fortify technology licensing revenue streams by expanding single-site metallocene patent coverage into Asian markets where domestic producers lack molecular weight distribution control capabilities. Deepen backward integration into catalyst precursor manufacturing to reduce royalty outflows to European and North American technology licensors. Prioritize capacity additions in Ningbo and Dalian to capture Chinese automotive polypropylene demand displacing Middle East seaborne imports. For New Entrants and Emerging Players: Technical service gaps in polymer characterization and regulatory compliance certification present entry vectors for specialized compounders serving EU REACH-mandated reformulation demand. Target Indian biaxially oriented polypropylene film extrusion where domestic capacity lags food processing growth. Pursue pyrolysis oil offtake partnerships with refining complexes to qualify mass balance-certified circular content for German and French retailer procurement specifications. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical recycling infrastructure as pyrolysis and gasification units require refining-scale investment thresholds. Five-to-ten year viability favors technology-licensing specialists with recurring royalty income over volume-exposed commodity producers. Monitor EU ECHA SCIP database registration timelines as inflection indicator for circular content certification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst Technology Licensing | Proprietary single-site metallocene patents extract royalty premiums from Asian capacity additions seeking specification-grade capabilities. |
| Backward Integration into Feedstock | Captive ethane cracking economics defend polyethylene margins against naphtha-linked European and Asian competitors. |
| Chemical Recycling Partnership | Pyrolysis oil offtake agreements with refining complexes unlock mass balance certification pathways mechanical recycling cannot match. |
| Regulatory Pre-Certification Investment | EU REACH-compliant masterbatch compounds bypass downstream converter testing, capturing specification premiums in export markets. |
| Regional Capacity Expansion | Gas-phase polypropylene additions in Yangtze River Delta displace Middle East imports under China's dual carbon intensity caps. |
Research Methodology
The analysis maps metallocene-grade specifications, commodity bulk grades, and circular content certification pathways, each validated through plant managers at integrated petrochemical complexes, procurement leads at automotive tier-1 suppliers, distribution channel partners in Asian export markets, and technical R&D directors at catalyst technology licensors. Primary interview insights triangulate against customs and trade flow databases, ACC and Cefic industry association reports, SEC 10-K filings from listed petrochemical majors, and energy intensity disclosures under China's MEE dual carbon framework. Bottom-up resin grade demand modeling reconciles with top-down macroeconomic absorption rates.
Consistency checks validate volume and value outputs against external benchmarks including regional steam cracker operating rates, propylene monomer spot pricing differentials, and automotive lightweighting content-per-vehicle trajectories. The analytical framework segments by density grade, end-use industry vertical, packaging format, and regional production hub across the analysis window. CAGRs derive from regression-based demand elasticity modeling calibrated to named feedstock cost scenarios and regulatory enforcement timelines. Industry-specific forecast inputs incorporate REACH Annex XVII substance restriction phase-in schedules and KBA type approval emission thresholds.
Underlying assumptions cover sustained shale ethane cost advantages, Chinese domestic propylene supply absorption, and EU circular content mandate enforcement, with deviation risk concentrated in naphtha price volatility and catalyst technology licensing access. Recalibration cycles align with material shifts in regulatory substance restriction expansions, automotive fleet efficiency mandate revisions, and chemical recycling capacity commissioning announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Global Polycarbonate Market