
 Polymer Antioxidants Market | 2026-2036
Polymer Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Antioxidants Market Analysis
The gap between specification-grade phenolic antioxidants and commodity sulfur-based alternatives is restructuring procurement patterns across polymer supply chains. BASF SE leverages its integrated intermediate production to sustain margin capture in high-performance grades. SONGWON anchors its position through phosphite antioxidant specialization for polyolefin stabilization. Adeka Corporation competes via aminic antioxidant leadership in Japanese automotive rubber compounds.
Polymer antioxidants are chemical additives that inhibit oxidative degradation in hydrocarbon-based materials, typically functioning through radical scavenging (phenolics, aminics), hydroperoxide decomposition (phosphites, sulfur compounds), or synergistic combinations at loadings between 0.05% and 1.0% by weight to extend service life under thermal and mechanical stress. Phenolic antioxidants occupy the largest volume position across plastics applications, while phosphite antioxidants represent the fastest-expanding category driven by polypropylene demand in automotive and packaging end uses. Rubber applications maintain mature growth trajectories with sulfur-based antioxidants retaining cost-driven dominance in tire manufacturing.
REACH registration requirements under ECHA govern antioxidant substance authorization across Europe, while EPA Toxic Substances Control Act provisions shape new chemical notification pathways for novel antioxidant structures in the United States. Japan METI maintains chemical substance inventories that condition market access for imported antioxidant formulations. Stakeholders must monitor evolving substance restriction proposals and polymer recycling compatibility mandates that will redefine antioxidant specification criteria across automotive and electronics value chains.
Market Dynamics
Specification-grade phenolic antioxidants are displacing commodity sulfur-based alternatives across automotive and electronics value chains, forcing raw material suppliers to restructure intermediate production around REACH-registered substance portfolios rather than cost-optimized bulk formulations.
Growth Catalysts
- Electric vehicle cable insulation demand:High-voltage architectures in battery electric vehicles require phenolic stabilization systems that withstand 150°C continuous operating temperatures, pulling specification-grade volumes into automotive supply chains.
- ECHA REACH substance authorization:Registration requirements for antioxidant intermediates create competitive moats for European producers with completed dossiers, accelerating consolidation among compliant suppliers.
- Polypropylene compounding expansion:Phosphite antioxidant loadings in automotive interior and packaging applications are rising as processors seek hydroperoxide decomposition synergy with hindered phenolics.
Market Restraints
- Phenol feedstock volatility:Cumene oxidation economics tie antioxidant margins to benzene-propylene spreads, exposing formulators to petrochemical cycle swings without pass-through mechanisms in long-term supply agreements.
- China phosphite concentration:Triphenyl phosphite and alkyl phosphite intermediate production clusters in Shandong and Jiangsu provinces, creating single-source dependency risks for global polyolefin stabilizer blenders.
- Sulfur antioxidant substitution ceiling:Tire manufacturers retain cost-driven preference for thioester and dithiocarbamate systems in sidewall compounds, limiting phenolic penetration in rubber's largest volume application.
Strategic Opportunities
- India polymer compounding growth:Domestic polypropylene film and injection molding expansion under PLI scheme incentives creates demand for phosphite-phenolic antioxidant systems currently served through import channels.
- Recycling-compatible antioxidant platforms:Formulations maintaining stabilization efficacy through multiple mechanical reprocessing cycles address EU Green Deal circular economy mandates for automotive and packaging recyclate integration.
- Direct-to-compounder digital channels:Technical service platforms enabling load-optimized antioxidant recommendations bypass traditional distributor markups in mid-tier polyolefin processing segments.
Industry Challenges
- Regulatory toxicology expertise scarcity:REACH registration dossier preparation and substance volume tracking require specialized regulatory affairs capabilities that smaller antioxidant blenders struggle to staff.
- Polymer recycling stream contamination:Unknown antioxidant histories in post-consumer feedstocks complicate restabilization protocols for circular material specifications demanded by automotive OEMs.
- ISO 9001 plus IATF 16949 certification burden:Dual quality system maintenance for automotive-qualified antioxidant production strains mid-cap formulators without captive automotive customer bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Antioxidants Market |
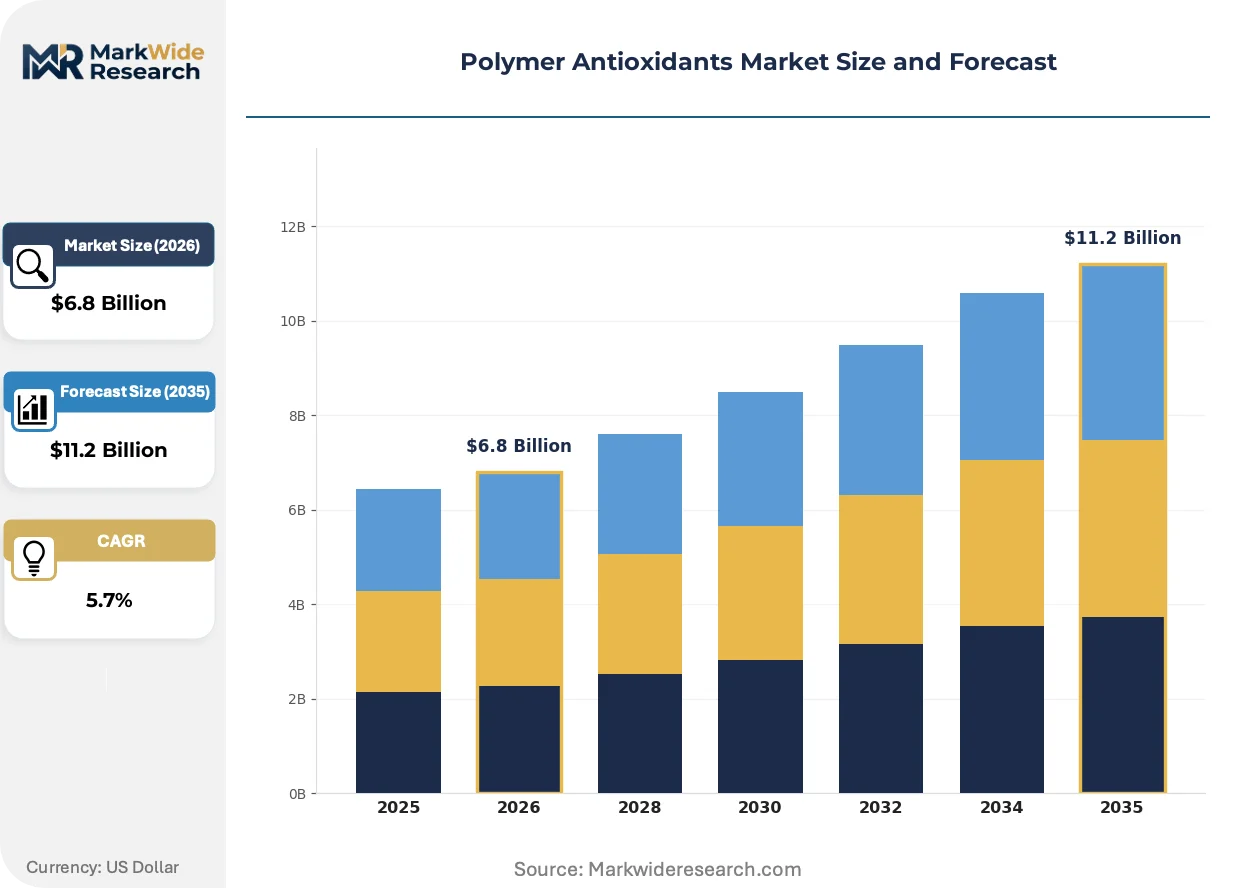
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic Antioxidants, Phosphite Antioxidants, Aminic Antioxidants, Sulfur-Based Antioxidants Application: Plastics, Rubber, Coatings, Adhesives End User: Automotive, Electronics, Packaging, Construction Form: Solid, Liquid, Masterbatches, Pellet |
| Companies Covered | BASF SE, SONGWON, Adeka Corporation, Solvay, SI Group, Inc., Clariant, Sumitomo Chemical Co., Ltd., 3V Sigma S.p.A., Dover Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Antioxidants Market Emerging Trajectories
Antioxidant formulation architectures are fragmenting into application-specific modules rather than universal multi-purpose packages, with processors demanding load-optimized synergistic blends tailored to exact polymer grades and thermal exposure profiles.
Reactive antioxidant grafting onto polymer backbones is modularizing stabilization chemistry directly into resin manufacturing rather than compounding-stage addition. Polypropylene producers in automotive supply chains are adopting this approach to eliminate antioxidant bloom and extraction concerns. The technology is compressing traditional antioxidant masterbatch demand into specialized high-performance niche applications.
EU F-Gas Regulation phase-down schedules are indirectly pressuring fluoropolymer wire insulation alternatives that rely more heavily on phenolic-phosphite stabilization systems than incumbent PVC formulations. Cable compounders serving electric vehicle platforms are reformulating around polypropylene and thermoplastic elastomer insulations with elevated antioxidant loadings. German automotive OEMs are accelerating qualification timelines for these alternative insulation systems to meet 2027 fleet electrification targets.
Specification-driven buying is consolidating antioxidant procurement around certified compounders with in-house stabilization laboratories rather than commodity distributors. Tier-1 automotive suppliers are requiring lot-to-lot consistency documentation and thermal aging validation that informal trading channels cannot provide. This behavioral shift is most visible in German and Japanese automotive wire harness supply chains, where ECHA REACH and METI chemical substance controls mandate full substance traceability.
Polymer Antioxidants Market Segmentation
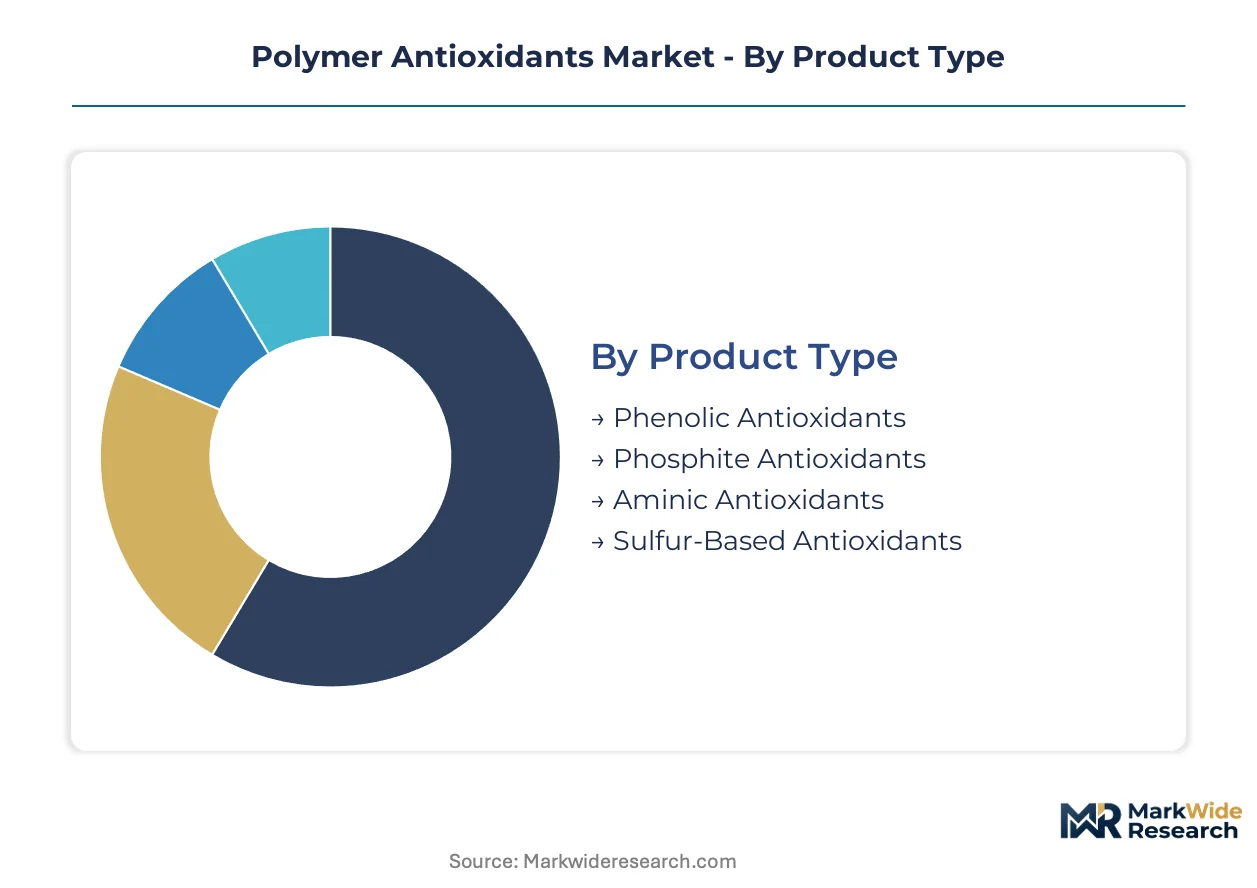
Antioxidant procurement patterns diverge sharply across product chemistries and end-use specifications, with automotive qualification requirements forcing formulators to maintain parallel supply streams for commodity and specification-grade portfolios.
Product Type:
Cost tier and performance ceiling separate buyers in this category, with premium formulations commanding multiples over sulfur-based alternatives.
- Phenolic Antioxidants:Hindered phenol structures deliver primary radical scavenging for polyolefin stabilization at 0.1-0.5% loadings. German automotive cable compounders specify these grades for 150°C continuous service under ECHA REACH substance controls. Phenolic formulations occupy the largest volume position across plastics applications.
- Phosphite Antioxidants:Hydroperoxide decomposition via organophosphite chemistry provides secondary stabilization synergy with phenolics. Polypropylene demand in automotive interiors and packaging applications is pulling triphenyl phosphite and alkyl phosphite volumes fastest. Phosphite antioxidants are expanding most quickly driven by processor requirements for melt-flow protection during high-shear compounding.
- Aminic Antioxidants:Aromatic amine structures dominate rubber stabilization, particularly in Japanese automotive compounds subject to METI chemical substance inventories.
- Sulfur-Based Antioxidants:Thioester and dithiocarbamate systems retain cost-driven dominance in tire sidewall manufacturing where specification-grade phenolics face substitution ceilings.
Phenolic antioxidants lead volumes today; phosphite antioxidants are gaining share fastest.
Application:
Volume scale and margin structure vary dramatically across these end-uses, with plastics commanding formulation complexity that rubber applications rarely require.
- Plastics:Polyolefin stabilization demands multi-component antioxidant systems combining phenolic primary stabilizers with phosphite secondary synergists. Electric vehicle cable insulation and battery enclosure materials are specification-grade phenolic formulations. Plastics applications concentrate antioxidant procurement around certified compounders with in-house thermal aging laboratories.
- Rubber:Tire manufacturing consumes sulfur-based antioxidants in sidewall and tread compounds where cost optimization outweighs thermal performance requirements. Japanese automotive rubber compounders specify aminic antioxidants for under-hood seals and gaskets. Rubber applications maintain mature growth trajectories with limited phenolic penetration.
- Coatings:Solvent-borne and water-borne systems require specialized antioxidant architectures to prevent film degradation during cure and outdoor exposure.
- Adhesives:Hot-melt and reactive adhesive formulations incorporate phenolic stabilizers to protect polymer backbones during high-temperature processing and end-use thermal cycling.
Plastics commands the largest value pool; rubber maintains the steadiest volume base.
End User:
Certification burden and technical service intensity separate these buyer groups, with automotive and electronics demanding documentation that packaging and construction rarely require.
- Automotive:Tier-1 suppliers require lot-to-lot consistency documentation, IATF 16949 quality system certification, and REACH-registered substance traceability. German and Japanese OEMs are accelerating qualification timelines for alternative cable insulation systems. Automotive procurement is consolidating around direct technical service relationships rather than distributor channels.
- Electronics:Connector housings, wire insulation, and circuit board substrates demand antioxidant systems compatible with lead-free solder reflow temperatures and RoHS substance restrictions. Electronics buyers prioritize extraction-resistant grades to prevent migration onto contact surfaces.
- Packaging:Food-contact compliance under EFSA and FDA regulations conditions antioxidant selection for polypropylene films and containers. Packaging processors favor masterbatch and pellet forms for dust-free handling.
- Construction:Geosynthetics, pipes, and weatherable profiles require UV-thermal stabilization packages with extended outdoor service life warranties.
Automotive leads specification-grade volumes; electronics shows the steepest specification escalation.
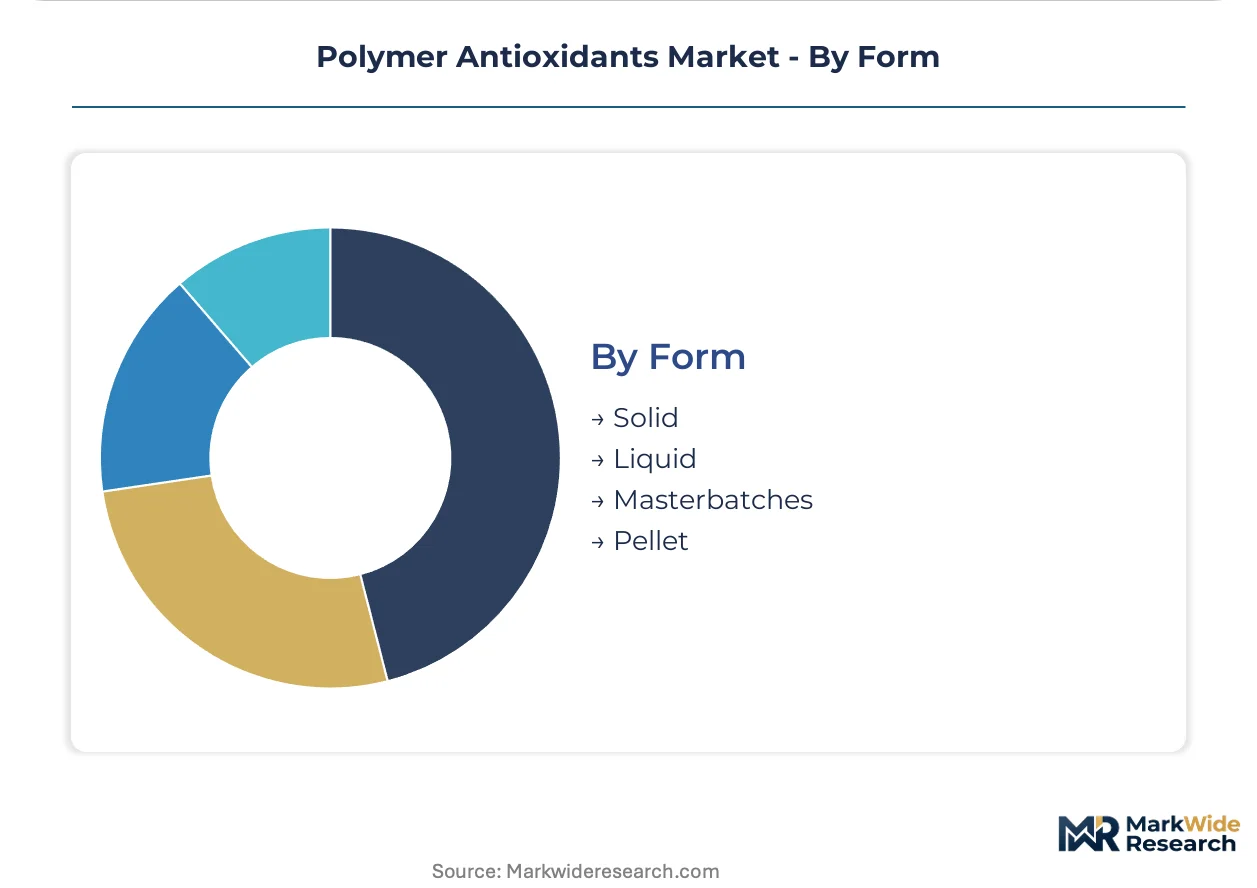
Form:
Handling economics and dosing precision drive form selection, with large-volume processors favoring concentrated formats that minimize warehouse footprint and weighing error.
- Solid:Crystalline or powder phenolic antioxidants serve small-batch compounders and custom rubber mixers with flexible dosing equipment. Solid forms dominate aminic antioxidant distribution for rubber applications.
- Liquid:Phosphite antioxidants in liquid form enable pump-fed continuous addition in polypropylene reactor finishing and large-scale compounding operations. Liquid handling eliminates dust exposure and improves dispersion uniformity.
- Masterbatches:Concentrated antioxidant dispersions in polymer carriers simplify downstream processing for film and injection molding operations without dedicated powder handling systems.
- Pellet:Dust-free solid formulations in pelletized form bridge handling convenience with solid antioxidant stability, preferred in automated feeding systems for extrusion and compounding lines.
Pellet and masterbatch forms lead volume convenience; liquid phosphites are climbing fastest in polypropylene reactor applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan maintain tighter specification-grade antioxidant procurement than China or India, where cost-optimized sulfur-based formulations still dominate tire and commodity plastics manufacturing.
Germany
Automotive cable compounders in Bavaria and Baden-Württemberg specify phenolic antioxidants for 150°C continuous service in electric vehicle architectures. ECHA REACH substance authorization requirements create competitive moats for producers with completed registration dossiers. The Rhine-Ruhr industrial corridor hosts integrated antioxidant intermediate production serving tier-1 automotive suppliers.
Japan
Automotive rubber compounders source aminic antioxidants for under-hood seals and gaskets subject to thermal aging specifications. METI chemical substance inventories condition market access for imported formulations. The Chubu region around Nagoya anchors domestic antioxidant blending capacity for Toyota and Honda supply chains.
China
Triphenyl phosphite and alkyl phosphite intermediate production clusters in Shandong and Jiangsu provinces. MIIT industrial chemical standards govern antioxidant substance registration for domestic polypropylene compounding expansion. The Yangtze River Delta concentrates polyolefin stabilization demand from packaging and automotive processors.
United States
EPA Toxic Substances Control Act provisions shape new chemical notification pathways for novel antioxidant structures. The Gulf Coast petrochemical corridor ties antioxidant margins to benzene-propylene spread volatility. Texas and Louisiana host phenol feedstock integration serving plastics stabilization formulators.
India
Domestic polypropylene film and injection molding expansion under PLI scheme incentives creates demand for phosphite-phenolic antioxidant systems. BIS standards for polymer additives condition import substitution strategies. Gujarat and Maharashtra industrial zones concentrate compounding capacity currently served through antioxidant import channels.
Polymer Antioxidants Market Vendor Landscape
Top-tier vendors anchor specification-grade antioxidant supply, while mid-cap blenders compete on cost-optimized sulfur-based formulations for tire and commodity applications. The market structures around three strategic archetypes: integrated petrochemical producers with captive intermediate supply, specialized phosphite and phenolic formulators, and regional distributors serving custom compounders. Competitive moves concentrate on REACH registration portfolio completion and direct technical service relationships with tier-1 automotive suppliers.
Within the integrated chemical producer tier, BASF SE and Solvay represent backward-integrated players with phenol and phosphite intermediate control. SONGWON occupies a position exemplifying phosphite antioxidant specialization for polyolefin stabilization systems. Adeka Corporation anchors the aminic antioxidant segment serving Japanese automotive rubber compounders under METI substance inventory requirements.
| Leading Market Players |
|---|
| BASF SE |
| SONGWON |
| Adeka Corporation |
| Solvay |
| SI Group, Inc. |
| Clariant |
| Sumitomo Chemical Co., Ltd. |
| 3V Sigma S.p.A. |
| Dover Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Benzene-propylene spread volatility cascades through antioxidant value chains, compressing margins for cumene-oxidation-dependent formulators while rewarding backward-integrated producers with captive phenol supply. Specification-grade phenolic antioxidants command substantial premiums over sulfur-based commodity alternatives as REACH registration costs and thermal performance certification create effective price floors.
Pricing Analysis
Capacity additions in Shandong province are reshaping price floors for phosphite intermediates, forcing European blenders to compete on technical service rather than cost alone. Three-tier pricing structure across specification-grade, standard industrial, and economy sulfur-based levels separates automotive-qualified phenolics from packaging-grade alternatives. Cost compression in commodity thioester antioxidants is intensifying because tire manufacturers retain volume procurement leverage. Packaging processors show highest price sensitivity; German automotive cable compounders prioritize lot consistency over unit cost.
Supply Chain Analysis
Direct-to-compounder channels handle tier-1 automotive demand, while distributor networks serve mid-tier polyolefin processors without dedicated stabilization laboratories. Triphenyl phosphite production clusters in China, South Korea, and Germany; phenol feedstock integration centers on the US Gulf Coast and Rotterdam. Antioxidant formulation draws from cumene oxidation, organophosphite synthesis, and aromatic amine chemistry. Single-source vulnerability runs through Shandong phosphite intermediate concentration. Distribution runs through certified compounders with in-house thermal aging capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer antioxidant markets reward geographic arbitrage between REACH-registered European supply and cost-optimized Asian manufacturing, with regulatory compliance cost differentials exceeding formulation margins in several product categories.
For Market Incumbents: Extend REACH registration portfolio coverage to capture specification-grade procurement consolidation among German and Japanese automotive suppliers. Deepen backward integration into phenol and phosphite intermediates to insulate margins from benzene-propylene spread volatility. Prioritize IATF 16949 certification maintenance as tier-1 suppliers eliminate uncertified blenders from approved vendor lists. For New Entrants and Emerging Players: Recycling-compatible antioxidant platforms offer technology-first entry into EU Green Deal circular economy mandates, where established suppliers lack proven reprocessing-cycle formulations. Target Indian phosphite-phenolic demand growth under PLI scheme incentives, currently served through import-dependent channels lacking local technical service presence. Lead with direct digital channels offering load-optimized recommendations to bypass traditional distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap formulators possessing completed REACH dossiers and automotive qualification relationships but lacking scale for global expansion. Five-to-ten year viability hinges on regulatory toxicology capabilities and recycling-stream stabilization expertise rather than commodity cost position. Monitor ECHA substance restriction proposals as inflection indicators for portfolio restructuring requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Intermediates | Captive cumene oxidation supply insulates BASF and Solvay from petrochemical cycle volatility. |
| REACH Registration Portfolio Completion | Full dossier status creates competitive moats for European producers serving automotive supply chains. |
| Recycling-Compatible Formulation Development | Multi-cycle stabilization efficacy addresses EU Green Deal automotive recyclate integration mandates. |
| Direct-to-Compounder Digital Channels | Technical service platforms bypass distributor markups in mid-tier polyolefin processing segments. |
| Phosphite Specialization for Polypropylene | Hydroperoxide decomposition synergy positions SONGWON for fastest-expanding antioxidant category demand. |
Methodological Framework
Multiple input streams — technical discussions with antioxidant formulators and automotive procurement leads, customs and trade flow analysis, and ECHA registration database review — were reconciled to construct demand estimates. Primary interviews with plant managers at polypropylene compounding facilities, technical R&D directors at stabilization laboratories, and distribution channel partners in Germany, Japan, and India informed supply-side dynamics. Secondary validation drew from SEC 10-K chemical segment disclosures, Cefic additive market reports, and MIIT industrial chemical registration records. Bottom-up volume modeling across product chemistry tiers was cross-checked against top-down polymer consumption projections.
Data-stream reconciliation anchored value forecasts to segment-specific pricing differentials and volume trajectories across the projection horizon. Segmentation dimensions included antioxidant chemistry type, polymer application, end-use industry certification tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted polymer demand growth and specification-grade penetration assumptions. Forecast inputs incorporated electric vehicle cable insulation thermal requirements, polypropylene compounding expansion rates, and REACH authorization timeline impacts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to phenol feedstock volatility and ECHA substance restriction evolution. Forecasts reflect documented assumptions regarding polymer recycling stream restabilization protocols and automotive OEM qualification timeline acceleration. Periodic stress-testing of base assumptions against phosphite intermediate supply concentration risks and regulatory toxicology expertise scarcity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Rotomolding Compound Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Global Opaque Polymers Market