
 Hydrocarbon Resins Market | 2026-2036
Hydrocarbon Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocarbon Resins Market Outlook
Bio-based feedstock substitution is rewriting the hydrocarbon resins technology stack, compelling producers to reformulate around renewable C5 and C9 streams without sacrificing tack or thermal stability. Eastman Chemical Company leverages its integrated hydrogenation capabilities to supply low-color premium grades for pressure-sensitive adhesives. ExxonMobil Corporation anchors global supply through its Baton Rouge and Rotterdam manufacturing complexes, sustaining feedstock security across Atlantic markets. KOLON Industries Inc. dominates Asia-Pacific specialty resin output, particularly hydrogenated DCPD grades for electronics and automotive sealants.
Hydrocarbon resins comprise thermoplastic polymers synthesized from petroleum-derived C5 aliphatic, C9 aromatic, or dicyclopentadiene (DCPD) feedstocks via cationic or thermal polymerization, yielding amorphous solids with softening points between 80°C and 140°C that function primarily as tackifiers, binders, and performance modifiers in formulated products. C5 resins lead adhesive applications due to superior compatibility with ethylene-vinyl acetate and styrene-isoprene-styrene block copolymers, while C9 aromatic resins command margin pools in high-performance coatings and rubber compounding where polarity and heat resistance matter. DCPD resins occupy the fastest-growing structural position, driven by hydrogenation advances that enable water-white grades penetrating medical packaging and electronic encapsulation segments.
EPA New Source Performance Standards and REACH Annex XVII restrictions on polycyclic aromatic hydrocarbon content shape formulation choices and import eligibility across North American and European markets. China's GB standards on volatile organic compound emissions in adhesive products, enforced by MEE provincial bureaus, compel domestic producers toward hydrogenated and water-white resin grades. Stakeholders must monitor feedstock volatility from steam cracker operating rate fluctuations and bio-based alternative yield scalability to secure margin stability through the forecast horizon.
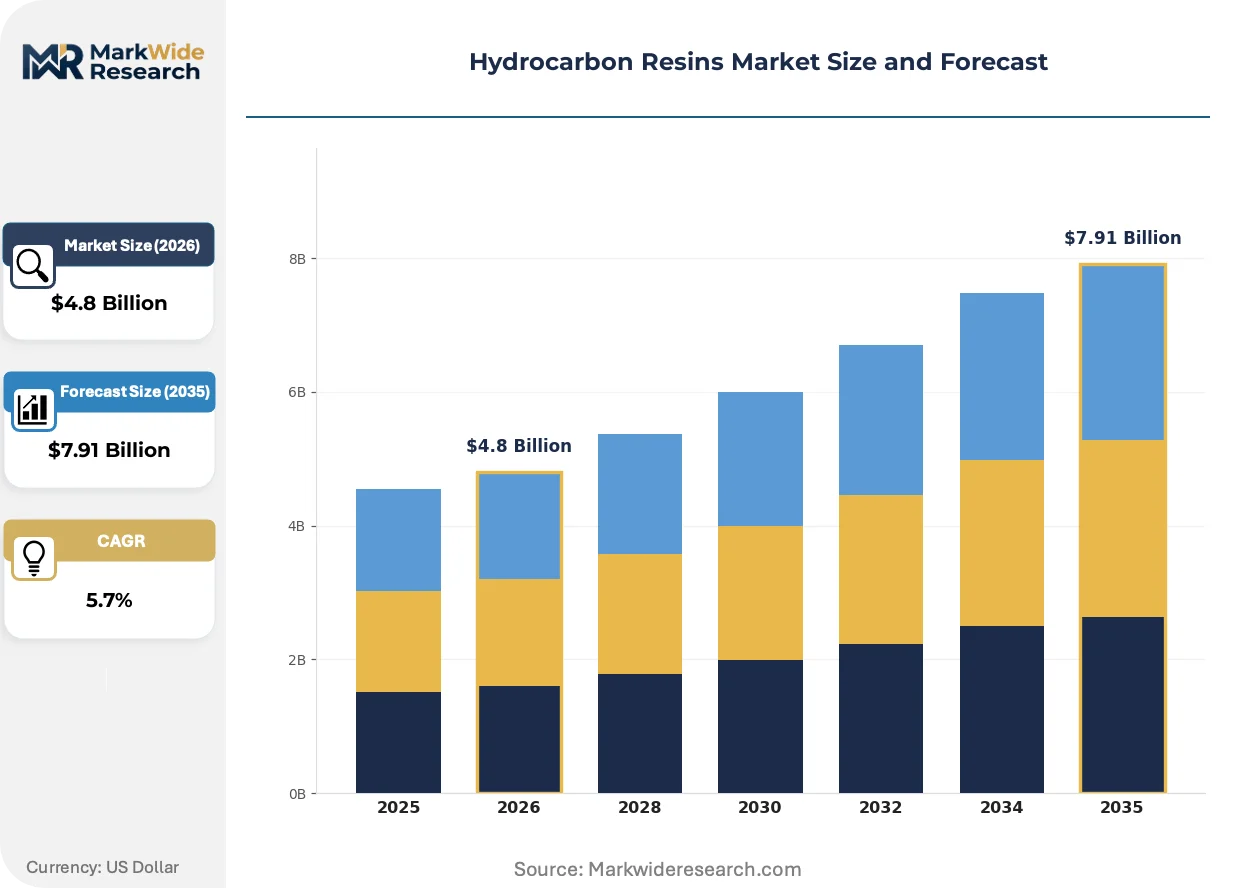
Market Dynamics
Bio-based feedstock substitution is compressing conventional petroleum-derived resin margins while hydrogenation technology unlocks water-white grades for medical and electronics packaging. Producers must now balance renewable C5 and C9 stream yields against thermal stability and tack performance requirements.
Growth Catalysts
- REACH Annex XVII PAH restrictions:European limits on polycyclic aromatic hydrocarbon content in rubber compounding are accelerating hydrogenated DCPD resin adoption across tire manufacturing.
- Hot-melt adhesive penetration:Automotive assembly plants in Germany, Japan, and the United States are replacing mechanical fasteners with C5-compatible pressure-sensitive formulations.
- China's eastern manufacturing corridor:Packaging and tire production clusters in Jiangsu and Zhejiang provinces sustain bulk procurement volumes for aliphatic resins.
Market Restraints
- Steam cracker feedstock volatility:Operating rate fluctuations at naphtha crackers in the US Gulf Coast and Rotterdam directly constrain C5 and DCPD monomer availability.
- Bio-based yield scalability:Renewable tall oil and turpentine-derived streams currently achieve only fractional substitution rates without sacrificing softening point consistency.
- EPA New Source Performance Standards:VOC emission thresholds for adhesive formulations are tightening capital requirements for North American production expansions.
Strategic Opportunities
- India's packaging sector:BIS certification requirements for food-contact adhesives create first-mover advantage for hydrogenated resin suppliers establishing local technical service.
- Electronic encapsulation:Water-white DCPD grades are penetrating semiconductor underfill and display lamination applications previously served by silicone alternatives.
- EU Green Deal sustainable chemistry mandates:Mass balance certification for bio-attributed resins opens premium pricing pools in cosmetics and pharmaceutical packaging.
Industry Challenges
- Hydrogenation catalyst expertise:Specialized reactor operation and noble metal recovery capabilities remain concentrated among a limited set of engineering contractors.
- MEE provincial enforcement variance:China's GB standards on volatile organic compound emissions are applied inconsistently across Jiangsu, Shandong, and Guangdong bureaus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocarbon Resins Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerized Resin, C5 Resin, C9 Resin, Dicyclopentadiene Resin Application: Adhesives, Coatings, Inks, Rubber Compounds End User: Automotive, Construction, Packaging, Woodworking Form: Solid, Liquid, Powder, Granular |
| Companies Covered | Eastman Chemical Company, ExxonMobil Corporation, TotalEnergies (Cray Valley), KOLON Industries Inc., Arakawa Chemical Industries Ltd., Lesco Chemical Limited, Zeon Corporation, Shandong Landun Petroleum Resin Co., Ltd., Puyang Tiancheng Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocarbon Resins Market Strategic Shifts
Hydrogenation technology is rewriting grade specifications across adhesive and coating applications. Three parallel developments are compressing product lifecycles and reshaping supplier-customer technical relationships.
Partial hydrogenation is migrating from niche premium grades to standard adhesive formulations. Tire manufacturers in Japan and South Korea now specify lightly hydrogenated C9 resins for tread compounds. This technology is compressing the price premium between aromatic and hydrogenated grades by half within three product generations.
REACH compliance deadlines for PAH content in consumer goods are forcing reformulation across European rubber compounding. ECHA enforcement actions against imported tire imports have triggered supply contract renegotiations. German and Czech tire plants are accelerating qualification of hydrogenated DCPD alternatives ahead of 2027 certification requirements.
Specification-driven buying is consolidating procurement authority at multinational adhesive formulators. Regional distributors in Southeast Asia are losing technical specification influence to central R&D laboratories in Basel and Shanghai. This concentration is most visible in pressure-sensitive adhesive tape manufacturing, where global accounts now dictate resin softening point tolerances below two degrees Celsius variance.
Hydrocarbon Resins Market Segmentation
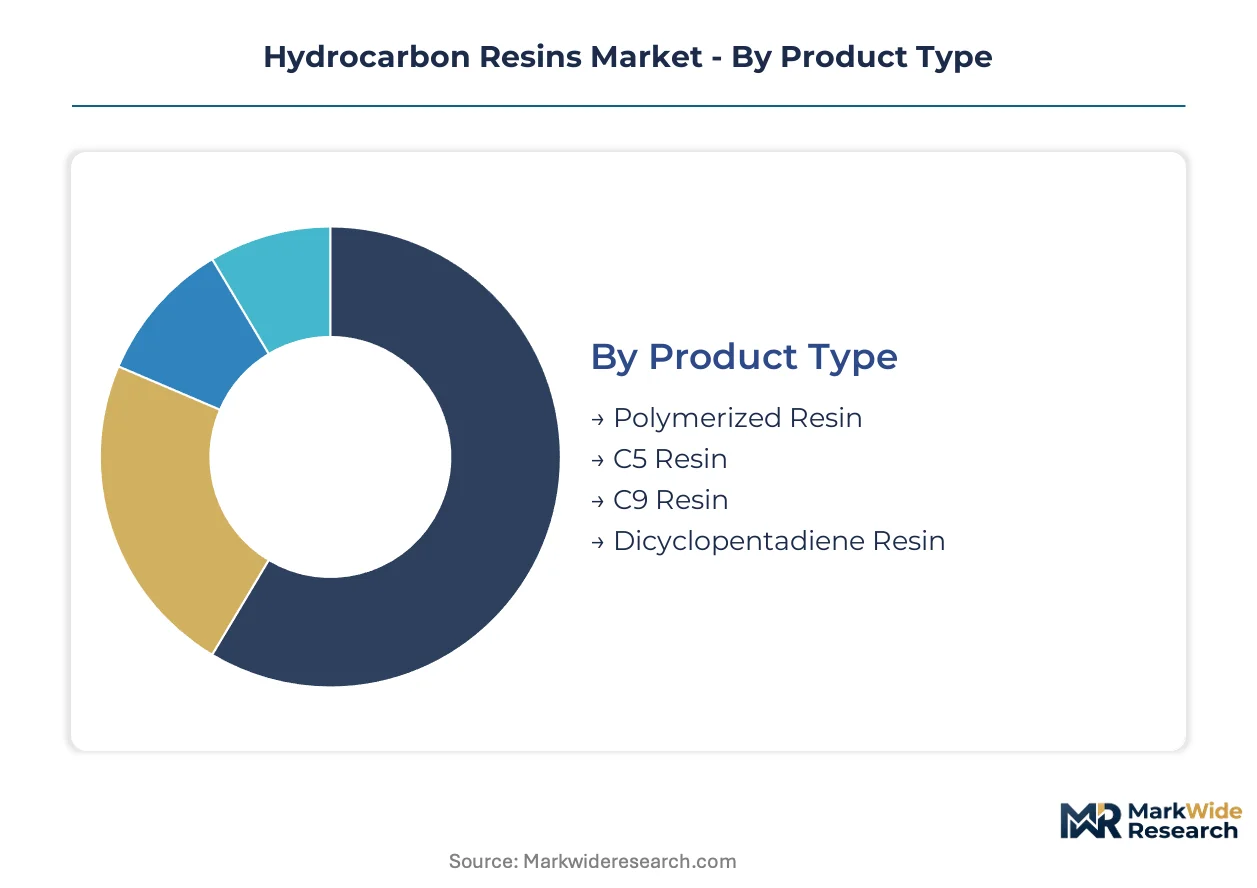
Feedstock chemistry and hydrogenation depth determine grade economics, while application-specific tack and thermal stability requirements drive procurement fragmentation across adhesive formulators and tire manufacturers.
Product Type:
Polymerization chemistry spans aliphatic, aromatic, and dicyclopentadiene feedstocks, each delivering distinct compatibility profiles with elastomers and coatings binders.
- C5 Resin:Aliphatic structures polymerized from piperylene and isoprene streams deliver superior compatibility with ethylene-vinyl acetate and styrene-isoprene-styrene block copolymers. Automotive assembly plants in Germany and Japan specify C5 grades for hot-melt pressure-sensitive adhesive formulations replacing mechanical fasteners.
- Dicyclopentadiene Resin:Hydrogenation advances unlock water-white grades with exceptional thermal stability and low color. Semiconductor packaging manufacturers in South Korea and medical film producers in Switzerland are qualifying hydrogenated DCPD for electronic encapsulation and pharmaceutical barrier applications.
- C9 Resin:Aromatic structures from vinyltoluene and indene streams provide polarity and heat resistance for high-performance coatings and rubber compounding where solubility parameter matching matters.
- Polymerized Resin:Blended or modified grades combine C5 and C9 fractions to achieve intermediate properties for general-purpose adhesive and sealant formulations.
The dominant share belongs to C5 Resin, while Dicyclopentadiene Resin is closing the gap fastest.
Application:
Performance requirements vary sharply across bonding, surface protection, and reinforcement functions.
- Adhesives:Tackifier loading in hot-melt and pressure-sensitive formulations demands precise softening point control. REACH Annex XVII PAH restrictions are accelerating hydrogenated grade qualification across European tape and label manufacturing.
- Rubber Compounds:Reinforcement and tackification in tire tread and sidewall formulations. ECHA enforcement against imported tires with elevated polycyclic aromatic hydrocarbon content has triggered reformulation mandates at German and Czech production facilities.
- Coatings:Binder modification for industrial and protective coatings where gloss retention and UV resistance are critical.
- Inks:Pigment wetting and gloss enhancement in publication gravure and flexographic printing applications.
Adhesives command the largest volume position, with Rubber Compounds expanding most quickly on regulatory-driven grade upgrading.
End User:
Industry-specific certification and performance standards fragment procurement specifications.
- Automotive:Hot-melt adhesive penetration in assembly operations demands low-VOC, high-heat-resistance grades. EPA New Source Performance Standards are tightening emission thresholds for adhesive formulations at US assembly plants.
- Packaging:Food-contact and medical-grade applications require hydrogenated water-white resins with extractables compliance. China's GB standards on volatile organic compound emissions in adhesive products are enforced variably across Jiangsu, Shandong, and Guangdong provincial bureaus.
- Construction:Sealant and waterproofing membrane applications prioritize UV stability and adhesion to diverse substrates.
- Woodworking:Edgebanding and panel lamination adhesives emphasize heat resistance and bond durability.
Automotive maintains the leading share, though Packaging is gaining ground fastest on medical and electronics qualification requirements.
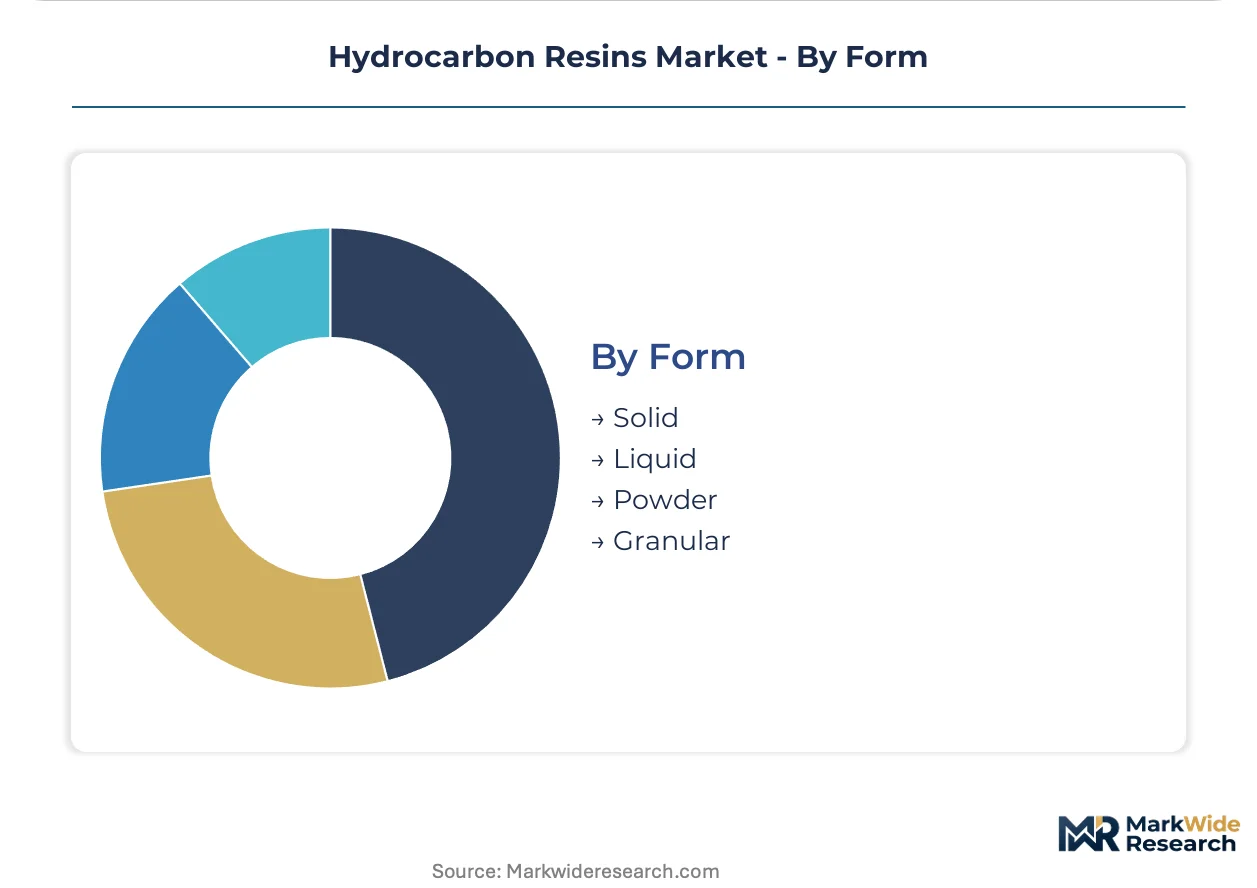
Form:
Physical state determines handling economics and formulation integration methods.
- Solid:Flaked or block forms dominate bulk adhesive compounding. Hot-melt adhesive manufacturers in China's eastern manufacturing corridor prefer solid delivery for melt tank feeding.
- Granular:Low-dust handling characteristics suit automated weighing systems. Tire compounders in Japan specify granular grades for Banbury mixer integration.
- Liquid:Solvent-cut or molten bulk delivery for coatings and ink manufacturers with direct pumping infrastructure.
- Powder:Micronized grades for powder coating and specialty adhesive applications requiring precise dispersion control.
Solid forms retain the dominant position, while Granular formats are climbing fastest on automation and dust-control priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam-to-Asia shipping lanes carry hydrogenated DCPD resin cargoes that supply South Korean electronics packaging and Chinese tire manufacturing clusters. This Atlantic-Pacific trade corridor reflects diverging regulatory pressures and specialty-grade demand across terminal markets.
United States
EPA New Source Performance Standards tighten VOC emission thresholds at automotive assembly plants in Michigan and Tennessee. Baton Rouge petrochemical complexes anchor C5 and DCPD feedstock security for adhesive formulators serving Detroit's EV production lines. Domestic producers face capital-intensive compliance timelines for hydrogenation capacity expansions.
Germany
REACH Annex XVII PAH restrictions accelerate hydrogenated grade qualification at Continental and Michelin tire plants. ECHA enforcement actions against imported rubber goods trigger supply contract renegotiations across the Rhine-Ruhr industrial belt. Stuttgart automotive clusters specify low-color premium resins for interior bonding applications.
China
GB standards on volatile organic compound emissions in adhesive products are enforced variably across Jiangsu, Shandong, and Guangdong provincial MEE bureaus. Yangtze River Delta packaging manufacturers in Suzhou and Nantong sustain bulk procurement volumes for aliphatic resins. Domestic hydrogenation capacity lags specialty-grade demand from semiconductor packaging producers in Shanghai.
Japan
METI carbon neutrality roadmaps pressure petrochemical refiners toward bio-attributed feedstock blends. Nagoya automotive assembly plants replace mechanical fasteners with hot-melt pressure-sensitive formulations. Tire compounders in Osaka specify granular resin grades for automated Banbury mixer integration.
South Korea
MFDS medical-grade certification requirements create technical barriers for imported hydrogenated resins. Busan-Ulsan chemical complexes expand hydrogenation capacity to serve Samsung and SK Hynix semiconductor underfill applications. Display lamination manufacturers in Gyeonggi Province qualify water-white DCPD grades as silicone alternatives.
Hydrocarbon Resins Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct value-capture tiers. Integrated petrochemical majors leverage feedstock security and hydrogenation capabilities to dominate premium-grade supply. Mid-scale regional producers concentrate on standardized aliphatic resins for packaging and construction adhesives. Competitive dynamics center on backward integration into steam cracker feedstocks and technology licensing for partial hydrogenation reactor design.
Among Asia-Pacific specialists, KOLON Industries Inc. and Arakawa Chemical Industries Ltd. occupy positions within the hydrogenated premium-grade tier. Eastman Chemical Company and ExxonMobil Corporation exemplify the integrated multinational archetype with captive feedstock positions across Atlantic markets. These four named entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| ExxonMobil Corporation |
| TotalEnergies (Cray Valley) |
| KOLON Industries Inc. |
| Arakawa Chemical Industries Ltd. |
| Lesco Chemical Limited |
| Zeon Corporation |
| Shandong Landun Petroleum Resin Co., Ltd. |
| Puyang Tiancheng Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
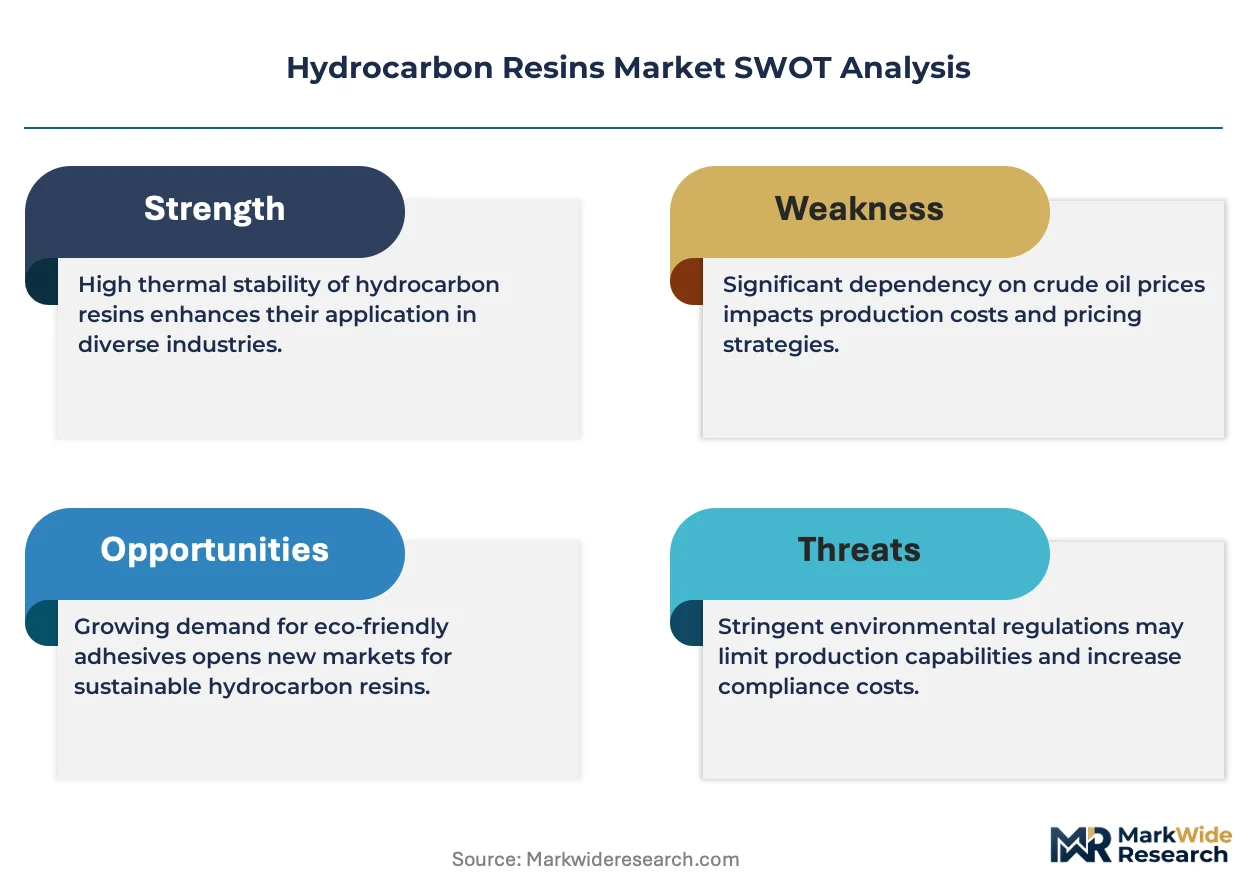
US Gulf Coast steam cracker concentration anchors C5 and DCPD monomer pricing power for downstream resin formulators, compressing margin pools at hydrogenation-dependent specialty grades while standard aliphatic resins compete on volume scale.
Pricing Analysis
Cost-plus contracts indexed to naphtha and crude oil benchmarks dominate feedstock procurement, with hydrogenation depth separating premium water-white grades from commodity aromatic tiers. Price differentiation rests on color specification and PAH certification level, with REACH Annex XVII compliance commanding substantial premiums. Pricing pressure stems from bio-based tall oil rosin substitution in packaging adhesives. Tire compounders exhibit highest price sensitivity, while semiconductor packaging buyers prioritize thermal stability over unit cost.
Supply Chain Analysis
Contract hydrogenation capacity concentrates at Eastman Chemical's Longview complex and KOLON Industries' Gimcheon facilities, limiting third-party tolling options for water-white grade production. Manufacturing gravity centers on the United States, South Korea, and Germany, with raw material dependencies spanning steam cracker C5 streams, DCPD from ethylene byproduct recovery, and noble metal catalysts for hydrogenation. Single-source vulnerability pervades palladium and platinum supply from Russian and South African mining operations. Distribution runs through regional chemical distributors with technical service capabilities for adhesive formulator qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized reactor operation expertise and noble metal recovery capabilities constitute scarce assets that constrain competitive entry, particularly for medical-grade and electronic encapsulation resin qualifications requiring MFDS and FDA compliance documentation.
For Market Incumbents: Build captive hydrogenation capacity moats through backward integration into C5 fractionation and catalyst regeneration operations. Secure long-term offtake agreements with South Korean semiconductor packaging manufacturers before domestic hydrogenation capacity expansion completes. Prioritize mass balance certification investments to capture EU Green Deal sustainable chemistry premium pools in cosmetics and pharmaceutical packaging applications. For New Entrants and Emerging Players: Establish a beachhead in India's food-contact adhesive segment by securing BIS certification ahead of multinational qualification timelines. Target granular resin formats for Japanese tire compounders seeking Banbury mixer automation compatibility. Pursue technical service partnerships with regional distributors in Southeast Asia to bypass consolidated global account procurement authority. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale hydrogenation specialists with existing medical-grade qualifications and unfilled capacity expansion permits. Long-term viability favors assets with demonstrated catalyst recovery economics and established relationships with Samsung or SK Hynix supply chain managers. Monitor South Korean domestic hydrogenation capacity utilization rates as the inflection signal for import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C5 Fractionation | Captive feedstock security insulates margin stability against US Gulf Coast cracker operating rate volatility. |
| Hydrogenation Capacity Expansion | Additional reactor trains at Baton Rouge or Rotterdam complexes capture water-white grade demand from medical packaging producers. |
| Mass Balance Certification Program | Bio-attributed resin credentials unlock EU Green Deal premium pricing in Swiss pharmaceutical barrier applications. |
| Long-term Supply Agreement with Semiconductor Packaging | Contracted volumes with Samsung or SK Hynix secure qualification-driven revenue visibility through technology node transitions. |
| Joint Venture for Regional Hydrogenation | Local production partnerships in Jiangsu province circumvent MEE provincial enforcement variance risks for Chinese adhesive formulators. |
Study Parameters
Initial hypotheses were tested against primary input from adhesive formulator procurement directors, tire manufacturer compounders, hydrogenation plant managers, and specialty resin distributors, then refined through secondary validation against SEC 10-K filings, Cefic industry reports, USITC trade databases, and customs import records. Bottom-up volume estimates from end-use application consumption rates were triangulated against top-down steam cracker byproduct availability models.
Demand-supply balance modeling across the analysis window incorporated feedstock chemistry segmentation, hydrogenation depth tiers, and regional regulatory cluster differentiation. CAGRs were derived from segment-level volume trajectories weighted by value-per-ton grade premiums. Key forecast inputs included steam cracker operating rate projections and bio-based tall oil rosin yield scalability assumptions.
Sensitivities concentrate around naphtha price volatility, REACH enforcement intensity against imported rubber goods, and palladium catalyst cost inflation. Forecasts reflect documented assumptions on hydrogenation technology diffusion rates and bio-attributed feedstock mass balance accounting standards. Quarterly review of South Korean semiconductor packaging capacity utilization and German tire plant reformulation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market