
 Polyfluoroalkyl Substances (PFAS) Waste Management Market | 2026-2036
Polyfluoroalkyl Substances (PFAS) Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Polyfluoroalkyl Substances (PFAS) Waste Management Market Analytics
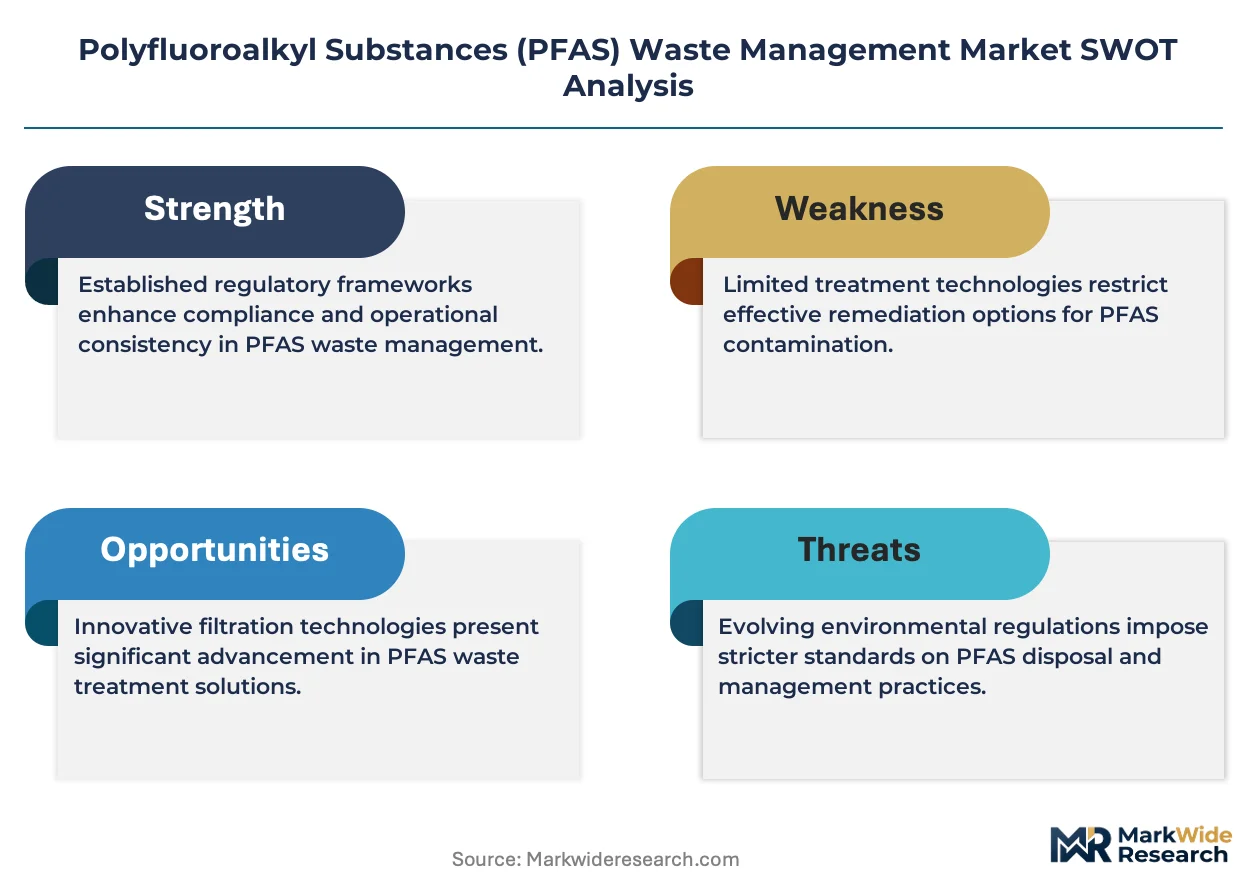
Thermal destruction and advanced oxidation process integration is tilting capital deployment toward high-temperature mineralization systems. Veolia Environnement S.A. leverages its European hazardous waste incineration network to anchor PFAS destruction capacity. Clean Harbors Inc. dominates North American thermal treatment infrastructure for fluorinated waste streams. Jacobs Engineering Group specializes in remediation engineering for Department of Defense PFAS site closures.
Polyfluoroalkyl substances waste management encompasses the collection, transport, treatment, and final disposition of materials containing per- and polyfluoroalkyl compounds with carbon-fluorine bond energies exceeding 485 kJ/mol, requiring thermal or chemical destruction rather than conventional biological degradation. The field addresses legacy contamination from aqueous film-forming foams, industrial process wastewater, and consumer product manufacturing residuals. Contaminated soil and groundwater categories carry the largest volume bases, though sludge treatment commands premium pricing due to concentrated fluoropolymer content. Chemical decomposition technologies represent the fastest-growing treatment segment as regulators tighten destruction removal efficiency standards beyond incineration capabilities. Manufacturing facilities constitute the most regulated end-user channel, while environmental agencies are emerging as high-volume procurement bodies for superfund and military remediation.
The EPA's CERCLA hazardous substance designation and emerging state-level maximum contaminant levels are reshaping liability frameworks and treatment mandates across the United States. The EU REACH restriction proposals and F-Gas Regulation phase-down are accelerating destruction demand for imported PFAS stocks in Europe. Stakeholders must monitor evolving destruction removal efficiency thresholds and emerging plasma-based mineralization alternatives to align capital commitments with regulatory compliance horizons.
Market Dynamics
The EPA's CERCLA hazardous substance designation is forcing immediate capital deployment into thermal mineralization infrastructure, while destruction removal efficiency thresholds tighten faster than incumbent technologies can achieve.
Growth Catalysts
- Defense sector remediation:Department of Defense base closures are generating concentrated PFAS waste streams requiring immediate contractor procurement for soil and groundwater treatment.
- REACH restriction proposals:ECHA's accelerating regulatory timeline is mandating destruction of imported PFAS stocks across European industrial facilities.
- Plasma-based mineralization:Emerging high-temperature decomposition technologies are achieving destruction removal efficiencies beyond conventional incineration capabilities.
Market Restraints
- Energy cost volatility:Thermal destruction's dependence on natural gas and electricity inputs creates margin compression during price spikes.
- Permitting bottlenecks:EPA and state-level air quality approvals for new high-temperature facilities extend project timelines by 24-36 months.
- Legacy liability fragmentation:CERCLA's retroactive application spreads cleanup costs across defunct manufacturers, insurers, and current property owners.
Strategic Opportunities
- Mobile treatment units:Deployable plasma and supercritical water oxidation systems are opening Department of Defense and remote industrial site markets previously unreachable by fixed infrastructure.
- State-level MCL adoption:Emerging maximum contaminant levels in Michigan, New York, and California are accelerating municipal procurement for drinking water treatment.
- Sludge-to-energy integration:Concentrated fluoropolymer waste streams from wastewater treatment plants are enabling energy recovery co-products that offset destruction costs.
Industry Challenges
- Specialized operator scarcity:PFAS-specific thermal system operation and maintenance expertise remains concentrated among a limited workforce pool.
- Validation protocol delays:EPA Method 1633 and equivalent analytical standards for demonstrating destruction removal efficiency are still undergoing multi-laboratory certification.
- Residual characterization uncertainty:Incomplete understanding of short-chain PFAS transformation products complicates final waste classification decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyfluoroalkyl Substances (PFAS) Waste Management Market |
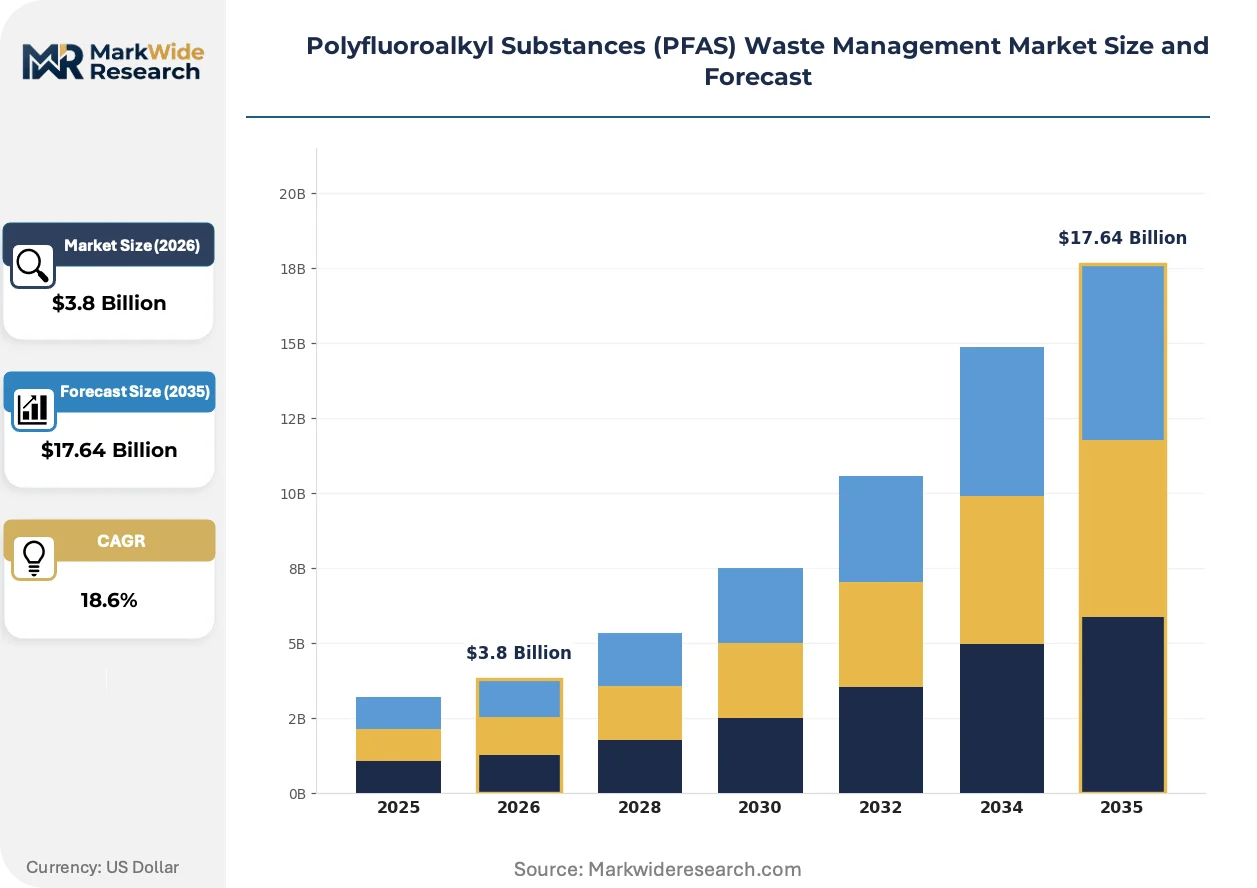
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Contaminated Soil, Groundwater, Wastewater, Sludge Treatment Technology: Activated Carbon, Reverse Osmosis, Incineration, Chemical Decomposition End User: Manufacturing Facilities, Municipalities, Environmental Agencies, Remediation Contractors Regulatory Framework: Federal Standards, State Regulations, Local Ordinances, International Guidelines |
| Companies Covered | Jacobs Engineering Group, AECOM, Veolia Environnement S.A., Ovivo, Wood PLC, Clean Harbors Inc., Arcadis NV, Aclarity, Tetra Tech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyfluoroalkyl Substances (PFAS) Waste Management Market Evolving Landscape
Treatment technology evolution is compressing the viable technology set toward systems capable of mineralizing carbon-fluorine bonds completely, while regulatory pressure accelerates obsolescence of partial destruction methods.
Supercritical water oxidation is hybridizing with thermal plasma injection to achieve simultaneous high-temperature decomposition and rapid quenching that prevents recombination of fluorinated fragments. Defense contractors and industrial facilities with concentrated aqueous film-forming foam stocks are piloting these integrated systems at 10-50 ton per day scales. The hybrid architecture is compressing project development timelines by eliminating separate pre-concentration steps.
The EPA's CERCLA hazardous substance designation for PFOA and PFOS is triggering immediate reporting obligations and retroactive liability for releases dating to the 1970s. Manufacturing facilities and municipal airports with historical foam use are now conducting comprehensive site assessments to quantify potential cleanup obligations. The designation is accelerating procurement of permanent destruction capacity over temporary containment solutions across the United States.
Service contracting for PFAS waste management is consolidating around performance-guaranteed destruction contracts that transfer analytical and regulatory risk to treatment providers. Municipal water utilities and industrial facilities are displacing time-and-materials arrangements with fixed-price agreements tied to verified destruction removal efficiency certificates. This shift is most visible in Michigan and North Carolina, where state-funded remediation programs prioritize contractors with demonstrated plasma or supercritical oxidation capabilities.
Polyfluoroalkyl Substances (PFAS) Waste Management Market Segmentation
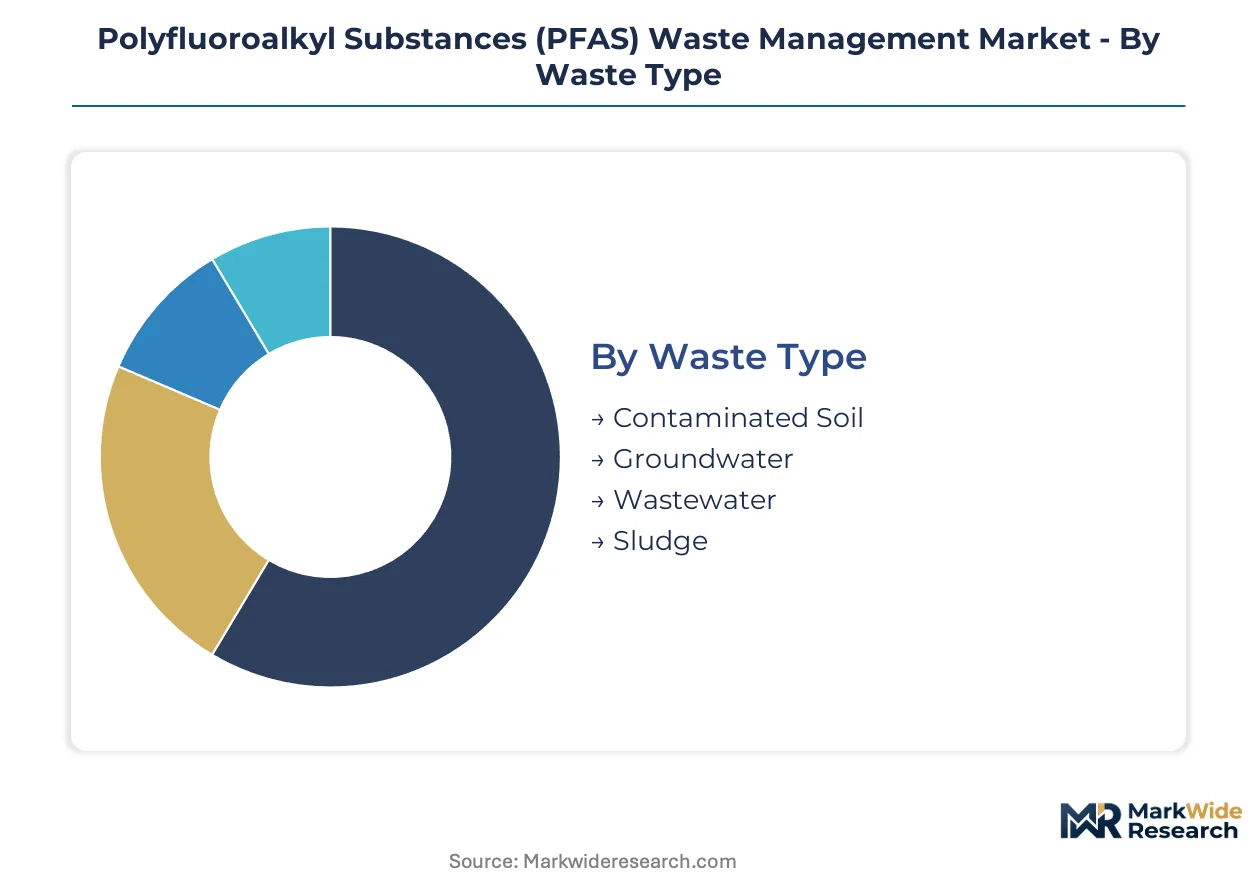
PFAS waste management segmentation reveals starkly different capital intensity and contract velocity across waste matrices and treatment modalities. Cycle time variation—from decades-long groundwater plume remediation to rapid-turn sludge destruction—determines contractor working capital requirements and technology deployment patterns.
Waste Type:
Soil and groundwater remediation cycles span years, while sludge and wastewater treatment turn in months, creating divergent revenue recognition profiles for service providers.
- Contaminated Soil:Excavated materials from military fire training areas and industrial legacy sites carry complex co-contaminant profiles requiring staged thermal desorption. Department of Defense base closures in the United States are concentrating procurement for large-volume soil remediation, though dewatering and pretreatment steps extend project timelines.
- Groundwater:Plume interception systems using pump-and-treat architectures face decades-long operational horizons as PFAS migrate through surficial aquifers. Municipal water utilities in Michigan and North Carolina are accelerating wellhead treatment installations as state maximum contaminant levels tighten.
- Wastewater:Industrial process streams from fluoropolymer manufacturing and metal plating operations contain high-concentration PFAS amenable to concentrated destruction. Manufacturing facilities in Germany and the United States are retrofitting on-site treatment to comply with ECHA REACH restrictions and EPA discharge permits.
- Sludge:Biosolids from wastewater treatment plants concentrate PFAS through sorption to organic matter, commanding premium destruction pricing due to high fluorine content per unit volume. European utilities are prioritizing sludge-to-energy pathways that offset thermal mineralization costs.
Contaminated soil dominates installed base. Sludge is where expansion concentrates.
Treatment Technology:
Capital deployment stratifies sharply between adsorption-based containment and destruction technologies, with margin profiles inversely correlated to regulatory validation burden.
- Activated Carbon:Granular and powdered carbon systems provide proven PFAS capture for water treatment, though spent media requires subsequent thermal destruction. Municipal utilities facing immediate compliance deadlines are deploying carbon vessels as interim solutions while permanent destruction capacity comes online.
- Reverse Osmosis:Membrane concentration generates high-strength brines requiring specialized handling, with concentrate volumes typically 5-10% of feedwater flow. Industrial facilities in Japan and South Korea are integrating reverse osmosis with crystallization to minimize liquid waste transport costs.
- Incineration:Hazardous waste rotary kilns and cement kilns achieve mineralization at temperatures exceeding 1,100°C, though stack emissions monitoring for fluorinated byproducts adds regulatory complexity. Clean Harbors and Veolia are expanding North American and European incineration capacity respectively.
- Chemical Decomposition:Supercritical water oxidation and plasma arc systems achieve destruction removal efficiencies beyond incineration capabilities, eliminating residual liability concerns. Defense contractors are piloting mobile chemical decomposition units for remote site remediation.
Incineration dominates installed base. Chemical decomposition is climbing the fastest.
End User:
Procurement sophistication varies dramatically across customer types, from compliance-driven manufacturing facilities to risk-transfer-seeking environmental agencies.
- Manufacturing Facilities:Fluoropolymer producers, semiconductor fabricators, and chrome plating operations face direct liability for process wastewater and legacy contamination. Facilities in the United States are shifting from time-and-materials contracts to fixed-price destruction agreements.
- Municipalities:Drinking water utilities and wastewater treatment plants are absorbing PFAS treatment costs through ratepayer-funded capital programs. Cities in California and New York are advancing bond issuances specifically for PFAS infrastructure.
- Environmental Agencies:EPA, state environmental departments, and military environmental commands are emerging as high-volume procurement bodies for superfund and base closure remediation. The EPA's CERCLA enforcement is accelerating agency-led competitive tendering.
- Remediation Contractors:Environmental service firms are consolidating PFAS capabilities through technology licensing and specialist acquisitions. Jacobs Engineering and AECOM are building integrated investigation-through-destruction service lines.
Manufacturing facilities dominate installed base. Environmental agencies are gaining share fastest.
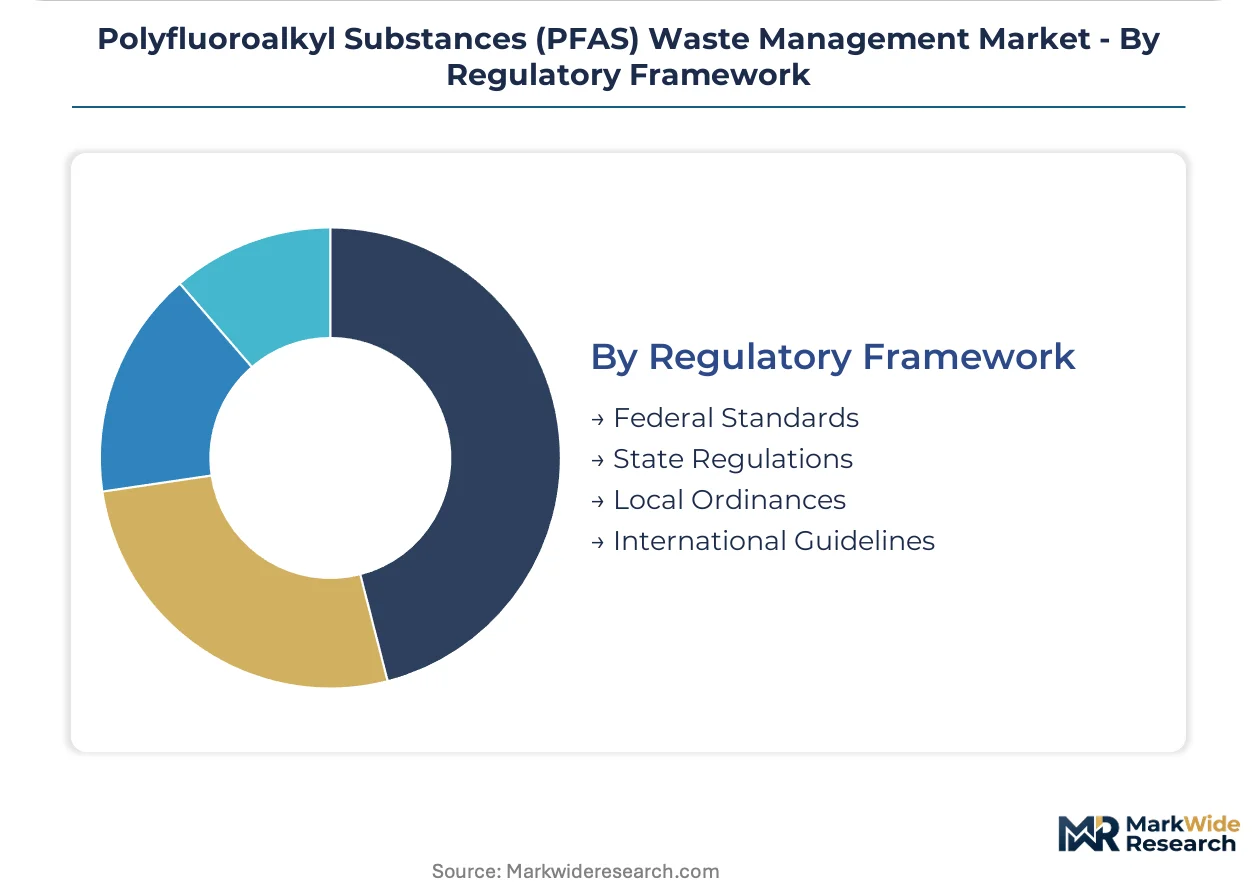
Regulatory Framework:
Compliance obligation timing and stringency diverge across jurisdictional tiers, with federal designations triggering immediate action while local ordinances create fragmented permitting landscapes.
- Federal Standards:EPA's CERCLA hazardous substance designation for PFOA and PFOS mandates immediate reporting and retroactive liability. The United States federal framework is forcing capital deployment into permanent destruction infrastructure.
- State Regulations:Michigan, North Carolina, and California maximum contaminant levels are accelerating municipal procurement ahead of federal timelines. State-level enforcement creates parallel compliance tracks with varying analytical methods.
- Local Ordinances:County and municipal discharge restrictions are imposing pretreatment requirements on industrial facilities. Local air quality districts in California are adding permitting layers beyond state and federal requirements.
- International Guidelines:OECD testing guidelines and WHO drinking water advisories are shaping regulatory development in jurisdictions without domestic PFAS standards. Emerging economies are adopting OECD frameworks for import screening and contamination assessment.
Federal standards dominate installed base. State regulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement departments and municipal water utilities concentrate buying power across four national markets. Each jurisdiction imposes distinct destruction efficiency mandates that shape contractor qualification requirements.
United States
Department of Defense base closures in Michigan and North Carolina are generating concentrated soil and groundwater remediation contracts. EPA's CERCLA hazardous substance designation for PFOA and PFOS triggers immediate reporting obligations for releases dating to the 1970s. Clean Harbors operates thermal treatment infrastructure serving military environmental commands and industrial legacy sites across the Southeast and Midwest.
Germany
Fluoropolymer manufacturing facilities in North Rhine-Westphalia face accelerated destruction timelines under ECHA REACH restriction proposals. The country's national environmental regulator enforces stringent air quality permits for high-temperature mineralization systems. Industrial clusters along the Rhine corridor are retrofitting on-site treatment to comply with discharge limits ahead of federal deadlines.
France
Veolia leverages its European hazardous waste incineration network to anchor PFAS destruction capacity for imported stocks. ECHA's regulatory timeline mandates destruction of aqueous film-forming foam inventories held at municipal airports and military installations. The Paris metropolitan area concentrates procurement for drinking water treatment infrastructure as precautionary maximum contaminant levels tighten.
Japan
Industrial facilities in the Kanto region are integrating reverse osmosis with crystallization systems to minimize liquid waste transport costs. The country's Ministry of Economy, Trade and Industry guides technology adoption through voluntary guidelines aligned with OECD testing frameworks. Semiconductor fabricators in Kyushu represent emerging demand for process wastewater treatment as fluorinated chemical use expands.
Canada
Health Canada and PMRA are developing federal drinking water guidelines that accelerate municipal procurement in Ontario and Quebec. Provincial environmental ministries enforce site-specific cleanup standards for fire training areas at commercial airports and military installations. Remediation contractors in the Toronto-Waterloo corridor are building integrated investigation-through-destruction service capabilities.
Polyfluoroalkyl Substances (PFAS) Waste Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct capability tiers. The market structure consolidates around incineration operators with validated destruction removal efficiency certificates, engineering firms with remediation execution expertise, and emerging technology developers with plasma-based mineralization systems. Two strategic archetypes dominate: asset-heavy thermal treatment providers securing long-term military contracts, and technology-licensing specialists deploying mobile units for remote site access. Competitive moves concentrate on M&A for specialized operator talent and strategic partnerships to accelerate permitting timelines.
Within the asset-heavy tier, Veolia Environnement S.A. and Clean Harbors Inc. exemplify geographic anchoring strategies, with the former leveraging European hazardous waste infrastructure and the latter dominating North American thermal treatment capacity. Jacobs Engineering Group occupies a position bridging remediation engineering and Department of Defense site closure execution. These three companies represent divergent approaches to regulatory risk transfer, from fixed-price destruction guarantees to performance-certified service contracting.
| Leading Market Players |
|---|
| Jacobs Engineering Group |
| AECOM |
| Veolia Environnement S.A. |
| Ovivo |
| Wood PLC |
| Clean Harbors Inc. |
| Arcadis NV |
| Aclarity |
| Tetra Tech Inc. |
| Others |
Value Network & Pricing Analysis
Natural gas supply concentration in the United States Gulf Coast and North Sea corridors directly determines margin distribution across thermal mineralization service tiers, with energy-indexed contracts passing through commodity volatility to defense procurement departments while fixed-price agreements concentrate risk with treatment providers.
Pricing Analysis
Cost-plus contracts indexed to Henry Hub natural gas benchmarks dominate Department of Defense remediation procurement, with price differentiation driven by destruction removal efficiency certification tier and mobile deployment capability. Pricing pressure intensifies in the activated carbon interim treatment segment as utilities delay permanent destruction commitments. Municipal water utilities exhibit highest price sensitivity due to ratepayer funding constraints, while environmental agencies demonstrate lowest sensitivity under CERCLA-mandated liability timelines.
Supply Chain Analysis
Extended payment terms from environmental agencies and supply-chain finance facilities from hazardous waste incineration operators stabilize working capital across project cycles. Equipment manufacturing concentrates in Germany, the United States, and Japan, while specialized carbon-fiber electrode supply for plasma systems draws from Japanese and German sources. Single-source vulnerability in high-temperature refractory ceramics creates procurement risk for new facility construction. Distribution runs through regional hazardous waste logistics networks anchored by rail-served thermal treatment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where performance-guaranteed destruction contracts and ongoing analytical validation services expand faster than capital equipment sales, with recurring revenue layers capturing regulatory compliance risk transfer.
For Market Incumbents: Entrench position through backward integration into mobile plasma system manufacturing and exclusive operator training academies. Plasma-based mineralization entrants threaten rotary kiln incumbents in Department of Defense procurement. Certification investment in EPA Method 1633 validation creates channel control over analytical risk transfer contracts. For New Entrants and Emerging Players: Build out capabilities in deployable supercritical water oxidation units for remote military site access, the most penetrable segment given fixed infrastructure gaps. Municipal sludge-to-energy integration in European utilities offers secondary white-space. Go-to-market through performance-guaranteed contracting that assumes analytical and regulatory liability. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light technology licensors with demonstrated plasma destruction removal efficiency certificates and established military contracting relationships. Long-term viability across the analysis window hinges on regulatory ratcheting of destruction standards beyond incineration capabilities. Watch for EPA adoption of plasma-based mineralization as reference technology in federal procurement guidelines.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Treatment Unit Deployment | Opens Department of Defense base closure contracts unreachable by fixed infrastructure. |
| Plasma System Technology Licensing | Accelerates market entry without capital-intensive incineration facility construction. |
| Performance-Guaranteed Contracting | Transfers analytical and regulatory risk from municipal utilities to service providers. |
| Backward Integration into Electrode Supply | Captures margin from Japanese carbon-fiber electrode manufacturers in plasma system value chain. |
| Sludge-to-Energy Co-Product Development | Offsets thermal mineralization costs for European wastewater treatment plant procurement. |
Research Methodology
Desk research of EPA enforcement databases, ECHA restriction proposal comment filings, and Department of Defense environmental contracting records preceded structured interviews with thermal treatment plant managers, remediation engineering directors, municipal utility procurement officers, and hazardous waste logistics coordinators. Secondary triangulation drew from SEC 10-K environmental service disclosures, state-level maximum contaminant level regulatory filings, and OECD PFAS testing guideline documentation. Bottom-up project pipeline analysis and top-down regulatory mandate scaling were cross-validated.
Assumptions held fixed include EPA CERCLA enforcement intensity and ECHA REACH restriction implementation timelines, while natural gas price trajectories and state-level MCL adoption schedules were varied across sensitivity scenarios. Segmentation modeling addressed waste matrix type, treatment technology modality, end-user procurement sophistication, and regulatory framework stringency. CAGRs were derived from contractor backlog analysis and announced capacity expansion timelines, with defense procurement cycle timing and municipal bond issuance velocity as key inputs.
Stress conditions across natural gas price volatility bands, EPA destruction removal efficiency threshold acceleration, and plasma technology commercialization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic contraction affecting municipal capital budgets, regulatory rollback of CERCLA hazardous substance designation, or breakthrough non-thermal destruction technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Recycled Waste Management Market