
 Recycled Waste Management Market | 2026-2036
Recycled Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Waste Management Market Analytics
Packaging manufacturers is pivoting toward post-consumer resin streams as brand sustainability commitments tighten material specifications. Waste Management Inc leverages its landfill-gas-to-energy infrastructure to anchor long-term power purchase agreements with regional utilities. Republic Services Inc competes through automated sorting investments that reduce contamination rates in single-stream recovery. Veolia Environnement SA dominates European industrial waste contracts through integrated collection-to-reprocessing networks.
Recycled waste management encompasses the collection, processing, and reintroduction of discarded materials into manufacturing supply chains, typically requiring contamination thresholds below five percent for mechanical recycling and thermal treatment temperatures exceeding 850 degrees Celsius for energy recovery applications. Plastic and metal segments lead capital deployment due to higher commodity price volatility and established buyer networks, while paper recycling sustains mature margin pools amid containerboard demand. The service dimension stratifies around collection density economics in urban corridors versus sorting automation scale in regional hubs.
EPA landfill methane regulations, EU Green Deal circular economy targets, and China's MEE solid waste import restrictions collectively reshape feedstock availability and processing investment locations. Extended producer responsibility frameworks in multiple jurisdictions transfer collection costs upstream to manufacturers, altering enterprise service procurement patterns. Stakeholders must monitor regulatory fragmentation between national recycling targets and local infrastructure capacity constraints.
Market Dynamics
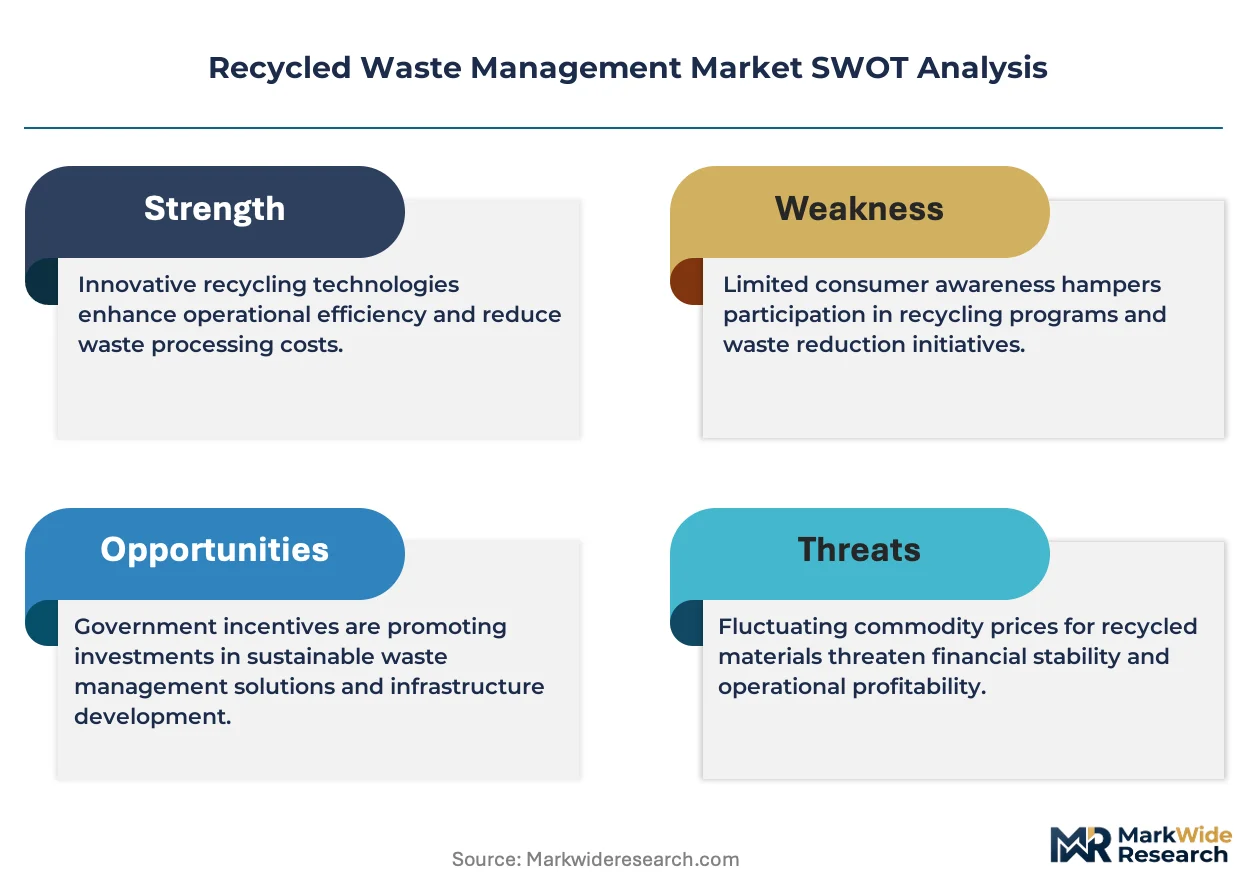
Extended producer responsibility frameworks are transferring collection costs upstream to manufacturers, fundamentally altering procurement patterns and service provider relationships across municipal and industrial waste streams.
Growth Catalysts
- EU Green Deal circular economy mandates:Municipalities across Germany and France are expanding source-separated organics programs with binding recycling targets, creating guaranteed feedstock volumes for processors.
- Post-consumer resin specifications:Packaging manufacturers are tightening material requirements under brand sustainability commitments, pulling investment into mechanical recycling infrastructure.
- China's industrial recycling corridors:Manufacturing scrap conversion into construction and packaging feedstock concentrates demand in coastal processing zones.
Market Restraints
- Contamination thresholds:Mechanical recycling requires feedstock below five percent contamination, limiting viable supply from single-stream collection systems.
- Thermal treatment capex:Energy recovery applications demand temperatures exceeding 850 degrees Celsius, constraining facility deployment to capital-rich operators.
- Import restriction fragmentation:China's MEE solid waste policies and divergent national recycling targets create regulatory friction in cross-border feedstock trade.
Strategic Opportunities
- Automated sorting convergence:Near-infrared and robotics integration is opening new processing capacity for mixed-plastic streams previously rejected to landfill.
- Landfill-gas-to-energy anchor contracts:Regional utilities are signing long-term power purchase agreements with waste operators possessing methane capture infrastructure.
- Indian urban corridor density:Collection economics in megacity clusters present untapped scale advantages for integrated collection-to-reprocessing networks.
Industry Challenges
- Sorting technician shortages:Automated facility operation requires specialized maintenance skills that outpace vocational training pipeline output.
- Legacy MRF retrofit complexity:Existing single-stream facilities face costly reconfiguration to meet rising contamination standards without operational shutdown.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Waste Management Market |
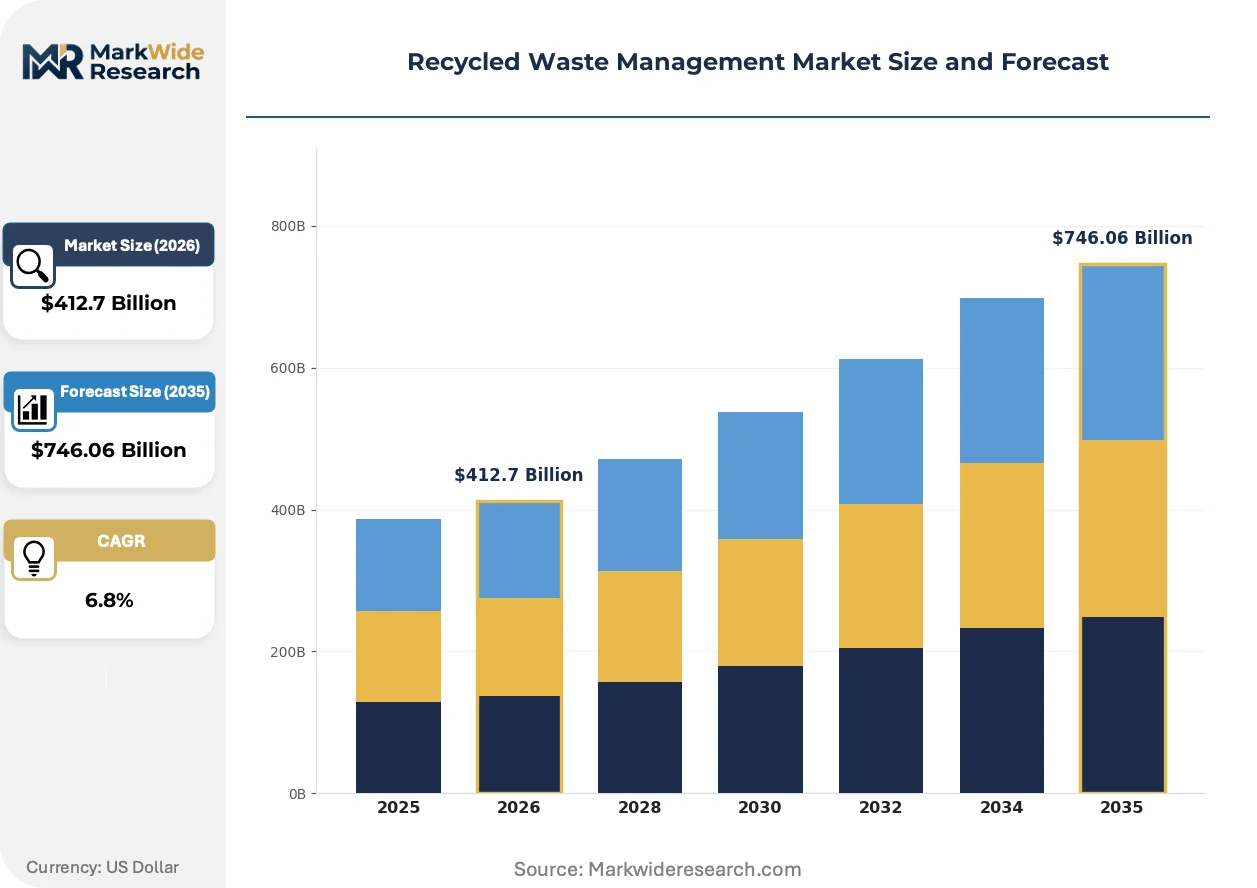
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Paper, Glass Service Type: Collection, Sorting, Recycling, Disposal Application: Commercial, Residential, Industrial, Agricultural End User: Municipalities, Enterprises, NGOs, Households |
| Companies Covered | Waste Management Inc, Republic Services Inc, Veolia Environnement SA, SUEZ SA, Waste Connections Inc, Clean Harbors Inc, Remondis SE & Co. KG, Biffa PLC, Covanta Holding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Waste Management Market Evolving Landscape
Digital tracking and advanced separation technologies are compressing processing costs while regulatory pressure on Scope 3 emissions intensifies supply chain visibility requirements.
Near-infrared spectroscopy paired with robotic pickers is expanding into mixed-waste sorting facilities previously limited to manual labor or magnetic separation. Mid-sized municipal operators in the US and Germany are adopting these systems at replacement-cycle pace. The technology is expanding into lower-volume regional hubs, compressing the minimum efficient scale for profitable sorting operations.
REACH chemical safety registrations and the EU Green Deal's carbon border adjustment mechanisms are tightening traceability requirements for recycled content claims. Industrial waste contracts now mandate chain-of-custody documentation from collection through reprocessing. Packaging and automotive sectors in the EU are responding by consolidating supplier relationships around vertically integrated processors with certified audit trails.
Brand sustainability commitments are displacing spot-market resin purchasing with multi-year offtake agreements tied to verified recycled content percentages. Food and beverage packaging buyers are locking supply directly with reprocessors, bypassing traditional commodity traders. This pattern concentrates contract negotiation in Germany and California, where disclosure regulations enforce measurement rigor.
Recycled Waste Management Market Segmentation
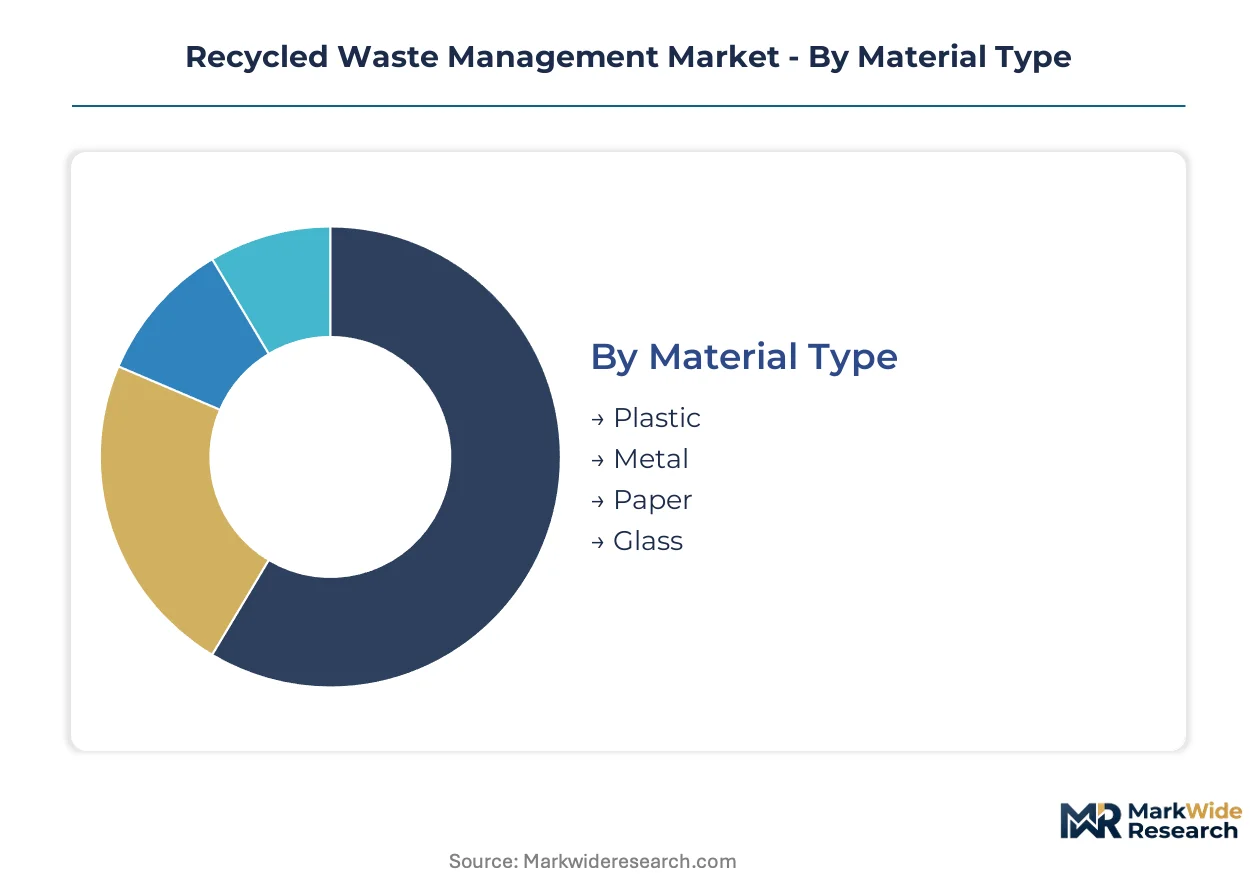
Recycled waste management operators configure service portfolios around feedstock contamination profiles and collection density economics. Material specifications and end-user procurement patterns determine capital deployment priorities across processing infrastructure.
Material Type:
Buyers in this category differentiate by commodity price volatility tolerance and established reprocessing network access.
- Plastic:Mechanical recycling demands sub-five-percent contamination thresholds for resin viability. China's coastal processing corridors convert post-industrial scrap into construction and packaging feedstock under MEE solid waste regulations. Brand sustainability commitments are pulling investment into post-consumer resin infrastructure.
- Metal:Ferrous and non-ferrous streams sustain mature buyer networks with price transparency through commodity exchanges. Industrial waste contracts in Germany and France specify chain-of-custody documentation under EU Green Deal circular economy mandates. Scrap volatility attracts capital-rich operators with hedging capabilities.
- Paper:Containerboard demand sustains margin pools amid established collection systems.
- Glass:Color-sorted cullet supplies bottling and fiberglass manufacturing with lower processing complexity.
Metal leads volumes today; plastic is gaining share fastest.
Service Type:
Procurement patterns in this category split between urban density economics and automation scale requirements.
- Collection:Municipal contracts in German cities and Indian megacity clusters prioritize route density for cost efficiency. Extended producer responsibility frameworks transfer upstream costs to manufacturers under EU Green Deal mandates. Franchise operators compete on truck fleet utilization and labor scheduling.
- Sorting:Near-infrared and robotics integration is expanding processing capacity for mixed-plastic streams previously rejected to landfill. Mid-sized US and German municipal operators adopt these systems at replacement-cycle pace. Contamination thresholds below five percent constrain viable feedstock supply.
- Recycling:Mechanical and thermal reprocessing requires capital-intensive facility deployment.
- Disposal:Landfill-gas-to-energy infrastructure anchors long-term power purchase agreements with regional utilities.
Collection commands the largest service revenue pool; sorting shows the steepest technology investment trajectory.
Application:
Volume concentration in this category follows manufacturing scrap generation patterns and residential population density.
- Industrial:Manufacturing scrap conversion concentrates in China's industrial recycling corridors for construction and packaging feedstock. Veolia Environnement SA dominates European industrial waste contracts through integrated collection-to-reprocessing networks. EPA landfill methane regulations shape facility investment locations.
- Residential:Single-stream recovery systems in US metropolitan areas face rising contamination standards requiring costly MRF retrofits. Republic Services Inc competes through automated sorting investments that reduce rejection rates. Source-separated organics programs expand under binding recycling targets.
- Commercial:Office and retail waste streams generate predictable volumes with lower contamination.
- Agricultural:Organic waste and packaging materials present seasonal collection challenges.
Industrial applications dominate contract values; residential is expanding most quickly under municipal program expansion.
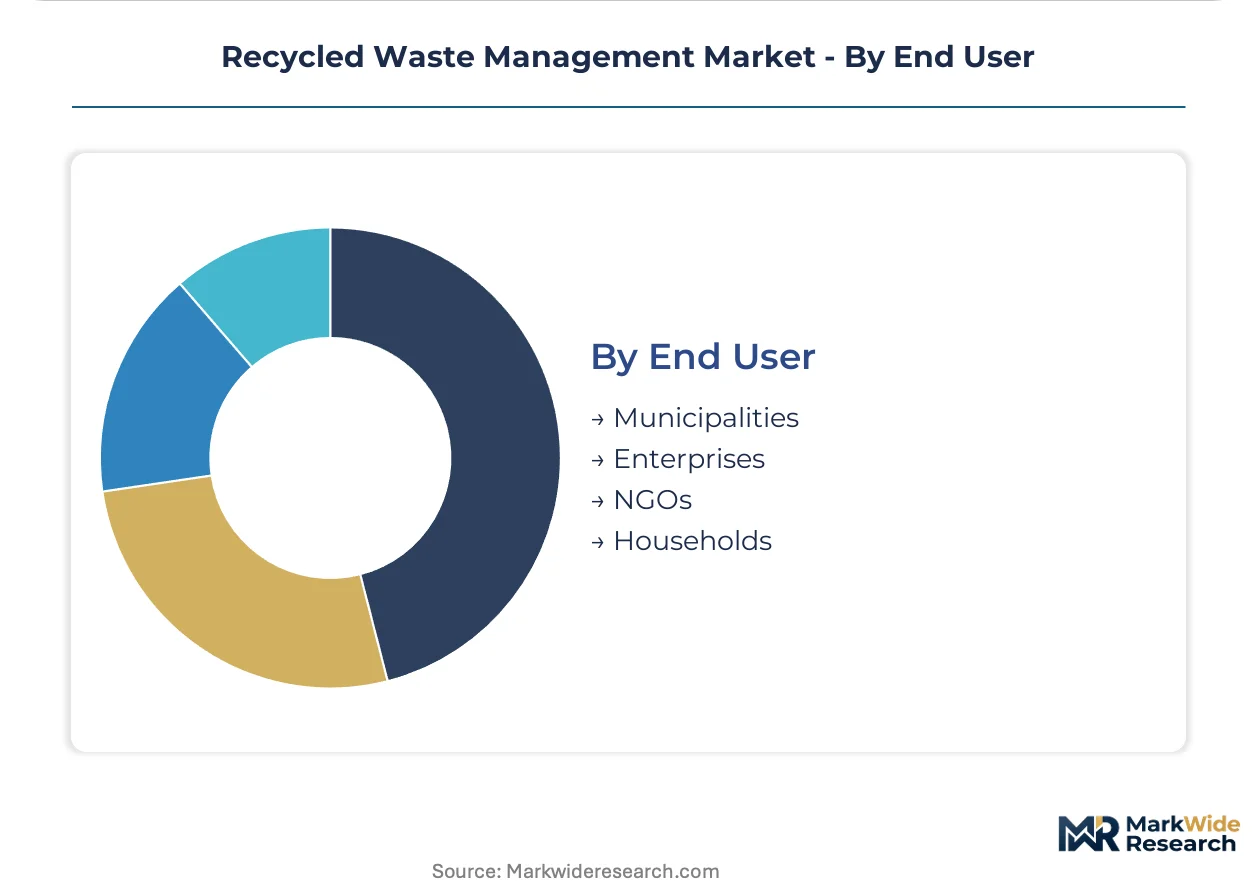
End User:
Budget authority and procurement sophistication separate stakeholders in this category.
- Municipalities:German cities are expanding source-separated organics programs with guaranteed feedstock volumes for processors. Local infrastructure capacity constraints create friction against national recycling targets. Procurement favors integrated operators with collection density and processing scale.
- Enterprises:Packaging manufacturers are tightening post-consumer resin specifications under brand sustainability commitments. Food and beverage buyers lock supply directly with reprocessors, bypassing traditional commodity traders. REACH chemical safety registrations mandate traceability documentation.
- NGOs:Advocacy organizations influence extended producer responsibility policy design.
- Households:Source separation behavior determines upstream feedstock quality for downstream processors.
Enterprises drive premium service pricing; municipalities anchor baseline volume commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial recycling corridors concentrate the highest processing volumes as manufacturing scrap conversion feeds construction and packaging material supply chains. Municipal program expansion in Germany and India drives residential collection infrastructure investment. Regulatory fragmentation between EPA landfill methane rules, EU Green Deal circular economy mandates, and China's MEE solid waste restrictions reshapes cross-border feedstock trade patterns.
United States
Single-stream recovery systems in metropolitan corridors face rising contamination thresholds requiring costly MRF retrofits. EPA landfill methane regulations anchor long-term power purchase agreements between waste operators and regional utilities. Republic Services Inc competes through automated sorting investments in Sun Belt population centers.
Germany
Municipalities expand source-separated organics programs with binding recycling targets under EU Green Deal circular economy mandates. REACH chemical safety registrations mandate chain-of-custody documentation for industrial waste contracts. Veolia Environnement SA dominates integrated collection-to-reprocessing networks in the Rhine-Ruhr industrial cluster.
China
Manufacturing scrap conversion into construction and packaging feedstock concentrates demand in coastal processing zones. MEE solid waste import restrictions redirect domestic collection infrastructure investment. Yangtze River Delta processors convert post-industrial plastic streams into resin for regional packaging manufacturers.
India
Collection economics in Mumbai and Delhi megacity clusters present scale advantages for integrated collection-to-reprocessing networks. Extended producer responsibility frameworks transfer upstream costs to manufacturers under evolving national waste management rules. Informal sector integration challenges persist in high-density urban corridors.
France
Industrial waste contracts specify traceability documentation under EU Green Deal circular economy mandates. Source-separated organics programs expand in Paris and Lyon metropolitan areas with guaranteed feedstock volumes. SUEZ SA maintains integrated service positions in Île-de-France industrial zones.
Recycled Waste Management Market Competitive Landscape
Capacity expansion dominates the current landscape as operators retrofit legacy MRF infrastructure to meet rising contamination standards. The market structures around three tiers: integrated multinational operators with landfill-gas-to-energy assets, regional specialists with dense urban collection networks, and technology-focused automated sorting providers. Strategic archetypes include vertical integrators controlling collection-through-reprocessing chains, automation-first players reducing labor dependence, and utility-facing operators monetizing methane capture infrastructure. M&A activity concentrates on automated sorting technology acquisition and regional collection density consolidation.
Among North American integrated operators, Waste Management Inc and Republic Services Inc exemplify the utility-anchored archetype through landfill-gas-to-energy infrastructure positions. Veolia Environnement SA represents the European vertical integration model with industrial waste contract dominance spanning collection to certified reprocessing. Waste Connections Inc occupies a position in mid-market regional consolidation, while Clean Harbors Inc sits within the specialized industrial and hazardous waste services tier. Remondis SE & Co. KG and Biffa PLC exemplify European collection-density specialists with municipal contract concentration. Covanta Holding Corporation represents the energy recovery-focused archetype with thermal treatment infrastructure positions.
| Leading Market Players |
|---|
| Waste Management Inc |
| Republic Services Inc |
| Veolia Environnement SA |
| SUEZ SA |
| Waste Connections Inc |
| Clean Harbors Inc |
| Remondis SE & Co. KG |
| Biffa PLC |
| Covanta Holding Corporation |
| Others |
Value Network & Pricing Analysis
Recovered paper index movements cascade through containerboard pricing tiers, compressing margins for municipal collectors while rewarding integrated operators with captive reprocessing capacity under EU Green Deal circular economy mandates.
Pricing Analysis
Input-cost pass-through from volatile resin and scrap metal benchmarks shapes contract structures across the value chain. Three-tier pricing separates certified post-consumer resin from standard mechanical grades and unprocessed mixed feedstock, with quality grade and volume scale as primary differentiation levers. Pricing pressure stems from contamination threshold tightening that raises preprocessing costs for single-stream suppliers. Municipal buyers exhibit highest price sensitivity due to fixed tax-base funding, while food and beverage packaging manufacturers absorb premiums for verified recycled content to meet brand sustainability commitments.
Supply Chain Analysis
Dual-sourcing requirements from major packaging buyers mandate multi-supplier qualification across Germany, China, and the United States to mitigate feedstock disruption risks. Raw material dependencies center on post-industrial plastic scrap, ferrous metals from manufacturing offcuts, and source-separated organics from municipal programs. Supply chain risk concentrates in regulatory restriction fragmentation between EPA landfill methane rules, EU Green Deal mandates, and China's MEE solid waste policies. Distribution runs through integrated collection-to-reprocessing networks for industrial contracts, while residential streams rely on regional MRF aggregation before long-haul transfer to coastal processing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Germany's binding recycling targets and India's evolving extended producer responsibility frameworks, where cost differentials in collection labor and landfilling fees exceed processing technology gaps.
For Market Incumbents: Cement dominance in Rhine-Ruhr industrial corridors through backward integration into automated sorting infrastructure, defending against technology-focused entrants capturing mixed-plastic volumes. Prioritize landfill-gas-to-energy capacity additions in US Sun Belt markets where EPA regulations anchor utility offtake pricing. For New Entrants and Emerging Players: Mid-sized Indian municipalities represent the most penetrable buyer archetype, with collection density economics favoring franchise operators over integrated multinationals. Pursue equipment-leasing partnerships with regional processors to bypass capital-intensive facility ownership while securing feedstock supply agreements under national waste management rules. For Investors and Strategic Acquirers: Asymmetric upside sits with automated sorting technology providers serving legacy MRF retrofit demand, given technician shortages constrain competitor expansion. Monitor near-infrared and robotics integration adoption curves as the inflection signal for valuation repricing across processing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Deployment | Near-infrared and robotics integration reduces contamination rates below EPA thresholds in US metropolitan MRFs. |
| Landfill-Gas-to-Energy Expansion | Long-term power purchase agreements with regional utilities monetize methane capture under tightening regulations. |
| Backward Integration into Collection | Captive feedstock supply secures guaranteed volumes for post-consumer resin infrastructure investments. |
| Post-Consumer Resin Certification | REACH-compliant chain-of-custody documentation unlocks premium pricing from EU packaging manufacturers. |
| Joint Venture in Industrial Corridors | Partnerships with Yangtze River Delta processors access China's manufacturing scrap conversion demand. |
Research Methodology
Bottom-up residential and industrial waste generation modeling reconciled against top-down processing capacity tracking forms the analytical core of this study. Primary interviews with municipal procurement officers, MRF operations managers, reprocessor technical directors, and packaging manufacturer sustainability leads combined with secondary validation from EPA enforcement data, EU EEA circular economy progress reports, China MEE solid waste bulletins, and customs trade statistics. Cross-referencing bottom-up feedstock availability estimates with top-down facility throughput records ensures triangulation integrity.
Historical trendline analysis of collection cost structures, contamination rate trajectories, and commodity price volatility established baseline growth patterns across the projection horizon. Segmentation modeling incorporated material type, service tier, application source, and end-user procurement sophistication as dimensions. CAGRs derived from capacity expansion pipelines, regulatory mandate timelines, and technology adoption S-curves were stress-tested against scrap resin and containerboard price cycle amplitudes.
Underlying measurement precision varies by segment; post-consumer plastic and metal recycling carry tighter precision than emerging organics recovery due to established reporting frameworks. Forecasts reflect assumptions on extended producer responsibility implementation pace, automated sorting technology cost curves, and cross-border feedstock trade policy stability. Deviation in EU Green Deal enforcement intensity or China's MEE solid waste restriction scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market