
 North America Waste Recycling Services Market | 2026-2036
North America Waste Recycling Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Waste Recycling Services Market Insights
AI-powered optical sorting is reconfiguring material recovery facility throughput across North America. Waste Management Inc. leverages its national landfill network to anchor integrated collection-to-energy operations. Republic Services Inc. differentiates through municipally contracted single-stream recycling programs spanning Sun Belt population corridors. Waste Connections Inc. specializes in secondary market acquisition routes that consolidate rural and ex-urban collection density.
Waste recycling services encompass the systematic collection, sorting, processing, and reclamation of discarded materials into reusable feedstocks, with modern facilities achieving contamination rates below ten percent through near-infrared polymer identification and eddy-current metal separation. These services divert municipal solid waste, construction debris, and industrial byproducts from landfills while supplying manufacturers with certified secondary raw materials. Collection and processing services dominate revenue generation due to long-term municipal contracts with inflation-indexed pricing, while thermal technology applications are expanding fastest as cement kilns and power generators seek refuse-derived fuel with documented calorific values. Plastic material recovery commands premium margins where food-grade pellet certification meets FDA compliance for packaging reuse.
The EPA enforces landfill methane capture standards and emerging PFAS disposal restrictions that elevate thermal processing demand above conventional landfilling. Ontario's Resource Recovery and Circular Economy Act mandates producer-funded recycling targets that reshape collection infrastructure across the province. State-level container deposit expansions in Michigan and California tighten post-consumer material supply chains. Stakeholders must monitor regulatory divergence between Canadian extended producer responsibility frameworks and U.S. state-by-state landfill diversion mandates to anticipate capital allocation for processing capacity.
Market Dynamics
AI-powered optical sorting is compressing contamination thresholds below ten percent across material recovery facilities, forcing processors to choose between capital-intensive retrofitting or municipal contract loss.
Growth Catalysts
- Extended Producer Responsibility Mandates:Ontario's Resource Recovery and Circular Economy Act funds collection infrastructure through producer fees, expanding curbside access across the province.
- Industrial Sludge Diversion:EPA's emerging PFAS landfill restrictions redirect hazardous waste toward advanced thermal processing, elevating demand for cement kiln co-processing capacity.
- Container Deposit Expansion:Michigan's deposit law expansion tightens post-consumer polyethylene terephthalate supply chains, securing food-grade pellet feedstock for packaging manufacturers.
Market Restraints
- Secondary Material Price Volatility:Baled cardboard and mixed paper values swing with Chinese import policy shifts, squeezing processor margins on long-term municipal contracts.
- Thermal Processing Concentration:Cement kiln capacity for refuse-derived fuel concentrates in the U.S. Great Lakes corridor, creating geographic bottlenecks for coastal industrial waste generators.
- Optical Sorting Capital Intensity:Near-infrared polymer identification systems require seven-figure installation costs that rural facilities cannot amortize across low tonnage volumes.
Strategic Opportunities
- Rural Collection Density Consolidation:Secondary market acquisition routes in ex-urban Texas and Arizona corridors remain fragmented, offering rollup potential for integrated operators.
- Food-Grade Pellet Certification:FDA compliance for post-consumer resin in food-contact packaging commands premium margins where supply scarcity meets brand sustainability commitments.
- Single-Stream Contract Expansion:Sun Belt municipal procurement of commingled collection services is accelerating as population migration strains legacy dual-stream infrastructure.
Industry Challenges
- Contamination Rate Management:Consumer misclassification of flexible films and food-soiled paper degrades optical sorting efficiency, requiring continuous public education investment.
- Interstate Regulatory Friction:Divergent state-level landfill diversion mandates complicate fleet routing and transfer station siting for multi-state collection networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Waste Recycling Services Market |
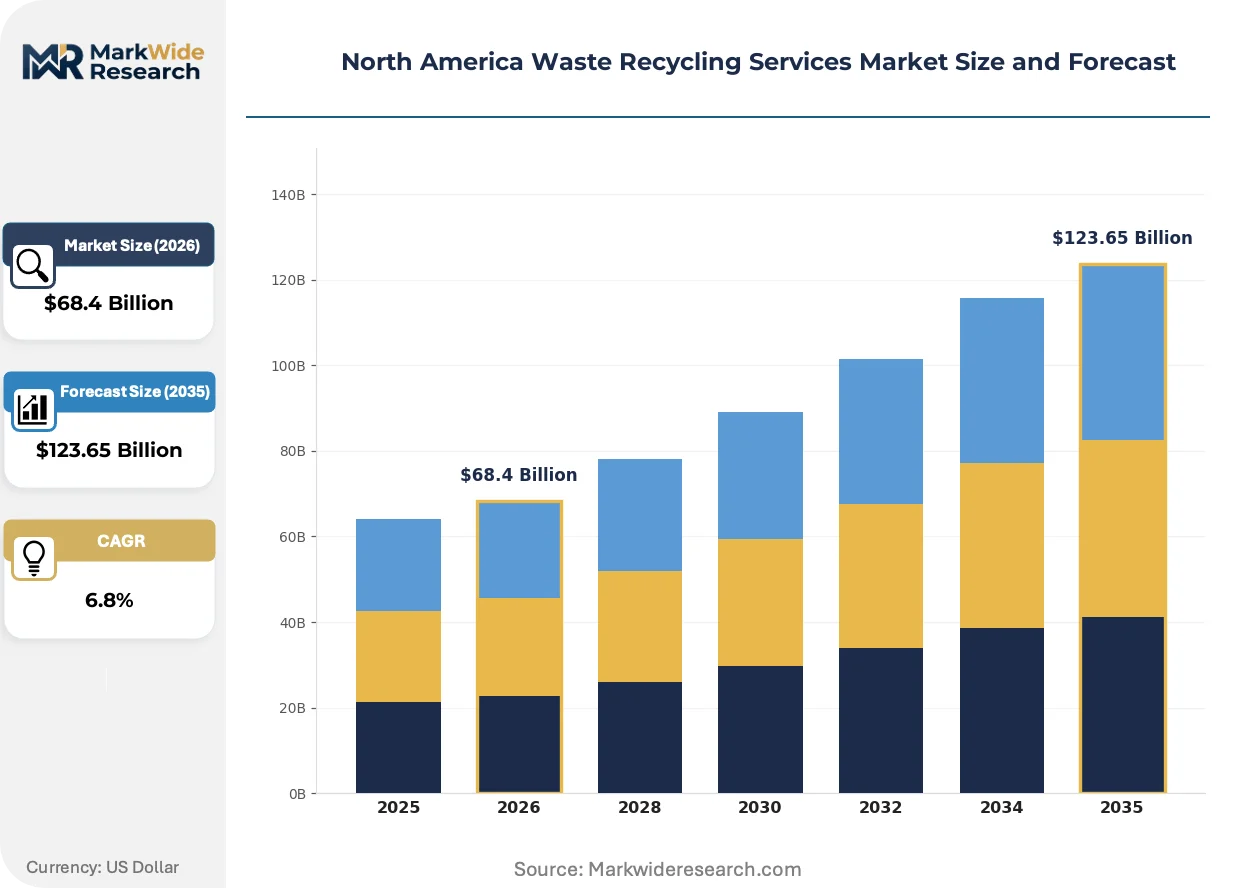
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Sorting, Processing, Disposal Material Type: Plastic, Metal, Paper, Glass End User: Residential, Commercial, Industrial, Municipal Technology: Mechanical, Biological, Thermal, Chemical |
| Companies Covered | Waste Management Inc., Republic Services Inc., Waste Connections Inc., Veolia Environment, Covanta Holding Corporation, Clean Harbors Inc., Rumpke Waste & Recycling, Heritage Environmental Services, Waste Pro USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Waste Recycling Services Market Trends and Innovations
Digital sensing and automated decision systems are reconfiguring how waste streams are characterized, routed, and valorized across the collection-to-processing chain.
Near-infrared spectroscopy paired with machine vision classification is digitizing polymer identification at conveyor speeds exceeding five meters per second. Material recovery facilities in California and Michigan are retrofitting legacy mechanical screens with these sensor arrays to capture polypropylene and polystyrene fractions previously lost to residue. The technology is digitizing quality control protocols, enabling real-time bale certification that satisfies brand audit requirements for recycled content claims.
EPA enforcement of landfill methane capture standards is tightening leachate management requirements for existing disposal sites. Industrial generators in Ohio and Pennsylvania face elevated compliance costs that accelerate thermal processing adoption over conventional landfilling. The cement manufacturing sector is responding by expanding refuse-derived fuel acceptance specifications to secure waste-derived feedstock for kiln energy substitution.
Municipal procurement departments are consolidating collection contracts into longer-term single-stream agreements with inflation-indexed pricing mechanisms. Sun Belt cities facing rapid population in-migration are displacing fragmented hauler arrangements with regional integrated operators capable of guaranteed diversion rate commitments. This concentration is most visible in Arizona and Texas metropolitan corridors where municipal sustainability targets outpace legacy infrastructure capacity.
North America Waste Recycling Services Market Segmentation
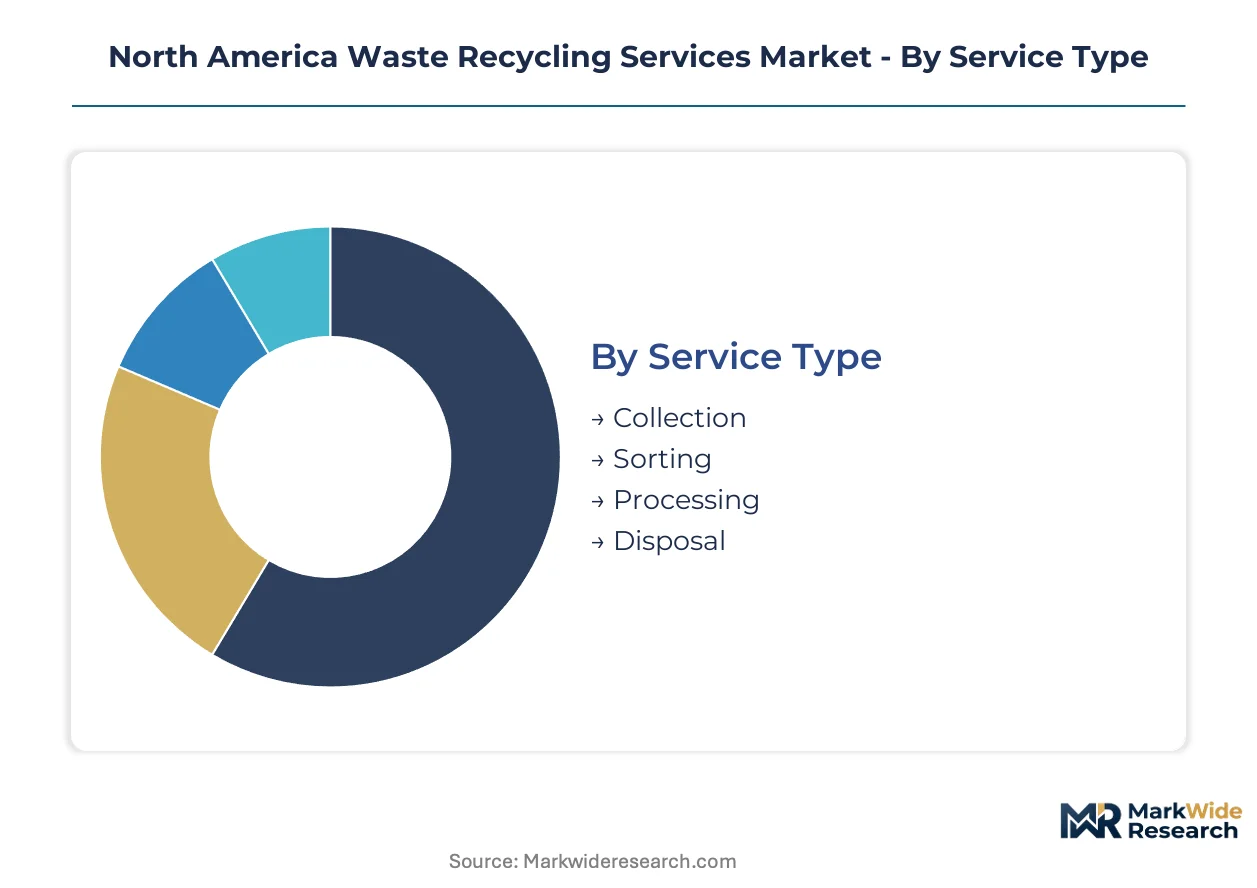
Waste recycling services in North America fragment across four operational dimensions that determine capital deployment and margin structure. Service type and material category dictate infrastructure requirements, while end-user concentration and technology choice shape competitive positioning across the U.S. Great Lakes corridor and Sun Belt expansion zones.
Service Type:
Mature collection networks anchor revenue stability; emerging thermal processing commands premium expansion capital.
- Collection:Curbside and containerized pickup services operate through long-term municipal contracts with inflation-indexed pricing mechanisms. Demand concentrates in Sun Belt metropolitan corridors where Arizona and Texas cities displace fragmented hauler arrangements with regional integrated operators capable of guaranteed diversion rate commitments.
- Processing:Material recovery facilities convert collected streams into baled commodities through mechanical separation and quality control protocols. Ontario's extended producer responsibility mandates reshape collection infrastructure across the province, elevating processor throughput requirements.
- Sorting:Near-infrared polymer identification and eddy-current metal separation achieve contamination rates below ten percent. AI-powered optical sorting compresses thresholds further, forcing capital-intensive retrofitting decisions.
- Disposal:Landfill operations face EPA methane capture enforcement and emerging PFAS restrictions that redirect industrial sludge toward alternative pathways.
Collection handles the majority of throughput; thermal processing within the disposal segment is expanding most quickly on share.
Material Type:
Cost tier stratification separates premium-certified feedstocks from commodity-grade bulk flows.
- Plastic:Post-consumer resin recovery demands food-grade pellet certification meeting FDA compliance for packaging reuse. Michigan's container deposit expansion tightens polyethylene terephthalate supply chains, securing premium feedstock for brand sustainability commitments.
- Metal:Ferrous and non-ferrous recovery leverages eddy-current separation with documented purity specifications for foundry acceptance. Industrial generators in Ohio and Pennsylvania supply consistent volume through manufacturing byproduct arrangements.
- Paper:Baled cardboard and mixed paper values swing with Chinese import policy shifts, squeezing processor margins on long-term municipal contracts.
- Glass:Color-sorted cullet serves container manufacturing with strict contamination limits on ceramics and heat-resistant materials.
Plastic commands premium margin tiers; metal offers volume stability across cyclical demand.
End User:
Customer type determines service configuration from residential curbside to industrial manifest tracking.
- Residential:Single-stream recycling programs span Sun Belt population corridors where municipal procurement accelerates zero-waste service adoption.
- Commercial:Office and retail generators require flexible collection frequencies and waste audit documentation for sustainability reporting.
- Industrial:Hazardous and non-hazardous byproduct streams face EPA landfill restrictions that elevate thermal processing demand above conventional disposal.
- Municipal:City and county procurement departments consolidate contracts into longer-term agreements with guaranteed diversion commitments.
Residential contracts provide revenue base stability; industrial services are climbing the fastest on margin contribution.
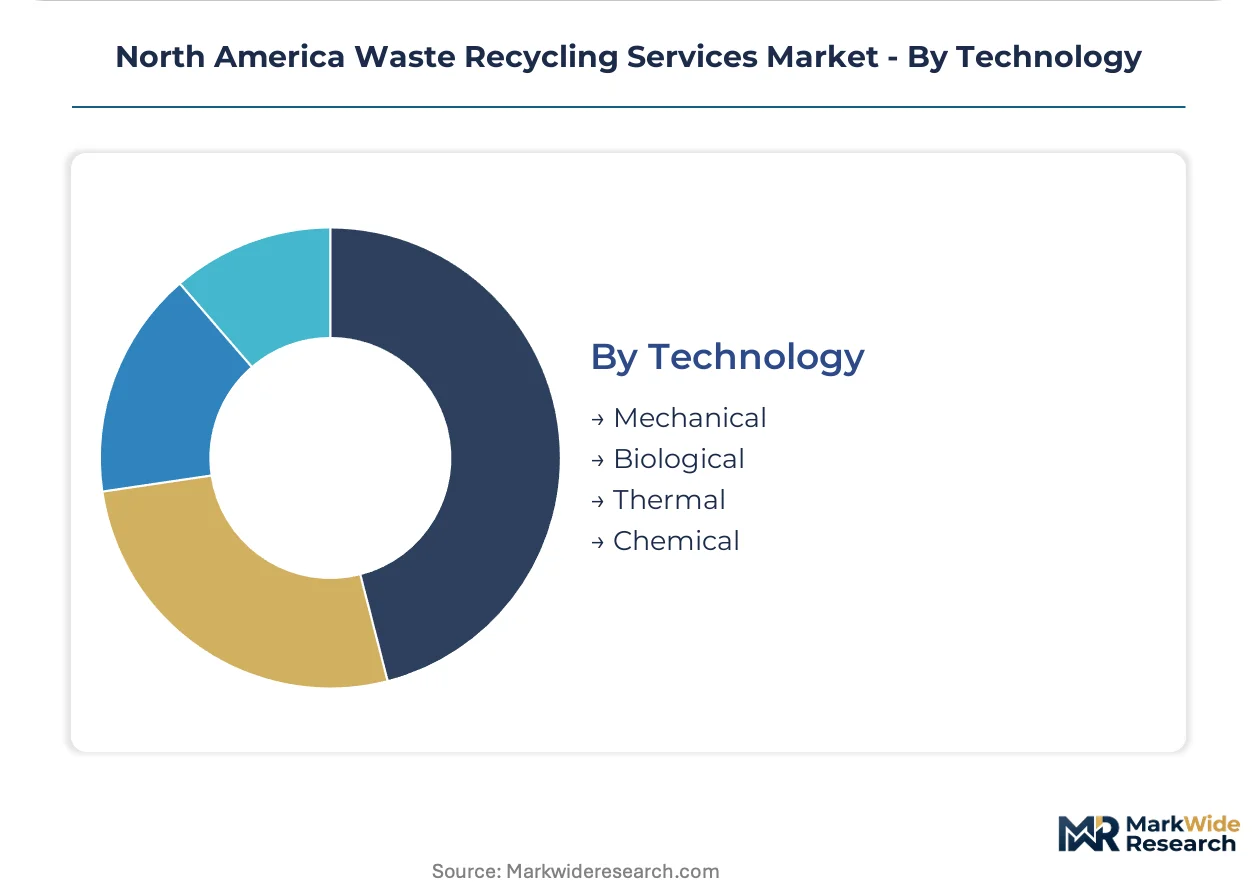
Technology:
Application intensity varies from high-volume mechanical throughput to specialized thermal destruction.
- Mechanical:Screening, shredding, and density separation handle the bulk of municipal solid waste volume with established equipment depreciation schedules.
- Biological:Composting and anaerobic digestion process organic fractions where moisture content and contaminant levels permit soil amendment or biogas recovery.
- Thermal:Cement kiln co-processing and refuse-derived fuel generation concentrate in the U.S. Great Lakes corridor, creating geographic bottlenecks for coastal industrial waste generators seeking documented calorific value destruction.
- Chemical:Solvent recovery and polymer depolymerization remain niche applications with scale limitations.
Mechanical systems handle throughput volume; thermal applications show steepest expansion trajectory as landfill restrictions tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes industrial corridor channels Canadian processed materials into U.S. cement kiln networks, while Sun Belt population migration reshapes collection infrastructure demand across the southern United States.
United States
Great Lakes industrial generators supply refuse-derived fuel to cement manufacturers seeking documented calorific value substitution. The EPA enforces landfill methane capture standards and emerging PFAS disposal restrictions that redirect hazardous sludge toward thermal processing. Michigan's container deposit expansion tightens post-consumer polyethylene terephthalate supply chains, securing premium feedstock for packaging manufacturers.
Canada
Ontario's extended producer responsibility mandates fund curbside collection expansion across the province. The Resource Recovery and Circular Economy Act reshapes processor throughput requirements with producer-funded recycling targets. Toronto and Hamilton anchor the province's material recovery facility network, where near-infrared retrofitting accelerates to meet contamination thresholds below ten percent.
Mexico
Manufacturing byproduct streams from maquiladora operations concentrate near the U.S. border for cross-border thermal processing. The country's environmental regulator tightens industrial waste manifest tracking for hazardous generator categories. Nuevo León and Baja California develop collection density through informal sector integration programs targeting polyethylene and cardboard recovery.
North America Waste Recycling Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across municipal contract corridors and industrial waste streams. The North American market consolidates around three integrated operators commanding national landfill networks and collection density. Strategic archetypes separate vertically integrated waste-to-energy platforms, municipally contracted single-stream processors, and rural consolidation specialists. Dominant competitive moves include secondary market acquisition routes in ex-urban corridors and inflation-indexed contract renewals with guaranteed diversion commitments.
Within the integrated platform tier, Waste Management Inc., Republic Services Inc., and Waste Connections Inc. anchor competitive positioning through distinct geographic and service configurations. Waste Management leverages its national landfill network to anchor collection-to-energy operations across metropolitan corridors. Republic Services exemplifies the municipally contracted single-stream archetype with Sun Belt population corridor concentration. Waste Connections occupies the rural consolidation position through secondary market acquisition routes targeting ex-urban collection density in Texas and Arizona.
| Leading Market Players |
|---|
| Waste Management Inc. |
| Republic Services Inc. |
| Waste Connections Inc. |
| Veolia Environment |
| Covanta Holding Corporation |
| Clean Harbors Inc. |
| Rumpke Waste & Recycling |
| Heritage Environmental Services |
| Waste Pro USA |
| Others |
Pricing and Supply Chain Analysis
Commodity price volatility in post-consumer paper and plastic bales determines both margin compression severity and processor decisions between long-term municipal contract retention versus spot-market thermal processing diversion. This risk vector compresses pricing tier spreads between food-grade certified pellet premiums and commodity-grade bulk flows while reshaping geographic sourcing patterns across the Great Lakes corridor.
Pricing Analysis
Prior-generation mechanical sorting infrastructure trades at depressed asset valuations against next-generation AI-powered optical systems commanding installation premiums. Three-tier pricing structure across food-grade pellet, industrial-grade regrind, and residue-derived fuel levels separates certified FDA-compliant resin from bulk polyethylene terephthalate flows. Pricing pressure stems from Chinese import policy discontinuities that disconnect baled cardboard values from long-term contract inflation escalators. Municipal procurement departments exhibit highest price sensitivity through competitive rebidding clauses, while cement manufacturers purchasing refuse-derived fuel demonstrate lowest sensitivity due to calorific value substitution economics.
Supply Chain Analysis
Integrated collection-to-landfill operators Waste Management, Republic Services, and Waste Connections control transfer station and disposal capacity across the United States and Canada. Geographic supply concentration centers on the U.S. Great Lakes industrial corridor, Ontario's extended producer responsibility zones, and Sun Belt metropolitan expansion corridors in Texas and Arizona. Raw material dependencies include post-consumer polyethylene terephthalate deposit streams, industrial sludge from Ohio and Pennsylvania manufacturing, and baled cardboard from California commercial generators. Single-source vulnerability concentrates in cement kiln co-processing capacity for thermal destruction. Distribution runs through municipally contracted collection networks into material recovery facilities, then onward to secondary commodities markets or captive thermal processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through Sun Belt municipal procurement departments aggregating fragmented hauler contracts into regional single-stream agreements with guaranteed diversion commitments.
For Market Incumbents: Build landfill network moats by securing permitted disposal capacity in constrained geographies against EPA methane enforcement tightening site availability. Defensive moves require optical sorting retrofitting at Great Lakes material recovery facilities to retain Ontario municipal contracts, plus thermal processing capacity expansion to capture industrial sludge diverted by emerging PFAS restrictions. Vertical integration into refuse-derived fuel specifications for cement kiln networks anchors pricing power against commodity bale volatility. For New Entrants and Emerging Players: Pursue rural collection density consolidation in ex-urban Texas and Arizona corridors where legacy dual-stream infrastructure strains under population migration. White-space targets include food-grade pellet certification capacity for brand sustainability commitments and single-stream contract expansion in Sun Belt municipalities outpacing incumbent service coverage. Go-to-market positioning should emphasize guaranteed diversion rate commitments with inflation-indexed pricing mechanisms unavailable from fragmented local operators. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors thermal processing infrastructure over conventional landfilling. Long-term viability across the projection horizon rests on cement kiln co-processing capacity and extended producer responsibility fund capture. Acquisition targets should display regional collection density in underserved corridors paired with permitted thermal processing assets. The signal to watch is Michigan container deposit expansion triggering polyethylene terephthalate supply chain tightness and pellet premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Optical Sorting Retrofit | Near-infrared polymer identification at Michigan and California facilities achieves contamination thresholds below ten percent for municipal contract retention. |
| Cement Kiln Co-processing Expansion | Great Lakes thermal capacity captures industrial sludge diverted by EPA PFAS landfill restrictions with documented calorific value destruction. |
| Food-Grade Pellet Certification | FDA-compliant post-consumer resin commands premium margins where brand sustainability commitments meet supply scarcity in packaging reuse. |
| Rural Collection Density Rollup | Secondary market acquisitions in Texas and Arizona corridors consolidate ex-urban tonnage volumes for amortized infrastructure investment. |
| Single-Stream Contract Consolidation | Sun Belt municipal procurement aggregates fragmented hauler arrangements into regional integrated operator agreements with guaranteed diversion commitments. |
Research Methodology
A spread of perspectives from municipal procurement officers, material recovery facility operators, cement kiln fuel buyers, and extended producer responsibility administrators converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from EPA enforcement records, Ontario Resource Recovery and Circular Economy Act filings, SEC 10-K disclosures from integrated operators, and commodity bale pricing indices. Bottom-up tonnage estimates from individual facility throughput triangulated against top-down market sizing from regulatory mandate volumes.
Demand-supply balance modeling across the analysis window incorporated service type segmentation, material category flows, technology adoption curves, and end-user concentration patterns. Segmentation dimensions modeled include collection versus processing versus thermal disposal, plastic-metal-paper-glass material splits, mechanical versus biological versus thermal technology applications, and residential-commercial-industrial-municipal customer archetypes. CAGRs derived from facility capacity expansion announcements, permit filings, and contract renewal trajectories. Industry-specific forecast inputs included cement kiln refuse-derived fuel acceptance specifications and container deposit redemption rate projections.
Sensitivities concentrate around Chinese import policy shifts, EPA PFAS enforcement timing, and extended producer responsibility fund allocation decisions. Forecasts reflect assumptions about optical sorting adoption rates, thermal processing permit approval velocity, and municipal contract rebidding cycles. Quarterly review of baled commodity price indices, cement kiln capacity utilization rates, and municipal procurement RFP issuance patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Waste Paper Management Market