
 Marine Waste Handling Equipment Market | 2026-2036
Marine Waste Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Waste Handling Equipment Market Foresight
Cruise operators is collapsing as the dominant buyer archetype for marine waste handling equipment, displacing traditional cargo fleet procurement cycles. Wärtsilä Corporation leverages its integrated propulsion and environmental systems portfolio to cross-sell waste treatment packages. Evac Group anchors its position through vacuum collection technology leadership across luxury vessel segments. Alfa Laval competes on thermal processing efficiency for sludge and oily waste streams.
Marine waste handling equipment encompasses mechanical, thermal, and biological systems engineered to process, store, and discharge or retain ship-generated garbage, wastewater, and oily residues in compliance with maritime environmental protocols. Vacuum collection systems typically operate at 35-50 kPa differential pressure to transport waste through narrow-bore piping networks, reducing tank volumes and structural weight penalties aboard space-constrained vessels. Separator systems command premium pricing due to MARPOL-driven oily bilge water discharge standards of 15 ppm maximum oil content. Dehydration technology segments show accelerated retrofit activity as operators seek to reduce offloading volumes and port disposal fees. Storage tanks remain the most mature product category, with margin pools shifting toward corrosion-resistant alloy fabrication and smart level monitoring integration.
The International Maritime Organization's MARPOL Annex V and Annex I frameworks mandate equipment certification by flag state administrations and recognized organizations, creating compliance-driven replacement cycles across existing fleets. ISO 14726 color-coding standards for shipboard piping and the EU's Ship Recycling Regulation extend design requirements to end-of-life material traceability. Classification societies including DNV and Lloyd's Register enforce equipment type-approval protocols that filter non-compliant suppliers from newbuild supply chains. Stakeholders must monitor emerging ballast water and carbon intensity regulations that could redirect R&D investment toward integrated environmental system architectures.
Market Dynamics
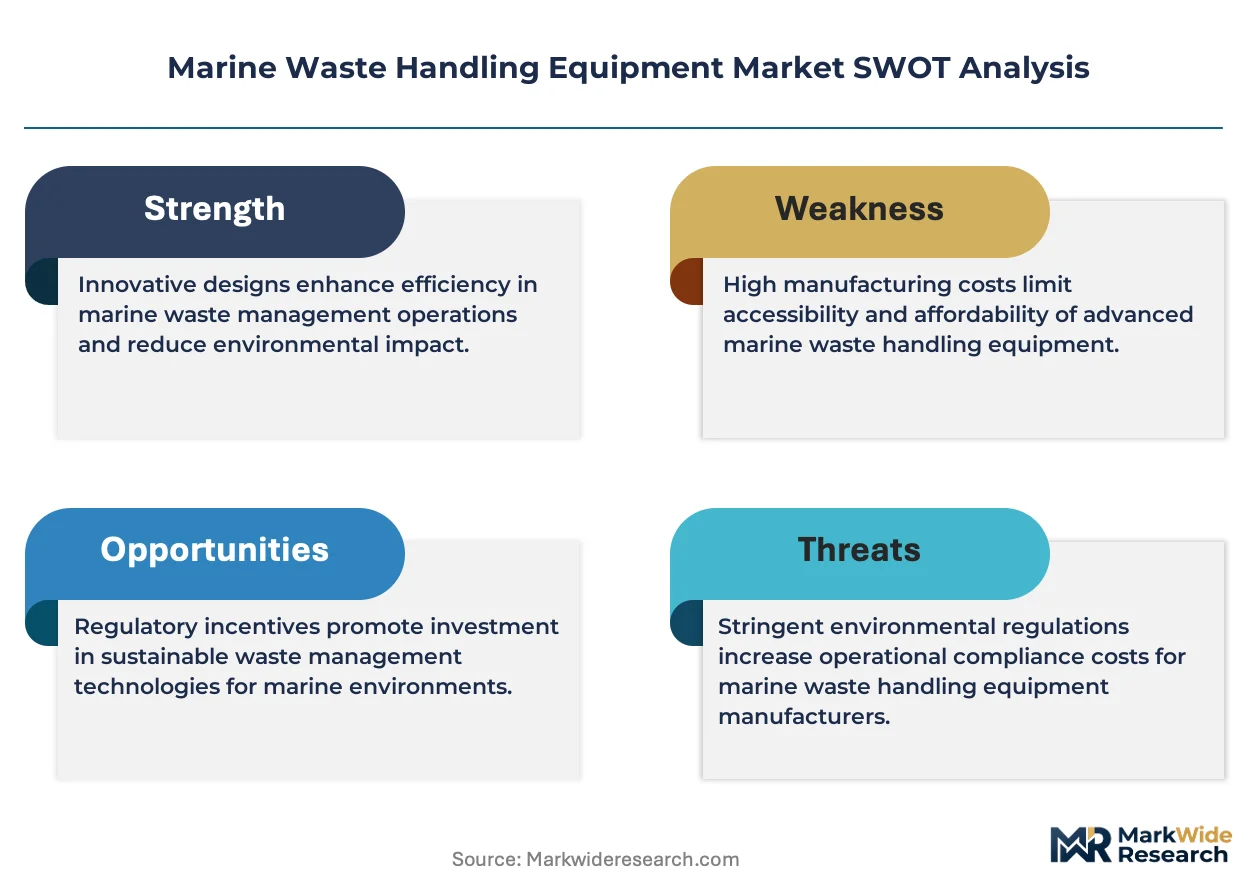
MARPOL Annex V amendments have compressed replacement cycles across international fleets, forcing shipowners to retrofit legacy garbage management systems ahead of mandatory compliance deadlines. This regulatory pressure cascade is restructuring procurement priorities from cost-minimization toward certification assurance.
Growth Catalysts
- IMO MARPOL Annex V:Flag state administrations now mandate garbage management plan certification for all vessels trading internationally, creating equipment replacement mandates across existing fleets.
- Vacuum collection technology:Narrow-bore piping networks operating at 35-50 kPa differential pressure reduce structural weight penalties and tank volumes aboard space-constrained cruise vessels.
- East Asian shipbuilding clusters:South Korean and Chinese yards integrate advanced waste treatment systems into newbuild specifications, embedding equipment demand into construction contracts.
Market Restraints
- Corrosion-resistant alloy fabrication:Premium material requirements for storage tanks compress margin pools and elevate unit costs for system integrators.
- Classification society type-approval protocols:DNV and Lloyd's Register certification filters exclude non-compliant suppliers from newbuild supply chains, concentrating vendor access.
- Port disposal fee structures:Dehydration technology retrofits face payback period uncertainty where regional port pricing varies unpredictably.
Strategic Opportunities
- Smart level monitoring integration:IoT-enabled tank sensors create recurring revenue streams through predictive maintenance contracts with fleet operators.
- EU Ship Recycling Regulation:End-of-life material traceability requirements extend equipment design specifications to capture decommissioning value.
- Thermal-biological system convergence:Integrated sludge processing architectures address both oily waste and organic garbage streams through single-unit installations.
Industry Challenges
- Flag state certification timelines:Recognized organization approval processes create installation scheduling bottlenecks during dry-dock windows.
- Legacy piping retrofit compatibility:ISO 14726 color-coding standard compliance demands system-wide infrastructure replacement rather than component-level upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Waste Handling Equipment Market |
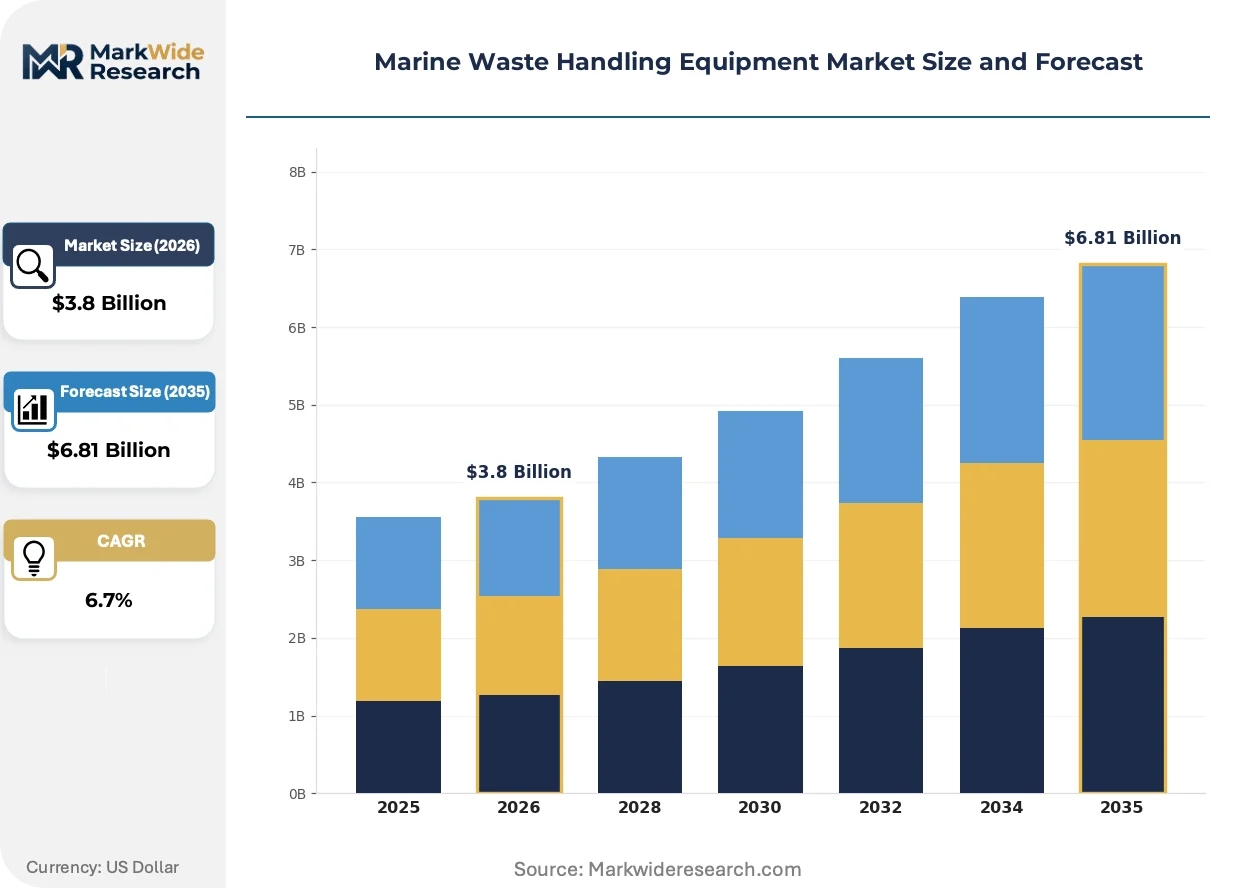
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waste Compactors, Separator Systems, Storage Tanks, Pumps Technology: Mechanical Systems, Dehydration Technology, Vacuum Technology, Aero-Mechanical End User: Cruise Lines, Cargo Ships, Fishing Vessels, Offshore Platforms Regulatory Framework: MARPOL Regulations, ISO Standards, National Guidelines, Local Compliance |
| Companies Covered | Wärtsilä Corporation, Evac Group, Damen Shipyards Group, Alfa Laval, Veolia Water Technologies, JWC Environmental, Westmatic Corporation, Tana Oy, Haarslev Industries A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Waste Handling Equipment Market Shifts & Advancements
Equipment architecture is pivoting from standalone mechanical units toward integrated environmental system platforms that consolidate waste, wastewater, and emissions processing. This convergence is compressing vendor portfolios and elevating systems integration capabilities as the primary competitive differentiator.
Membrane bioreactor technology is displacing conventional biological treatment systems in cruise vessel applications. Carnival Corporation and Royal Caribbean International are specifying MBR packages for newbuilds delivered from 2024 onward. The technology is displacing activated sludge processes by reducing footprint requirements forty percent while achieving MARPOL-compliant discharge standards without secondary clarification.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are accelerating adoption of CO2-based refrigeration in thermal waste processing equipment. Compressor manufacturers must redesign sludge dryer heat pump circuits to utilize natural refrigerants with lower global warming potential. Equipment suppliers serving European-flagged fleets face compressed R&D timelines to maintain CE marking validity across product lines.
Shipowners are consolidating procurement authority at fleet technical management centers, displacing vessel-level purchasing autonomy. Third-party technical managers like V.Group and Bernhard Schulte Shipmanagement now specify standardized waste handling configurations across mixed-owner fleets. This concentration is most visible in Greek and German tanker and bulker operations where outsourced technical management penetration exceeds sixty percent.
Marine Waste Handling Equipment Market Segmentation
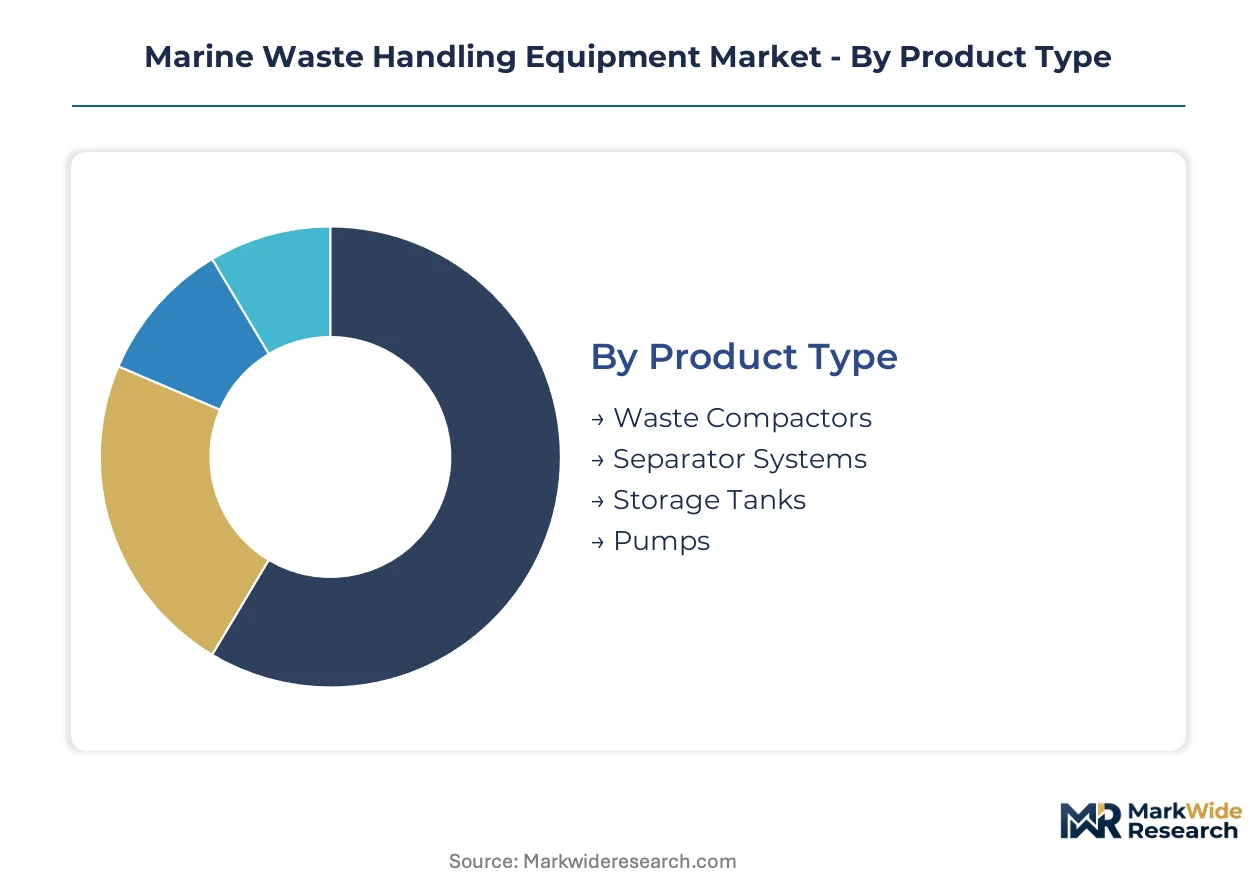
Marine waste handling equipment procurement flows through distinct channel configurations that vary by vessel type and regulatory jurisdiction. Equipment integrators calibrate their distribution strategies around the technical complexity and certification requirements inherent to each segment.
Product Type:
Channel mix for mechanical equipment favors direct OEM relationships with major yards, while storage and pumping systems move through specialized marine distributors.
- Waste Compactors:Hydraulic compression units reduce garbage volume by 80-90% prior to storage or discharge. Cruise operators in Mediterranean and Caribbean itineraries specify these systems most heavily due to extended voyage durations between port calls.
- Separator Systems:Centrifugal and coalescing units achieve MARPOL-mandated 15 ppm oil content in bilge water discharge. Chinese and South Korean newbuild yards embed these into propulsion system packages, creating captive demand channels.
- Storage Tanks:Corrosion-resistant alloy fabrication dominates specifications from classification societies.
- Pumps:Vacuum and centrifugal configurations serve collection and transfer functions across all vessel classes.
By volume, Storage Tanks leads. By growth pace, Separator Systems is ahead.
Technology:
Cost tier stratification separates premium vacuum systems from commodity mechanical alternatives, with dehydration occupying the mid-tier retrofit market.
- Mechanical Systems:Shredders, compactors, and conveyors form the baseline infrastructure aboard cargo fleets. Fishing vessel operators in North Atlantic and Southeast Asian waters favor these systems for their operational simplicity and minimal maintenance requirements.
- Dehydration Technology:Thermal and mechanical drying systems reduce sludge volumes for port disposal. Offshore platform operators in the North Sea and Gulf of Mexico deploy these units to minimize supply vessel trips and helicopter logistics costs.
- Vacuum Technology:35-50 kPa differential pressure systems command premium positioning in cruise newbuilds.
- Aero-Mechanical:Hybrid pneumatic-conveyor configurations serve niche high-capacity applications.
Mechanical Systems holds the largest installed base. Vacuum Technology is expanding most quickly.
End User:
Application intensity varies sharply: cruise vessels demand integrated environmental suites while cargo operators prioritize compliance-minimum configurations.
- Cruise Lines:Fleet-wide mandates for advanced waste processing now exceed regulatory minima. Carnival Corporation and Royal Caribbean International specify membrane bioreactor packages for newbuild deliveries, consolidating procurement at Miami and Monaco technical centers.
- Cargo Ships:Container and bulk carriers retrofit garbage management systems ahead of MARPOL Annex V compliance deadlines. Greek and German technical managers standardize configurations across mixed-owner fleets through outsourced management contracts.
- Fishing Vessels:Smaller fleet operators in Iceland and Norway face compressed payback periods for equipment investments.
- Offshore Platforms:Fixed and floating production units require continuous-duty processing capacity.
Cargo Ships generates the highest unit volume. Cruise Lines shows the steepest expansion trajectory.
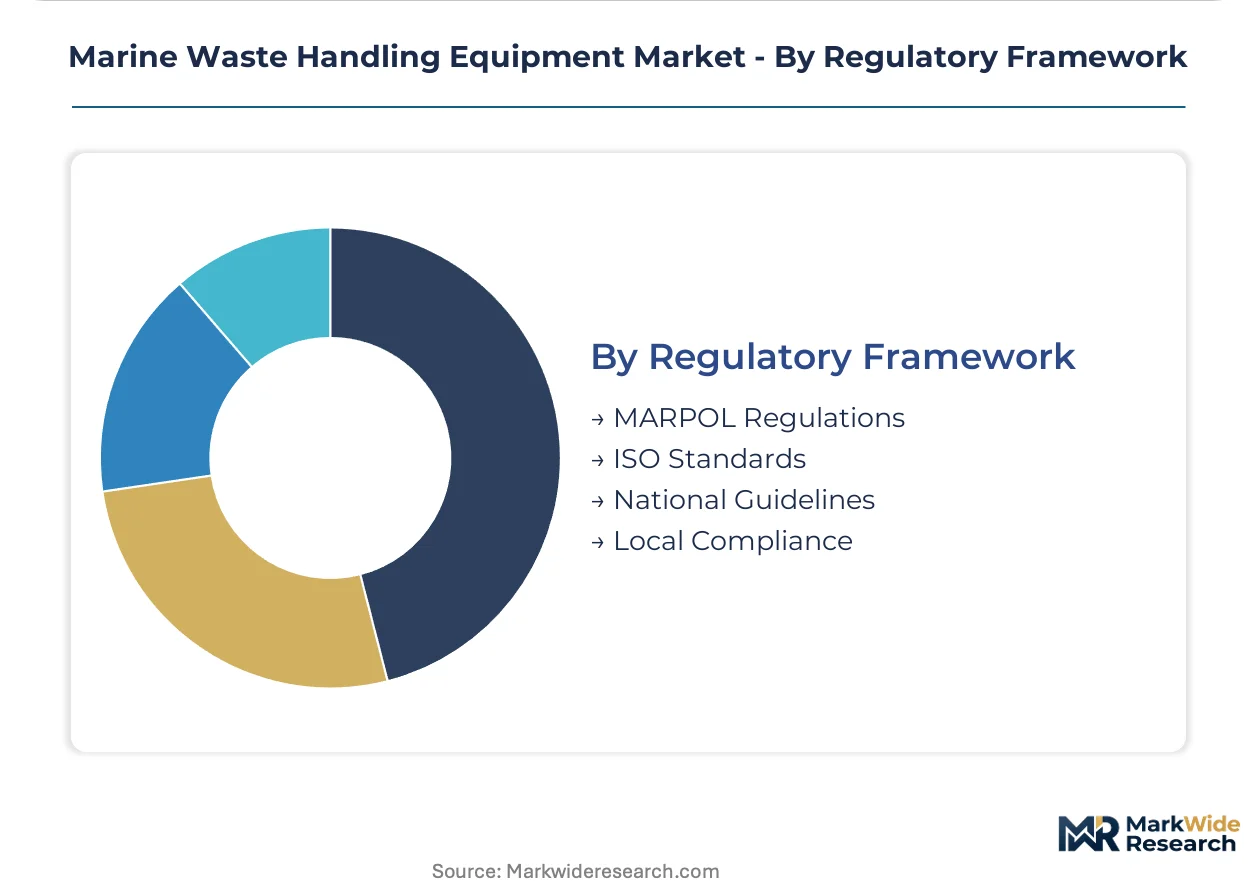
Regulatory Framework:
Certification tier determines supplier access: IMO instruments create universal baselines while national and local layers add market-specific compliance costs.
- MARPOL Regulations:Annex V garbage management and Annex I oily waste standards mandate equipment certification by flag state administrations. DNV and Lloyd's Register type-approval protocols filter non-compliant suppliers from newbuild supply chains.
- ISO Standards:ISO 14726 color-coding for shipboard piping extends to waste handling infrastructure. Compliance demands system-wide replacement rather than component-level upgrades during retrofits.
- National Guidelines:EU F-Gas Regulation restricts refrigerant choices in thermal processing equipment.
- Local Compliance:Port state control variations in California, Singapore, and Rotterdam create regional specification divergences.
MARPOL Regulations anchors universal demand. Local Compliance is gaining share fastest as port state enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding capacity clusters in South Korea and China concentrate equipment demand through newbuild integration contracts. Classification society headquarters in Norway and the United Kingdom shape certification requirements that filter supplier access worldwide. Port state enforcement variations in California, Singapore, and Rotterdam create regional specification divergences that equipment vendors must navigate.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor global newbuild output, embedding waste treatment systems into construction specifications. The Korean Register of Shipping enforces type-approval protocols that filter non-compliant suppliers from yard supply chains. Busan and Ulsan shipbuilding clusters drive captive demand for vacuum collection and separator systems aboard cruise and cargo vessels.
China
State-owned yards in Shanghai and Dalian scale production of container carriers and bulkers with integrated environmental suites. The China Classification Society mandates equipment certification under MARPOL Annex V implementation guidelines. Jiangsu and Zhejiang province shipbuilding corridors concentrate retrofit activity ahead of compliance deadlines for international trading fleets.
United States
Carnival Corporation and Royal Caribbean International consolidate procurement authority at Miami technical centers for Caribbean and Mediterranean cruise operations. The EPA enforces vessel general permit discharge standards that exceed MARPOL minima in Alaskan and Californian waters. Seattle and Fort Lauderdale marine service hubs coordinate fleet-wide equipment standardization across outsourced technical management contracts.
Germany
Greek and German tanker operators through Hamburg and Bremen technical managers standardize garbage management configurations across mixed-owner fleets. Lloyd's Register's Hamburg office coordinates type-approval protocols with flag state administrations. The EU F-Gas Regulation restricts refrigerant choices in thermal processing equipment serving European-flagged vessels.
Norway
DNV headquarters in Oslo sets classification standards that propagate through Nordic offshore and cruise vessel specifications. Norwegian fishing vessel operators in North Atlantic waters favor mechanical systems for operational simplicity. Stavanger and Bergen offshore service clusters demand continuous-duty processing capacity for platform supply and production support vessels.
Marine Waste Handling Equipment Market Competitive Landscape
Concentration sits with diversified marine engineering conglomerates that cross-sell environmental systems through integrated propulsion packages. Three to five Nordic and European specialists anchor premium positioning through classification society type-approval dominance. The vendor base separates between yard-integrated OEM channels and aftermarket retrofit distributors. Strategic moves center on portfolio diversification into adjacent wastewater and emissions processing, plus geographic expansion through technical management center relationships.
Among Finland-based engineering groups, Wärtsilä Corporation exemplifies the diversified conglomerate archetype through cross-selling leverage. Evac Group and Alfa Laval occupy positions within the Nordic specialist tier, with the former representing vacuum technology leadership and the latter anchoring thermal processing efficiency positioning. These three entities illustrate the competitive structure separating integrated platform providers from focused subsystem specialists.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| Evac Group |
| Damen Shipyards Group |
| Alfa Laval |
| Veolia Water Technologies |
| JWC Environmental |
| Westmatic Corporation |
| Tana Oy |
| Haarslev Industries A/S |
| Others |
Supply & Pricing Matrix
Shipyard capacity utilization rates in South Korea and China above eighty percent compress supplier negotiation leverage and elevate price floors for corrosion-resistant alloy components. This scale concentration funnels procurement power toward integrated environmental system providers while fragmenting standalone equipment vendors into price-taking positions.
Pricing Analysis
Volume-discount tiering structures separate cruise line fleet contracts from single-vessel cargo retrofits by thirty to fifty percent unit differentials. Certification grade under MARPOL Annex V and DNV type-approval status anchors premium positioning against uncertified alternatives. Cost compression in standard mechanical systems intensifies as Chinese fabricators expand vacuum collection manufacturing. Cargo fleet technical managers exhibit highest price sensitivity due to compliance-minimum procurement mandates, while cruise operators prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Singapore port congestion elevate landed costs for European and Southeast Asian retrofit projects. Manufacturing concentrates in South Korea, China, and Finland, with Busan and Shanghai clusters feeding newbuild integration pipelines. Stainless steel and duplex alloy feedstocks draw from German and Japanese mill supply agreements. Single-source vulnerability sits with specialized vacuum pump assemblies from Nordic component specialists. Distribution runs through yard-integrated OEM channels for newbuilds and aftermarket marine distributors for retrofit fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characteristics define this market as MARPOL Annex V retrofit mandates penetrate the remaining non-compliant cargo fleet. Membrane bioreactor technology adoption in cruise newbuilds signals penetration acceleration across adjacent vessel classes.
For Market Incumbents: Secure type-approval portfolio breadth across DNV, Lloyd's Register, and Korean Register protocols to filter emerging competitors from yard supply chains. Deepen backward integration into corrosion-resistant alloy fabrication to defend margin position against Chinese cost competition. Lock long-term service contracts with V.Group and Bernhard Schulte Shipmanagement to preempt technical management center consolidation.
For New Entrants and Emerging Players: Anchor in dehydration technology retrofits for North Sea offshore platforms where payback visibility from reduced helicopter logistics costs supports premium pricing. Target Greek and German tanker technical managers with standardized garbage management configurations that undercut incumbent integration premiums. Pursue partnership routes with Jiangsu and Zhejiang province retrofit yards ahead of MARPOL compliance deadlines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane bioreactor specialists with cruise line validation and thermal-biological system convergence capabilities. Five-to-ten year viability rests on classification society certification moats rather than manufacturing scale alone. Watch for EU F-Gas Regulation compliance failures as inflection signal for refrigerant-dependent thermal processing equipment.
| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Certification Expansion | DNV and Lloyd's Register type-approval unlocks yard-integrated OEM channel access. |
| Membrane Bioreactor Technology Integration | Carnival Corporation and Royal Caribbean International specifications validate cruise segment penetration. |
| Smart Sensor Platform Development | IoT-enabled tank monitoring creates recurring predictive maintenance revenue streams. |
| Corrosion-Resistant Alloy Backward Integration | In-house duplex steel fabrication compresses supply exposure and stabilizes margin pools. |
| Technical Management Center Partnerships | V.Group and Bernhard Schulte standardization mandates consolidate procurement authority. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with shipyard procurement directors, fleet technical managers, classification society surveyors, and environmental system engineers; and secondary validation through Lloyd's Register equipment lists, DNV type-approval databases, IMO circulars, and customs trade records for marine environmental equipment. Bottom-up vessel fleet modeling and top-down shipbuilding output triangulation anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation by product type, technology tier, end-user vessel class, and regulatory jurisdiction cluster. CAGRs derived from installed base replacement cycles, newbuild integration rates, and retrofit compliance deadlines. Forecast inputs incorporated MARPOL Annex V implementation timelines and East Asian shipbuilding orderbook trajectories.
Material uncertainties — flag state certification delays, port disposal fee volatility, and refrigerant regulatory shifts — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
GCC Industrial Waste Management Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Animal Waste Incinerator Market