
 Middle East and Africa Polyethylene Wax Market | 2026-2036
Middle East and Africa Polyethylene Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Polyethylene Wax Market Foresight
Specialty coatings formulators are unwinding legacy supply relationships with commodity traders and redirecting volume toward technical-grade suppliers. Sasol Ltd anchors its position through backward integration into Fischer-Tropsch feedstocks at its South African complexes. BASF SE leverages its Ludwigshafen technical service network to support MEA customers with formulation optimization. Clariant AG competes through color masterbatch adjacencies that bundle polyethylene wax into turnkey polymer systems.
Polyethylene wax comprises low- to high-molecular-weight ethylene homopolymers or copolymers produced via high-pressure polymerization or thermal degradation of polyethylene, with melt viscosities typically ranging from 10 to 10,000 mPa·s at elevated temperatures; it functions primarily as a lubricant, dispersant, and surface modifier in thermoplastic processing and surface coatings. High Density Wax commands the dominant share in plastics compounding, where its elevated melting point and narrow molecular weight distribution justify premium positioning over low-density alternatives. Emulsified Wax represents the fastest-expanding product category, as waterborne coatings adoption accelerates among MEA packaging converters seeking to meet tightening volatile organic compound protocols.
Saudi Standards, Metrology and Quality Organization (SASO) and South African Bureau of Standards (SABS) enforce divergent certification requirements that fragment product registration costs across the region, while REACH-equivalent chemical notification frameworks under Gulf Cooperation Council harmonization create compliance complexity for European exporters. The UAE's Ministry of Industry and Advanced Technology is advancing local content mandates that favor domestic wax blending operations over direct importation of finished grades. Stakeholders must monitor regulatory divergence between Gulf and sub-Saharan jurisdictions when configuring regional supply footprints.
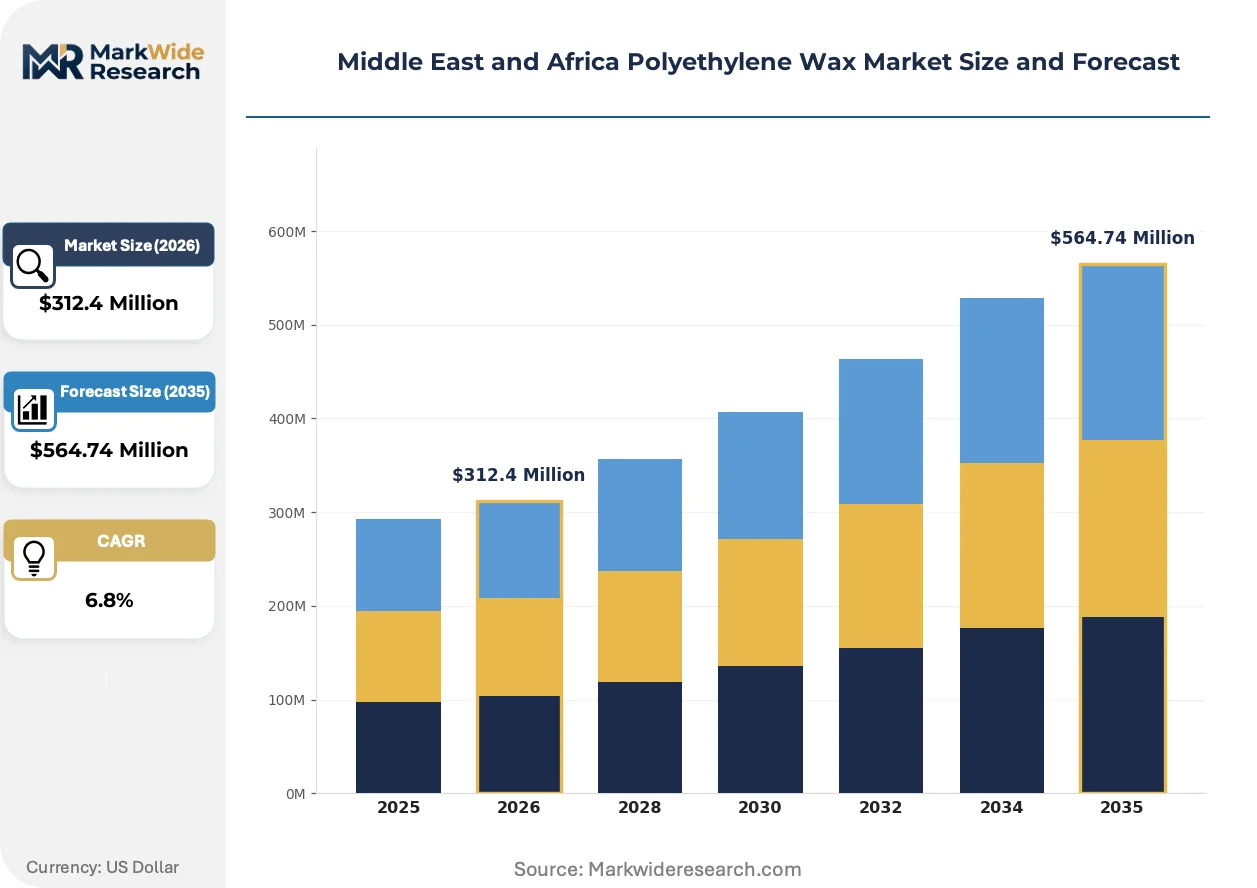
Market Dynamics
Petrochemical integration across Gulf Cooperation Council states is compressing supply chains and forcing independent wax blenders to defend margin positions through technical service differentiation rather than feedstock cost parity.
Growth Catalysts
- REACH-equivalent GCC harmonization:Chemical notification frameworks are accelerating registration of European-sourced high-density grades into Saudi Arabia and the UAE.
- Waterborne coatings adoption:Packaging converters across the Gulf are reformulating solvent-based systems to meet tightening volatile organic compound protocols.
- SABS automotive specifications:South Africa's tightened certification requirements are displacing uncertified imports with locally compounded emulsified wax formulations.
Market Restraints
- Naphtha price volatility:Feedstock cost swings at Saudi and UAE crackers compress blending margins for non-integrated compounders.
- Fischer-Tropsch supply concentration:Sasol's Secunda complex dominates sub-Saharan Fischer-Tropsch wax supply, creating single-source risk for regional formulators.
- Paraffin wax substitution:Lower-cost paraffin alternatives from Iranian and Egyptian refiners displace polyethylene wax in price-sensitive candle and board applications.
Strategic Opportunities
- Egyptian downstream expansion:Underpenetrated plastics compounding capacity in Alexandria and Suez offers first-mover positioning for technical-grade suppliers.
- Color masterbatch bundling:Polyethylene wax integration into turnkey polymer systems creates stickier relationships with Nigerian and Kenyan packaging converters.
- UAE local content mandates:Ministry of Industry and Advanced Technology procurement rules favor domestic wax blending operations over finished-grade importation.
Industry Challenges
- Formulation chemist scarcity:Gulf-based processors struggle to recruit experienced waterborne coatings specialists capable of optimizing emulsified wax performance.
- SASO-SABS divergence:Non-harmonized certification timelines force suppliers to maintain parallel technical dossiers, inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Polyethylene Wax Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Coatings, Adhesives, Plastics, Inks Product Type: Low Density Wax, High Density Wax, Emulsified Wax, Others End User: Packaging, Automotive, Consumer Goods, Textiles Technology: Extrusion, Blown Film, Injection Molding, Others |
| Companies Covered | Baker Hughes, euroceras Sp. z o.o., BASF SE, Sasol Ltd, Lion Chemtech Co., Ltd., Clariant AG, Mitsui Chemicals Inc, The Lubrizol Corporation, Honeywell International Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Polyethylene Wax Market Shifts & Advancements
Formulation science and supply chain configuration are converging to reshape how polyethylene wax grades are specified, sourced, and delivered across Middle East and Africa processing markets.
Metallocene-catalyzed polyethylene wax is displacing conventional Ziegler-Natta grades in high-performance coatings applications. Saudi masterbatch compounders are adopting these narrow molecular weight distribution materials for automotive interior specifications. The shift is compressing demand for legacy low-density waxes in premium segments while opening technical service revenue pools for suppliers with polymerization expertise.
SASO's alignment with Gulf Cooperation Council chemical notification frameworks is fragmenting product registration costs. European exporters now face parallel compliance obligations distinct from REACH dossiers. The coatings segment bears the heaviest burden, as waterborne formulations require substance-level disclosure not mandated for plastics compounding applications.
Specialty coatings formulators are unwinding legacy supply relationships with commodity traders. Technical-grade suppliers with in-house application laboratories are capturing specification authority previously held by distributors. This behavioral shift is most visible in Dubai and Jeddah, where packaging converters now demand formulation optimization support bundled with wax procurement.
Middle East and Africa Polyethylene Wax Market Segmentation
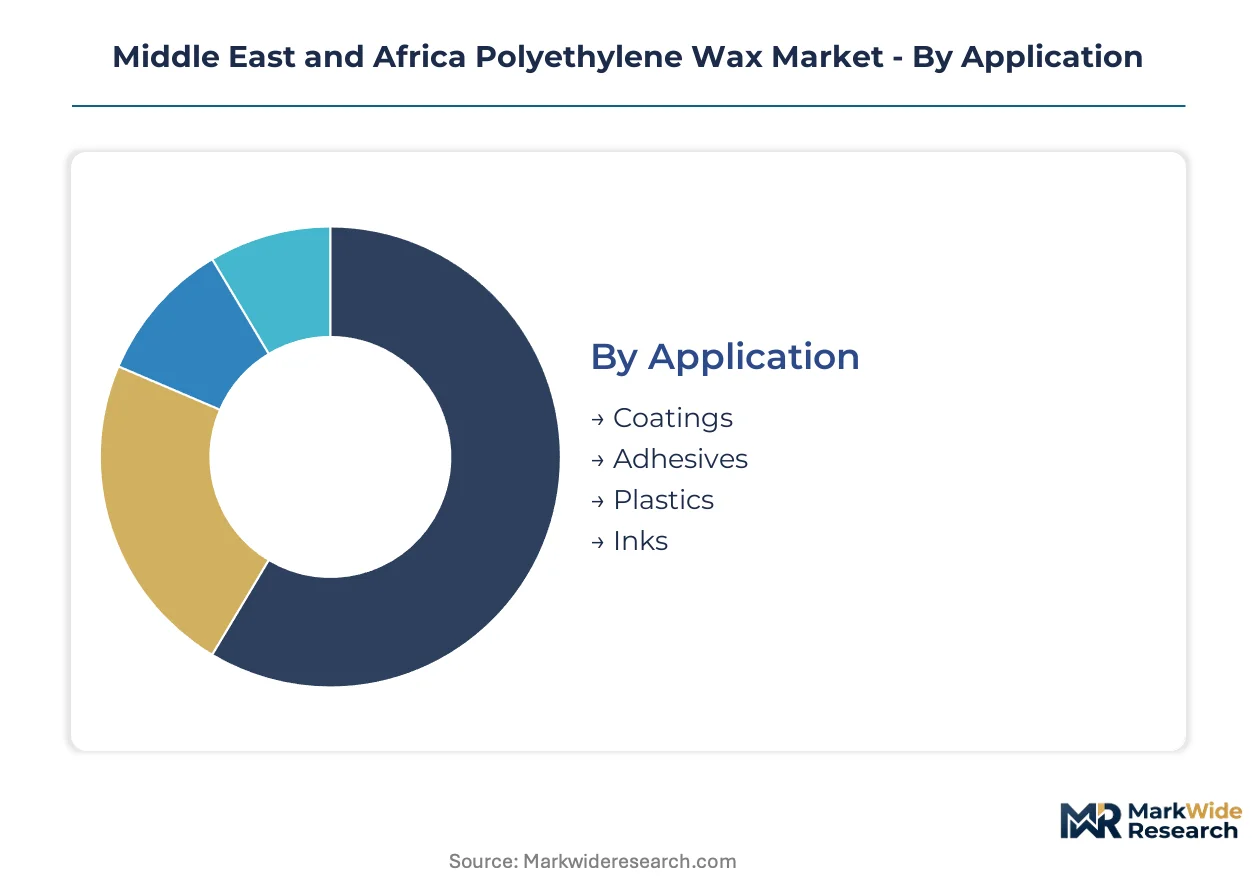
Polyethylene wax specifications diverge sharply across Middle East and Africa processing markets, with substitution pressures from Fischer-Tropsch wax and paraffin alternatives forcing suppliers to defend segment-specific value propositions. Technical-grade positioning now determines margin capture in each slice of the market structure.
Application:
Coatings processors face the most acute substitution threat as waterborne reformulation accelerates across Gulf packaging converters, while plastics compounders leverage feedstock integration to resist paraffin displacement.
- Coatings:Waterborne architectural and industrial formulations dominate procurement volumes across Saudi Arabia and UAE processing clusters. VOC protocol tightening under SASO frameworks is accelerating emulsified wax specification for decorative and protective coatings.
- Plastics:Masterbatch and compounding applications concentrate demand for high-density grades with narrow molecular weight distribution. Petrochemical integration across Jubail and Ruwais complexes secures captive supply for polyethylene resin producers backward integrating into wax blending.
- Adhesives:Hot-melt formulations for packaging assembly drive consistent offtake across Egyptian and Nigerian converter bases.
- Inks:Flexographic and gravure printing applications in South African label production specify oxidized polyethylene wax grades for rub resistance.
Plastics anchors the volume base while coatings gains share at the steepest rate.
Product Type:
Cost tier stratification separates integrated petrochemical producers from independent blenders, with feedstock access determining competitive viability in each density grade.
- High Density Wax:Elevated melting point and crystalline structure suit thermoplastic processing aids and premium coatings. Saudi masterbatch compounders specify these grades for automotive interior applications under SABS-equivalent performance requirements.
- Emulsified Wax:Aqueous dispersion formats enable waterborne coatings conversion without solvent handling infrastructure. UAE packaging converters in Dubai Industrial City and Jebel Ali Free Zone are reformulating solvent systems to meet tightening environmental protocols.
- Low Density Wax:Broader molecular weight distribution and lower melt viscosity serve price-sensitive candle and board sizing applications across North African markets.
- Others:Oxidized and micronized specialty grades address niche friction and surface modification requirements in textile and leather finishing.
High density wax anchors the volume base while emulsified wax expands most quickly.
End User:
Customer type concentration reflects diverging technical sophistication, with automotive specifications demanding certified grades while consumer goods tolerate broader quality variance.
- Packaging:Flexible film converters across Gulf Cooperation Council states represent the dominant procurement pool. Waterborne coatings adoption and masterbatch customization requirements are concentrating specification authority with technical-grade suppliers.
- Automotive:Interior trim and underhood specifications under South African Bureau of Standards certification displace uncertified imports. Sasol's Secunda complex supplies Fischer-Tropsch alternatives that compete directly with polyethylene wax in friction-reduction applications.
- Consumer Goods:Candle manufacturing and household product formulations in Egypt and Iran absorb price-sensitive low-density volumes.
- Textiles:Yarn lubrication and fabric finishing operations in Moroccan and Tunisian mills specify emulsified grades for aqueous processing compatibility.
Packaging anchors the volume base while automotive gains share at the steepest rate.
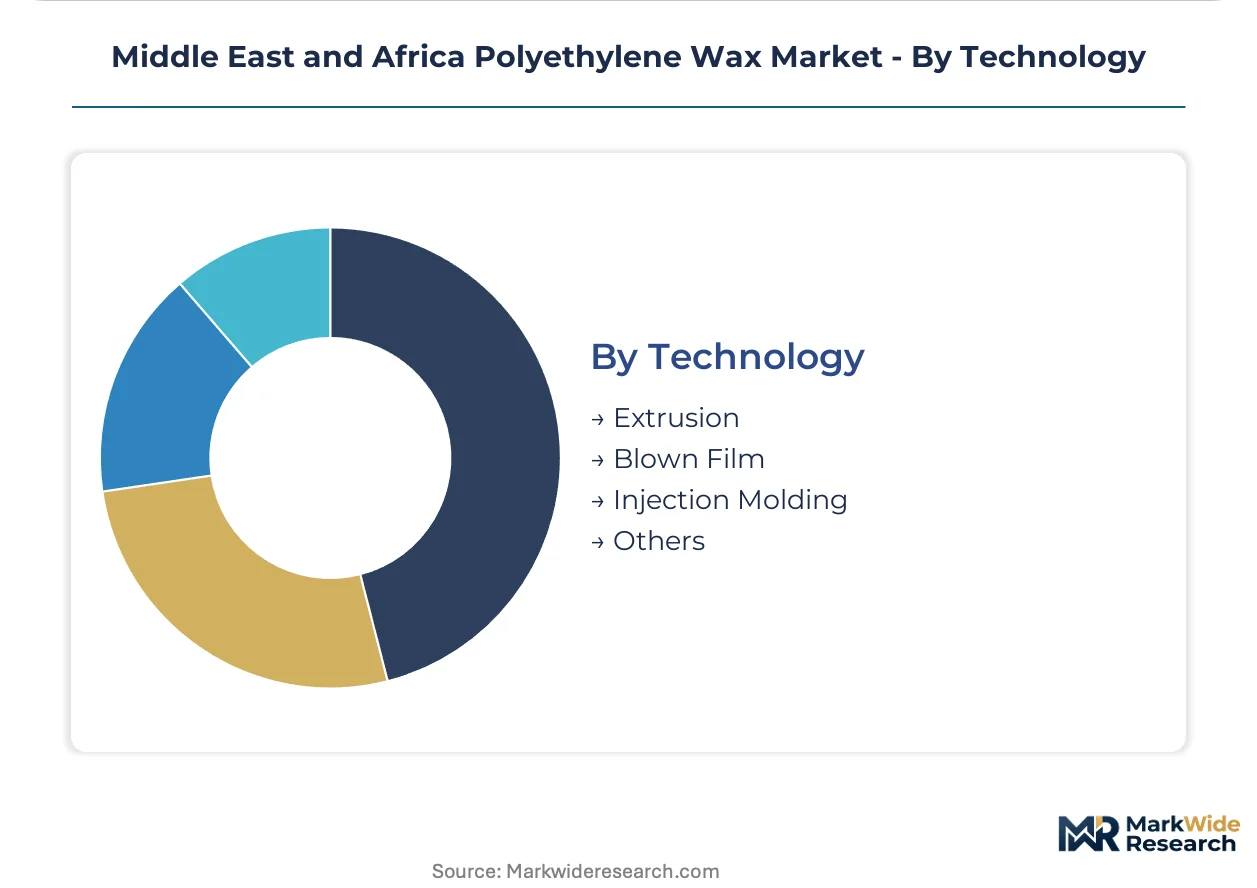
Technology:
Processing method determines wax incorporation format, with extrusion and blown film dominating continuous operations while injection molding drives discrete part applications.
- Extrusion:Continuous profile and sheet production across Saudi pipe and film operations requires consistent lubricant performance at elevated shear rates. High-density wax grades reduce die buildup and stabilize output dimensions.
- Blown Film:Bubble stability and optical clarity specifications in UAE flexible packaging plants favor narrow-distribution polyethylene wax as processing aids.
- Injection Molding:Cycle time reduction and mold release performance in South African automotive component molding drives demand for specialized wax formulations.
- Others:Rotational molding and compression forming in specialized industrial applications represent fragmented niche demand.
Extrusion anchors the volume base while blown film gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi polyethylene wax shipments flow primarily to UAE and Egyptian masterbatch compounders, while South African Fischer-Tropsch alternatives serve sub-Saharan packaging converters. This trade-flow pattern concentrates specification authority in Gulf petrochemical clusters.
Saudi Arabia
Masterbatch compounders in Jubail Industrial City drive demand for high-density grades with narrow molecular weight distribution. SASO chemical notification frameworks now require substance-level disclosure for waterborne coatings formulations. Petrochemical integration at SABIC-affiliated complexes secures captive wax blending capacity for downstream polyethylene resin producers.
United Arab Emirates
Packaging converters in Dubai Industrial City and Jebel Ali Free Zone are reformulating solvent-based systems to meet tightening volatile organic compound protocols. The Ministry of Industry and Advanced Technology advances local content mandates favoring domestic wax blending operations. Technical-grade suppliers with in-house application laboratories capture specification authority previously held by commodity distributors.
South Africa
Automotive interior trim specifications under SABS certification displace uncertified polyethylene wax imports. Sasol's Secunda complex dominates Fischer-Tropsch wax supply, creating single-source risk for regional formulators. Johannesburg-based masterbatch compounders bundle polyethylene wax into turnkey polymer systems for Nigerian and Kenyan packaging converters.
Egypt
Plastics compounding capacity in Alexandria and Suez remains underpenetrated by technical-grade suppliers. The country's national standards body enforces import registration requirements that fragment compliance timelines. Cairo-based candle manufacturers absorb price-sensitive low-density volumes from Iranian refiners.
Nigeria
Flexible film converters in Lagos and Port Harcourt represent emerging procurement pools for emulsified wax grades. Central Bank foreign exchange restrictions complicate import financing for European-sourced high-density formulations. Local packaging clusters seek bundled technical service support alongside wax procurement.
Middle East and Africa Polyethylene Wax Market Competitive Landscape
Player mix skews toward petrochemical majors with backward integration into ethylene feedstocks and specialty chemical houses with formulation expertise. The competitive terrain splits between integrated producers leveraging captive supply economics and independent blenders defending positions through technical service differentiation. Three archetypes dominate: Gulf-based petrochemical majors, European specialty chemical multinationals, and Fischer-Tropsch specialists with sub-Saharan feedstock control. Capacity expansion and geographic licensing agreements constitute the dominant competitive moves.
Within the Fischer-Tropsch specialist tier, Sasol Ltd anchors sub-Saharan supply through its South African complex structure. Among European specialty chemical houses, BASF SE and Clariant AG occupy positions bundling polyethylene wax into broader polymer additive portfolios. Baker Hughes represents the oilfield services conglomerate archetype with wax adjacencies in drilling fluid formulations.
| Leading Market Players |
|---|
| Baker Hughes |
| euroceras Sp. z o.o. |
| BASF SE |
| Sasol Ltd |
| Lion Chemtech Co., Ltd. |
| Clariant AG |
| Mitsui Chemicals Inc |
| The Lubrizol Corporation |
| Honeywell International Inc |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles at Gulf-based masterbatch compounders concentrate pricing power with integrated petrochemical producers while squeezing independent blenders reliant on spot ethylene purchases. This lead-time band reflects the tight coupling between feedstock integration and margin capture across Saudi and UAE processing clusters.
Pricing Analysis
Metallocene-catalyzed grades command a technology-generation pricing gap of roughly one-third above conventional Ziegler-Natta materials, with narrow molecular weight distribution justifying premiums in automotive specifications. Three-tier pricing structure across premium, standard, and economy levels separates certified SABS grades from uncertified imports and commodity low-density volumes. Cost compression in economy tiers is intensifying because Iranian paraffin refiners undercut polyethylene wax in candle and board applications. Consumer goods manufacturers in Egypt and North Africa exhibit the highest price sensitivity, while Saudi automotive masterbatch compounders accept premium positioning for certified high-density formulations.
Supply Chain Analysis
Sixty-to-ninety-day inventory cycles at Gulf-based masterbatch compounders reflect just-in-time coordination with SABIC-affiliated crackers in Jubail and Ruwais. Supply concentrates in Saudi Arabia, the UAE, and South Africa, with raw material dependencies spanning naphtha feedstocks at Gulf crackers and Fischer-Tropsch streams at Sasol's Secunda complex. Single-source vulnerability permeates sub-Saharan markets where Sasol dominates Fischer-Tropsch wax supply. Distribution runs through technical-grade suppliers with in-house application laboratories rather than commodity traders, as Dubai and Jeddah packaging converters demand bundled formulation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of waterborne coatings chemists capable of optimizing emulsified wax performance across Gulf processing clusters defines competitive advantage in this market. Technical service depth now separates viable suppliers from margin-compressed commodity players.
For Market Incumbents: Fortify backward integration into ethylene feedstocks at Jubail and Ruwais complexes to defend against naphtha price volatility eroding blending margins. Expand in-house application laboratory capacity in Dubai Industrial City to capture specification authority from commodity distributors. Prioritize SASO certification investment for waterborne formulations ahead of GCC chemical notification harmonization. For New Entrants and Emerging Players: Technical service gaps in Egyptian plastics compounding represent the most penetrable white-space target, with Alexandria and Suez converters seeking formulation optimization support absent from current supply relationships. Emulsified wax grades for Nigerian flexible film converters offer a second entry vector, with Lagos-based packaging clusters demanding bundled procurement and technical assistance. Position through joint development agreements with local masterbatch compounders rather than direct distribution. For Investors and Strategic Acquirers: Long-term, this sits as a regional consolidation play because petrochemical integration economics favor scale players with captive feedstock access over independent blenders. Target acquisition archetypes include mid-cap technical-grade suppliers with established SASO dossiers and Gulf-based application laboratory networks. Monitor Egyptian downstream expansion announcements as the inflection signal for first-mover positioning in underpenetrated compounding capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstocks | SABIC-affiliated complexes in Jubail secure captive wax blending capacity against naphtha volatility. |
| Technical Service Laboratory Expansion | Dubai-based application facilities capture specification authority from legacy commodity distributors. |
| SASO Certification Investment | Substance-level disclosure compliance opens Saudi waterborne coatings procurement to European suppliers. |
| Egyptian Downstream Joint Venture | Alexandria and Suez compounding capacity offers first-mover positioning in underpenetrated technical-grade supply. |
| Fischer-Tropsch Supply Diversification | Reducing Sasol Secunda dependency mitigates single-source risk for sub-Saharan formulators. |
Research Methodology
A standing panel of masterbatch plant managers, coatings formulators at UAE packaging converters, Fischer-Tropsch procurement leads, and SASO regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from GCC customs and trade data, SABS certification registries, SEC filings of petrochemical majors, and Saudi Standards, Metrology and Quality Organization notification frameworks. Bottom-up segment sizing triangulated against top-down ethylene derivative demand models to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across density grade tiers, end-use industry clusters, emulsification technology formats, and regional production hub economics. CAGRs derived from trend extrapolation of petrochemical integration rates, waterborne coatings conversion velocities, and SABS certification penetration curves. Industry-specific inputs included naphtha crack spread volatility indices and Fischer-Tropsch wax substitution elasticities in South African automotive applications.
Forecasts assume regulatory continuity in SASO and SABS regimes; material policy shifts in GCC chemical notification frameworks or South African automotive specifications would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Concrete Containing Polymer Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Synthetic and Bio Thermosets Market