
 Anti-Static Fibers Market | 2026-2036
Anti-Static Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Fibers Market Analysis
Asian carbon fiber producers is recalibrating capacity allocation toward conductive yarn lines to serve semiconductor cleanroom demand. Toray Industries leverages its polymer science heritage to sustain premium positioning in nylon-based anti-static substrates. DuPont anchors North American supply through integrated aramid-conductive fiber platforms. KB Seiren specializes in ultra-fine denier electrostatic discharge yarns for Japanese electronics OEMs.
Anti-static fibers are engineered textile filaments incorporating conductive additives such as carbon black, metal oxides, or inherently conductive polymers to achieve surface resistivity below 10^9 ohms per square, primarily deployed to prevent electrostatic discharge damage in sensitive manufacturing environments. Polyester variants dominate volume shipments due to cost-efficient carbon loading and broad textile processability, while conductive fiber technology captures margin pools through precision resistivity control in semiconductor wafer handling. Hybrid fiber formulations are gaining fastest traction as they balance wash durability with electrostatic decay rates under 0.5 seconds.
EPA guidelines on particulate emissions in US electronics fabrication and REACH substance restrictions in Europe shape material formulation roadmaps, forcing substitution of legacy antistatic agents with halogen-free conductive additives. China's GB standards on static control in explosive atmospheres and Japan's JIS testing protocols for electrostatic decay further fragment certification requirements across supply chains. Stakeholders must monitor evolving ESD association standards and regional chemical registration deadlines to preempt compliance-driven specification changes.
Market Dynamics
Semiconductor fabrication capacity expansion in East Asia is compressing lead times for anti-static fiber procurement while forcing suppliers to recalibrate resistivity specifications for advanced node manufacturing. This demand surge from wafer handling applications is reshaping allocation decisions across carbon fiber and conductive polymer supply chains.
Growth Catalysts
- China GB Standards:China's explosive atmosphere static control mandates are accelerating replacement of legacy textile materials in chemical processing facilities. Domestic semiconductor foundry buildouts amplify specification stringency.
- Electronics Manufacturing:Cleanroom garment demand from semiconductor and flat-panel display production is pulling conductive yarn volumes upward. Wafer handling protocols now require sub-10^9 ohm surface resistivity as standard.
- Conductive Polymer Blends:Halogen-free conductive additives are displacing legacy antistatic agents under REACH substance restrictions. Formulation shifts enable European electronics OEMs to maintain export access.
Market Restraints
- Acrylonitrile Cost Volatility:Carbon fiber precursor prices fluctuate with petrochemical feedstock markets. Anti-static fiber margins compress when acrylonitrile spot prices spike.
- Japanese Supplier Concentration:Ultra-fine denier electrostatic discharge yarn production clusters with specialized Japanese textile houses. Geographic concentration creates supply vulnerability for precision electronics applications.
- Wash Durability Ceiling:Carbon-loaded polyester fibers exhibit conductivity degradation after 50+ industrial laundering cycles. This technical limitation restricts adoption in reusable cleanroom apparel segments.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme subsidies for semiconductor and mobile device production are creating latent demand for ESD-compliant textiles. Domestic garment converters lack qualified fiber supply.
- Battery Cell Assembly:Lithium-ion dry room environments require static control below 10^6 ohms. Anti-static fiber producers can extend formulations from semiconductor to energy storage applications.
- EU Green Deal:Circular economy textile mandates favor durable, recyclable conductive fibers over disposable alternatives. Premium positioning opens for bio-based conductive polymer formulations.
Industry Challenges
- Multi-Jurisdiction Certification:Simultaneous compliance with EPA particulate guidelines, REACH substance restrictions, and JIS electrostatic decay protocols elongates product launch timelines. Testing costs accumulate across certification stacks.
- Polymer Science Talent Scarcity:Formulation chemists with expertise in both textile processing and conductive additive dispersion command premium compensation. Recruitment friction slows R&D pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Fibers Market |
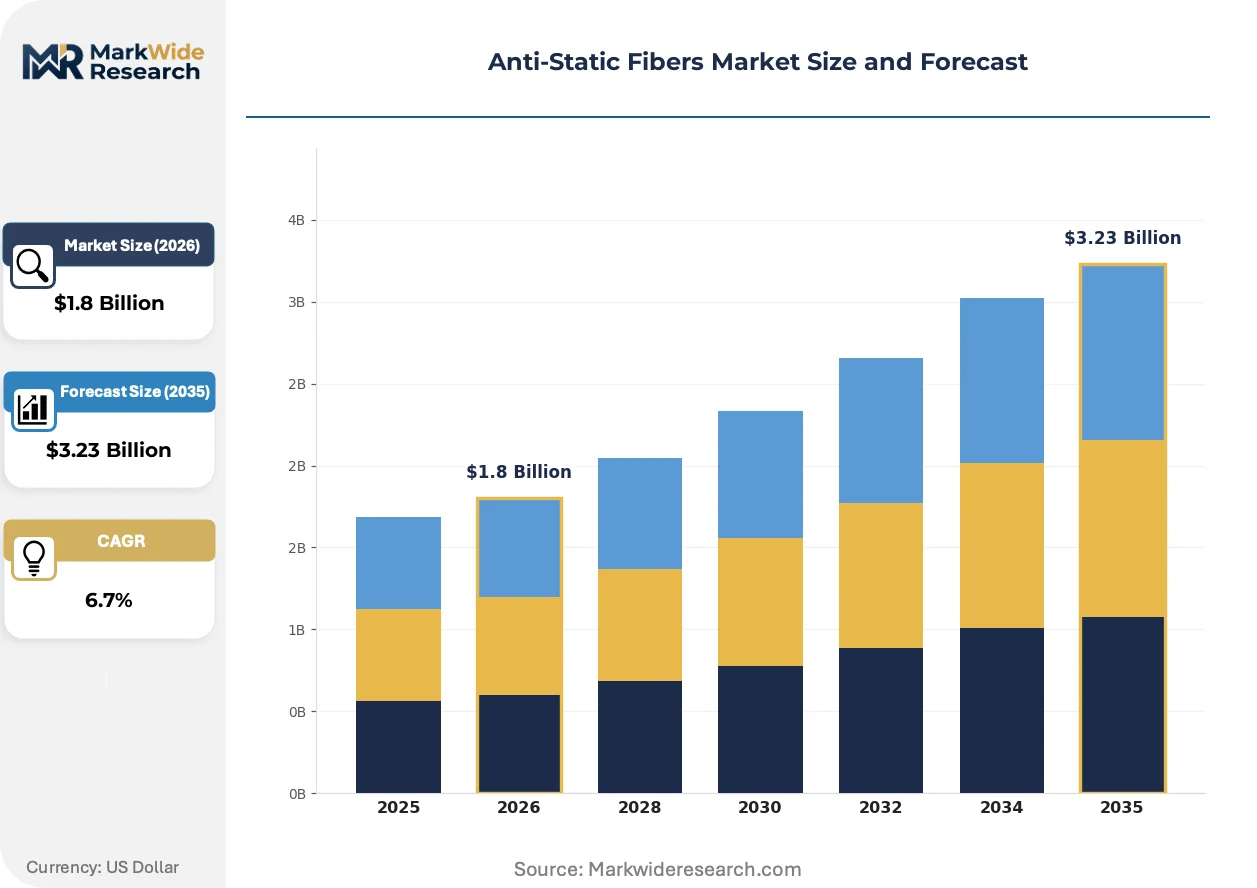
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon, Polyester, Polypropylene, Acrylic Application: Textiles, Electronics, Packaging, Automotive End User: Manufacturers, Retailers, Distributors, Contractors Technology: Electrostatic Discharge, Anti-Static Coatings, Conductive Fibers, Hybrid Fibers |
| Companies Covered | Barnet, KB Seiren, Toray Industries, 3M, DuPont, Teijin Limited, Swicofil AG, Honeywell, Kuraray Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Fibers Market Emerging Trajectories
Hybrid fiber architectures are displacing single-material solutions as end-users demand simultaneous optimization of electrostatic decay rates, textile processability, and laundering durability. This convergence is compressing development cycles and reshaping supplier qualification protocols.
Conductive polymer core-sheath bicomponent fibers are consolidating technical preference among semiconductor cleanroom operators. Toray Industries and specialized Japanese houses have accelerated adoption through integrated spinning and conductivity control. This architecture is consolidating market share from carbon-black-loaded alternatives by delivering sub-0.5-second electrostatic decay without particulate shedding.
REACH authorization procedures for legacy antistatic agents are forcing formulation roadmaps toward halogen-free conductive additives. ECHA substance evaluation timelines compress decision windows for European electronics textile suppliers. Small and mid-sized compounders face disproportionate compliance burden relative to integrated polymer houses with dedicated regulatory affairs functions.
Buyer consolidation among semiconductor foundry operators is lengthening contract durations while compressing approved vendor lists. Procurement teams at TSMC, Samsung, and Intel now mandate multi-year supply agreements with embedded volume commitments and resistivity specification bands. This shift is most visible in Taiwan and South Korea, where foundry concentration has eliminated spot-market purchasing for critical cleanroom materials.
Anti-Static Fibers Market Segmentation
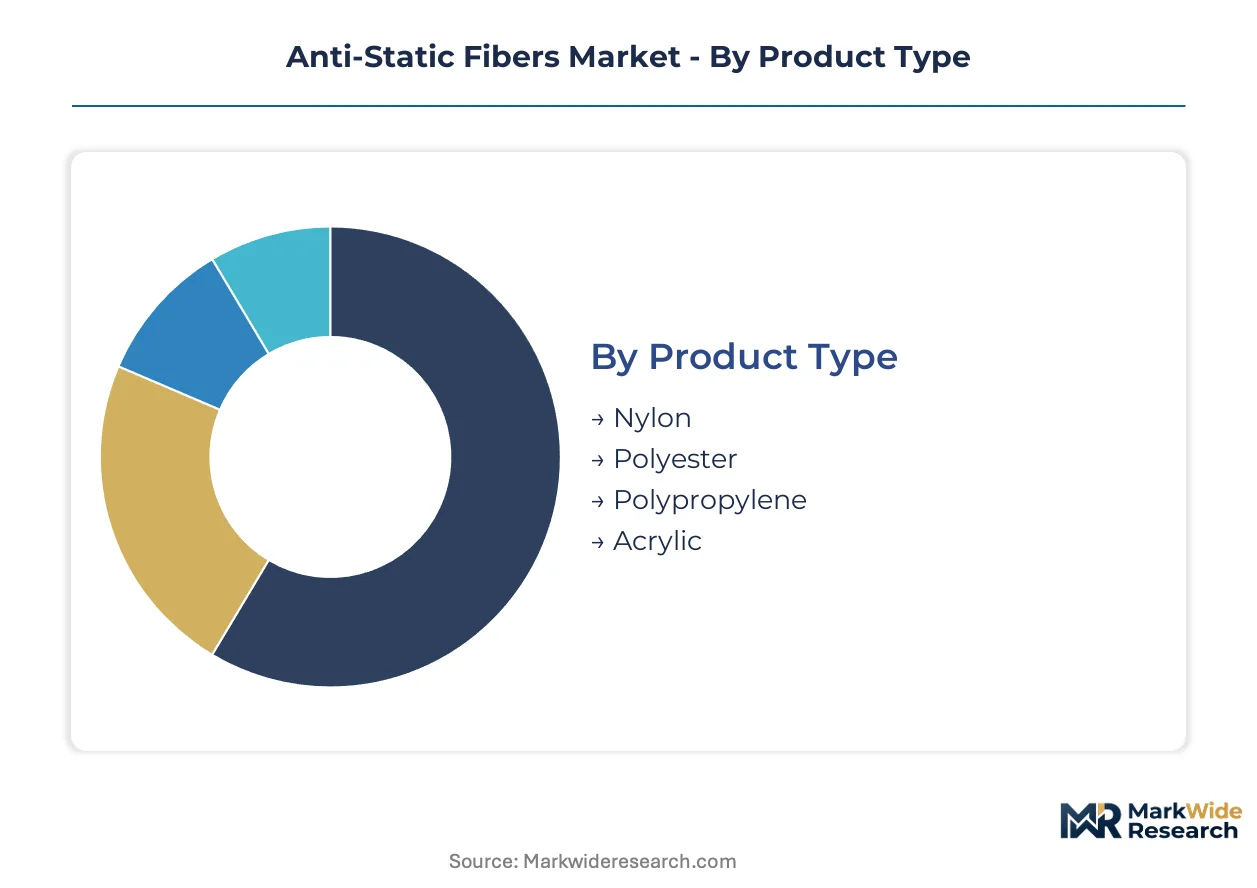
Anti-static fiber procurement decisions pivot on resistivity specifications, laundering durability, and compliance with regional chemical regulations. Segmentation reveals how formulation trade-offs map to end-use value pools across semiconductor, automotive, and industrial textile applications.
Product Type:
Buyers select polymer substrates based on carbon loading efficiency, textile processability, and wash-cycle retention of conductive properties.
- Nylon:Inherently hydrophilic structure enables uniform carbon black dispersion and superior abrasion resistance in cleanroom garment applications. Semiconductor wafer handling protocols in Taiwan and South Korea specify nylon-based substrates for their sub-0.5-second electrostatic decay performance. Toray Industries leverages polymer science heritage to sustain premium positioning in this segment.
- Polyester:Cost-efficient carbon loading and broad compatibility with standard textile machinery dominate volume shipments. Carbon-loaded variants face conductivity degradation after 50+ industrial laundering cycles, restricting adoption in reusable cleanroom apparel segments.
- Polypropylene:Low density and chemical resistance suit explosive atmosphere applications under China's GB standards. The polymer's hydrophobicity requires specialized conductive additive dispersion techniques.
- Acrylic:Soft hand-feel and dyeability position this material for consumer-facing anti-static textiles. Acrylonitrile cost volatility compresses margins when petrochemical feedstock prices spike.
Volume sits with Polyester; growth tilts toward Nylon as semiconductor fabrication advances to smaller process nodes.
Application:
Application selection tracks the severity of electrostatic discharge risk and the regulatory density of the operating environment.
- Electronics:Cleanroom garment demand from semiconductor and flat-panel display production pulls conductive yarn volumes upward. Wafer handling protocols at TSMC, Samsung, and Intel now mandate sub-10^9 ohm surface resistivity as standard, with procurement teams mandating multi-year supply agreements.
- Textiles:Industrial workwear and protective apparel incorporate anti-static fibers to comply with occupational safety mandates. Wash durability requirements favor hybrid fiber formulations over carbon-black-loaded alternatives.
- Packaging:Flexible intermediate bulk containers and semiconductor shipping materials require static dissipation without particulate shedding. REACH substance restrictions accelerate halogen-free conductive additive adoption in European supply chains.
- Automotive:Seating fabrics and fuel system components deploy anti-static properties to prevent spark ignition in vapor-rich environments. Electric vehicle battery assembly dry rooms extend specification stringency from semiconductor applications.
Electronics commands the dominant revenue share; automotive applications are expanding most quickly as lithium-ion cell production scales.
End User:
End-user category determines contract structure, with foundry operators consolidating procurement through embedded volume commitments.
- Manufacturers:Semiconductor foundries, flat-panel display producers, and battery cell assemblers drive specification-setting. Buyer consolidation among TSMC, Samsung, and Intel compresses approved vendor lists and lengthens contract durations.
- Contractors:Facility construction and maintenance providers procure anti-static textiles for temporary cleanroom installations. Spot-market purchasing persists in this fragmented channel.
- Distributors:Industrial textile distributors aggregate demand from small and mid-sized electronics assemblers. Inventory carrying costs concentrate in carbon fiber and conductive polymer supply chains.
- Retailers:Consumer-facing channels for anti-static apparel and home textiles represent a marginal volume pool with price-sensitive substitution dynamics.
Procurement gravity centers on Manufacturers; Distributors offer the steepest expansion trajectory as India's PLI scheme builds domestic electronics manufacturing.
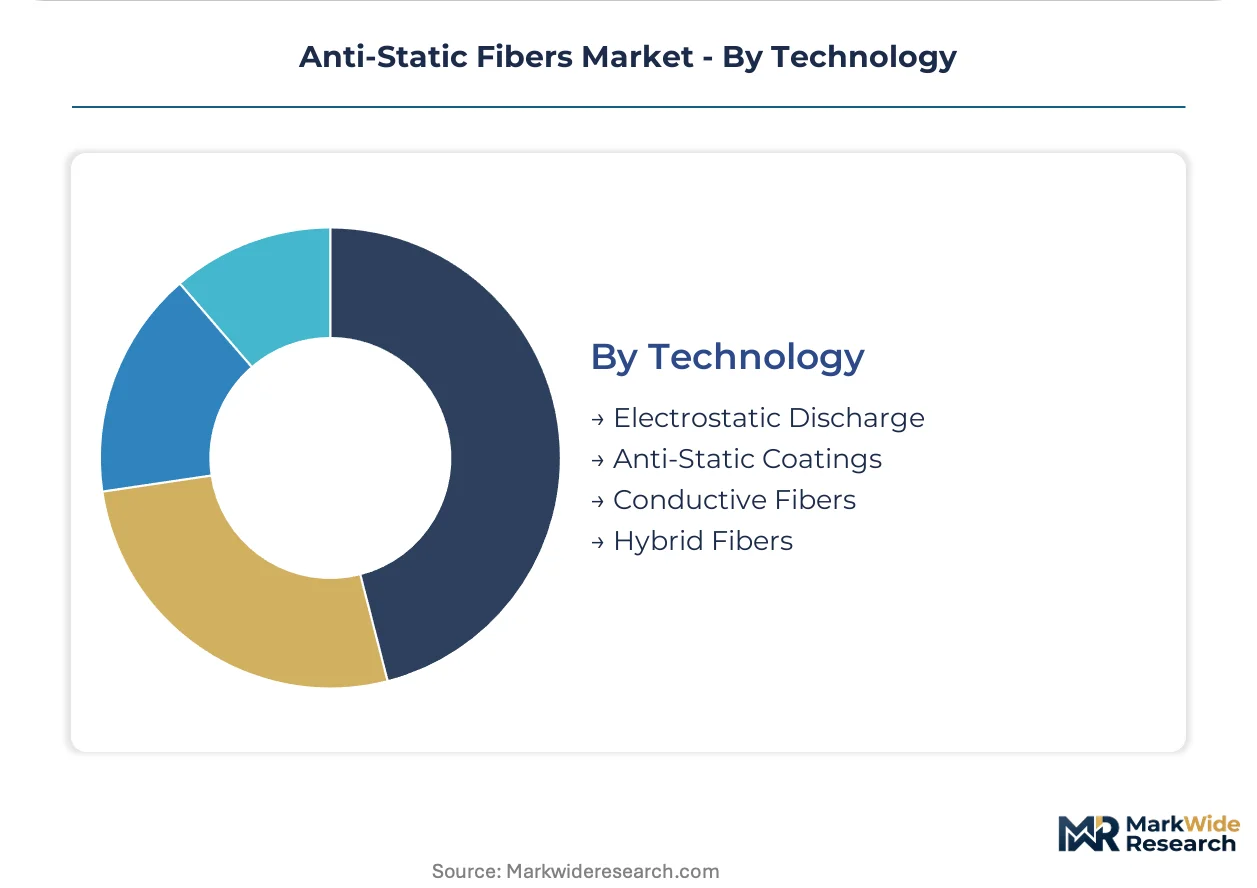
Technology:
Technology selection balances electrostatic decay performance against particulate shedding and regulatory compliance burdens.
- Hybrid Fibers:Core-sheath bicomponent architectures combine conductive polymer cores with protective polymer sheaths. This formulation delivers sub-0.5-second electrostatic decay without carbon particle shedding, consolidating technical preference among semiconductor cleanroom operators in Japan and Taiwan.
- Conductive Fibers:Inherently conductive polymers achieve precision resistivity control for advanced node manufacturing. ECHA substance evaluation timelines compress decision windows for European electronics textile suppliers.
- Electrostatic Discharge:Surface-treated yarns with topical anti-static agents serve cost-sensitive disposable applications. Wash durability limitations restrict reusable garment adoption.
- Anti-Static Coatings:Post-spinning chemical treatments offer retrofit options for legacy textile inventories. EPA particulate guidelines and REACH restrictions constrain formulation flexibility.
Hybrid Fibers capture the fastest-growing trajectory; Electrostatic Discharge retains volume leadership in disposable cleanroom segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylonitrile feedstock availability in East Asian petrochemical corridors shapes regional production economics. Semiconductor fabrication clusters concentrate procurement power across Taiwan, South Korea, and eastern China. Regulatory fragmentation across EPA, REACH, and GB standards forces multi-jurisdiction compliance strategies.
China
Domestic semiconductor foundry buildouts by SMIC and Hua Hong Semiconductor amplify specification stringency for wafer handling textiles. GB standards on static control in explosive atmospheres mandate replacement of legacy materials in chemical processing facilities. The Yangtze River Delta hosts the densest concentration of carbon fiber precursor plants serving conductive yarn manufacturers.
Japan
Ultra-fine denier electrostatic discharge yarn production clusters with specialized textile houses in Osaka and Nagoya prefectures. JIS testing protocols for electrostatic decay set technical benchmarks that Taiwanese and South Korean foundries reference in procurement specifications. Toray Industries and KB Seiren anchor domestic supply chains through integrated polymer science capabilities.
South Korea
Samsung and SK Hynix fabrication complexes drive cleanroom garment demand with multi-year supply agreements replacing spot-market purchasing. The country's national chemical regulator enforces alignment with REACH substance restrictions to maintain European export access for electronics OEMs. Busan-Ulsan corridor hosts carbon fiber conversion facilities recalibrating capacity toward conductive yarn lines.
Taiwan
TSMC procurement teams mandate sub-10^9 ohm surface resistivity as standard for advanced node manufacturing, compressing lead times for anti-static fiber suppliers. The Hsinchu Science Park concentrates foundry operators whose buyer consolidation eliminates fragmented purchasing channels. Domestic textile converters face qualification barriers from Japanese and Korean fiber houses.
United States
EPA guidelines on particulate emissions in electronics fabrication shape material formulation roadmaps for domestic cleanroom operators. Intel's Arizona and Oregon fabrication sites anchor North American demand through integrated aramid-conductive fiber platforms. DuPont sustains supply continuity amid regulatory pressure on halogen-free conductive additive adoption.
Anti-Static Fibers Market Vendor Landscape
Global majors compete with regional champions across polymer science capabilities and semiconductor foundry relationships. The vendor base organizes around integrated chemical conglomerates with captive fiber spinning, specialized Japanese textile houses with ultra-fine denier expertise, and regional compounders serving industrial textile channels. Three archetypes dominate: polymer science heritage players, precision electronics specialists, and diversified materials conglomerates. Competitive moves concentrate on backward integration into conductive additive production and strategic partnerships with foundry operators for multi-year supply agreements.
Within the polymer science heritage tier, Toray Industries and DuPont exemplify integrated capabilities spanning resin synthesis through fiber spinning. KB Seiren occupies a specialized position among Japanese precision textile houses. These three anchors represent divergent strategic postures: Toray leverages nylon substrate expertise for semiconductor cleanroom dominance, DuPont anchors North American supply through aramid-conductive platforms, and KB Seiren concentrates on ultra-fine denier specifications for Japanese electronics OEMs. Regional compounders outside this core triangle face qualification barriers from buyer consolidation at TSMC, Samsung, and Intel.
| Leading Market Players |
|---|
| Barnet |
| KB Seiren |
| Toray Industries |
| 3M |
| DuPont |
| Teijin Limited |
| Swicofil AG |
| Honeywell |
| Kuraray Co. |
| Others |
Supply Flow & Price Mechanics
Acrylonitrile spot price volatility cascades through carbon fiber precursor markets into three distinct pricing tiers for anti-static fiber procurement. Semiconductor foundry operators in Taiwan and South Korea absorb premium-grade nylon-based substrates at contracted rates, while industrial textile channels in Southeast Asia transact on carbon-loaded polyester spot markets. The Yangtze River Delta concentration of acrylonitrile production amplifies regional cost advantages for Chinese conductive yarn manufacturers serving domestic electronics assembly.
Pricing Analysis
Multi-year supply agreements bundle technical certification maintenance and resistivity testing protocols into headline pricing for semiconductor cleanroom operators. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified hybrid fibers from carbon-black-loaded polyester and topical anti-static treatments. Cost compression in carbon-loaded polyester segments is intensifying because acrylonitrile feedstock volatility compresses compounder margins. Contract manufacturers and temporary cleanroom installers exhibit highest price sensitivity, while TSMC and Samsung procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Polymer science talent scarcity in Osaka, Nagoya, and Hsinchu constrains expansion of ultra-fine denier spinning capacity for precision electronics applications. Manufacturing concentrates in Japan, South Korea, and Taiwan, with raw material flows drawing from Chinese acrylonitrile plants and German carbon black specialists. Single-source vulnerability clusters around specialized Japanese textile houses controlling sub-10-micron conductive yarn production. Distribution runs through foundry-approved vendor lists and industrial textile distributors serving fragmented electronics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among semiconductor foundry operators is forcing sub-scale compounders toward exit or acquisition, compressing viable vendor lists to integrated polymer houses with captive regulatory affairs functions.
For Market Incumbents: Hedge against REACH authorization timelines by accelerating halogen-free conductive additive formulation shifts before ECHA evaluation windows close. Secure backward integration into carbon fiber precursor supply through offtake agreements with Yangtze River Delta petrochemical corridors. Toray Industries and DuPont demonstrate how polymer science heritage sustains premium positioning against commodity carbon-loaded alternatives. For New Entrants and Emerging Players: Enter via India's PLI scheme subsidies for semiconductor and mobile device manufacturing, where domestic garment converters lack qualified ESD-compliant fiber supply. Target battery cell assembly dry rooms extending specification stringency from semiconductor applications, as lithium-ion production scales create latent demand for sub-10^6 ohm static control textiles. Partner with industrial textile distributors to bypass foundry qualification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale compounders with existing EPA or REACH compliance infrastructure in South Korea and Taiwan, where national chemical regulators enforce alignment with European substance restrictions. Long-term viability hinges on captive conductive additive production and foundry relationship depth. Watch TSMC and Intel procurement team decisions on embedded volume commitments as inflection indicators for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Additives | Captive carbon black or inherently conductive polymer production insulates margins from acrylonitrile volatility. |
| Multi-Year Foundry Supply Agreements | Embedded volume commitments with TSMC, Samsung, or Intel lock out spot-market competitors. |
| Halogen-Free Formulation Transition | REACH compliance enables continued European electronics OEM export access. |
| Ultra-Fine Denier Capacity Expansion | Sub-10-micron spinning capabilities capture precision wafer handling specification tiers. |
| India PLI Scheme Market Entry | Domestic electronics manufacturing subsidies create first-mover advantage in qualified fiber supply. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cleanroom garment procurement managers, polymer formulation chemists, semiconductor foundry EHS directors, and industrial textile distribution heads combined with ECHA substance evaluation databases, EPA particulate emission guidelines, and JIS testing protocol documentation. Bottom-up fiber shipment estimates triangulated against top-down electronics manufacturing capex disclosures.
Reconciliation of import-export flows, foundry capacity announcements, and conductive yarn production data informed the analytical framework across the projection horizon. Segmentation dimensions modeled include polymer substrate type, application severity tier, end-user contract structure, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating semiconductor node advancement timelines and GB standards implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH substance restriction acceleration or acrylonitrile supply disruption scenarios. Forecasts reflect documented assumptions regarding foundry buildout timelines and conductive additive dispersion technology maturation. Material deviation in ECHA authorization timelines or Chinese semiconductor self-sufficiency policy intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Global Synthetic Spider Silk Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Asia-Pacific Spandex Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Rayon Fibers Market
Synthetic Fibers
IMO Fiber Market
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
Fiber Blends Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Global Acrylic Fibers Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Clothing Fibers Market
Synthetic Fibers
Polyester Fibers Market