
 Monofilament Market | 2026-2036
Monofilament Market Size, Share, and Industry Trends Forecast 2026-2036
Monofilament Market Outlook
Aftermarket technical support and filament recycling services is tilting margin pools away from commodity extrusion toward value-added lifecycle offerings. Toray Industries Inc. leverages its polymer science depth to dominate aerospace-grade monofilament supply chains. Shakespeare Company LLC anchors North American recreational fishing line demand through proprietary copolymer formulations. Hinafil India Ltd competes on cost-optimized polypropylene output for agricultural mesh applications.
Monofilament denotes a single continuous synthetic fiber extruded to precise diameters, typically ranging from 0.05 mm to 5.0 mm, engineered for tensile strength, chemical resistance, or controlled degradation profiles depending on end-use requirements. Nylon monofilament retains the largest share in fishing line and suture applications where knot strength and elasticity prove critical. Polyester grades are gaining fastest in medical mesh and cardiovascular applications due to superior hydrolytic stability and reduced tissue reaction rates. Extrusion technology occupies the dominant process position, though braiding capabilities differentiate suppliers serving surgical and industrial rope segments.
EPA guidelines on microplastic discharge and FDA 21 CFR requirements for implantable device materials constrain formulation choices and manufacturing site qualifications for suppliers targeting regulated end uses. REACH substance restrictions and EU MDR biocompatibility testing protocols further elevate compliance costs for European market access. Stakeholders must monitor evolving state-level packaging waste regulations and polymer traceability mandates that threaten to fragment raw material sourcing strategies.
Market Dynamics
Medical device sterilization standards from FDA and EU MDR are compressing formulation flexibility while elevating biocompatibility certification costs for monofilament suppliers serving implantable applications.
Growth Catalysts
- EU MDR biocompatibility testing mandates:Surgical mesh manufacturers are accelerating polyester monofilament qualification to meet implantable device traceability requirements across European hospital procurement networks.
- China's dual carbon goals:Domestic fishing line producers are retrofitting extrusion lines to process bio-based polyamides, creating captive demand for sustainable monofilament feedstocks.
- Angioplasty guidewire demand:Cardiovascular device OEMs in Germany and the United States are specifying ultra-fine diameter nitinol-coated monofilament for minimally invasive catheter systems.
Market Restraints
- Caprolactam price volatility:Nylon 6 monofilament margins compress when benzene-derived feedstock costs spike, forcing mid-tier extruders to absorb input fluctuations or lose automotive textile contracts.
- REACH substance restrictions:Phthalate plasticizer bans and emerging PFAS limitations constrain formulation options for European medical and consumer monofilament applications.
- Polyethylene terephthalate substitution:Recycled PET fiber is displacing virgin polyester monofilament in non-critical agricultural netting, eroding volume in commodity-grade segments.
Strategic Opportunities
- India's PLI scheme for technical textiles:Domestic monofilament producers can capture incentives by qualifying output for geotextile and agro-mesh applications under the national manufacturing promotion framework.
- 3D printing filament convergence:Medical modeling labs are sourcing PEEK monofilament for patient-specific surgical guides, opening premium pricing tiers beyond traditional suture markets.
- Closed-loop recycling infrastructure:Industrial fishing fleet operators in Japan are piloting take-back programs for spent nylon line, creating service revenue pools that bypass virgin resin commodity cycles.
Industry Challenges
- ISO 13485 certification timelines:Medical-grade monofilament suppliers face 18-24 month quality system audits before qualifying for implantable device supply chains, freezing working capital in pre-revenue validation phases.
- Multi-axis braiding integration:Surgical suture manufacturers struggle to merge precision extrusion with automated braiding lines, creating yield losses when transitioning from monofilament to multifilament construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monofilament Market |
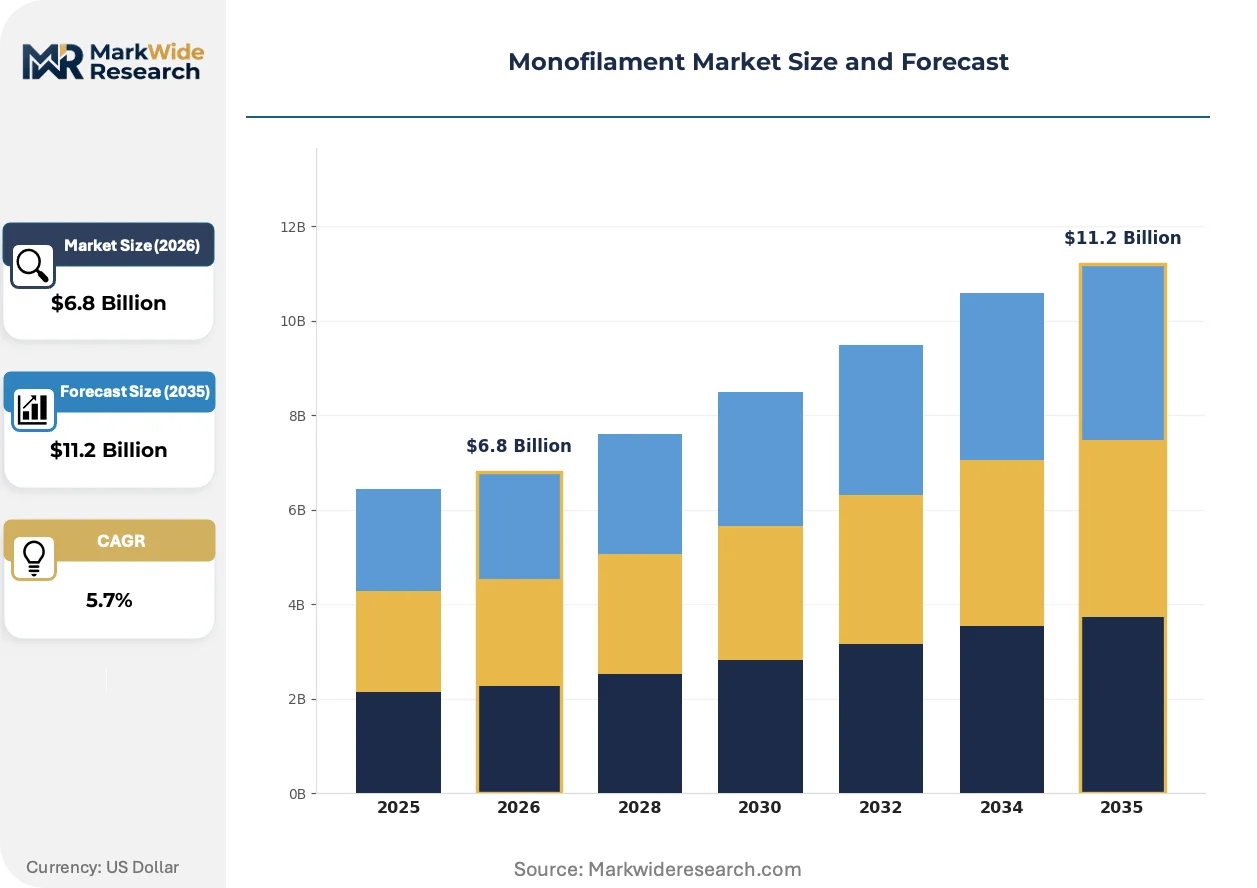
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon, Polyester, Polypropylene, PVA Technology: Extrusion, Injection Molding, Braiding, Winding End Use Industry: Aquaculture, Medical Devices, Fishing, Sporting Goods Application: Sutures, Fishing Lines, Ropes, Monofilament Mesh |
| Companies Covered | Superfil Products Ltd, Shakespeare Company LLC, Toray Industries Inc., Ascend Performance Materials, Ruichang Monofilament, Ashley Polymers Inc., Engineered Monofilaments Corporation, Hinafil India Ltd, Perlon GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monofilament Market Strategic Shifts
Extrusion process control systems are embedding real-time diameter monitoring, enabling medical-grade producers to tighten tolerance bands while regulatory frameworks harden traceability requirements for implantable materials.
Smart sensor integration into melt pumps is digitizing quality assurance workflows, allowing surgical suture manufacturers to eliminate batch testing delays. Device OEMs in Switzerland and the United States are qualifying these sensor-augmented lines for cardiovascular applications where diameter consistency directly impacts catheter deliverability. The compression of manual inspection labor is reallocating technical staff toward polymer science R&D functions.
EPA microplastic discharge guidelines are forcing fishing line producers to reformulate with accelerated degradation additives, particularly for freshwater applications where ghost gear accumulation triggers state-level enforcement actions. Washington and California regulators are advancing the strictest implementation timelines, pushing suppliers to validate biodegradation rates under standardized marine conditions before product registration.
Hospital procurement consortia are consolidating vendor panels for suture materials, displacing fragmented distributor networks with direct contractual relationships between GPOs and qualified monofilament extruders. This concentration is visible most acutely in the United States, where three national purchasing organizations now control the majority of synthetic absorbable suture volume, compressing margin structures for mid-tier suppliers lacking FDA 510(k) predicate device portfolios.
Monofilament Market Segmentation
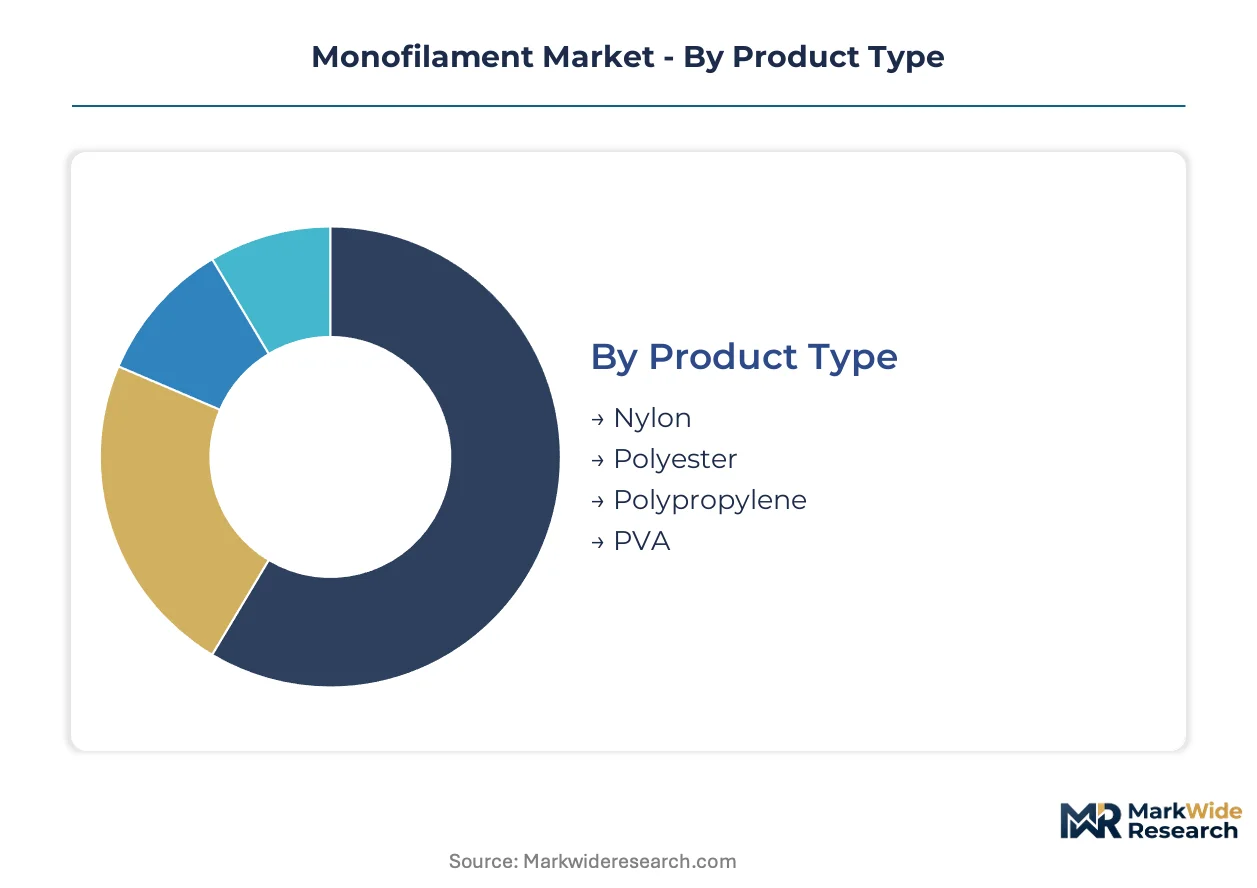
Monofilament producers face divergent margin structures across medical, industrial, and consumer applications. Segmentation by polymer chemistry and manufacturing process determines which suppliers qualify for regulated implantable device supply chains versus commodity fishing line markets.
Product Type:
Mature commodity grades dominate volume throughput while emerging specialty polymers capture premium pricing tiers in regulated medical applications.
- Nylon:Polyamide 6 and 6,6 formulations deliver superior knot strength and controlled elasticity for surgical sutures and high-performance fishing lines. Angioplasty guidewire demand from cardiovascular OEMs in Germany and the United States is compressing diameter tolerances below 0.10 mm for nitinol-coated variants.
- Polyester:Polyethylene terephthalate and PBT grades exhibit hydrolytic stability and minimal tissue reaction rates in implantable mesh applications. EU MDR biocompatibility testing mandates are accelerating polyester qualification timelines across European hospital procurement networks.
- Polypropylene:Cost-optimized extrusion output serves agricultural netting and non-critical consumer applications where tensile requirements moderate. India's PLI scheme for technical textiles is incentivizing domestic polypropylene capacity for geotextile markets.
- PVA:Water-soluble polyvinyl alcohol monofilament enables temporary surgical applications and specialized packaging where controlled dissolution proves critical. Japanese industrial fishing fleets are piloting PVA-based biodegradable alternatives under METI sustainability guidelines.
Nylon handles the majority of throughput; polyester is expanding most quickly on share as medical mesh applications multiply.
Technology:
Process selection separates precision medical-grade suppliers from commodity extruders on certification burden and capital intensity.
- Extrusion:Single-screw and twin-screw melt extrusion forms the dominant process position, enabling continuous fiber production with diameter control to ±0.001 mm. Real-time diameter monitoring systems are embedding into medical-grade lines to satisfy FDA 21 CFR traceability requirements for implantable materials.
- Braiding:Multi-axis braiding integrates monofilament into multifilament surgical sutures and high-strength industrial ropes. Swiss and US cardiovascular device manufacturers are qualifying automated braiding lines where diameter consistency impacts catheter deliverability.
- Injection Molding:Limited monofilament applications include precision-molded connector components and specialized medical device fittings requiring complex geometries.
- Winding:Post-extrusion spooling and tension-controlled winding systems determine yield rates for ultra-fine medical grades and bulk fishing line packaging.
Extrusion commands the installed equipment base; braiding is climbing the fastest as surgical suture manufacturers automate multifilament construction.
End Use Industry:
Customer concentration varies sharply between fragmented consumer markets and consolidated hospital procurement networks.
- Medical Devices:Implantable sutures, cardiovascular guidewires, and surgical mesh demand ISO 13485-certified production with 18-24 month qualification timelines. Three US national purchasing organizations now control the majority of synthetic absorbable suture volume, compressing margins for suppliers lacking FDA 510(k) portfolios.
- Fishing:Recreational and commercial line producers face EPA microplastic discharge guidelines forcing reformulation with accelerated degradation additives. Washington and California regulators are advancing the strictest implementation timelines for freshwater biodegradation validation.
- Aquaculture:Netting and cage applications require UV-stabilized grades with 5-10 year service life in marine environments.
- Sporting Goods:Tennis racket strings and specialized equipment components utilize high-modulus monofilament with customized elasticity profiles.
Medical Devices generates the highest margin per kilogram; Fishing moves the largest absolute tonnage.
Application:
Functional requirements dictate polymer selection and certification tier across wound closure, marine equipment, and structural mesh.
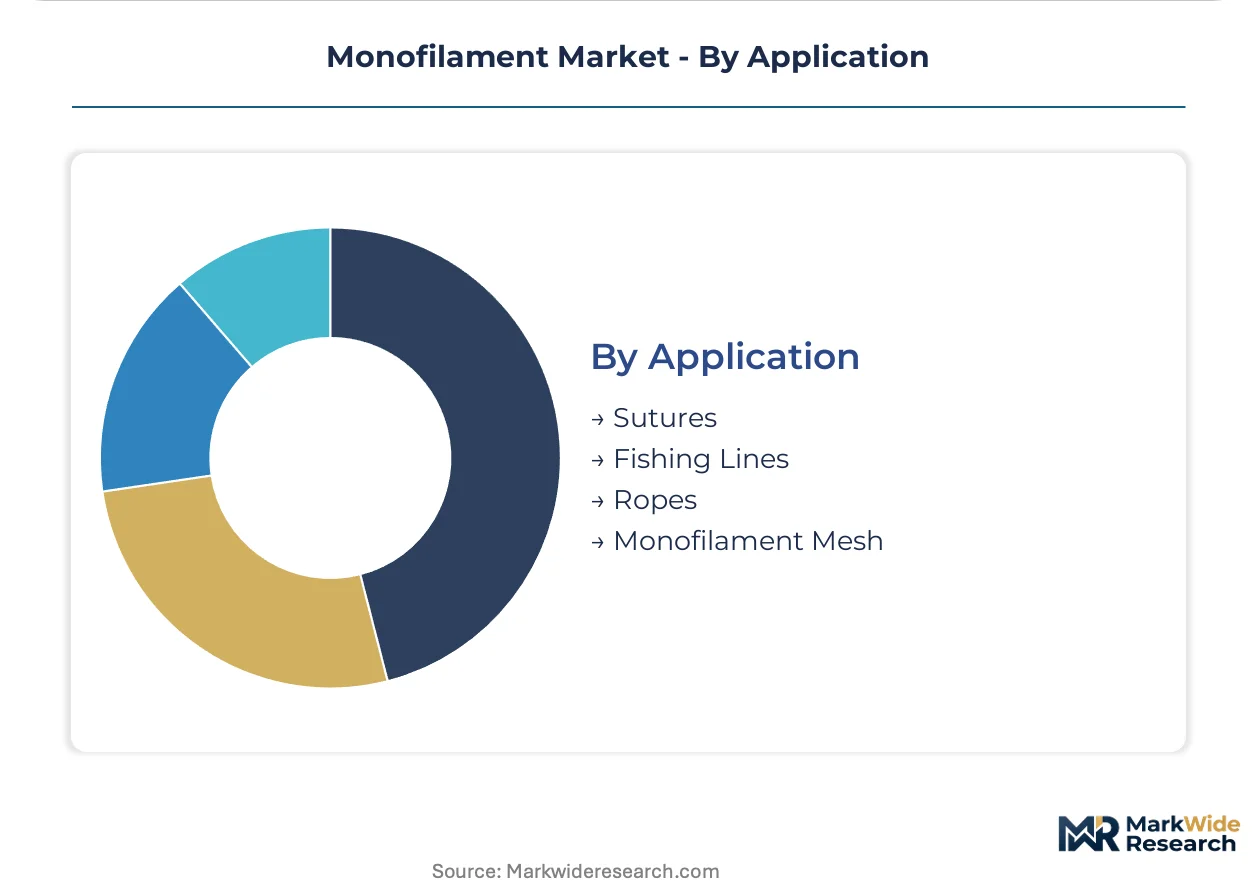
- Sutures:Absorbable and non-absorbable monofilament configurations serve distinct surgical procedures with specific degradation profiles. Hospital procurement consortia are consolidating vendor panels and displacing fragmented distributor networks with direct GPO contracts.
- Fishing Lines:Copolymer and fluorocarbon formulations compete on castability, abrasion resistance, and knot strength in recreational and commercial segments. Shakespeare Company LLC anchors North American demand through proprietary formulations.
- Monofilament Mesh:Hernia repair and pelvic floor reconstruction applications require permanent implant-grade polyester with pore architecture optimized for tissue integration.
- Ropes:Industrial and marine rope applications utilize braided monofilament constructions where tensile strength and fatigue resistance prove critical.
Sutures command premium pricing; Fishing Lines absorb the greatest raw material volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in agricultural and consumer fishing segments exhibit acute price sensitivity, while medical device OEMs absorb substantial premiums for implant-grade certification and traceability compliance.
United States
Cardiovascular guidewire manufacturers in Minnesota and Massachusetts drive demand for ultra-fine diameter nitinol-coated monofilament with sub-0.10 mm tolerances. FDA 21 CFR sterilization standards and 510(k) predicate device requirements extend qualification timelines to 18-24 months for new suppliers. The Greater Boston medical device cluster concentrates angioplasty catheter OEM procurement, with three national purchasing organizations now controlling the majority of synthetic absorbable suture volume.
Germany
Industrial rope and automotive textile applications sustain steady consumption of high-tenacity polyamide grades across the Ruhr industrial belt. EU MDR biocompatibility testing protocols and REACH substance restrictions elevate compliance costs for medical-grade extruders serving European hospital networks. The Stuttgart region hosts precision extrusion specialists supplying braided monofilament constructions for minimally invasive surgical instruments.
China
Domestic fishing line producers in Zhejiang and Shandong provinces are retrofitting extrusion capacity to process bio-based polyamides under the national dual carbon goals framework. The country's national pharmaceutical regulator enforces evolving sterilization standards for implantable device materials that increasingly mirror FDA technical requirements. The Yangtze River Delta concentrates technical textile manufacturing, with local producers capturing government incentives for geotextile and agro-mesh qualification.
India
Cost-optimized polypropylene output for agricultural netting and non-critical consumer applications dominates volume throughput in Gujarat and Maharashtra. The national manufacturing promotion framework offers production-linked incentives for technical textiles, incentivizing domestic monofilament capacity expansion for geotextile markets. The Ahmedabad-Vadodara industrial corridor hosts extrusion specialists competing on scale economies for commodity-grade mesh applications.
Japan
Industrial fishing fleet operators in Shimizu and Yaizu are piloting closed-loop take-back programs for spent nylon line under METI sustainability guidelines. JIS standards for marine equipment materials constrain formulation choices for UV-stabilized grades requiring 5-10 year service life. The Nagoya industrial zone concentrates precision polymer processing, with local suppliers integrating real-time diameter monitoring systems for medical-grade certification.
Monofilament Market Competitive Environment
Capability concentration sits with polymer science specialists commanding aerospace and medical certification tiers; scale advantage sits with commodity extruders serving agricultural and consumer fishing volumes. The vendor base stratifies across three functional archetypes: integrated polymer producers with captive resin supply, precision extrusion houses with ISO 13485 medical qualifications, and regional commodity specialists competing on unit economics. Dominant competitive moves include backward integration into specialty resin compounding and geographic expansion through distributor network consolidation in emerging technical textile markets.
Within the integrated polymer producer tier, Toray Industries Inc. and Ascend Performance Materials exemplify capability concentration through polymer science depth. Among regional commodity specialists, Hinafil India Ltd occupies a position representing cost-optimized scale play for agricultural applications. Shakespeare Company LLC anchors the consumer fishing segment archetype through proprietary formulation heritage. These three company profiles illustrate the structural divergence between premium-tier certification holders and volume-driven commodity competitors.
| Leading Market Players |
|---|
| Superfil Products Ltd |
| Shakespeare Company LLC |
| Toray Industries Inc. |
| Ascend Performance Materials |
| Ruichang Monofilament |
| Ashley Polymers Inc. |
| Engineered Monofilaments Corporation |
| Hinafil India Ltd |
| Perlon GmbH |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight volatility amplifies margin divergence between medical-grade extruders and commodity suppliers, compressing economy-tier pricing while premium certification tiers absorb logistics premiums through long-term offtake contracts.
Pricing Analysis
Aftermarket technical support and filament recycling services generate lifetime value multiples exceeding raw material margins. Three-tier pricing structure across implant-grade, industrial-performance, and commodity-economy levels separates ISO 13485-certified medical output from agricultural mesh grades. Pricing pressure stems from recycled PET fiber substitution in non-critical netting applications. Hospital procurement consortia exhibit lowest price sensitivity; agricultural buyers in India and China drive hardest unit-cost negotiations.
Supply Chain Analysis
Contract manufacturing concentration sits with Ascend Performance Materials, Toray Industries, and regional Chinese extruders operating dedicated medical-grade cleanrooms. Raw material supply draws from benzene-derived caprolactam naphtha chains in the US Gulf Coast, purified terephthalic acid feedstocks in South Korea, and bio-based polyamide pilot streams in China. Single-source vulnerability concentrates in aerospace-grade resin compounding. Distribution runs through direct GPO contracts for medical devices and fragmented distributor networks for consumer fishing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Monofilament market fragmentation creates niche opportunities as hospital procurement consortia displace fragmented distributor networks with direct contractual relationships.
For Market Incumbents: Insulate implantable-device revenue streams by deepening backward integration into specialty resin compounding and accelerating EU MDR biocompatibility certification timelines. Counter recycled PET substitution threats in agricultural netting by qualifying closed-loop recycling service contracts that bypass virgin resin commodity cycles.
For New Entrants and Emerging Players: India's technical textile underpenetration offers white-space capture through PLI scheme qualification for geotextile and agro-mesh applications. Target cardiovascular guidewire supply gaps in Germany's Stuttgart precision extrusion cluster. Pursue direct GPO contracting routes rather than distributor intermediation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with undermonetized medical-grade monofilament divisions lacking ISO 13485 certification depth. Long-term viability hinges on implantable-device traceability compliance rather than commodity volume scale. Monitor FDA 510(k) predicate device portfolio expansion as inflection signal for margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Compounding | Captive supply of aerospace-grade polyamide secures margin pools beyond commodity extrusion. |
| EU MDR Biocompatibility Certification Investment | Accelerated qualification timelines unlock European hospital procurement network access. |
| Closed-Loop Recycling Infrastructure Deployment | Japanese fishing fleet take-back programs create service revenue bypassing virgin resin cycles. |
| Real-Time Diameter Monitoring System Integration | Swiss and US cardiovascular OEMs qualify sensor-augmented lines for catheter deliverability. |
| Direct GPO Contracting Route Establishment | Three US national purchasing organizations consolidate synthetic absorbable suture vendor panels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across extrusion plant managers, hospital GPO contracts managers, biomedical engineers at cardiovascular OEMs, and agricultural mesh procurement leads. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, EPA microplastic discharge guidelines, and customs trade data for caprolactam and PTA feedstocks. Bottom-up capacity assessments and top-down demand modeling were triangulated.
Calibration anchored volume and value outputs across polymer chemistry tiers, end-use industry verticals, and regional regulatory clusters. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs included angioplasty guidewire demand trajectories and bio-based polyamide adoption curves under China's dual carbon framework.
Practitioners should monitor REACH substance restriction expansions, state-level packaging waste mandates, and polymer traceability requirements for early signals of sourcing strategy disruption. Quarterly review of caprolactam price volatility, FDA sterilization standard revisions, and hospital procurement consortium vendor panel rotations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Synthetic Textile Fiber Market
Synthetic Fibers
Polyester Staple Fiber Market
Synthetic Fibers
Fiberglass Roving Market
Synthetic Fibers
Synthetic Sewing Thread Market
Synthetic Fibers
Global Lyocell Fibers Market
Synthetic Fibers
US Textile Market
Synthetic Fibers
Modacrylic Fiber Market
Synthetic Fibers
Synthetic Fiber Market
Synthetic Fibers
Sic Fibers Market
Synthetic Fibers
Nanofibers Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
North America High Performance Fibers Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Spandex Market
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Polypropylene Fiber Market