
 Europe Thermoplastics Market | 2026-2036
Europe Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Thermoplastics Market Foresight
Automotive OEMs is recalibrating material specifications across vehicle platforms, pushing thermoplastics deeper into structural and interior applications. BASF SE leverages its integrated polyamide and polypropylene compounds portfolio to supply lightweighting solutions for electric vehicle battery housings. Covestro AG specializes in high-performance polycarbonate blends that sustain optical clarity and impact resistance for headlamp lenses and display covers. Evonik Industries AG anchors its position through specialty polyamides designed for thermal management in powertrain systems.
Thermoplastics are polymers that soften upon heating and solidify when cooled, enabling repeated melt-processing through injection molding, extrusion, or blow molding without chemical degradation. Their molecular structure lacks cross-linked bonds, which permits regrind and recycling while delivering tunable mechanical properties from flexible polyethylene to rigid polystyrene. Polyethylene and polypropylene dominate volume flows across Europe, with polypropylene capturing expanding share in automotive underhood applications due to its heat resistance and density advantages. PVC maintains entrenched positions in construction piping and medical tubing where long certification cycles protect incumbent supply relationships. Injection molding commands the largest application share by value, though 3D printing filaments represent the fastest-growing processing outlet as aerospace and medical device producers adopt fused deposition modeling for end-use parts.
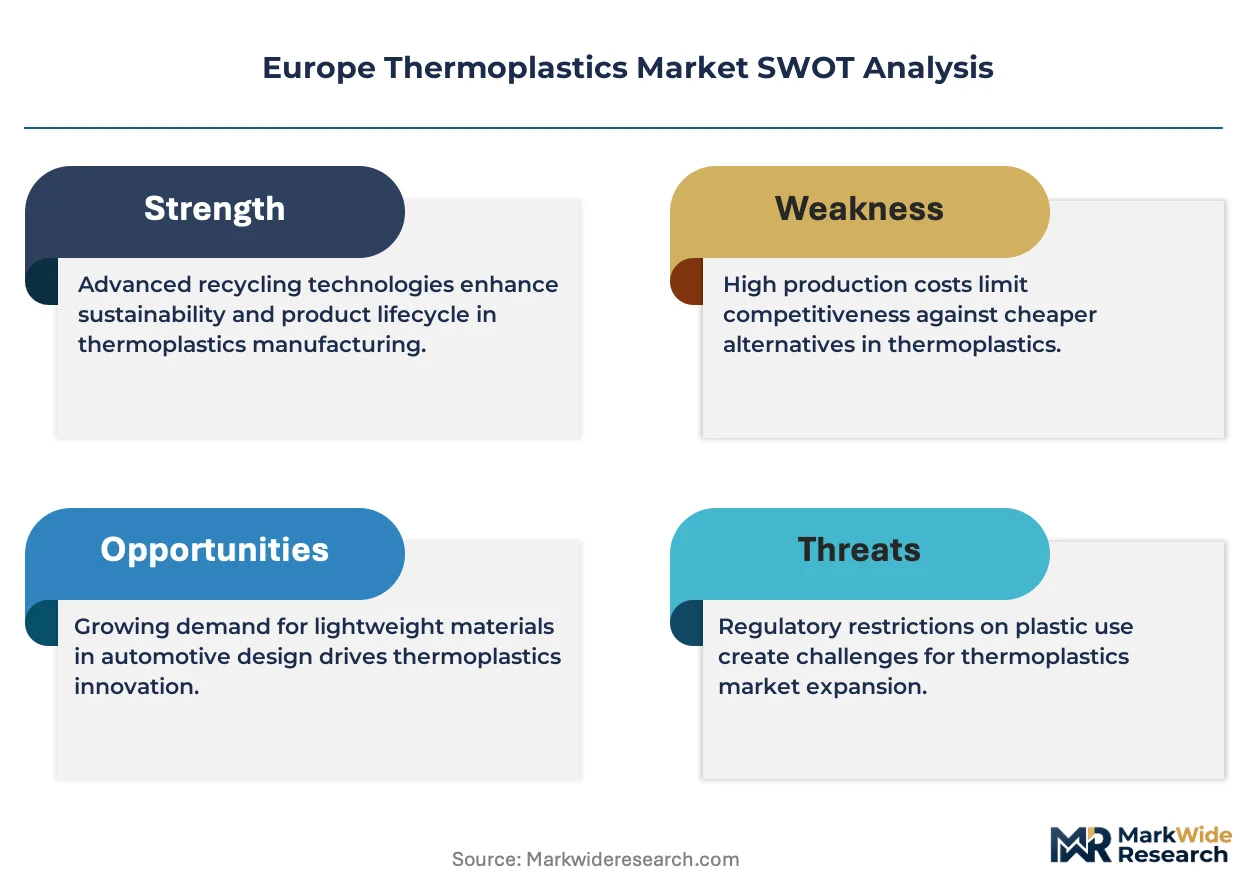
REACH registration requirements and the EU Green Deal carbon border adjustments are reshaping feedstock sourcing decisions across European resin producers. ECHA substance restrictions on phthalate plasticizers and persistent organic pollutants are forcing PVC and flexible compound reformulations, while CE marking under the Construction Products Regulation governs thermoplastic pipe and insulation approvals. Stakeholders must monitor how the EU F-Gas Regulation and upcoming packaging waste directives alter demand for fluoropolymer alternatives and single-use plastic substitutions.
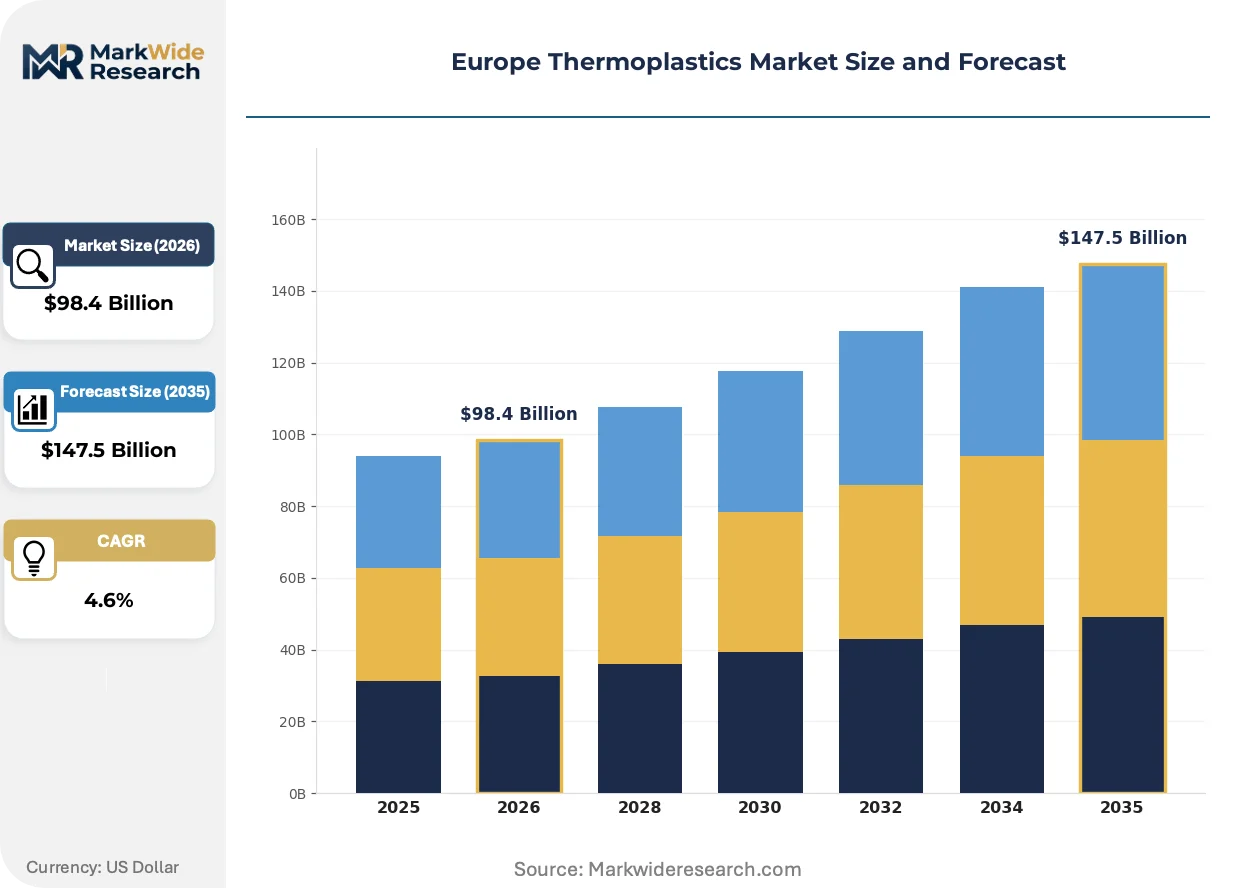
Market Dynamics
REACH substance restrictions and the EU Green Deal carbon border adjustments are forcing European resin producers to reconfigure feedstock sourcing and accelerate substitution of conventional polymers with recyclable alternatives across automotive and packaging value chains.
Growth Catalysts
- EU Green Deal carbon border mechanisms:Importers face escalating compliance costs on carbon-intensive materials, redirecting procurement toward low-carbon polypropylene and bio-based polyethylene compounds produced within the European Economic Area.
- Automotive lightweighting mandates:OEMs redesigning vehicle platforms to meet EU emissions targets specify glass-filled polyamide for battery housings and structural brackets, displacing metal stampings in electric vehicle architectures.
- Packaging waste directive revisions:Extended producer responsibility schemes and single-use plastic bans concentrate demand for mechanically recycled polyethylene terephthalate in food-contact applications across German and French retail supply chains.
Market Restraints
- Naphtha and natural gas price volatility:European crackers depend on North Sea and Norwegian gas supplies subject to geopolitical disruption, compressing resin producer margins during feedstock price spikes.
- Specialty additive supply concentration:Flame retardants and heat stabilizers for engineering thermoplastics concentrate among Chinese and German chemical suppliers, exposing compounders to single-source risk during logistics disruptions.
- Mechanical recycling performance ceiling:Reprocessed polypropylene and polyethylene suffer property degradation after multiple heat histories, limiting closed-loop adoption in automotive safety-critical applications.
Strategic Opportunities
- Chemical recycling infrastructure gaps:Spain and Poland lack pyrolysis capacity relative to waste plastic generation, creating first-mover advantages for integrated resin producers building molecular recycling plants.
- Thermoplastic composites in renewable energy:Wind turbine blade manufacturers test unidirectional glass-reinforced polyamide tapes as recyclable alternatives to thermoset epoxy, opening volume outlets outside traditional automotive and packaging.
- Digital product passport mandates:The Ecodesign for Sustainable Products Regulation will require granular material traceability, rewarding compounders with blockchain-enabled supply chain documentation.
Industry Challenges
- Polymer process engineering talent scarcity:European universities produce insufficient injection molding and extrusion specialists to staff recycling facility expansions planned through 2030.
- CE marking timeline compression:Construction product regulations require multi-year fire resistance and mechanical testing for thermoplastic pipe and insulation, delaying market entry against incumbent PVC and polyethylene suppliers.
- Legacy ERP integration with mass balance accounting:Producers adopting ISCC PLUS certification for bio-attributed polymers face data architecture costs reconciling physical and certificate-based material flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Thermoplastics Market |
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $147.5 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, PVC End User: Automotive OEMs, Packaging, Construction, Electronics Application: Injection Molding, Extrusion, Blow Molding, 3D Printing Size: Small Scale, Medium Scale, Large Scale, Custom Size |
| Companies Covered | BASF SE, Covestro AG, Evonik Industries AG, INEOS AG, DSM, Arkema, LyondellBasell Industries Holdings B.V., LANXESS, SABIC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Thermoplastics Market Shifts & Advancements
Material science breakthroughs and regulatory digitization are converging to transform how European thermoplastics are formulated, validated, and traced through circular value chains.
Advanced compatibilization chemistry is rewriting the technical and economic boundaries of mixed-polymer recycling. Reactive extrusion systems employing maleic anhydride grafting and ionomeric modifiers now blend contaminated polyethylene-polypropylene streams into specification-grade compounds. Compounders in Belgium and the Netherlands deploy these systems at commercial scale, supplying automotive interior panels that previously required virgin resin.
The EU F-Gas Regulation phase-down is compressing demand for fluoropolymer process aids and refrigerant tubing while accelerating substitution with high-performance polyamides and thermoplastic elastomers. Extrusion houses serving HVAC and medical device sectors reformulate compounds to eliminate perfluorinated additives ahead of 2030 bans. German automotive suppliers now qualify polyphenylene sulfide for underhood thermal management applications previously reserved for polytetrafluoroethylene-lined components.
Automotive OEMs now mandate recycled content certificates with mass balance chain-of-custody documentation, displacing spot-market resin purchasing with long-term offtake contracts tied to specific recycling facilities. Tier-1 suppliers in Stuttgart and Turin restructure procurement organizations to audit reprocessor feedstock sources directly. This verification-driven sourcing concentrates volume among integrated compounders with captive mechanical and chemical recycling assets.
Europe Thermoplastics Market Segmentation
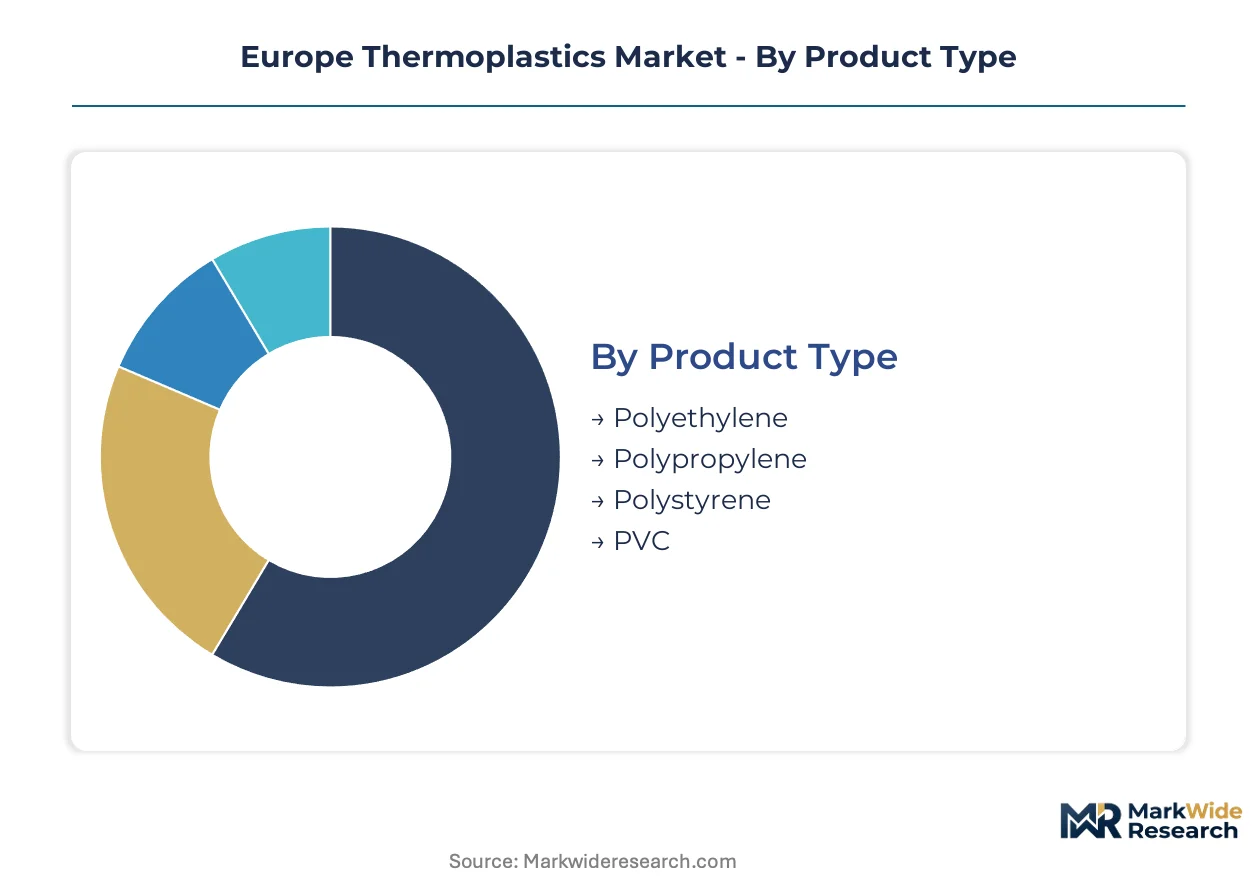
Segmentation reveals how EU Green Deal compliance and automotive lightweighting mandates concentrate demand across distinct polymer grades and processing methods. Buyers prioritize heat resistance specifications in electric vehicle applications and recyclability credentials in packaging procurement.
Product Type:
Material selection hinges on density-to-performance ratios and REACH registration status for downstream certification.
- Polyethylene:Linear low-density formulations dominate flexible packaging films and agricultural mulch across French and German retail supply chains. Brand owners specify mechanically recycled grades to satisfy extended producer responsibility schemes.
- Polypropylene:Glass-filled and mineral-reinforced compounds penetrate automotive underhood components and battery housings as OEMs displace metal stampings. Heat resistance up to 150°C enables charge port and inverter applications.
- Polystyrene:Expandable grades insulate construction panels in Polish and Romanian building retrofits; crystal grades serve medical device housings requiring gamma sterilization compatibility.
- PVC:Rigid formulations maintain entrenched positions in German drainage piping and Italian window profiles where multi-decade certification cycles protect incumbent supply relationships.
Polyethylene leads on scale; polypropylene leads on momentum.
End User:
Procurement sophistication varies sharply across buyer categories, with automotive and packaging sectors driving specification innovation.
- Automotive OEMs:Battery electric platform redesigns specify polyamide and polypropylene compounds for structural brackets and thermal management housings. Stuttgart and Turin engineering centers mandate mass balance chain-of-custody documentation.
- Packaging:German and French retailers concentrate demand for food-contact compliant recycled polyethylene terephthalate. Single-use plastic bans accelerate substitution with mechanically recycled alternatives.
- Construction:CE marking requirements under the Construction Products Regulation govern thermoplastic pipe and insulation approvals, compressing market entry timelines for new resin formulations.
- Electronics:Flame-retardant polycarbonate blends serve laptop housings and connector components; halogen-free specifications spread under RoHS amendments.
Packaging leads on volume velocity; automotive leads on value capture.
Application:
Processing method determines capital equipment requirements and scrap recycling economics for compounders.
- Injection Molding:Multi-cavity tooling produces automotive interior panels and medical device components with tight dimensional tolerances. Robotic automation reduces cycle times in high-volume Belgian and Dutch facilities.
- Extrusion:Twin-screw systems compound glass-reinforced polypropylene for construction profiles and cable jacketing. Die design expertise concentrates among German and Austrian equipment suppliers.
- Blow Molding:High-density polyethylene fuel tanks and industrial drums sustain demand in logistics and agricultural chemical packaging.
- 3D Printing:Fused deposition modeling filaments represent the steepest expansion trajectory as aerospace and medical device producers qualify end-use polymer parts.
Injection molding leads on installed base; 3D printing leads on growth slope.
Size:
Production scale dictates reactor technology choice and logistics optimization for resin producers.
- Small Scale:Batch reactors serve specialty polyamide and thermoplastic elastomer compounds for medical tubing and connector applications.
- Medium Scale:Modular extrusion lines supply regional automotive Tier-1 clusters in Spain and Eastern Europe with just-in-time delivery.
- Large Scale:World-scale crackers in Rotterdam and Antwerp feed continuous polypropylene and polyethylene streams to pan-European distribution networks.
- Custom Size:Toll compounders blend color concentrates and additive packages for brand-owner proprietary specifications in packaging and consumer goods.
Large scale leads on throughput; custom size leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage across the European Economic Area intensifies as REACH compliance costs and carbon border adjustments reshape where resin compounders locate capacity. German producers absorb regulatory premiums through scale economies while Spanish and Polish operators exploit infrastructure gaps to capture chemical recycling first-mover positions.
Germany
Automotive OEMs in Stuttgart and Munich drive specification-grade polyamide demand for electric vehicle battery housings and thermal management systems. The KBA enforces stringent material traceability requirements under the EU Green Deal implementation framework. The Rhine-Ruhr chemical cluster hosts integrated crackers supplying pan-European distribution networks with low-carbon polypropylene compounds.
France
Packaging converters in the Île-de-France region concentrate procurement of mechanically recycled polyethylene terephthalate for food-contact retail applications. ANSM oversees medical-grade thermoplastic certifications for device housings and tubing. The Lyon chemical corridor sustains specialty polyamide production for aerospace connector applications.
Italy
Tier-1 automotive suppliers in Turin restructure procurement organizations to audit reprocessor feedstock sources directly under mass balance chain-of-custody mandates. CE marking requirements under the Construction Products Regulation protect incumbent PVC window profile manufacturers in the Po Valley. Milan-based compounders blend color concentrates for brand-owner proprietary packaging specifications.
Netherlands
Rotterdam-Antwerp crackers feed continuous polyethylene and polypropylene streams to compounders deploying reactive extrusion systems for mixed-polymer recycling. The Dutch national implementation of extended producer responsibility schemes concentrates mechanically recycled resin demand. Eindhoven-region toll compounders serve just-in-time automotive interior panel contracts.
Spain
Pyrolysis capacity lags waste plastic generation across Catalonia and the Basque Country, creating entry opportunities for integrated resin producers building molecular recycling infrastructure. Spanish construction retrofits sustain expandable polystyrene insulation demand under national building efficiency programs. Barcelona packaging converters qualify chemically recycled alternatives ahead of single-use plastic directive deadlines.
Europe Thermoplastics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin producers commanding premium positions in automotive specification-grade compounds while toll compounders capture margin in custom color and additive blending. The market structure tiers into world-scale crackers with captive polymerization assets, regional compounders with modular extrusion flexibility, and specialty additive houses protecting formulation intellectual property. Dominant competitive moves center on backward integration into pyrolysis and mechanical recycling feedstocks, alongside long-term offtake contracts tied to mass balance certification schemes.
Within the integrated chemical archetype, BASF SE and Covestro AG anchor positions through diversified polymer portfolios spanning commodity polyethylene to engineering-grade polycarbonates. Evonik Industries AG exemplifies the specialty additive and high-performance compound tier. These three German-headquartered operators represent distinct strategic postures: scale-driven resin production, performance polymer differentiation, and niche formulation expertise respectively.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Evonik Industries AG |
| INEOS AG |
| DSM |
| Arkema |
| LyondellBasell Industries Holdings B.V. |
| LANXESS |
| SABIC |
| Others |
Supply & Pricing Matrix
Captive pyrolysis investments by integrated resin producers in Rotterdam and Antwerp anchor both supply security and pricing power across specification-grade polyamide and polypropylene compounds. This backward integration into molecular recycling feedstocks insulates compounders from naphtha price spikes while commanding premium positions in automotive mass balance-certified procurement.
Pricing Analysis
Distributor margins on commodity polyethylene and polypropylene compress as direct-to-OEM contracts for specification-grade compounds expand. Three-tier pricing structure across premium engineering thermoplastics, standard injection molding grades, and economy bulk resins stratifies by REACH registration status and carbon intensity certification. Cost compression in commodity tiers intensifies because of volatile North Sea naphtha feedstock costs. Packaging converters exhibit highest price sensitivity, while automotive Tier-1 suppliers prioritize traceability credentials over unit economics.
Supply Chain Analysis
EU Green Deal domestic-content mandates for low-carbon polymers are reshaping sourcing toward European Economic Area production. Supply concentrates in Germany, Belgium, and the Netherlands, with Rotterdam-Antwerp crackers feeding continuous polyethylene and polypropylene streams. Raw material dependencies center on North Sea natural gas, Norwegian naphtha, and imported flame retardant additives from Chinese suppliers. Single-source vulnerability in specialty heat stabilizers exposes compounders to logistics disruption. Distribution runs through pan-European polymer distribution networks with just-in-time delivery to automotive clusters in Stuttgart and Turin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European production and lower-cost but carbon-intensive import alternatives, with carbon border adjustments compressing the cost differential.
For Market Incumbents: Lock in long-term offtake contracts with automotive OEMs requiring mass balance chain-of-custody documentation before pyrolysis capacity saturates. Deepen backward integration into Spanish and Polish chemical recycling infrastructure to capture first-mover rents. Prioritize ISCC PLUS certification investment to defend margin position against emerging bio-attributed resin competitors. For New Entrants and Emerging Players: Reactive extrusion compatibilization technology offers a technology-first wedge into mixed-polymer recycling previously uneconomical for mechanical reprocessors. Target underpenetrated construction profiles in Polish and Romanian building retrofits where CE marking timelines protect incumbent PVC relationships less aggressively. Pursue toll-compounding partnerships with Milan-based color concentrate specialists to bypass world-scale cracker capital requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with modular extrusion flexibility because automotive procurement consolidation is concentrating volume among integrated suppliers with captive recycling assets. Focus acquisition screening on Belgian and Dutch operators deploying reactive extrusion systems at commercial scale. Monitor EU F-Gas Regulation implementation as inflection indicator for fluoropolymer substitution demand accelerating polyphenylene sulfide and high-performance polyamide adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis | Captive molecular recycling feedstock secures mass balance certification for automotive OEM contracts under EU Green Deal compliance. |
| ISCC PLUS Certification Investment | Blockchain-enabled supply chain documentation satisfies Ecodesign for Sustainable Products Regulation digital product passport mandates. |
| Reactive Extrusion Capacity Expansion | Advanced compatibilization chemistry unlocks specification-grade compounds from contaminated polyethylene-polypropylene waste streams. |
| Long-term Automotive Offtake Agreements | Direct procurement relationships with Stuttgart and Turin engineering centers displace spot-market resin purchasing. |
| Joint Venture in Chemical Recycling Infrastructure | Spanish and Polish pyrolysis gaps create first-mover advantages for integrated producers building molecular recycling plants. |
Research Methodology
Direct dialogue with resin plant managers, automotive Tier-1 procurement leads, packaging converter technical directors, and ECHA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from Cefic industry statistics, Eurostat trade flow data, SEC filings of listed chemical producers, and EU official journal regulatory texts. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with macroeconomic demand modeling across polymer grades and end-use applications.
Bottom-up volume modeling built from named cracker capacities, operating rate assumptions, and derivative compounder throughput estimates, while top-down demand aggregation synthesized automotive production forecasts and packaging waste directive implementation timelines. Segmentation dimensions spanned polymer chemistry, processing method, end-use industry, and regional production hub clustering. CAGRs derived from regression analysis of historical price-volume relationships and elasticity-adjusted demand projections across the analysis window. Key inputs included electric vehicle platform rollout schedules and extended producer responsibility scheme enforcement calendars.
The model holds under stable REACH substance restriction timelines and predictable EU carbon border adjustment phase-in; deviation in geopolitical disruption of North Sea gas supplies or accelerated F-Gas Regulation bans would shift compounder feedstock economics and substitution trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Bio-Based Polypropylene Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Global Unsaturated Polyester Resins Market