
 Poly Alpha Olefin (PAO) Market | 2026-2036
Poly Alpha Olefin (PAO) Market Size, Share, and Industry Trends Forecast 2026-2036
Poly Alpha Olefin (PAO) Market Analytics
Synthetic ester is expanding its share in high-performance lubricant formulations, displacing mineral oil in electric vehicle thermal management fluids. ExxonMobil Chemical leverages integrated alpha-olefin feedstock positions to anchor North American supply security. INEOS competes through European cracking and polymerization assets. Chevron Phillips Chemical specializes in metallocene-catalyzed PAO grades for aerospace specifications.
Poly Alpha Olefin denotes a synthetic hydrocarbon base stock polymerized from linear alpha-olefins, typically 1-decene, yielding defined viscosity indices exceeding 140 and pour points below minus 40 degrees Celsius for extreme-temperature lubrication. Low molecular weight PAO dominates automotive engine oil volumes, while specialty PAO commands margin pools in aerospace and precision industrial applications. Medium molecular weight grades sustain growth in wind turbine gearbox fluids where oxidative stability requirements exceed mineral oil capabilities.
EPA fuel economy standards and the EU Green Deal's industrial emissions targets tighten lubricant performance benchmarks, accelerating PAO substitution for Group I and II base oils. China's MIIT publishes GB standards for new energy vehicle coolants that reference synthetic base stock compatibility. Stakeholders must monitor regulatory divergence between California's Air Resources Board protocols and emerging EU Ecodesign requirements for lubricant biodegradability.
Market Dynamics
The shift from mineral-based to synthetic lubricant formulations is compressing demand cycles for Group I and II base oils while elevating factory-fill specifications across automotive original equipment manufacturers.
Growth Catalysts
- EU F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon refrigerants redirects capital toward lower-viscosity synthetic base stocks compatible with next-generation thermal management systems.
- Electric vehicle powertrain thermal fluids:Battery and e-motor cooling architectures require oxidative stability beyond mineral oil capabilities, pulling PAO into factory-fill specifications for premium battery electric platforms.
- Germany's automotive engineering clusters:Dense concentrations of powertrain R&D facilities and additive blending infrastructure anchor regional procurement gravity for high-viscosity-index base stocks.
Market Restraints
- 1-decene feedstock concentration:Linear alpha-olefin supply chains concentrate among integrated petrochemical producers, exposing compounders to ethylene-cracking economics and olefin allocation decisions.
- REACH registration burdens:The European Chemicals Agency's substance evaluation protocols extend lead times for new PAO grades entering lubricant formulations, compressing formulation refresh cycles.
- Group III+ base oil substitution:Severely hydrocracked mineral oils achieve viscosity indices above 120 at substantially lower cost, constraining PAO penetration in mid-tier automotive service-fill segments.
Strategic Opportunities
- Wind turbine gearbox fluids:Offshore wind installations in the North Sea and Baltic regions specify 10,000-hour oxidation stability that only synthetic hydrocarbons deliver, opening premium volume pools.
- China's MIIT GB standards:New energy vehicle coolant regulations referencing synthetic base stock compatibility create formulation specification windows for PAO producers with local technical service presence.
- Metallocene catalyst convergence with molecular distillation:Advanced polymerization control enables tailored viscosity grades for aerospace hydraulic specifications previously served by ester chemistry.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required to balance PAO-ester-polyalkylene glycol triblends for electric vehicle thermal management outpaces technical training pipeline output.
- OEM factory-fill certification timelines:Volkswagen, BMW, and Mercedes-Benz qualification protocols demand 24-36 month field trials, locking out new entrants and freezing specification windows.
- California Air Resources Board divergence:CARB's lubricant biodegradability protocols create compliance complexity distinct from EU Ecodesign requirements, forcing dual-track formulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly Alpha Olefin (PAO) Market |
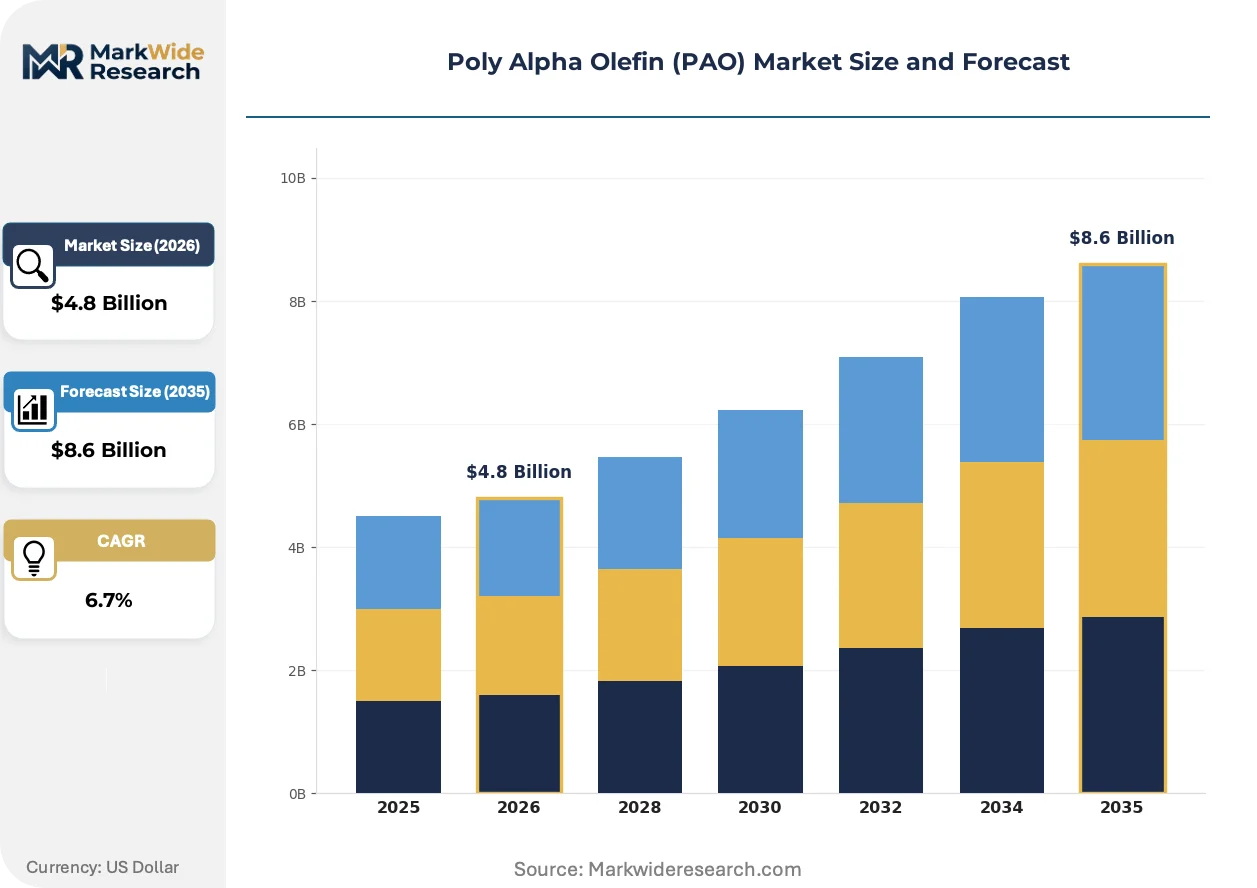
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Molecular Weight, High Molecular Weight, Medium Molecular Weight, Specialty PAO End Use Industry: Automotive, Aerospace, Oil & Gas, Industrial Application: Lubricants, Coatings, Adhesives, Sealants Form: Liquid, Solid, Gel, Powder |
| Companies Covered | Lanxess, Shanxi Lu'an Carbon One Chemical Co., Ltd, INEOS, Dowpol Chemical International, TAIF Lubricants, ExxonMobil Chemical, Sinopec Maoming Petrochemical Company, Lanzhou PetroChina Lubricant Additive Co., Ltd, Chevron Phillips Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly Alpha Olefin (PAO) Market Evolving Landscape
Formulation science is converging with powertrain electrification to redefine base stock performance benchmarks. Synthetic hydrocarbon architectures now compete directly with ester chemistry in thermal management applications.
Metallocene-catalyzed PAO polymerization is integrating precision molecular weight control into aerospace hydraulic fluid specifications. Boeing and Airbus tier-one suppliers specify these grades for -54°C cold-start performance in high-altitude operations. The technology is integrating into military specification MIL-PRF-87257, compressing qualification timelines for conventional Ziegler-Natta catalyzed alternatives.
REACH authorization lists are tightening restrictions on short-chain chlorinated paraffins and certain boron compounds used in lubricant additives. The European Chemicals Agency's 2023 sunset date for specific substance categories forced reformulation investments across metalworking and automotive lubricant portfolios. German compounders responded fastest, leveraging existing PAO-ester infrastructure to substitute restricted chemistries.
Automotive procurement departments now specify total cost of ownership metrics rather than unit volume pricing for factory-fill contracts. Tier-one lubricant suppliers bundle technical service, used oil analysis, and drain interval optimization into multi-year supply agreements. This behavior is most visible in Nordic markets where fleet operators track total fluid life-cycle costs across severe cold-start duty cycles.
Poly Alpha Olefin (PAO) Market Segmentation
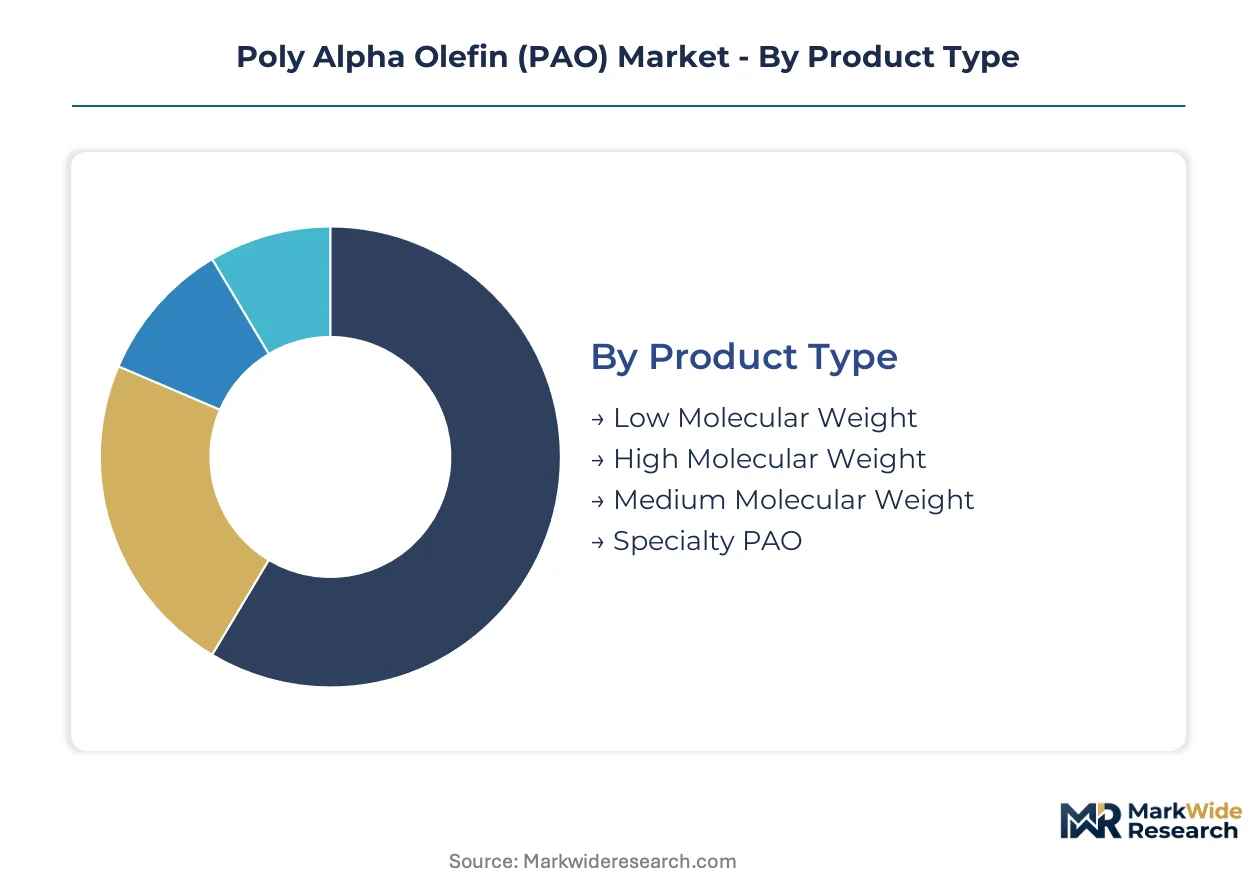
PAO specifications diverge sharply across molecular architectures and thermal performance envelopes. Formulators select viscosity grades based on oxidative stability demands and cold-flow requirements rather than commodity pricing.
Product Type:
Polymerization control over carbon chain length defines thermal stability limits and low-temperature fluidity.
- Low Molecular Weight:Viscosity grades from 2 to 10 cSt at 100°C dominate automotive engine oil formulations. German OEM factory-fill specifications for passenger car motor oils absorb the majority of volumes.
- High Molecular Weight:Grades exceeding 40 cSt serve industrial gearboxes and compressor lubricants requiring film strength under boundary lubrication conditions. Wind turbine OEMs in Denmark and Germany specify these for 10,000-hour drain intervals.
- Medium Molecular Weight:10-40 cSt grades bridge automotive and industrial applications with balanced pour point and viscosity index performance.
- Specialty PAO:Metallocene-catalyzed grades with tailored molecular weight distribution target aerospace hydraulic specifications and precision instrument lubrication.
Low Molecular Weight leads on scale; Specialty PAO leads on momentum.
End Use Industry:
Performance specifications tighten fastest where thermal management complexity intersects with regulatory compliance.
- Automotive:Battery electric vehicle coolant formulations and internal combustion engine oils drive formulation refresh cycles. China's MIIT GB standards for new energy vehicles reference synthetic base stock compatibility.
- Aerospace:MIL-PRF-87257 and Boeing specification BMS3-32 demand -54°C cold-start performance. Metallocene PAO displaces ester chemistry in hydraulic systems for high-altitude operations.
- Oil & Gas:Subsea production equipment and Arctic drilling operations specify PAO for extreme pressure and temperature cycling.
- Industrial:Compressor and hydraulic fluids in food-grade and cleanroom applications leverage PAO's inert chemical profile.
Automotive dominates volume contribution; Aerospace commands margin expansion.
Application:
Functional requirements determine base stock selection more than feedstock cost considerations.
- Lubricants:Engine oils, gear oils, and hydraulic fluids represent the core demand pool. REACH authorization restrictions on chlorinated paraffins accelerate PAO substitution in metalworking fluids.
- Coatings:Low-viscosity grades serve as film-forming agents in protective coatings requiring UV stability and moisture resistance.
- Adhesives:Tackifier compatibility and oxidative stability position PAO in pressure-sensitive adhesive formulations.
- Sealants:Plasticizer functionality in construction and automotive sealant compounds leverages PAO's chemical inertness.
Lubricants anchor procurement volumes; Coatings exhibit the steepest expansion trajectory.
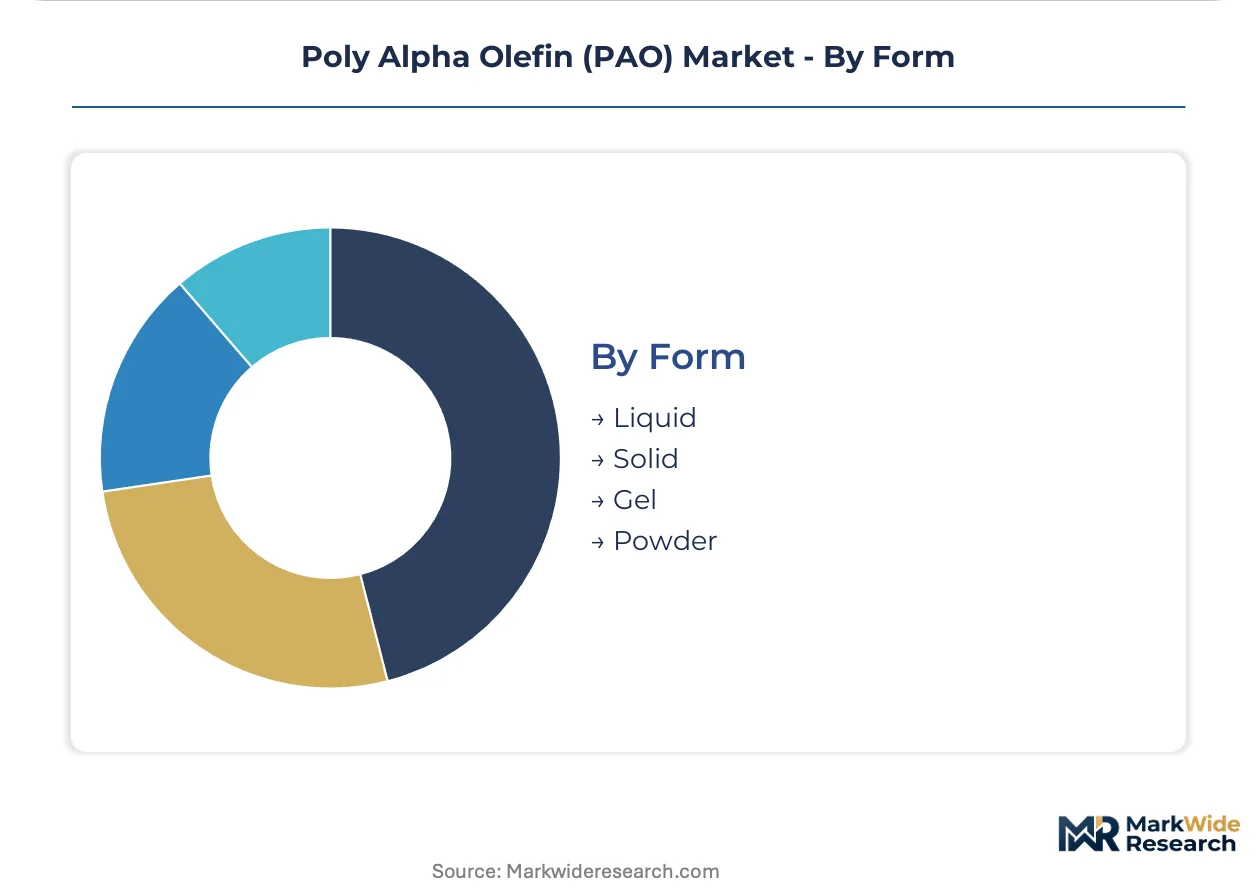
Form:
Physical state determines handling infrastructure and blending compatibility with additive packages.
- Liquid:Standard viscosity grades ship in bulk tankers and drums for direct blending operations. Automotive and industrial lubricant compounders specify liquid delivery for continuous manufacturing.
- Solid:Higher molecular weight grades solidify at ambient temperatures, requiring heated storage and processing equipment.
- Gel:Thickened formulations serve specialty applications in cosmetic and personal care product bases.
- Powder:Spray-dried or micronized forms enable dry lubricant compounding and polymer additive masterbatches.
Liquid form captures operational scale; Powder form shows emerging application diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering clusters anchor procurement gravity for high-viscosity-index base stocks. The country's dense concentrations of powertrain R&D facilities and additive blending infrastructure concentrate European demand for synthetic lubricant formulations.
United States
EPA fuel economy standards tighten lubricant performance benchmarks, accelerating PAO substitution for Group I and II base oils. California's Air Resources Board protocols create compliance complexity distinct from federal requirements. Houston and the Gulf Coast petrochemical corridor host integrated alpha-olefin production assets that supply North American compounders.
China
MIIT publishes GB standards for new energy vehicle coolants that reference synthetic base stock compatibility. The country's dual carbon goals redirect formulation investments toward lower-emission lubricant architectures. Yangtze River Delta automotive clusters in Shanghai and Jiangsu province absorb premium PAO volumes for electric vehicle thermal management fluids.
Japan
METI industrial emissions targets elevate factory-fill specifications for domestic automotive original equipment manufacturers. JIS standards for precision instrument lubrication sustain demand for metallocene-catalyzed specialty grades. Kansai region chemical producers in Osaka and Hyogo prefectures maintain blending infrastructure for aerospace hydraulic specifications.
Saudi Arabia
The country's national petrochemical regulator aligns downstream olefin allocation with synthetic lubricant feedstock security. Cracking and polymerization assets in the Eastern Province supply linear alpha-olefin streams to regional compounders. Jubail Industrial City hosts integrated facilities that anchor Middle Eastern PAO production capacity.
India
BIS lubricant quality standards tighten specifications for automotive and industrial applications. The PLI scheme for advanced chemistry cell manufacturing indirectly elevates thermal fluid performance requirements. Gujarat's chemical manufacturing belt in Vadodara and Surat concentrates domestic blending operations for synthetic base stocks.
Poly Alpha Olefin (PAO) Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated petrochemical producers secure alpha-olefin feedstock positions. The vendor base concentrates among multinational chemical conglomerates with captive ethylene-cracking assets and regional compounders with specialized blending capabilities. Three strategic archetypes emerge: integrated oil majors with upstream olefin control, independent PAO specialists with metallocene technology positions, and regional state-owned enterprises serving domestic formulation markets. Competitive intensity centers on backward integration into linear alpha-olefin supply and geographic expansion into Asian electric vehicle supply chains.
Among integrated majors, ExxonMobil Chemical and Chevron Phillips Chemical exemplify archetypes with Gulf Coast cracking assets and aerospace specification expertise. INEOS occupies a position within European supply security, leveraging Rotterdam and Grangemouth olefin infrastructure. Shanxi Lu'an Carbon One Chemical Co., Ltd represents Chinese state-backed capacity expansion serving domestic automotive formulation demand.
| Leading Market Players |
|---|
| Lanxess |
| Shanxi Lu'an Carbon One Chemical Co., Ltd |
| INEOS |
| Dowpol Chemical International |
| TAIF Lubricants |
| ExxonMobil Chemical |
| Sinopec Maoming Petrochemical Company |
| Lanzhou PetroChina Lubricant Additive Co., Ltd |
| Chevron Phillips Chemical |
| Others |
Value Network & Pricing Analysis
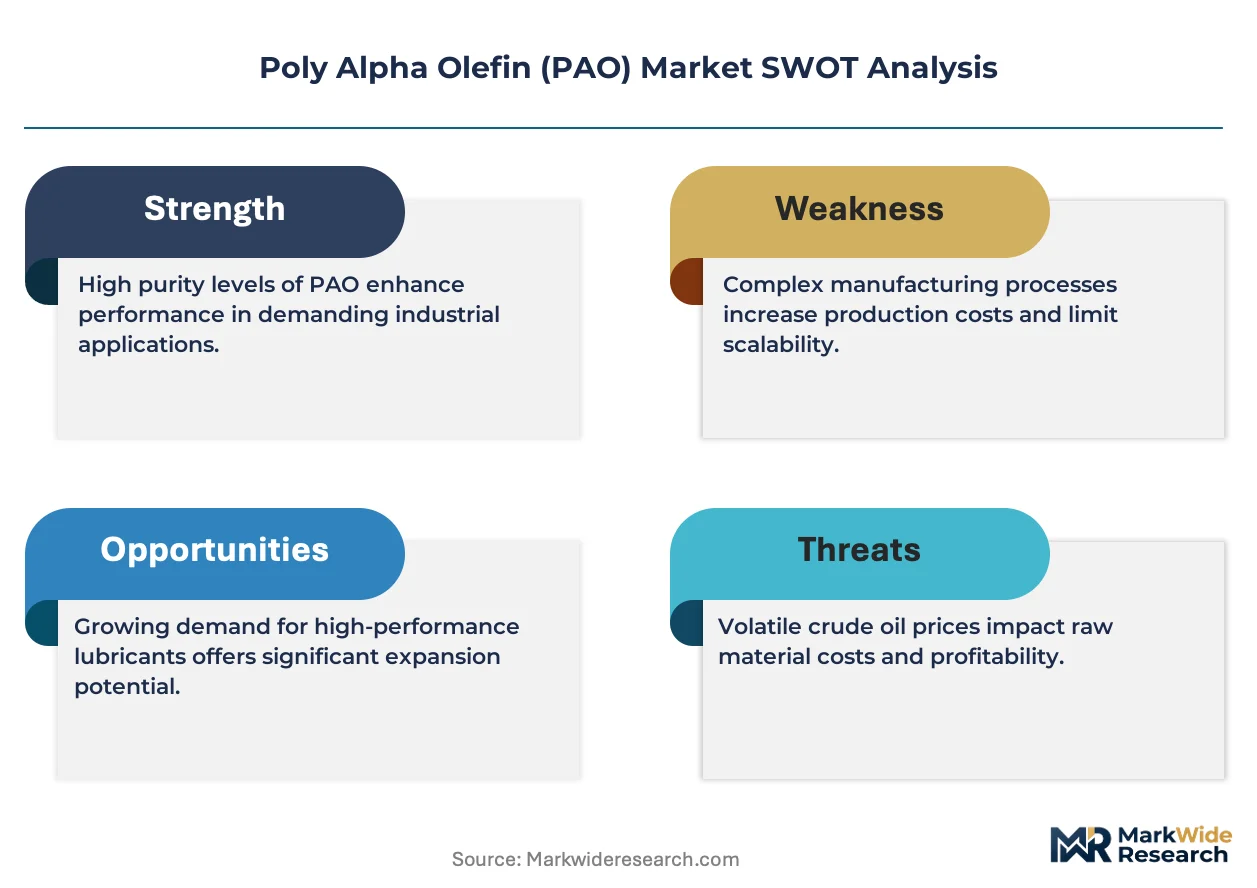
Backward integration into linear alpha-olefin feedstock anchors both supply security and pricing power for integrated petrochemical producers, while compounders without captive cracking assets absorb ethylene-cycle volatility through contract pass-through mechanisms.
Pricing Analysis
Ethylene-cracking economics pass directly into PAO contract structures, with 1-decene feedstock costs anchoring base stock quotations. Pricing stratifies across aerospace-certified metallocene grades, automotive factory-fill specifications, and industrial service-fill volumes, with quality grade and certification level as primary differentiation drivers. Cost compression in mid-tier automotive segments is intensifying because Group III+ base oils achieve comparable viscosity indices at substantially lower cost. Fleet operators and industrial procurement teams exhibit highest price sensitivity, while aerospace OEMs and premium EV thermal management specifications demonstrate inelastic demand.
Supply Chain Analysis
Specialized polymerization chemist availability concentrates in Germany's Ruhr industrial region and the US Gulf Coast petrochemical corridor, constraining capacity expansion timelines for advanced metallocene facilities. Manufacturing gravity centers on the United States, Germany, and China, with production drawing from linear alpha-olefin streams tied to ethylene-cracker economics. Supply chain risk rests on single-source vulnerability for 1-decene feedstock among integrated majors. Distribution runs through bulk tanker and drum logistics to automotive and industrial compounders, with just-in-time delivery requirements for factory-fill contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PAO market reads as a late-cycle quality story, with specification tightening in electric vehicle thermal management fluids redirecting procurement toward premium synthetic base stocks.
For Market Incumbents: Anchor factory-fill certification timelines as a defensive moat, extending 24-36 month qualification protocols with Volkswagen, BMW, and Mercedes-Benz to freeze specification windows. Deepen captive supply of linear alpha-olefin feedstock through ethylene-cracker debottlenecking in the US Gulf Coast and Rotterdam corridors, neutralizing cost volatility from olefin allocation decisions. For New Entrants and Emerging Players: Metallocene catalyst convergence with molecular distillation offers a technology-first wedge into aerospace hydraulic specifications previously served by ester chemistry. White-space targets concentrate on China's Yangtze River Delta automotive clusters, where MIIT GB standards for new energy vehicle coolants create formulation specification windows for PAO producers with local technical service presence. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration burdens compress formulation refresh cycles and extend lead times for new PAO grades. Long-term viability favors integrated petrochemical majors with backward integration into alpha-olefin supply and regional compounders with specialized blending capabilities in high-growth automotive clusters. Watch metallocene capacity announcements as the inflection signal for margin compression in specialty grades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Feedstock | Captive 1-decene supply from Gulf Coast cracking assets neutralizes ethylene-cycle volatility for ExxonMobil Chemical and Chevron Phillips Chemical. |
| Metallocene Catalyst Capacity Expansion | Advanced polymerization control enables tailored viscosity grades for Boeing and Airbus hydraulic specifications at premium pricing. |
| Local Technical Service Presence in China | MIIT GB standards for new energy vehicle coolants require formulation support in Shanghai and Jiangsu province automotive clusters. |
| REACH-Compliant Formulation Infrastructure | German compounders leverage existing PAO-ester blending assets to substitute restricted chlorinated paraffin additives faster than competitors. |
| Long-Term Factory-Fill Supply Agreements | Automotive procurement departments bundle technical service and drain interval optimization into multi-year contracts with Nordic fleet operators. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with plant managers at integrated petrochemical facilities, procurement leads at automotive OEMs and Tier 1 lubricant suppliers, distribution channel partners in industrial chemical logistics, and technical R&D directors in additive blending operations. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and REACH substance registration databases. Bottom-up volume estimates from polymerization capacity and utilization rates triangulate against top-down demand aggregation from end-use industry consumption patterns.
Rate-of-change decomposition separates volume growth from value expansion across the analysis window, with segmentation modeling across molecular weight grade tiers, end-use industry applications, and regional production hub clusters. CAGRs derive from regression analysis of historical capacity additions correlated with OEM factory-fill specification adoption curves. Industry-specific forecast inputs include electric vehicle production trajectories from automotive registration databases and wind turbine installation pipelines from offshore project development trackers.
The model holds under stable ethylene-cracker operating rates and unchanged REACH authorization timelines; deviation in olefin allocation decisions or accelerated substance restrictions would shift capacity expansion schedules and formulation substitution rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
EVA Copolymer Market