
 Global Polyamide-Imide Resin Market | 2026-2036
Global Polyamide-Imide Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyamide-Imide Resin Market Foresight
Capital-intensity divergence between integrated polymer producers and specialty compounders is unwinding competitive stability in polyamide-imide supply. Solvay S.A. leverages backward integration into chlorotoluene intermediates to secure feedstock continuity. Ensinger GmbH anchors its position through in-house production of stock shapes and precision-machined components for aerospace buyers. Toray Industries, Inc. dominates filament and film grades through proprietary biaxial stretching technology.
Polyamide-imide resin combines aromatic imide rings with flexible amide linkages to yield a thermoplastic or thermoset polymer with continuous service temperatures exceeding 220 degrees Celsius and dielectric strength above 20 kV per millimeter. Manufacturers synthesize these resins through condensation of trimellitic anhydride derivatives with aromatic diamines, followed by solution or melt processing into coatings, films, fibers, and molded parts for insulation and structural applications. Thermoplastic grades lead volume consumption in wire enamel and injection-molded connectors where reprocessability reduces manufacturing scrap. Solvent-based technology still commands the coating segment but faces displacement from solvent-free powder and waterborne systems as environmental regulations tighten across manufacturing jurisdictions.
The EPA enforces National Emission Standards for Hazardous Air Pollutants that limit methylene chloride and N-methyl-2-pyrrolidone emissions from coating operations, pushing resin buyers toward lower-solvent formulations. ECHA maintains REACH authorization requirements for diisocyanates and certain aromatic amines used in advanced polyimide chemistry, directly affecting raw material access for European compounders. China's MEE implements dual carbon goals that tighten energy efficiency standards for electrical equipment, indirectly stimulating demand for higher-temperature insulation materials. Stakeholders must monitor regulatory phase-outs of polar aprotic solvents while evaluating captive synthesis versus merchant supply for critical anhydride intermediates.
Market Dynamics
REACH authorization requirements and EPA NESHAP standards are compressing solvent-based formulation margins while accelerating capital redeployment toward waterborne and powder coating technologies across wire enamel and industrial coating supply chains.
Growth Catalysts
- Transformer motorization in China:Domestic production of high-efficiency motors and power transformers is expanding procurement of Class 220 thermal insulation materials for winding wire applications.
- Dual carbon goals:China's MEE energy efficiency mandates for electrical equipment are indirectly stimulating demand for higher-temperature insulation grades in industrial motor rebuild programs.
- Filament winding automation:Aerospace pressure vessel manufacturers are adopting automated fiber placement systems that favor thermoplastic polyamide-imide towpregs for reduced cycle times.
Market Restraints
- Chlorotoluene feedstock concentration:Backward integration into trimellitic anhydride intermediates is limited to three integrated chemical groups, creating supply vulnerability for specialty compounders.
- Polar aprotic solvent phase-outs:ECHA REACH restrictions on N-methyl-2-pyrrolidone and methylene chloride are forcing reformulation investments without guaranteed performance parity.
- Polyetherimide substitution:SABIC's Ultem grades are capturing cost-sensitive connector applications below 180 degrees Celsius continuous service temperature.
Strategic Opportunities
- India electrical infrastructure:Central Electricity Authority standards for distribution transformer efficiency are creating new specification pathways for high-temperature wire enamel in domestic rewind shops.
- Solvent-free powder coatings:Fluidized bed application technology is opening industrial valve and pump markets previously inaccessible to liquid PAI formulations.
- EU Green Deal industrial heat:Process equipment manufacturers are specifying PAI-based insulation for electrified heating elements replacing natural gas-fired systems in German chemical plants.
Industry Challenges
- Polymer synthesis expertise scarcity:Condensation chemistry specialists capable of controlling molecular weight distribution in imide ring closure are concentrated among retiring technical workforces in the United States and Germany.
- Multi-jurisdiction certification timelines:UL 1446 thermal class recognition, IEC 60172 wire enamel qualification, and JIS C 4003 testing must be sequenced for global OEM approvals, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyamide-Imide Resin Market |
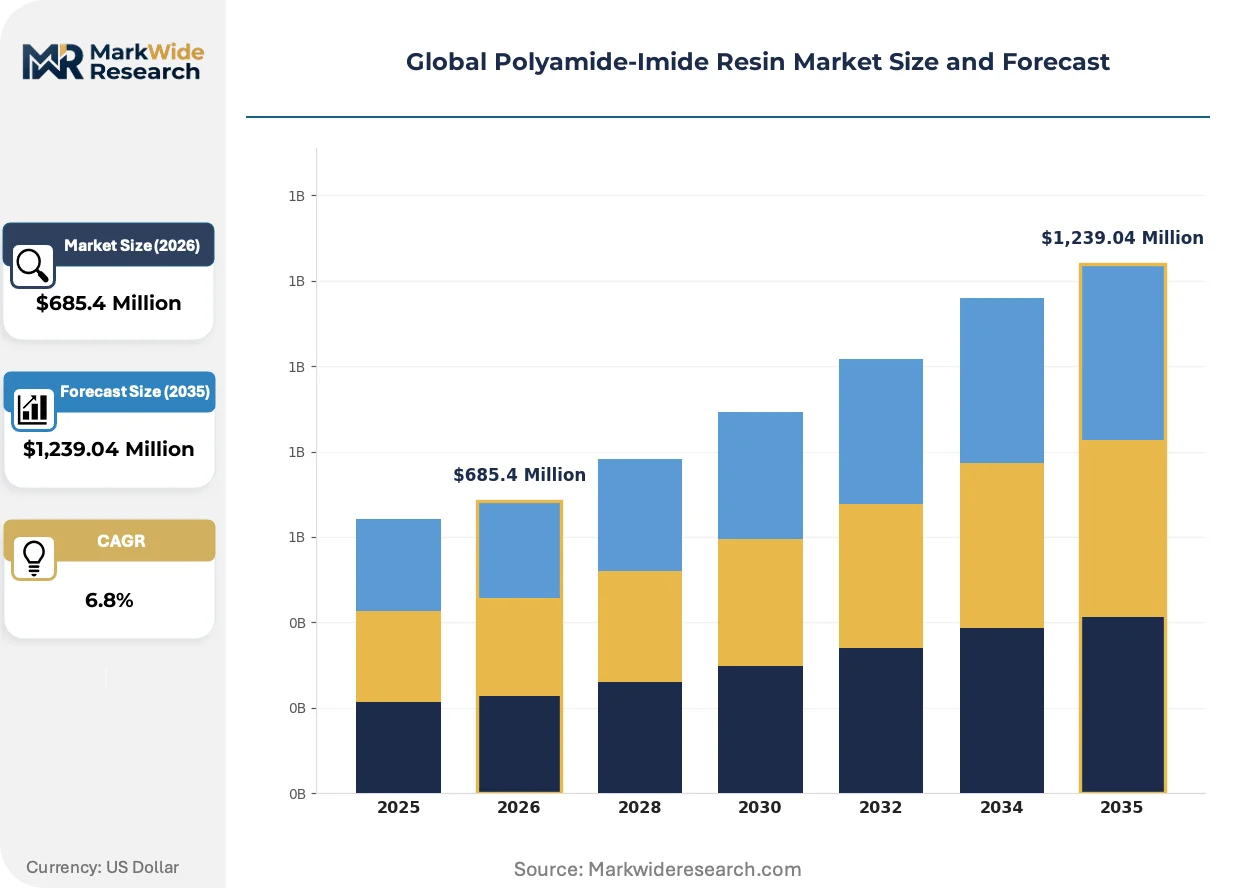
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermoset, Copolymer, Homopolymer Technology: Solvent-Based, Solvent-Free, Extrusion, Injection Molding, Compression Molding Application: Electrical Insulation, Aerospace Components, Automotive Parts, Industrial Machinery, Consumer Electronics End User Industry: Transportation Equipment, Electrical & Electronics, Heavy Equipment, Defense, Packaging |
| Companies Covered | Solvay S.A., Toyobo Co., Ltd., Elantas GmbH, Axalta Coating Systems, LLC, Innotek Technology Ltd., Ensinger GmbH, Drake Plastics Ltd. Co., Mitsubishi Gas Chemical Company, Inc., Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyamide-Imide Resin Market Shifts & Advancements
Formulation chemistry and application technology are converging to eliminate solvent dependence while preserving dielectric performance, fundamentally restructuring coating equipment investment priorities across motor and transformer manufacturing.
Waterborne polyamide-imide dispersions are supplanting conventional solvent-borne wire enamels in high-speed magnet wire lines. European motor manufacturers in Germany and Italy are retrofitting vertical enameling towers for aqueous cure profiles. This technology is compressing volatile organic compound emissions by over ninety percent while demanding longer bake cycles that reduce line throughput.
EPA National Emission Standards for Hazardous Air Pollutants are tightening methylene chloride and N-methyl-2-pyrrolidone limits in coating operations. US wire enamel applicators face capital decisions between emission control installation and formulation switching. The transformer rewind segment is accelerating qualification of reduced-solvent grades to avoid permitting delays.
Buyer consolidation among global OEM motor manufacturers is compressing supplier qualification cycles and unbundling technical service from material supply contracts. Tier-one automotive suppliers in Japan are demanding direct mill relationships for PAI resin rather than compounder intermediation. This pattern is most visible in precision-machined component procurement for electric power steering systems.
Global Polyamide-Imide Resin Market Segmentation
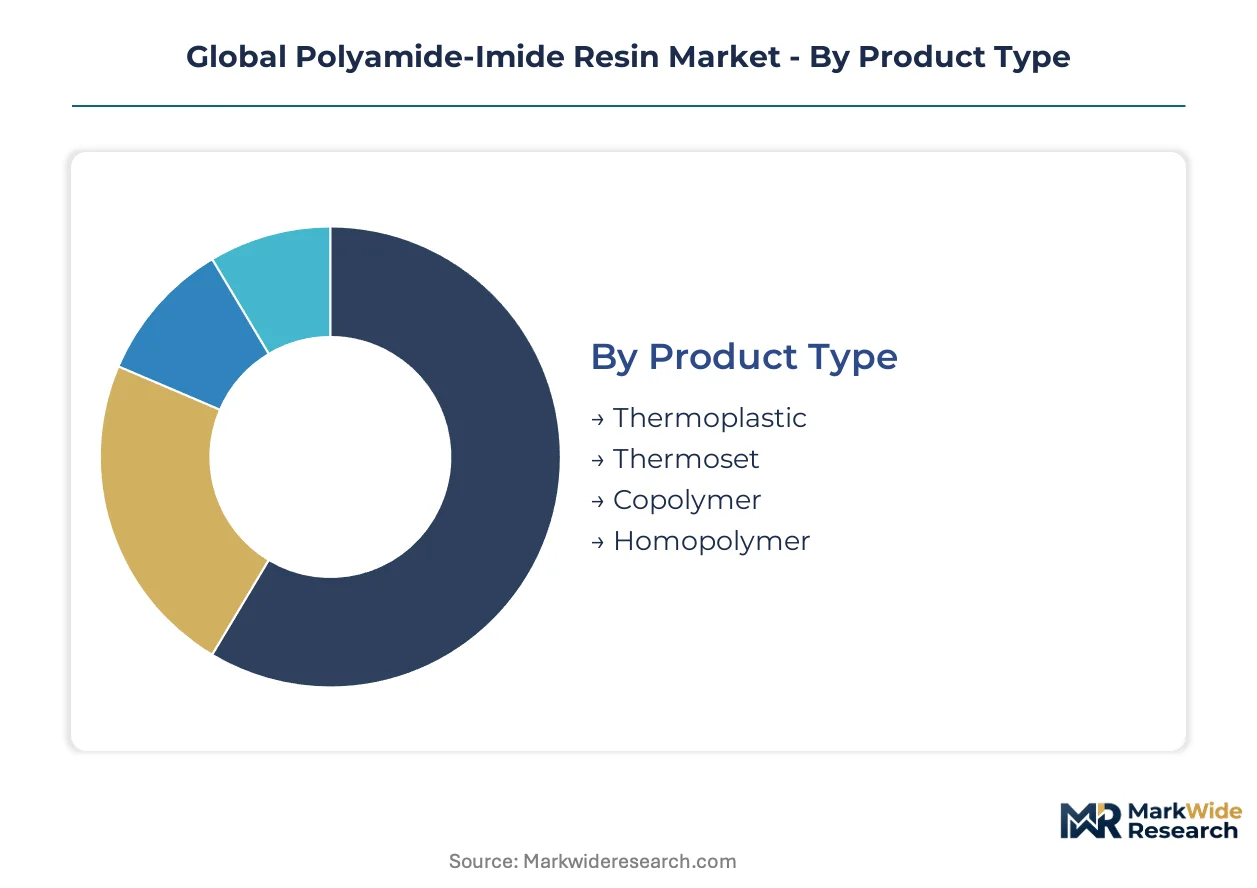
Polyamide-imide resin segmentation reveals how substitution pressures from polyetherimide and polyetheretherketone reshape competitive boundaries across thermal grades and processing methods. Buyers select segments based on continuous service temperature thresholds, regulatory compliance burdens, and reprocessability requirements.
Product Type:
Substitution pressure from SABIC Ultem and Victrex PEEK concentrates most intensely on lower-temperature thermoplastic grades, while thermoset formulations defend niche positions through dielectric performance.
- Thermoplastic:Reprocessable grades dominate wire enamel and injection-molded connector production where manufacturing scrap recovery reduces material costs. Chinese motor manufacturers and German automotive suppliers specify these resins for Class 220 insulation in high-efficiency motor windings, though polyetherimide captures applications below 180 degrees Celsius.
- Thermoset:Cross-linked structures deliver superior dimensional stability and chemical resistance for aerospace pressure vessels and semiconductor process equipment. Curing requirements limit reprocessability but secure positions where thermal cycling demands exceed thermoplastic limits.
- Copolymer:Modified architectures balance cost and performance for industrial valve coatings and pump housings requiring moderate chemical exposure.
- Homopolymer:Unmodified chains serve premium aerospace and defense specifications where lot-to-lot consistency and traceability dominate procurement criteria.
Thermoplastic grades anchor the volume base while copolymer formulations gain share at the steepest rate through cost-engineered substitutions in industrial equipment.
Technology:
Cost tier stratification separates capital-intensive solvent-free systems from established solvent-based infrastructure facing EPA NESHAP and ECHA REACH compliance costs.
- Solvent-Based:Conventional solutions dominate legacy wire enamel lines with established cure profiles and deep supply chain integration. N-methyl-2-pyrrolidone and methylene chloride formulations face phase-out timelines under US and European emissions regulations, forcing reformulation investments or emission control capital deployment.
- Solvent-Free:Powder coating and reactive melt systems eliminate volatile organic compound emissions entirely, opening industrial valve and pump markets previously inaccessible to liquid formulations. Fluidized bed application technology demands new equipment investments but avoids permitting delays.
- Extrusion:Continuous profile production serves stock shape manufacturers feeding precision machining operations for aerospace connectors and bearing cages.
- Injection Molding:High-volume precision components for automotive electric power steering systems and consumer electronics housings leverage thermoplastic reprocessability.
- Compression Molding:Batch processing accommodates low-volume aerospace and defense specifications requiring extensive quality documentation and lot testing.
Solvent-based technology retains the largest installed base while solvent-free systems expand most quickly through regulatory-driven equipment replacement cycles.
Application:
Customer type concentration in global OEM motor manufacturers compresses supplier qualification cycles and unbundles technical service from material contracts.
- Electrical Insulation:Magnet wire enamel and slot insulation for transformers, motors, and generators constitute the dominant demand cluster. India's Central Electricity Authority efficiency standards for distribution transformers create new specification pathways in domestic rewind shops.
- Aerospace Components:Filament-wound pressure vessels, precision-machined connectors, and thermal isolation hardware serve commercial aviation and space launch systems. Automated fiber placement systems favor thermoplastic towpregs for reduced cycle times.
- Automotive Parts:Electric power steering housings, transmission components, and thermal management modules specify PAI where continuous temperatures exceed 200 degrees Celsius.
- Industrial Machinery:Process equipment manufacturers specify PAI-based insulation for electrified heating elements replacing natural gas-fired systems in German chemical plants under EU Green Deal industrial heat programs.
- Consumer Electronics:Miniaturized connectors and thermal management substrates serve high-density packaging requirements.
Electrical insulation commands the volume base while aerospace components climb the fastest through filament winding automation adoption.
End User Industry:
Supply concentration in chlorotoluene-derived trimellitic anhydride intermediates limits backward integration to three integrated chemical groups, creating vulnerability for specialty compounders serving fragmented end-use sectors.
- Transportation Equipment:Commercial aviation, rail, and marine propulsion systems specify PAI for weight reduction and thermal durability in harsh operating environments.
- Electrical & Electronics:Transformer, motor, and generator manufacturers in China, Germany, and Japan drive procurement of Class 220 thermal insulation materials. China's MEE dual carbon goals tighten energy efficiency standards, indirectly stimulating demand for higher-temperature grades.
- Heavy Equipment:Mining, construction, and agricultural machinery utilize PAI for wear-resistant bearings and seals in abrasive conditions.
- Defense:Munitions, aerospace platforms, and naval systems require ITAR-controlled supply chains with extensive lot traceability and domestic sourcing mandates.
- Packaging:Specialized high-temperature processing equipment components serve food and pharmaceutical sterilization applications.
Electrical & Electronics anchors the volume base while Defense gains share at the steepest rate through reshoring requirements and platform modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between Chinese motor manufacturers and European coating applicators is widening as MEE dual carbon goals accelerate specification upgrades while ECHA REACH compliance costs erode margins in solvent-based formulation markets.
China
Domestic production of high-efficiency motors and power transformers is expanding procurement of Class 220 thermal insulation materials for winding wire applications. MEE dual carbon goals tighten energy efficiency standards for electrical equipment, indirectly stimulating demand for higher-temperature grades. Shanghai and Jiangsu province host concentrated magnet wire manufacturing clusters where local enamelers are retrofitting lines for waterborne PAI dispersions.
Germany
Process equipment manufacturers specify PAI-based insulation for electrified heating elements replacing natural gas-fired systems under EU Green Deal industrial heat programs. ECHA REACH authorization requirements restrict diisocyanates and aromatic amines, directly affecting raw material access for domestic compounders. The Rhine-Ruhr industrial corridor maintains specialized wire enamel production serving transformer rewind shops across Central Europe.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforce methylene chloride and N-methyl-2-pyrrolidone limits in coating operations, pushing resin buyers toward lower-solvent formulations. Wire enamel applicators face capital decisions between emission control installation and formulation switching. Ohio and Indiana host dense concentrations of motor and transformer manufacturing where qualification of reduced-solvent grades is accelerating.
Japan
Tier-one automotive suppliers demand direct mill relationships for PAI resin rather than compounder intermediation, compressing supplier qualification cycles. METI energy efficiency standards for industrial equipment stimulate specification of high-temperature insulation materials. The Nagoya-Toyota industrial corridor concentrates precision-machined component procurement for electric power steering systems.
India
Central Electricity Authority standards for distribution transformer efficiency create new specification pathways for high-temperature wire enamel in domestic rewind shops. BIS certification requirements for electrical insulation materials extend product launch timelines for imported resin formulations. Gujarat and Maharashtra host expanding electrical equipment manufacturing clusters where local enamelers are qualifying Class 220 thermal grades.
Global Polyamide-Imide Resin Market Competitive Landscape
Concentration sits with integrated chemical groups controlling chlorotoluene-derived trimellitic anhydride intermediates, while specialty compounders and precision fabricators occupy fragmented downstream positions. Three strategic archetypes dominate: backward-integrated polymer producers securing feedstock continuity, in-house stock shape manufacturers serving aerospace buyers, and coating-focused compounders navigating solvent phase-out timelines. Competitive moves center on captive synthesis investments for critical anhydride intermediates and qualification partnerships with global OEM motor manufacturers.
Among integrated chemical producers, Solvay S.A. and Toray Industries, Inc. exemplify the upstream-control archetype through their positions in condensation chemistry and proprietary processing technologies. Ensinger GmbH represents the precision-fabrication tier with its focus on stock shapes and machined components for demanding industrial applications. These three anchors illustrate how competitive positioning diverges between feedstock-secure producers and application-specialized compounders across the value chain.
| Leading Market Players |
|---|
| Solvay S.A. |
| Toyobo Co., Ltd. |
| Elantas GmbH |
| Axalta Coating Systems, LLC |
| Innotek Technology Ltd. |
| Ensinger GmbH |
| Drake Plastics Ltd. Co. |
| Mitsubishi Gas Chemical Company, Inc. |
| Toray Industries, Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between chlorotoluene-integrated producers and wire enamel compounders lock in trimellitic anhydride supply access while providing quarterly price visibility against volatile aromatic feedstock indices. Solvay S.A. and Mitsubishi Gas Chemical Company leverage these structures to buffer specialty compounders from spot market swings in China and Germany.
Pricing Analysis
Configured-to-order pricing for aerospace homopolymer grades commands spreads exceeding standard thermoplastic wire enamel quotations by substantial margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL 1446 thermal class certification and volume commitment scale. Cost compression in solvent-based formulations is intensifying because ECHA REACH authorization fees and EPA NESHAP compliance capital erode compounder margins. Chinese motor manufacturers exhibit highest price sensitivity, while German aerospace buyers prioritize lot traceability over unit cost.
Supply Chain Analysis
Inventory cycles for trimellitic anhydride intermediates stretch lead times when chlorotoluene feedstock tightens at Louisiana and Rotterdam hubs. Manufacturing concentrates in the United States, China, and Germany where chlorotoluene oxidation capacity anchors polymer production. Raw material flows draw from aromatic amine suppliers in Japan and anhydride derivative producers in Belgium. Single-source vulnerability sits with the three integrated groups controlling chlorotoluene-to-TMA conversion. Distribution runs through regional compounder networks serving magnet wire manufacturers in Shanghai, Nagoya, and Ohio.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as transformer motorization in China restarts capital expenditure programs for Class 220 insulation upgrades.
For Market Incumbents: Shield margin structures by accelerating backward integration into chlorotoluene intermediates before feedstock concentration tightens further. Prioritize UL 1446 and IEC 60172 certification investments to defend against polyetherimide substitution in sub-180°C connector applications. Lock in five-year offtake agreements with Shanghai and Jiangsu magnet wire clusters to preempt competitor capacity.
For New Entrants and Emerging Players: Differentiate on waterborne dispersion technology to capture European wire enamel retrofit demand as ECHA REACH restrictions phase out N-methyl-2-pyrrolidone formulations. Target India's Central Electricity Authority efficiency upgrade pathway where BIS certification barriers filter out established suppliers. Lead with fluidized bed powder coating systems for industrial valve markets previously inaccessible to liquid PAI.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale compounders with captive synthesis capabilities in aromatic diamine chemistry and established OEM qualification pipelines. Long-term viability hinges on regulatory compliance technology rather than commodity scale. Watch EPA NESHAP enforcement intensity as the inflection signal for accelerated solvent-free formulation switching.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive chlorotoluene supply secures trimellitic anhydride continuity against feedstock concentration. |
| Waterborne Formulation Launch | ECHA REACH compliance positions European compounders ahead of N-methyl-2-pyrrolidone phase-outs. |
| Long-term Supply Agreement | MEE dual carbon goals in China create multi-year procurement commitments for Class 220 grades. |
| Joint Venture | Indian electrical infrastructure expansion rewards local enamel production partnerships with Gujarat manufacturers. |
| Green Manufacturing Transition | EU Green Deal industrial heat programs specify PAI insulation for electrified chemical process equipment. |
Research Methodology
Initial hypotheses were tested against primary input from polymer synthesis chemists, wire enamel plant managers, aerospace procurement directors, and electrical OEM specification engineers and refined through secondary validation against SEC 10-K filings, Cefic chemical trade data, customs import records, and IEC certification registries. Bottom-up resin consumption estimates triangulated with top-down market sizing across the analysis window.
Variance decomposition isolates volume drivers by grade tier, end-use industry, processing technology, and regional regulatory cluster. CAGRs were derived from segmented growth rate reconciliation against macroeconomic indicators. Forecast inputs incorporated MEE dual carbon policy implementation timelines and EPA NESHAP enforcement trajectories.
Decision-makers should treat outputs as directional under sustained chlorotoluene feedstock concentration and REACH authorization timelines; material deviation in regulatory phase-out schedules would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Vinyl Acetate Homopolymer Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Global Anti-Vibration Polymer Market