
 South America Polymer Emulsion Market | 2026-2036
South America Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polymer Emulsion Market Analytics
A capital-intensity divergence between integrated petrochemical producers and specialty chemical operators is rotating competitive dynamics across the region. BASF SE leverages its Ludwigshafen-derived technology base to sustain formulation leadership in acrylic emulsions for decorative coatings. Celanese Corporation anchors its position through captive vinyl acetate monomer supply and backward integration into emulsion polymerization units in Brazil.
South America polymer emulsion denotes a colloidal dispersion of polymer particles, typically 0.1 to 1.0 micrometers in diameter, stabilized by surfactants in a continuous aqueous phase and manufactured through free-radical emulsion polymerization at 60 to 90 degrees Celsius. These systems serve as binders, film formers, and adhesion promoters across architectural coatings, pressure-sensitive adhesives, and textile finishing operations. Acrylic emulsions dominate volume consumption in exterior architectural paints where weatherability and UV resistance command premium positioning, while polyurethane dispersions represent the fastest-expanding category in automotive refinish and flexible packaging laminates where solvent-free performance is non-negotiable. Vinyl acetate homopolymer and copolymer emulsions occupy mature, cost-sensitive niches in interior flat wall paints and paper saturation applications across the region.
Brazil's national environmental regulator enforces CONAMA resolution limits on volatile organic compound emissions in architectural coatings, directly compelling reformulation toward water-borne polymer systems. ANVISA oversees chemical substance registration under Brazil's REACH-equivalent framework, creating compliance thresholds that favor established multinationals with dedicated regulatory affairs capabilities. Argentina's Secretariat of Environment and Sustainable Development maintains parallel VOC protocols that shape cross-border product standardization within Mercosur trade channels. Stakeholders must monitor pending harmonization of chemical hazard classification across Mercosur member states, as divergent implementation timelines threaten to fragment supply chain planning and inventory deployment strategies.
Market Dynamics
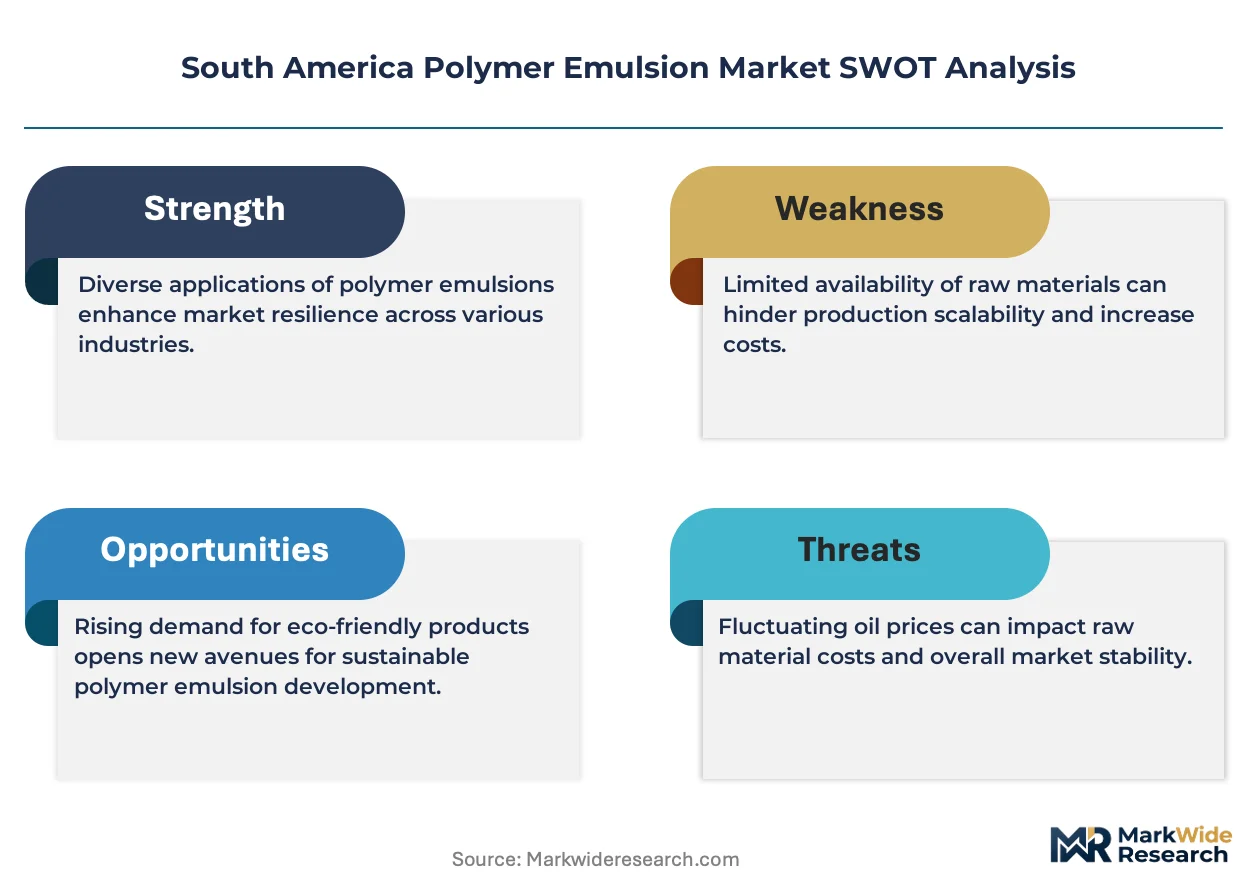
REACH-aligned regulatory harmonization across Mercosur economies is forcing systematic substitution of solvent-based coating systems with water-borne polymer emulsions, compressing reformulation timelines and redistributing competitive advantage toward integrated formulators with captive VAM supply.
Growth Catalysts
- CONAMA Resolution VOC Limits:Brazil's national environmental regulator mandates volatile organic compound emission caps in architectural coatings, compelling manufacturers to accelerate water-based acrylic emulsion adoption across decorative paint portfolios.
- Construction Sector Expansion:Residential and commercial building activity across São Paulo and Minas Gerais industrial corridors is generating sustained demand for exterior architectural coatings with weatherability performance.
- Pressure-Sensitive Adhesives:Flexible packaging and label manufacturing operations in Argentina are transitioning from solvent-based systems to vinyl acetate copolymer emulsions for compliance with cross-border Mercosur product standards.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer and vinyl acetate prices track naphtha and ethylene cost swings, compressing formulation margins for non-integrated emulsion producers without captive cracker access.
- Import Dependency Concentration:Specialty surfactants and initiator chemistries concentrate in Asian manufacturing bases, exposing South American emulsion plants to extended lead times and currency fluctuation risk.
- Performance Ceiling in High-Durability Applications:Water-borne polyurethane dispersions face solvent-borne two-component systems in automotive refinish segments where chemical resistance and gloss retention remain critical specifications.
Strategic Opportunities
- Textile Finishing Underpenetration:Argentina's apparel and technical textile sectors present expansion potential for acrylic and polyurethane emulsion binders currently supplied through Brazilian import channels.
- Biobased Monomer Integration:Emerging fermentation-derived acrylic acid and bio-vinyl acetate technologies enable premium positioning for sustainability-certified architectural coating formulations targeting green building certification schemes.
- Direct-to-Applicator Digital Platforms:E-commerce procurement channels for professional painters and small contractors are bypassing traditional distributor tiers in Brazilian southeastern states, enabling margin capture and demand data accumulation.
Industry Challenges
- Emulsion Polymerization Process Engineering Talent:Free-radical kinetics expertise and particle size distribution control specialists remain scarce across regional technical universities, constraining plant debottlenecking and new product development velocity.
- ANVISA Chemical Registration Timelines:Brazil's REACH-equivalent substance notification protocols impose multi-year approval horizons for novel monomer chemistries, delaying formulation innovation cycles relative to European and North American competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polymer Emulsion Market |
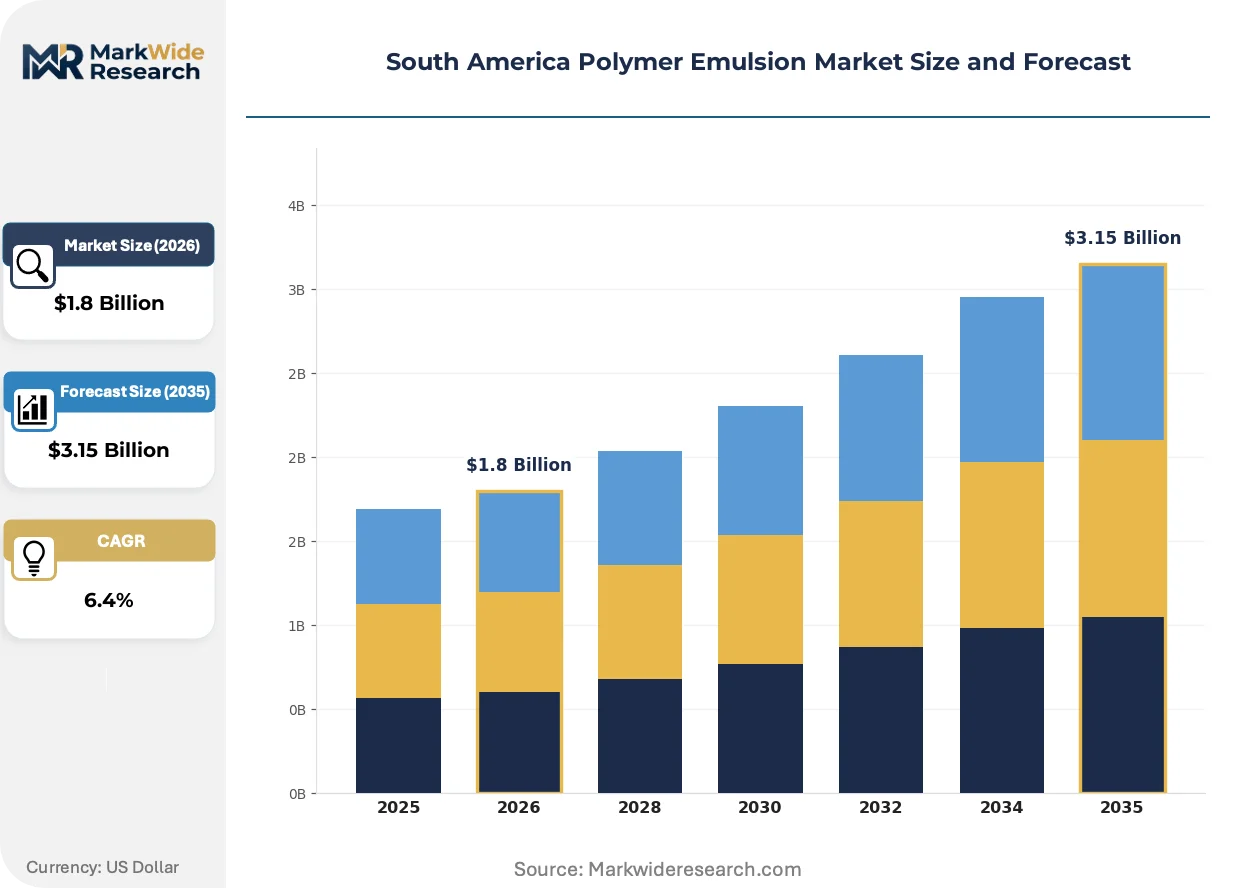
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Styrene Butadiene, Vinyl Acetate, Polyurethane Application: Paints & Coatings, Adhesives, Textiles, Paper End User: Construction, Automotive, Consumer Goods, Electronics Technology: Emulsion Polymerization, Solution Polymerization, Bulk Polymerization, Suspension Polymerization |
| Companies Covered | Arkema Group, Celanese Corporation, BASF SE, The Lubrizol Corporation, Wacker Chemie AG, Dow, Clariant, Solvay, Akzo Nobel N.V., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polymer Emulsion Market Evolving Landscape
Technology trajectories in South American polymer emulsions are diverging between commodity scale efficiency and specialty performance premiumization, with regulatory compliance acting as the forcing mechanism for portfolio restructuring.
Polyurethane dispersion technology is bifurcating the high-performance coatings segment. These systems deliver solvent-free application with automotive refinish-grade gloss and chemical resistance. Brazilian OEM collision repair networks and flexible packaging converters are adopting PUDs at accelerating rates for CONAMA compliance. The technology is bifurcating market tiering, separating premium performance-positioned formulators from commodity acrylic suppliers in specification-driven end-uses.
ANVISA's chemical substance registration framework under Brazil's REACH-equivalent regime is tightening inventory management protocols for imported raw materials. Industrial consequence includes mandatory downstream notification obligations for polymer emulsion formulators using registered substances. Small and mid-scale Brazilian coating manufacturers without dedicated regulatory affairs functions face compliance cost escalation and are consolidating supplier relationships toward integrated multinationals with established registration dossiers.
Specification-driven procurement is compressing switching cycles among large Brazilian architectural coating brands. Historical supplier relationships anchored on price and logistics reliability are yielding to performance benchmarking protocols and third-party certification requirements. Professional painting contractors in São Paulo's commercial construction sector now demand batch-to-batch viscosity stability documentation and accelerated weathering test data, privileging emulsion suppliers with in-house analytical laboratories and technical service field presence.
South America Polymer Emulsion Market Segmentation
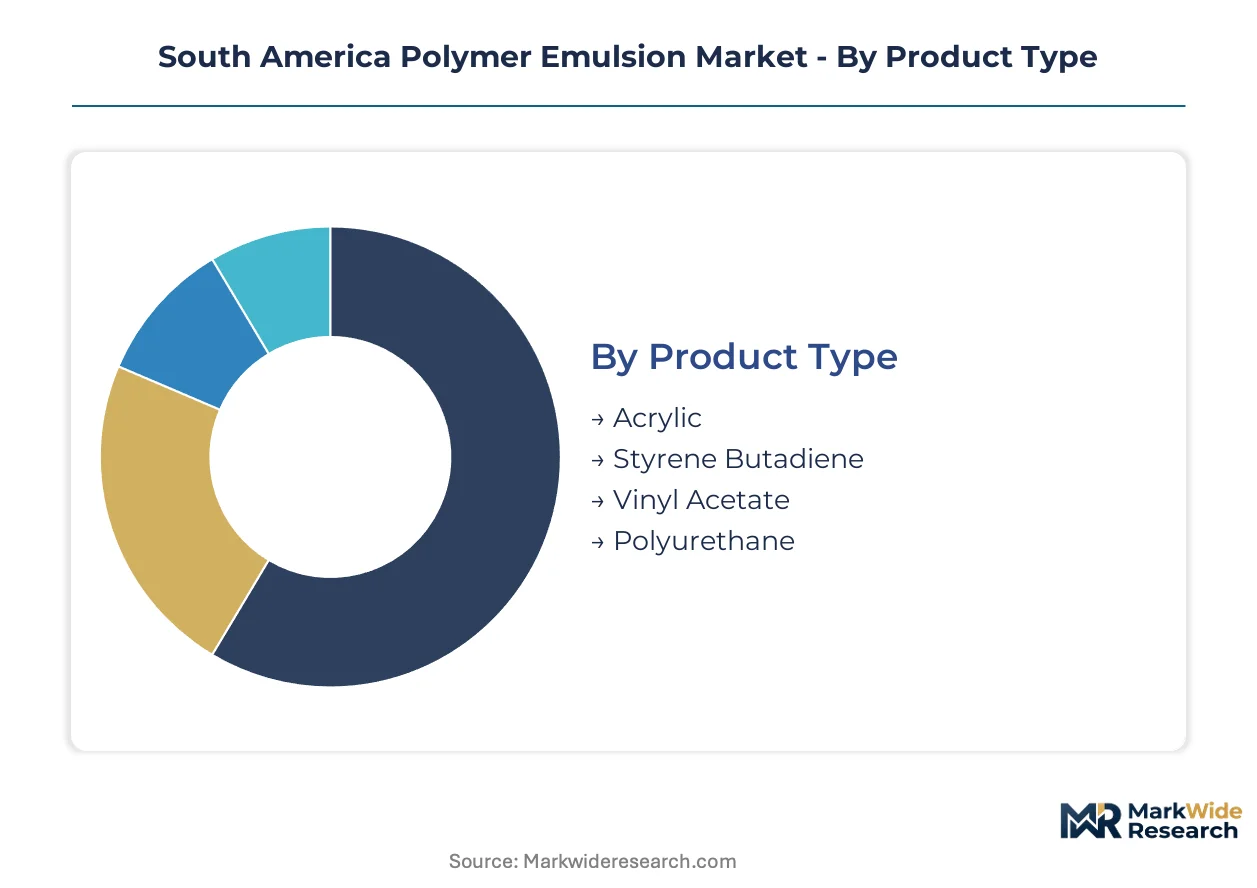
Segmentation in South America polymer emulsions reveals how formulation chemistry, application requirements, and manufacturing technology intersect with regional supply chain realities. Understanding these divisions exposes where margin pools concentrate and which technology investments yield competitive separation.
Product Type:
Channel distribution varies sharply by chemistry—acrylic and polyurethane emulsions flow through technical service-intensive direct sales to large formulators, while vinyl acetate moves through bulk distributors serving cost-sensitive paper and adhesive markets.
- Acrylic:Water-borne copolymers of methyl methacrylate and butyl acrylate deliver exterior durability and UV resistance for architectural coatings. Demand concentrates in São Paulo state's commercial construction sector where CONAMA VOC compliance mandates water-based systems.
- Polyurethane:Aliphatic and aromatic polyurethane dispersions provide solvent-free performance with automotive-grade gloss and chemical resistance. Argentine flexible packaging converters and Brazilian collision repair networks are adopting these systems fastest for high-specification laminates and refinish coatings.
- Styrene Butadiene:Carboxylated SBR latexes serve carpet backing and paper coating applications across regional pulp and paper clusters.
- Vinyl Acetate:Homopolymer and copolymer emulsions occupy mature cost-sensitive niches in interior flat wall paints and wood adhesives.
Acrylic dominates installed base. Polyurethane is where expansion concentrates.
Application:
Cost tier stratification separates specification-driven coatings from commodity adhesives and paper treatments.
- Paints & Coatings:Architectural, industrial, and automotive refinish formulations demand tailored particle size distribution and film-forming temperature. Brazilian southeastern industrial corridor construction activity sustains volume leadership.
- Adhesives:Pressure-sensitive and construction adhesive segments transition from solvent systems to water-borne vinyl acetate and acrylic emulsions under Mercosur-aligned VOC regulations.
- Textiles:Fabric finishing and nonwoven binders represent underpenetrated territory with Argentine apparel manufacturers currently supplied through Brazilian import channels.
- Paper:Saturation and coating applications consume mature vinyl acetate chemistries with limited formulation innovation.
Paints & Coatings commands revenue concentration. Adhesives is climbing the fastest on regulatory substitution.
End User:
Customer type determines technical service intensity and contract structure—construction and automotive demand field presence, while consumer goods and electronics rely on specification compliance documentation.
- Construction:Residential and commercial building across Brazil's Minas Gerais and São Paulo states generates sustained demand for weatherable exterior coatings and tile adhesives.
- Automotive:OEM collision repair networks and component manufacturing specify polyurethane dispersions for refinish and interior trim applications.
- Consumer Goods:Packaging adhesives and label stock production in Argentina drive vinyl acetate copolymer consumption.
- Electronics:Specialty applications in cable coatings and component encapsulation remain nascent with import-dependent supply chains.
Construction anchors volume. Automotive is gaining share fastest on performance premiumization.
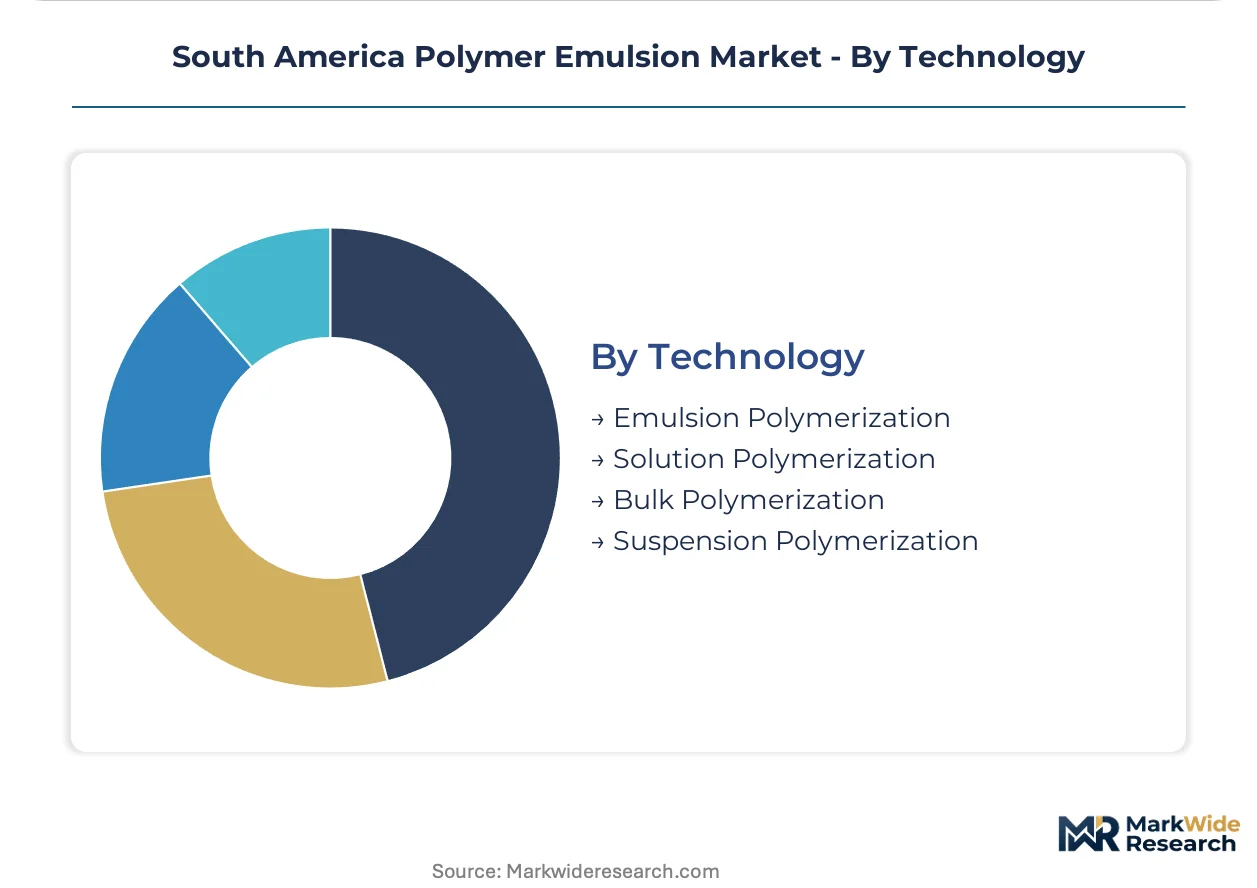
Technology:
Supply concentration in polymerization process expertise shapes regional manufacturing footprint—emulsion technology dominates local production while other methods concentrate in imported specialty materials.
- Emulsion Polymerization:Free-radical aqueous dispersion at 60-90°C produces the colloidal particle architecture underlying all regional volume production. Brazilian plants operate this technology at scale for acrylic and vinyl acetate chemistries.
- Solution Polymerization:Organic solvent-based processes yield high-molecular-weight polymers for subsequent dispersion, used in imported specialty polyurethane precursors.
- Bulk Polymerization:Mass polymerization without solvent or water produces solid resins requiring subsequent processing, limited regional presence.
- Suspension Polymerization:Bead polymerization in aqueous suspension serves PVC and other commodity polymer production with minimal emulsion market overlap.
Emulsion polymerization dominates installed capacity. Solution polymerization is where technology licensing concentrates for high-performance imports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Argentina's flexible packaging sector exhibit acute price sensitivity to vinyl acetate copolymer emulsions, while Brazilian automotive refinish networks prioritize polyurethane dispersion performance over cost, creating a demand-elasticity split that shapes regional supply strategies.
Brazil
Construction activity across São Paulo and Minas Gerais states consumes acrylic emulsions for exterior architectural coatings with weatherability specifications. ANVISA's REACH-equivalent chemical registration framework imposes multi-year approval timelines for novel monomer chemistries. The southeastern industrial corridor hosts captive vinyl acetate monomer production feeding backward-integrated emulsion polymerization units.
Argentina
Flexible packaging converters and label manufacturers drive vinyl acetate copolymer demand for pressure-sensitive adhesives. The Secretariat of Environment and Sustainable Development maintains VOC emission protocols that shape cross-border product standardization within Mercosur channels. Buenos Aires province concentrates apparel and technical textile operations currently supplied through Brazilian import channels for acrylic binders.
Chile
Mining sector maintenance coatings and industrial infrastructure projects generate specialty acrylic emulsion demand with corrosion resistance requirements. The country's national environmental regulator enforces progressive VOC limits in industrial coatings that accelerate water-borne system adoption. Santiago's metropolitan manufacturing belt concentrates paint formulation operations serving northern mining regions.
Colombia
Residential construction recovery in Bogotá and Medellín metropolitan areas sustains interior flat wall paint consumption of cost-sensitive vinyl acetate homopolymers. The national Ministry of Environment and Sustainable Development implements chemical hazard classification frameworks that favor established multinational suppliers with registration capabilities. Antioquia department's construction materials cluster drives regional distribution network density.
South America Polymer Emulsion Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South American polymer emulsion sector. The market structure consolidates around integrated petrochemical producers with captive monomer supply and specialty chemical operators with formulation expertise. Three archetypes dominate: backward-integrated multinationals with Ludwigshafen-derived technology bases, regional producers with Brazilian manufacturing footprints, and import-dependent distributors serving niche applications. Competitive moves concentrate on regulatory registration dossier accumulation and direct-to-applicator digital platform deployment.
Within the integrated multinational tier, BASF SE and Celanese Corporation anchor positions through distinct supply chain configurations. BASF SE exemplifies technology-led formulation leadership in acrylic emulsions, while Celanese Corporation represents backward integration into captive vinyl acetate monomer supply. Dow occupies a position bridging commodity scale and specialty performance segments. These three entities sit within a competitive set where ANVISA registration capabilities and southeastern Brazilian logistics infrastructure determine market access velocity.
| Leading Market Players |
|---|
| Arkema Group |
| Celanese Corporation |
| BASF SE |
| The Lubrizol Corporation |
| Wacker Chemie AG |
| Dow |
| Clariant |
| Solvay |
| Akzo Nobel N.V. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Brazilian southeastern emulsion plants shapes regional price floors, with backward-integrated producers commanding premium positioning while import-dependent formulators absorb currency-driven margin compression. ANVISA registration requirements and captive vinyl acetate monomer supply create divergent cost structures that stratify competitive tiers across Mercosur channels.
Pricing Analysis
Technical service contracts and formulation support agreements generate lifetime value exceeding base product margins for acrylic emulsion suppliers serving São Paulo's commercial construction sector. Three-tier pricing structure across premium, standard, and economy levels separates polyurethane dispersions with automotive-grade certification from commodity vinyl acetate homopolymers. Cost compression in vinyl acetate copolymers is intensifying because Argentine flexible packaging converters prioritize price over performance. Small Brazilian coating manufacturers exhibit acute price sensitivity, while automotive refinish networks prioritize specification compliance.
Supply Chain Analysis
Strategic stockpiling of specialty surfactants and initiator chemistries dominates inventory strategy among Brazilian emulsion producers facing extended lead times from Asian manufacturing bases. Raw material procurement draws from China, South Korea, and Germany for surfactant packages, redox initiators, and polyurethane prepolymers. Single-source vulnerability concentrates in imported specialty additives. Distribution runs through technical service-intensive direct sales for large formulators and bulk distributors serving cost-sensitive paper and adhesive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH-aligned regulatory harmonization across Mercosur economies is disrupting competitive positioning, forcing systematic solvent-to-water formulation transitions that favor integrated producers with captive monomer supply and established ANVISA registration dossiers.
For Market Incumbents: Consolidate regulatory affairs capabilities to accelerate novel monomer approvals under Brazil's REACH-equivalent framework, compressing formulation innovation cycles relative to import-dependent competitors. Deepen captive vinyl acetate monomer supply through southeastern Brazilian capacity additions, defending margin position against naphtha cost volatility. Lock in long-term technical service contracts with São Paulo commercial construction contractors to capture specification-driven procurement shifts.
For New Entrants and Emerging Players: Lead with biobased acrylic acid and bio-vinyl acetate formulations targeting green building certification schemes, where sustainability premiums offset scale disadvantages. Argentina's apparel and technical textile sectors present the most penetrable white space, currently supplied through Brazilian import channels with limited local technical presence. Deploy direct-to-applicator digital platforms for professional painters in southeastern states, bypassing traditional distributor tiers to accumulate demand data and margin capture.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical operators with polyurethane dispersion expertise and established ANVISA registration capabilities over commodity acrylic producers facing feedstock margin compression. Long-term viability hinges on regulatory dossier accumulation and backward integration into captive monomer supply. Watch ANVISA chemical registration timeline acceleration as the inflection signal indicating competitive barrier reduction or consolidation trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VAM Supply | Celanese Corporation's captive monomer production in Brazil eliminates feedstock cost volatility exposure. |
| Green Manufacturing Transition | Fermentation-derived bio-acrylic acid enables premium positioning for CONAMA-compliant architectural coatings. |
| Long-term Supply Agreement | Direct contracts with São Paulo commercial contractors secure specification-driven procurement relationships. |
| Joint Venture | Technology licensing partnerships transfer Ludwigshafen-derived emulsion polymerization expertise to regional plants. |
| Capacity Expansion | Southeastern Brazilian debottlenecking captures construction sector demand growth across Minas Gerais states. |
Research Methodology
A spread of perspectives from emulsion plant managers, procurement leads at downstream coating OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation from customs and trade data, ACC and Cefic regional reports, SEC 10-K filings of listed chemical producers, and ANVISA chemical registration databases. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic drivers across the South American polymer emulsion sector.
Segmentation dimensions modeled include product chemistry tier, end-use application, customer type, and regional production hub across the analysis window. CAGRs were derived from demand elasticity modeling against construction sector output and regulatory substitution timelines. Forecast inputs incorporated CONAMA resolution implementation schedules and Mercosur chemical hazard classification harmonization progress.
Forecasts assume regulatory continuity in Brazil's ANVISA framework and Argentina's Secretariat of Environment protocols; material policy shifts would require re-modeling of substitution rates and competitive positioning. Commodity petrochemical feedstock volatility and currency fluctuation risk represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Smart Polymers Market